
 Mexico Automotive Electric Actuators Market | 2026-2036
Mexico Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Electric Actuators Market Foresight
Tier-1 suppliers and vehicle assemblers is bifurcating the procurement landscape as OEMs nearshore powertrain and chassis electrification programs to Mexico. Robert Bosch GmbH leverages its manufacturing footprint in Guadalajara to supply electromechanical actuators for climate control and seat adjustment systems. Denso Corporation anchors its position through captive production of rotary actuators aligned with Japanese OEM assembly lines in Baja California. Continental competes on hydraulic-to-electronic conversion programs, sustaining R&D partnerships with domestic vehicle assemblers in the Bajío region.
Automotive electric actuators are electromechanical devices that convert electrical energy into precise mechanical motion, typically achieving positional accuracy within 0.1 millimeters and operating across temperature ranges from -40°C to 150°C to control vehicle subsystems. Their primary purpose is to replace hydraulic and pneumatic mechanisms with electronically controlled motion systems that reduce weight, improve energy efficiency, and enable software-defined vehicle architectures. Rotary actuators dominate power steering applications due to established torque density requirements, while linear actuators represent the fastest-expanding category as chassis control systems adopt brake-by-wire and active suspension platforms. Electromechanical technology captures the deepest margin pools as OEMs phase out hydraulic architectures, though pneumatic systems retain niche positions in legacy commercial vehicle fleets.
Mexico's Secretary of Environment and Natural Resources (SEMARNAT) enforces NOM-044 emission standards that compel actuator suppliers to certify electronic control precision in powertrain management systems. The Ministry of Economy (SE) administers USMCA rules of origin that require North American content thresholds, shaping where Tier-1 suppliers locate actuator assembly operations. The Federal Consumer Protection Agency (PROFECO) monitors aftermarket replacement parts quality, creating compliance barriers for non-certified aftermarket providers. Stakeholders must monitor how SEMARNAT's alignment with EPA Tier 4 standards and SE's evolving automotive sector incentives reshape supplier qualification timelines and localization mandates for electronic actuator production.
Market Dynamics
The hydraulic-to-electronic actuator conversion is compressing supplier qualification timelines as OEMs nearshore powertrain electrification to Mexico's Bajío corridor. Tier-1 procurement teams now mandate electromechanical architectures for chassis control and seat adjustment systems, forcing component suppliers to revalidate production lines under tighter USMCA content thresholds.
Growth Catalysts
- NOM-044-SEMARNAT emission standards:These regulations compel powertrain management systems to adopt electronic actuator precision, eliminating hydraulic alternatives from new vehicle platforms.
- Brake-by-wire adoption:Chassis electrification programs across Guanajuato and Querétaro assembly plants are specifying linear actuators for active suspension and electronic braking systems.
- USMCA rules of origin:North American content thresholds are localizing actuator assembly operations, drawing Tier-1 suppliers to expand captive production in Nuevo León.
Market Restraints
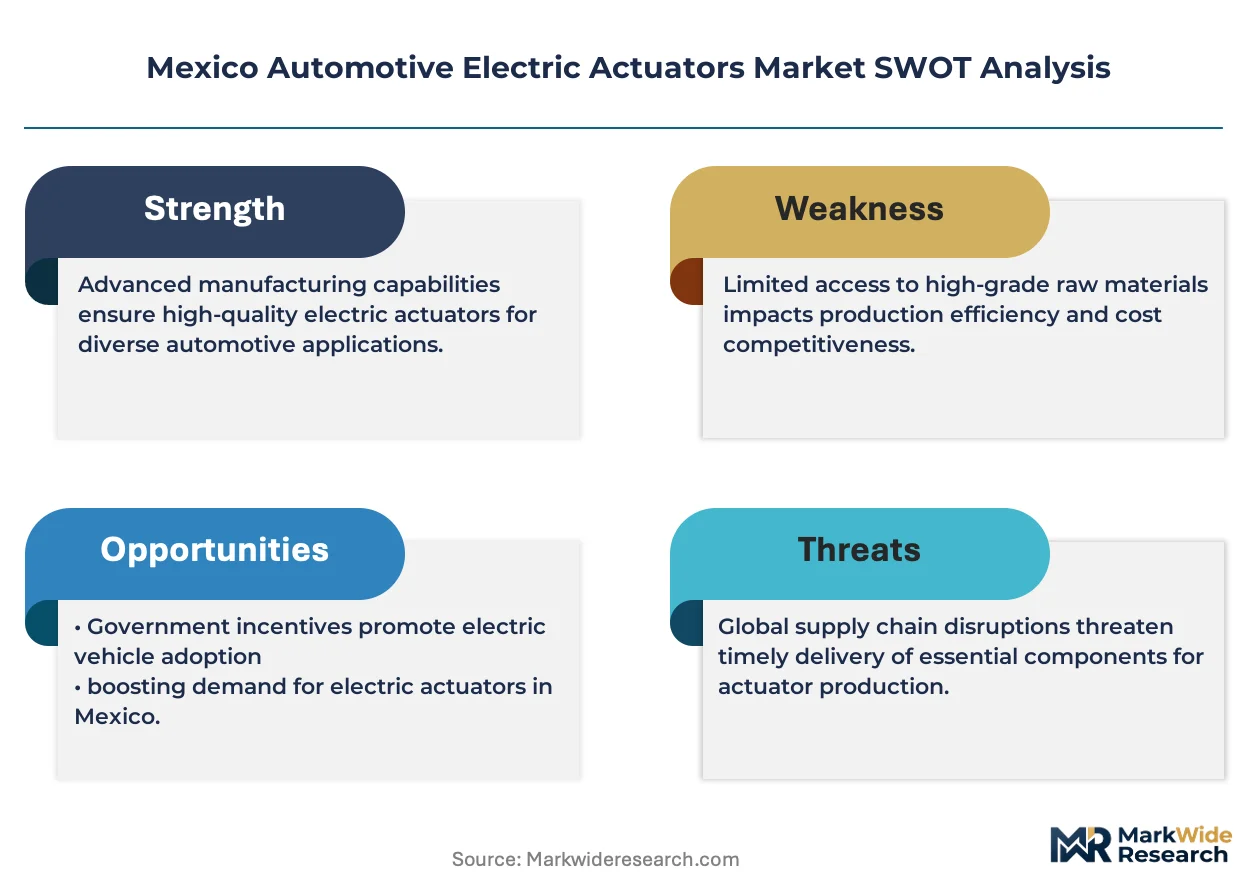
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings constrain permanent magnet motor production for high-torque rotary actuators.
- Single-source semiconductor dependency:Mature node chip supply concentrates in East Asian foundries, creating vulnerability for actuator control module procurement.
- Hydraulic legacy fleet inertia:Commercial vehicle operators in legacy segments delay electronic retrofits due to sunk capital in pneumatic maintenance infrastructure.
Strategic Opportunities
- Aguascalientes powertrain hub:Underpenetrated actuator sourcing for transmission control modules presents white space as Japanese OEMs expand hybrid assembly capacity.
- Software-defined vehicle convergence:Integration of actuator control with domain controllers enables over-the-air calibration updates, opening service revenue streams.
- PROFECO aftermarket certification:Quality enforcement creates barrier-protected replacement parts channels for certified electromechanical suppliers.
Industry Challenges
- Embedded systems firmware integration:Actuator suppliers must synchronize control algorithms with OEM domain architectures, extending development cycles.
- High-voltage safety certification:Electrified chassis systems require ISO 26262 functional safety validation, compressing supplier qualification bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Electric Actuators Market |
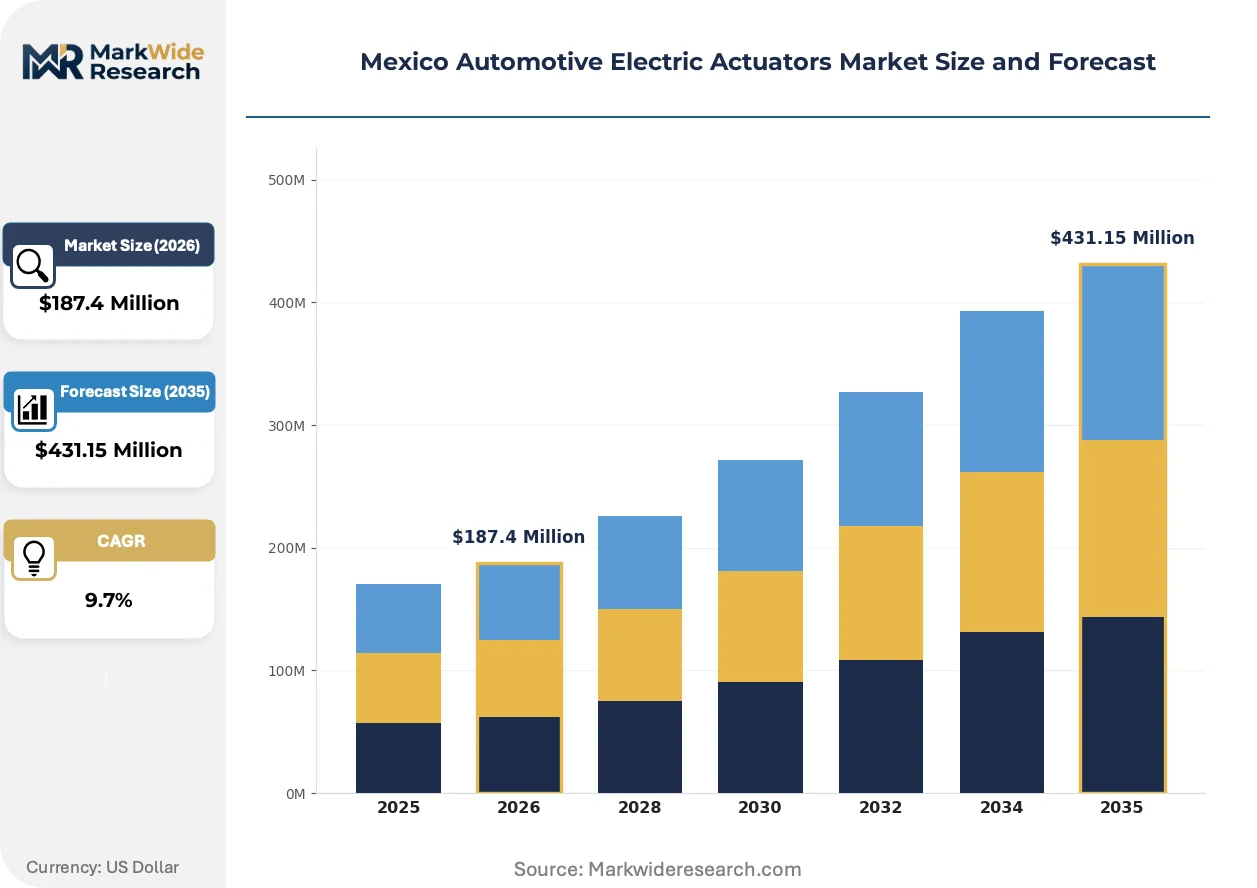
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Actuators, Linear Actuators, Fluid Actuators, Specialty Actuators Application: Power Steering, Chassis Control, Climate Control, Seat Adjustment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electromechanical, Electronic, Hydraulic, Pneumatic |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Mitsubishi Electric, Aptiv PLC, Nidec Corporation, Continental, ZF Friedrichshafen, Johnson Electric, Schaeffler, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Electric Actuators Market Shifts & Advancements
Actuator technology is converging with vehicle electrification architectures, compressing form factors while expanding software control surfaces. Three forces are reshaping how electromechanical motion systems penetrate Mexican automotive supply chains.
Smart material actuators utilizing shape-memory alloys are miniaturizing climate control flap mechanisms while maintaining torque output across SEMARNAT-mandated thermal cycling ranges. Tier-1 HVAC suppliers in Guadalajara are adopting these compact architectures to free packaging space for battery thermal management hardware. The technology is miniaturizing traditional servo motor footprints by sixty percent, enabling multi-zone climate systems in compact vehicle platforms.
SEMARNAT's alignment with EPA Tier 4 emission protocols is mandating real-time actuator position feedback in exhaust gas recirculation systems. This regulatory convergence forces suppliers to integrate Hall-effect sensors directly into electromechanical housings, eliminating external encoder modules. Powertrain electrification programs in Querétaro are most affected, with OEMs now specifying sealed actuator assemblies for underhood thermal environments.
Buyer consolidation among Bajío-based OEM assembly plants is compressing supplier negotiation cycles from annual to quarterly frameworks. Tier-1 procurement teams now demand actuator performance guarantees tied to vehicle platform lifecycle volumes rather than discrete component pricing. This behavioral shift is most visible in Guanajuato, where chassis system integrators are consolidating vendor panels to three qualified sources per actuator category.
Mexico Automotive Electric Actuators Market Segmentation
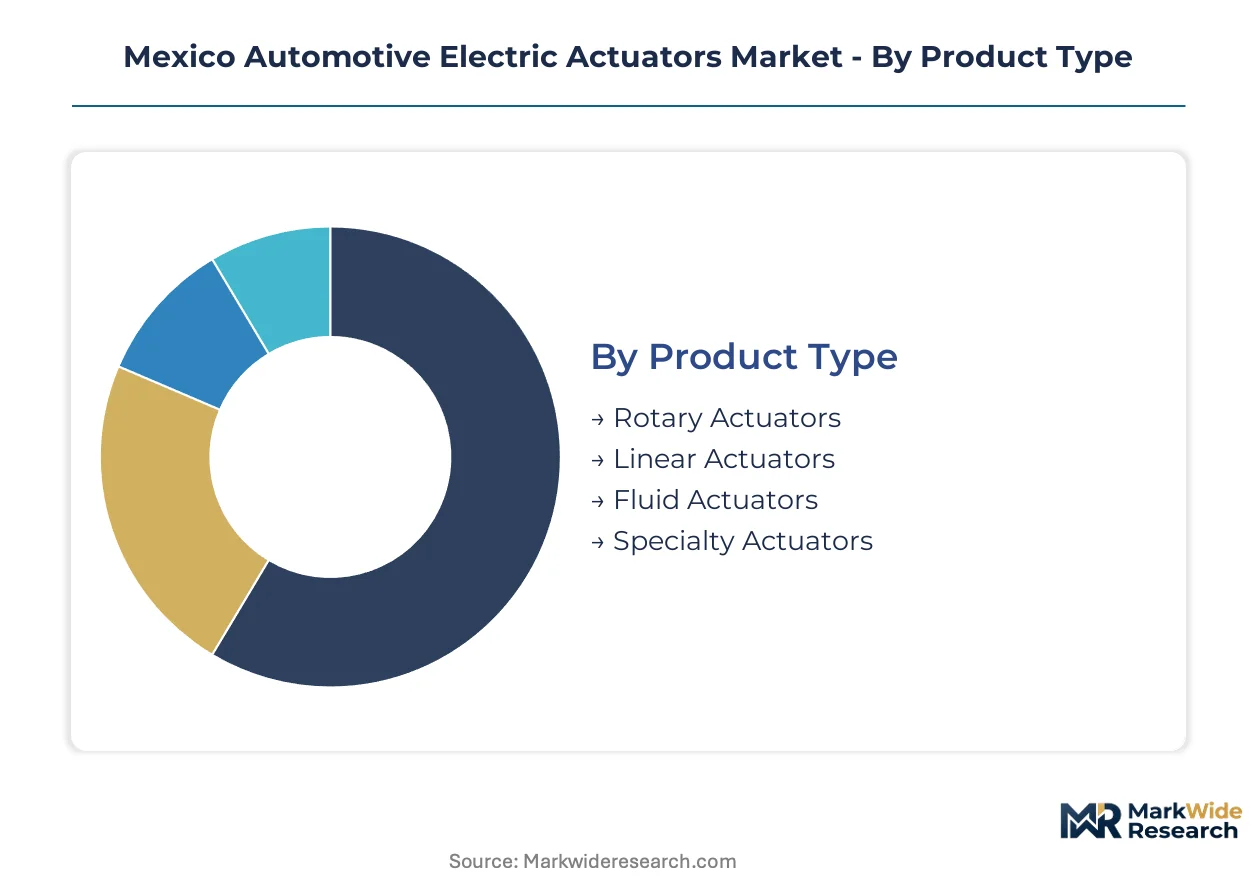
Segmentation reveals how hydraulic-to-electronic substitution pressure varies across actuator architectures and buyer categories. Suppliers must align qualification investments with segments where OEM procurement mandates are tightening fastest.
Product Type:
Rotary actuators face the most intense substitution threat as power steering electrification eliminates hydraulic rack-and-pinion systems across Mexican assembly plants.
- Rotary Actuators:Permanent magnet synchronous motors deliver torque density exceeding 15 Nm/kg for steering column applications. Demand concentrates in Guanajuato powertrain facilities where Japanese OEMs specify electromechanical architectures for EPS platforms under NOM-044 compliance timelines.
- Linear Actuators:Ball-screw and belt-drive mechanisms achieve positional repeatability within 0.05 millimeters for brake-by-wire calipers. Querétaro chassis integrators are sourcing these for active suspension programs as USMCA content rules localize assembly operations.
- Fluid Actuators:Hydraulic servo valves retain position in legacy commercial vehicle braking systems where fleet operators delay electronic retrofits due to sunk maintenance infrastructure.
- Specialty Actuators:Shape-memory alloy mechanisms address thermal cycling requirements in SEMARNAT-certified exhaust gas recirculation systems.
Rotary actuators anchor the volume base while linear actuators gain share at the steepest rate.
Application:
Cost tier differentiation separates chassis control applications commanding premium pricing from climate control systems competing on unit economics.
- Power Steering:Column-assist and rack-assist electric motors operate across -40°C to 150°C thermal envelopes with ISO 26262 ASIL-D functional safety certification. Bajío corridor OEMs mandate electromechanical replacements for hydraulic pumps as NOM-044 standards phase out fluid-based architectures.
- Chassis Control:Active suspension and brake-by-wire systems integrate linear actuators with domain controllers for over-the-air calibration updates. Guanajuato assembly plants specify these for premium vehicle platforms where software-defined vehicle architectures command supplier R&D partnerships.
- Climate Control:HVAC flap actuators prioritize compact form factors over precision, with Guadalajara suppliers adopting smart material architectures to free packaging space for battery thermal management hardware.
- Seat Adjustment:Memory-position motors compete on cost-per-function, with Nuevo León seat integrators consolidating vendor panels to three qualified sources per actuator category.
Power steering applications dominate current procurement volumes while chassis control systems expand most quickly as electrification programs accelerate.
End User:
Customer type determines qualification burden and contract structure, with OEM direct procurement imposing the steepest certification requirements.
- OEMs:Vehicle manufacturers in Aguascalientes and Querétaro specify actuator performance guarantees tied to platform lifecycle volumes rather than discrete component pricing, compressing supplier negotiation cycles to quarterly frameworks.
- Tier-1 Suppliers:Robert Bosch GmbH and Denso Corporation operate captive production in Guadalajara and Baja California respectively, sourcing electromechanical architectures for climate control and seat adjustment systems under USMCA content thresholds.
- Vehicle Assemblers:Contract manufacturers in the Bajío corridor rely on Tier-1 system integrators for actuator procurement, limiting direct supplier relationships.
- Aftermarket Providers:PROFECO quality enforcement creates certification barriers for non-certified replacement parts providers, protecting channels for electromechanical suppliers with documented SEMARNAT compliance.
Tier-1 suppliers capture the deepest integration relationships while aftermarket providers face the steepest compliance barriers to market entry.
Technology:
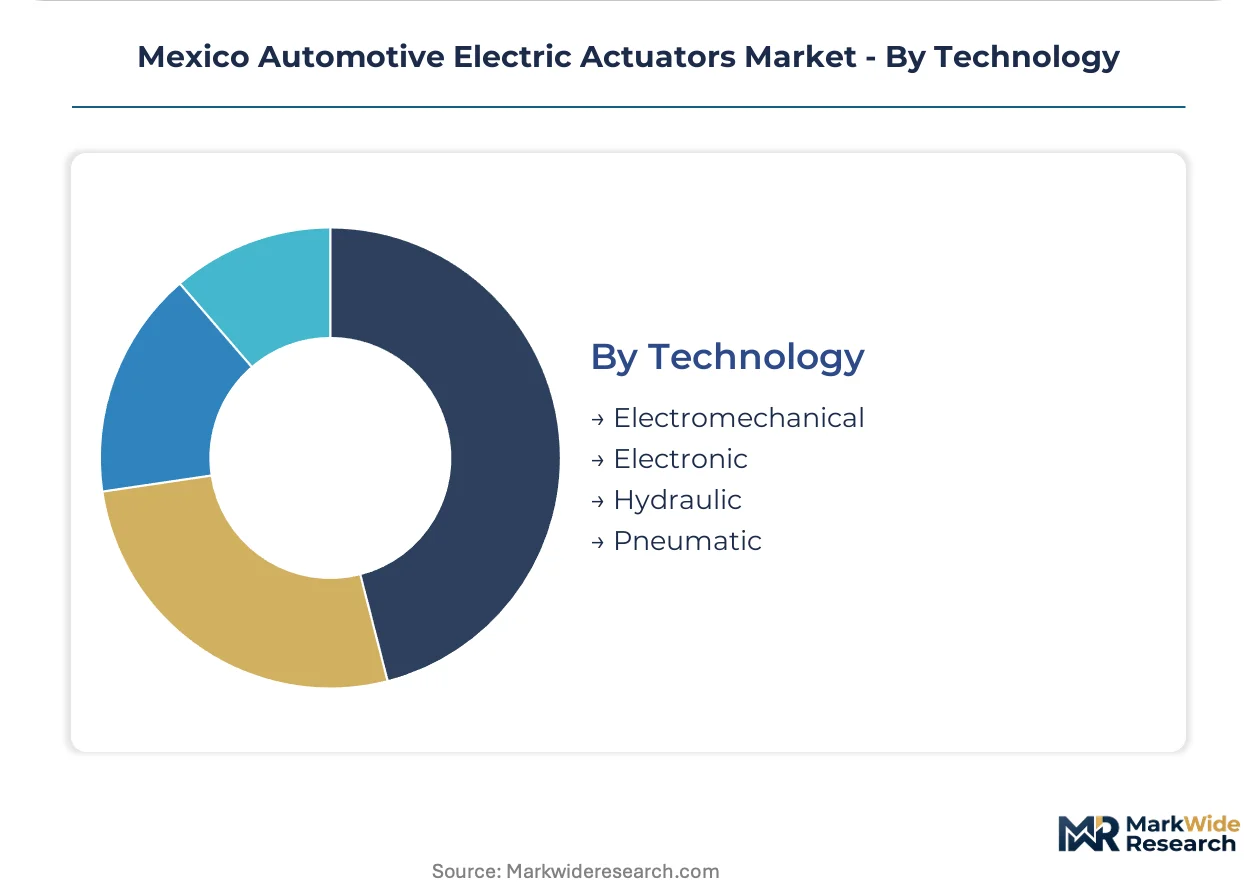
Technology maturity curves separate declining hydraulic architectures from electromechanical systems capturing margin expansion.
- Electromechanical:Brushless DC motors with integrated position sensors achieve closed-loop control precision required for SEMARNAT-certified powertrain management. OEMs in Nuevo León and Guanajuato mandate these architectures for all new vehicle platforms.
- Electronic:Solid-state actuator controllers without moving parts address high-voltage safety requirements in electrified chassis systems, requiring ISO 26262 functional safety validation that compresses supplier qualification bandwidth.
- Hydraulic:Fluid power systems retain niche position in legacy commercial vehicle fleets where pneumatic maintenance infrastructure creates retrofit inertia.
- Pneumatic:Compressed air mechanisms persist in heavy-duty braking applications among operators delaying capital replacement cycles.
Electromechanical technology commands the dominant revenue share while electronic architectures climb the fastest as solid-state designs penetrate high-voltage chassis systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lázaro Cárdenas port complex anchors Mexico's automotive electric actuator supply chain, handling specialized containerized components for Guanajuato and Querétaro assembly plants. This Pacific gateway enables just-in-time delivery of electromechanical subsystems to Tier-1 suppliers operating under USMCA content thresholds.
Nuevo León
Monterrey's industrial corridor concentrates brake-by-wire actuator sourcing for premium vehicle platforms. The state's economic development agency coordinates with SEMARNAT to fast-track environmental certifications for electromechanical production facilities. Apodaca and Santa Catarina host expanding captive assembly operations serving Detroit Three OEMs.
Guanajuato
Silao and Irapuato anchor power steering electrification programs for Japanese and German OEMs. NOM-044 compliance deadlines are compressing supplier qualification timelines for rotary actuator procurement. The Bajío automotive corridor's transmission control module demand is drawing Tier-1 integrators to localize electromechanical assembly.
Querétaro
Active suspension and chassis control actuator demand concentrates in El Marqués industrial parks. The state's aerospace-adjacent precision manufacturing base is transferring tolerances to automotive electromechanical systems. OEM procurement teams specify linear actuators with domain controller integration for software-defined vehicle architectures.
Baja California
Tijuana and Mexicali assembly plants source rotary actuators for climate control and seat adjustment systems. The region's maquiladora infrastructure supports Japanese OEM supply chains with captive production aligned to USMCA rules of origin. Cross-border logistics corridors enable rapid qualification cycles for electronic control module suppliers.
Jalisco
Guadalajara's electronics manufacturing cluster is pivoting toward HVAC actuator production for battery thermal management integration. The state's technology parks house R&D partnerships between domestic assemblers and electromechanical specialists. Tlajomulco's industrial zones are absorbing overflow capacity from Nuevo León qualification bottlenecks.
Mexico Automotive Electric Actuators Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and captive production dimensions. The supplier base concentrates around three tiers: integrated system houses with full actuator-controller integration, component specialists focused on motor and geartrain manufacturing, and regional assemblers serving aftermarket channels. Market structure favors scale-driven consolidation in rotary actuator categories while linear actuator segments retain fragmentation due to application-specific customization. Dominant competitive moves include backward integration into permanent magnet supply chains and strategic partnerships for ISO 26262 functional safety certification.
Among Germany-based integrated system houses, Robert Bosch GmbH and Continental exemplify the captive production archetype with established Mexican manufacturing footprints. Denso Corporation represents Japanese specialists leveraging Baja California proximity to OEM assembly lines. Nidec Corporation anchors the motor-centric tier with permanent magnet synchronous motor expertise. Johnson Electric occupies a position bridging component supply and system integration for climate control applications.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Mitsubishi Electric |
| Aptiv PLC |
| Nidec Corporation |
| Continental |
| ZF Friedrichshafen |
| Johnson Electric |
| Schaeffler |
| Others |
Supply & Pricing Matrix
Scale economies in permanent magnet motor production concentrate pricing power among Guanajuato-based Tier-1 suppliers with captive winding and magnet-assembly operations. This concentration compresses price floors for electromechanical architectures while hydraulic-to-electronic conversion mandates force smaller component suppliers to absorb requalification costs under tighter USMCA content thresholds.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by ISO 26262 certification grade and volume commitment scale. Premium tiers command position for ASIL-D certified chassis control actuators with domain controller integration, while economy tiers serve climate control flap mechanisms competing on unit cost. Pricing pressure stems from rare earth magnet cost volatility constraining permanent magnet motor margins. Aftermarket providers face the steepest price sensitivity due to PROFECO certification barriers, whereas OEM direct procurement tolerates premium positioning for platform-lifecycle performance guarantees.
Supply Chain Analysis
Just-in-time delivery preferences dominate Tier-1 procurement, with Lázaro Cárdenas port infrastructure enabling 72-hour component cycles to Nuevo León assembly plants. Supply draws from China for rare earth processing, Japan for precision geartrain manufacturing, and domestic Mexican facilities for final electromechanical assembly under USMCA rules. Single-source semiconductor dependency for mature-node actuator controllers creates vulnerability to East Asian foundry allocation. Distribution runs through captive Tier-1 channels directly into OEM assembly lines, bypassing independent distributor networks for electronic actuator categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico automotive electric actuators market sits in early-cycle expansion as NOM-044 emission standards eliminate hydraulic alternatives from new vehicle platforms, creating forced-adoption tailwinds for electromechanical architectures.
For Market Incumbents: Consolidate vendor panel positions in Guanajuato powertrain facilities by backward integration into permanent magnet supply chains and captive sensor-module production. Hydraulic-to-electronic conversion timelines compress qualification bandwidth; incumbents must lock ASIL-D certification capacity before Tier-1 procurement teams finalize three-source panels per actuator category. Channel control through direct OEM platform engineering relationships represents the critical defensive lever. For New Entrants and Emerging Players: SEMARNAT fast-track environmental certification for electromechanical production facilities offers entry acceleration. Aguascalientes transmission control module sourcing presents the most penetrable white space as Japanese OEMs expand hybrid assembly capacity. Target aftermarket channels where PROFECO quality enforcement protects certified replacement parts margins. Go-to-market positioning should emphasize software-defined vehicle compatibility with over-the-air calibration capability. For Investors and Strategic Acquirers: Component specialists with ISO 26262 functional safety validation and existing Tier-2 relationships to Bosch or Denso captive operations represent the highest-conviction acquisition archetype. Long-term viability hinges on electrified chassis content expansion across the projection horizon. Watch brake-by-wire adoption rates in Querétaro assembly plants as the inflection signal for linear actuator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Supply Security | Backward integration into neodymium sourcing insulates Tier-1 suppliers from dysprosium price volatility. |
| ASIL-D Certification Investment | ISO 26262 functional safety validation opens chassis control actuator procurement to Nuevo León OEMs. |
| Domain Controller Integration | Software-defined vehicle architecture compatibility enables over-the-air calibration service revenue streams. |
| USMCA Content Localization | Captive assembly operations in Guanajuato satisfy North American content thresholds for Tier-1 qualification. |
| Smart Material Actuator Development | Shape-memory alloy miniaturization frees packaging space for battery thermal management hardware in Guadalajara HVAC systems. |
Research Methodology
Operator-level perspectives from Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and SEMARNAT compliance officers anchored the qualitative base. Primary interview insights combined with vehicle production databases, USMCA trade flow records, IHS Markit registration data, and SEC filings from listed automotive component suppliers. Bottom-up actuator unit economics triangulated against top-down market sizing from regional assembly plant capacity announcements.
Sensitivity analysis tested forecast outputs against rare earth price volatility scenarios and semiconductor supply disruption assumptions across the analysis window. Segmentation dimensions modeled include actuator architecture, application system, OEM tier positioning, technology maturity, and regional production cluster. CAGRs derived from fitted adoption curves for hydraulic-to-electronic substitution rates, weighted by NOM-044 compliance phase-in schedules and USMCA localization incentives. Industry-specific inputs incorporated brake-by-wire penetration assumptions and powertrain electrification program timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained USMCA trade policy and SEMARNAT-EPA regulatory alignment; material deviation would warrant model refresh. Forecasts reflect assumptions of Tier-1 supplier consolidation to three qualified sources per actuator category and captive production localization trends. Revision becomes warranted when rare earth magnet cost volatility or semiconductor supply concentration crosses thresholds that alter electromechanical actuator cost parity against hydraulic alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market