
 Global Automated External Defibrillators Market | 2026-2036
Global Automated External Defibrillators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated External Defibrillators Market Analysis
The EU Green Deal's healthcare decarbonization targets is decoupling procurement criteria from pure cost metrics across European hospital systems. Philips Healthcare leverages its integrated resuscitation ecosystem to sustain premium positioning in acute care settings. ZOLL Medical Corporation anchors its competitive stance through real-time data connectivity platforms that link deployed units to emergency response networks.
An automated external defibrillator constitutes a portable electronic device that analyzes cardiac rhythm and delivers biphasic electrical shocks at 150-360 joules to restore normal heart function during sudden cardiac arrest. The apparatus integrates ECG sensors, capacitor banks, and voice-guided instruction systems designed for operation by laypersons in pre-hospital environments. Semi-automatic AEDs occupy the largest installed base due to their balance of user control and fail-safe operation, while smartphone-enabled AEDs represent the fastest-expanding technology segment as Bluetooth-linked apps streamline maintenance tracking and geolocation services. Pediatric AEDs command distinct margin pools given specialized electrode configurations and dose-attenuation algorithms required for patients under eight years.
The FDA's 510(k) clearance pathway and the EU MDR's Class III device classification impose stringent clinical evidence requirements that filter market entrants and elevate compliance costs for manufacturers. Japan's PMDA enforces JIS T 1205 performance standards that constrain product design flexibility while ensuring shock delivery consistency across temperature and humidity extremes. Stakeholders must monitor how data-enabled AED architectures interface with emerging interoperability mandates from WHO digital health frameworks and national emergency medical dispatch systems.
Market Dynamics
Deployment mandates from educational institutions and workplace safety regulators are compressing replacement cycles and forcing manufacturers to prioritize connectivity-ready architectures over legacy standalone units.
Growth Catalysts
- Campus Safety Mandates:School districts across the United States and regional education ministries in Germany are requiring AED installation in all secondary facilities, creating recurring procurement pipelines.
- Bluetooth-Linked Maintenance Platforms:Smartphone-enabled AEDs with automated self-test reporting are reducing liability exposure for facility managers and accelerating replacement of aging installed bases.
- Japan's JIS T 1205 Standards:Stringent performance requirements for shock delivery consistency are elevating product reliability benchmarks and filtering marginal suppliers from hospital procurement lists.
Market Restraints
- Capacitor Bank Supply Concentration:Specialty high-voltage capacitor manufacturing concentrates in Japanese and German component suppliers, exposing AED assemblers to extended lead times during demand surges.
- EU MDR Class III Compliance Costs:Clinical evidence requirements for conformity assessment have doubled documentation burdens and extended time-to-market for new entrants by 18-24 months.
- Pad Electrode Shelf-Life Limitations:Gel-based adhesive electrodes require replacement every 2-4 years regardless of use, creating ongoing cost friction for price-sensitive municipal buyers.
Strategic Opportunities
- India's Healthcare Infrastructure Expansion:The country's PLI scheme for medical devices and emerging public access defibrillation pilots in Mumbai and Delhi present first-mover positioning for connectivity-integrated units.
- Drone-Enabled Emergency Delivery Networks:Integration with aerial dispatch systems in Sweden and the United Arab Emirates is creating demand for ruggedized, GPS-trackable AED form factors.
- EU Green Deal Procurement Criteria:Healthcare decarbonization targets are opening premium positioning for manufacturers with verified lifecycle carbon footprints and recyclable electrode programs.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortages of specialists capable of integrating ECG analysis algorithms with real-time cloud telemetry are constraining R&D velocity for mid-tier manufacturers.
- FDA 510(k) Predicate Device Dependencies:Substantial equivalence pathways require alignment with legacy product architectures, complicating breakthrough form factor innovations and extending regulatory review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated External Defibrillators Market |
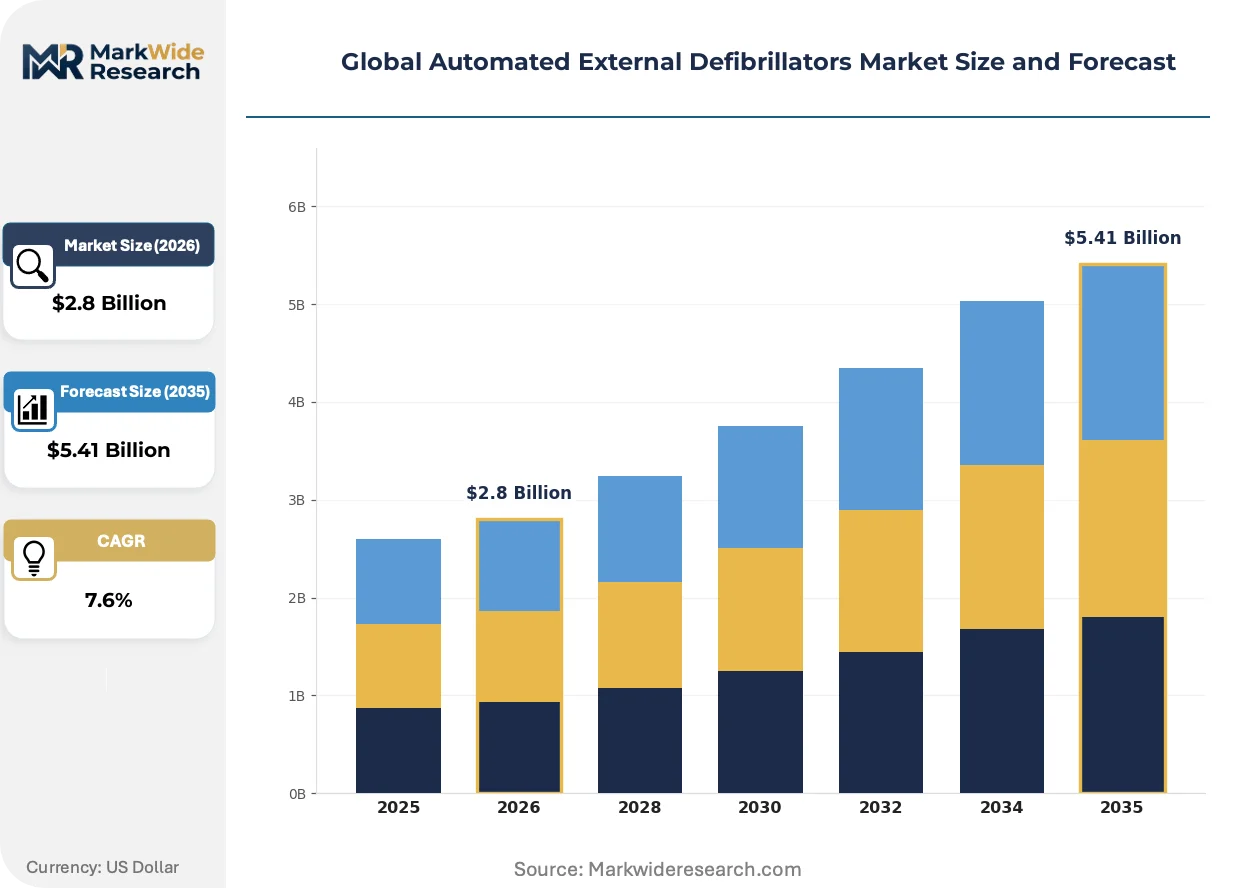
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard AEDs, Pediatric AEDs, Fully Automatic AEDs, Semi-Automatic AEDs End User: Hospitals, EMS Providers, Corporate Offices, Educational Institutions Technology: Wearable Defibrillators, Traditional Defibrillators, Smartphone-Enabled AEDs, Data-Enabled AEDs Distribution Channel: Online Retail, Direct Sales, Medical Supply Stores, Distributors |
| Companies Covered | Philips Healthcare, ZOLL Medical Corporation, Stryker Corporation, Nihon Kohden Corporation, Schiller AG, Medtronic plc, CU Medical Systems, Mindray, Defibtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated External Defibrillators Market Emerging Trajectories
Real-time data architectures and predictive maintenance algorithms are displacing reactive service models across the installed base, while regulatory pressure on traceability accelerates hardware refresh cycles.
Artificial intelligence-enabled rhythm analysis is automating shock decision protocols with greater sensitivity to pulseless electrical activity and asystole patterns. Hospital systems in South Korea and the Netherlands are deploying these units in emergency departments to reduce operator-dependent variability. The technology is automating quality assurance processes that previously required manual ECG strip review, compressing training requirements for clinical staff.
The EU MDR's Unique Device Identification mandates are forcing serialization of every electrode pad and battery component at the unit-of-use level. Manufacturers serving European markets must now maintain centralized databases linking device history records to patient events. High-volume distributors in France and Italy are absorbing compliance costs through consolidated logistics partnerships with notified bodies.
Facility managers are unbundling after-sales service contracts from initial hardware purchases, driving competitive pressure on standalone maintenance pricing. Corporate wellness programs in the United States are negotiating direct relationships with remote monitoring platforms rather than accepting manufacturer-captive service tiers. This disintermediation is most pronounced in multi-site retail and hospitality chains seeking centralized visibility across dispersed AED fleets.
Global Automated External Defibrillators Market Segmentation
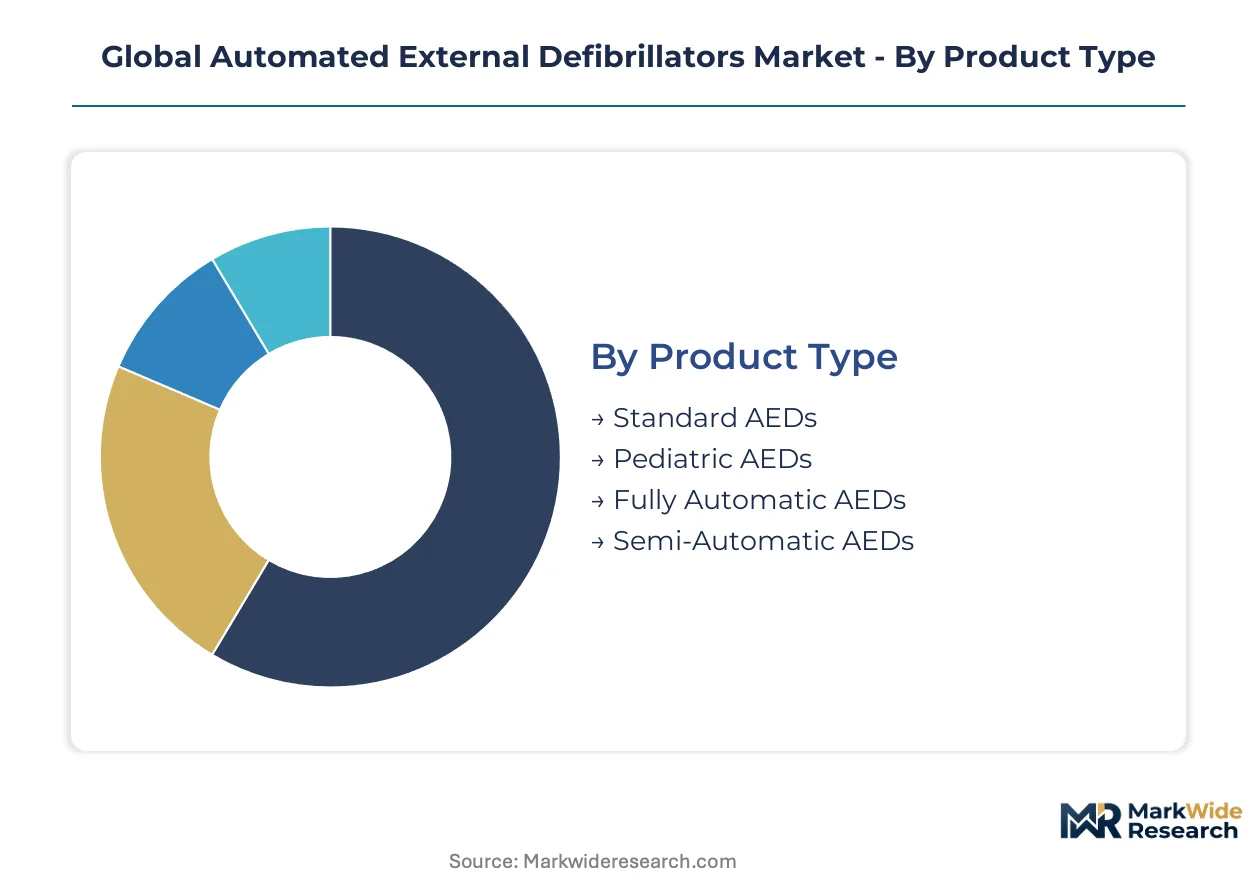
Segmentation in the AED market reveals how procurement priorities diverge across clinical versus layperson environments, with technology sophistication and regulatory compliance serving as the primary axes of differentiation. Understanding these splits enables manufacturers to align R&D investment with specific margin pools and replacement cycle dynamics.
Product Type:
Volume concentrates in semi-automatic configurations, while premium positioning accrues to specialized pediatric variants and fully automatic systems with minimal user intervention.
- Semi-Automatic AEDs:These devices require operator confirmation before shock delivery, balancing user control with built-in safety interlocks. Demand concentrates in United States school districts and German workplace safety programs where liability mitigation drives procurement specifications. The installed base remains largest due to regulatory familiarity and training infrastructure compatibility.
- Pediatric AEDs:Specialized units incorporate dose-attenuation algorithms and smaller electrode geometries calibrated for patients under eight years. Premium margins persist in pediatric hospital wings and ambulatory surgery centers across Japan and the Netherlands where JIS T 1205 and EU MDR standards enforce strict age-stratified protocols.
- Standard AEDs:General-purpose adult-configured devices dominate municipal procurement and public access installations.
- Fully Automatic AEDs:Shock delivery proceeds without operator button press, reducing hesitation errors in high-stress environments.
Today's leader: Semi-Automatic AEDs. Tomorrow's challenger: Fully Automatic AEDs.
End User:
Application context determines connectivity requirements, with acute care settings demanding EHR integration and public deployment prioritizing ruggedization and theft deterrence.
- Hospitals:Acute care settings require biphasic waveform consistency, paddle-to-pad compatibility, and telemetry integration with emergency department information systems. Procurement in South Korea and the Netherlands increasingly specifies AI-enabled rhythm analysis to reduce operator-dependent variability during resuscitation events.
- Educational Institutions:Campus safety mandates across United States school districts and German regional education ministries are compressing replacement cycles. These buyers prioritize voice-guided instruction clarity, automated self-test reporting, and Bluetooth-linked maintenance platforms that reduce facility manager liability exposure.
- EMS Providers:Pre-hospital deployment demands ruggedized housings, extended temperature operating ranges, and compatibility with regional dispatch protocols.
- Corporate Offices:Corporate wellness programs in United States multi-site retail and hospitality chains are disintermediating manufacturer-captive service tiers in favor of direct remote monitoring platform relationships.
Educational Institutions are expanding most quickly; Hospitals retain the deepest procurement budgets per unit.
Technology:
Connectivity architectures are displacing standalone units, with data transmission capabilities now table stakes for institutional procurement rather than premium add-ons.
- Smartphone-Enabled AEDs:Bluetooth-linked applications stream automated self-test results, geolocation data, and battery status to centralized fleet management dashboards. Adoption accelerates in United Arab Emirates drone-enabled emergency networks and Swedish aerial dispatch pilots where GPS-trackable form factors enable rapid deployment verification.
- Data-Enabled AEDs:Real-time cloud telemetry interfaces with national emergency medical dispatch systems and WHO digital health frameworks, compressing response coordination delays. Hospital systems in South Korea deploy these units to automate quality assurance processes previously requiring manual ECG strip review.
- Traditional Defibrillators:Non-connected legacy architectures persist in price-sensitive municipal segments with extended replacement timelines.
- Wearable Defibrillators:Vest-based systems provide continuous monitoring for high-risk cardiac patients outside acute settings.
Data-Enabled AEDs command current premium positioning; Smartphone-Enabled AEDs are gaining share fastest among new installations.
Distribution Channel:
Channel selection reflects buyer sophistication, with institutional purchasers bypassing retail intermediaries while smaller facilities rely on distributor technical support.
- Direct Sales:Manufacturers maintain captive salesforces for hospital systems and large corporate accounts requiring customized fleet management integration. United States corporate wellness programs and French hospital consortiums negotiate centralized visibility across dispersed AED deployments through direct platform relationships.
- Distributors:Medical supply distributors absorb EU MDR Unique Device Identification compliance costs through consolidated logistics partnerships with notified bodies, serving Italian and French high-volume procurement.
- Online Retail:E-commerce channels serve small business and individual purchasers with standardized configurations.
- Medical Supply Stores:Local brick-and-mortar outlets provide immediate availability for urgent replacement needs and training equipment bundling.
Direct Sales currently dominates institutional volume; Distributors are consolidating position as compliance complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automated external defibrillator industry traces its commercial roots to the United States, where early public access defibrillation programs in the 1990s established the template for layperson-operated cardiac emergency response systems now replicated worldwide.
United States
Campus safety mandates from school districts in Texas and Florida drive recurring procurement volumes for semi-automatic units with voice-guided instruction. The FDA's 510(k) clearance pathway filters market entrants through substantial equivalence requirements. Corporate wellness investments across multi-site retail chains in California and New York Metro accelerate replacement of legacy standalone units with connectivity-ready architectures.
Germany
Regional education ministries in Bavaria and North Rhine-Westphalia mandate AED installation in all secondary facilities, compressing replacement cycles. The EU MDR's Class III device classification and stricter conformity assessments elevate compliance costs and documentation burdens. Industrial clusters around Munich and Stuttgart concentrate distribution partnerships absorbing Unique Device Identification serialization requirements through consolidated logistics.
Japan
PMDA enforcement of JIS T 1205 performance standards constrains product design flexibility while ensuring shock delivery consistency across temperature extremes. Pediatric hospital wings in Tokyo and Osaka command premium margins for specialized dose-attenuation algorithms. Ambulatory surgery centers in the Kansai region prioritize units meeting stringent age-stratified protocols.
Netherlands
Hospital systems in Amsterdam and Rotterdam deploy AI-enabled rhythm analysis units to reduce operator-dependent variability during resuscitation events. The EU Green Deal's healthcare decarbonization targets open premium positioning for manufacturers with verified lifecycle carbon footprints. Emergency departments across the Randstad automate quality assurance processes previously requiring manual ECG strip review.
India
The PLI scheme for medical devices and emerging public access defibrillation pilots in Mumbai and Delhi present first-mover positioning for connectivity-integrated units. CDSCO regulatory pathways are streamlining as the country expands healthcare infrastructure. Procurement concentrates in Maharashtra and Karnataka where corporate hospital chains and municipal health departments anchor initial deployment volumes.
Global Automated External Defibrillators Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration and regulatory compliance capabilities. The vendor base organizes into three tiers: integrated resuscitation ecosystem providers, real-time data connectivity specialists, and regional assembly operations serving price-sensitive municipal segments. Consolidation pressures favor manufacturers with captive compliance expertise and established notified body relationships. Dominant competitive moves include portfolio diversification into smartphone-enabled maintenance platforms and strategic partnerships with drone-enabled emergency delivery networks.
Within the integrated ecosystem tier, Philips Healthcare and ZOLL Medical Corporation occupy positions exemplifying premium-tier anchoring through resuscitation platform breadth and data connectivity specialization respectively. Stryker Corporation represents the diversified medical technology archetype with defibrillator assets sitting within broader emergency care portfolios. These three companies illustrate how regulatory compliance scale and connectivity architecture investment separate margin tiers in institutional procurement.
| Leading Market Players |
|---|
| Philips Healthcare |
| ZOLL Medical Corporation |
| Stryker Corporation |
| Nihon Kohden Corporation |
| Schiller AG |
| Medtronic plc |
| CU Medical Systems |
| Mindray |
| Defibtech |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EU MDR Class III compliant units and legacy FDA 510(k) cleared devices manifests in divergent pricing power and supply chain sourcing strategies across institutional and municipal procurement channels. Premium connectivity-integrated architectures command sustained margin pools through notified body audit trails, while price-sensitive school districts and municipal buyers concentrate volume in standard configurations with compressed service bundling.
Pricing Analysis
Three-tier pricing structure across premium connectivity-integrated, standard semi-automatic, and economy basic-response levels stratifies procurement budgets by end-user sophistication and liability exposure tolerance. Price differentiation hinges on FDA 510(k) predicate alignment versus EU MDR Class III clinical evidence requirements, alongside real-time telemetry integration depth. Cost compression in standard configurations intensifies as Japanese and German capacitor suppliers extend lead times, forcing assemblers to absorb component volatility. Municipal buyers exhibit highest price sensitivity, while Dutch hospital systems and South Korean emergency departments prioritize AI-enabled rhythm analysis despite premium positioning.
Supply Chain Analysis
Direct-to-hospital and direct-to-corporate channels handle institutional hyperscale demand, while medical supply distributors manage fragmented educational and municipal procurement. Component manufacturing concentrates in Japan for high-voltage capacitors meeting JIS T 1205 standards, Germany for precision electrode substrates, and China for battery cell assemblies. Raw material dependencies include specialty dielectric films, medical-grade conductive gels, and lithium-manganese dioxide power cells. Single-source vulnerability in Japanese capacitor production exposes AED assemblers to demand surge disruptions. Distribution runs through consolidated logistics partnerships with notified bodies for EU MDR compliance serialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR Class III compliance costs in Germany and the Netherlands create margin headroom for manufacturers with established notified body relationships, while India's PLI scheme and CDSCO streamlining offer cost-advantaged production positioning.
For Market Incumbents: Lock in captive supply agreements with Japanese capacitor manufacturers before demand surges from campus safety mandates tighten component availability. Deepen backward integration into electrode pad manufacturing to control gel formulation consistency and reduce pad replacement revenue leakage. Prioritize AI-enabled rhythm analysis R&D to defend premium positioning against emerging connectivity specialists targeting South Korean hospital procurement. For New Entrants and Emerging Players: Capture first-mover positioning in India's Mumbai and Delhi public access defibrillation pilots by bundling connectivity-integrated units with localized maintenance platforms. Exploit underpenetrated drone-enabled emergency delivery networks in Sweden and the United Arab Emirates through ruggedized GPS-trackable form factors. Lead with direct sales relationships to corporate wellness programs seeking disintermediated fleet management visibility. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing EU MDR notified body relationships and scalable connectivity architectures but lacking global distribution depth. Five-to-ten year viability favors acquisition targets with verified lifecycle carbon footprints aligned to EU Green Deal procurement criteria. Watch for inflection when India's CDSCO accelerates regulatory harmonization with international standards, triggering consolidation among domestic assembly operations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Certification Pathway | Notified body alignment unlocks premium hospital procurement in Germany and the Netherlands. |
| Bluetooth-Linked Maintenance Platform Development | Real-time telemetry reduces facility manager liability exposure in United States school districts. |
| Drone-Enabled Form Factor Ruggedization | GPS-trackable units integrate with Swedish and UAE aerial emergency dispatch networks. |
| Backward Integration into Capacitor Sourcing | Captive supply from Japanese manufacturers insulates against component lead time volatility. |
| AI-Enabled Rhythm Analysis Investment | Automated shock protocols reduce operator variability in South Korean emergency departments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and facility directors at educational institutions with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement contract repositories, and customs trade data for capacitor and electrode component flows. Bottom-up installed base modeling and top-down procurement budget analysis triangulated volume estimates across product configurations.
Segment-weighting approaches distributed value and volume projections across semi-automatic versus fully automatic product types, hospital versus educational versus corporate end-user categories, and smartphone-enabled versus data-enabled versus traditional technology tiers, with regional regulatory cluster differentiation for EU MDR, FDA 510(k), and Japan PMDA pathways. CAGRs were derived from replacement cycle compression analysis and connectivity adoption curve modeling, incorporating campus safety mandate implementation timelines and drone-enabled network pilot expansion rates as industry-specific demand drivers across the projection horizon.
Regulatory timeline delays, capacitor supply disruptions, and procurement budget freezes from municipal fiscal stress are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Heart Closure Devices Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Next Generation Nebulizers Market