
 Information Technology Service Management (ITSM) Market | 2026-2036
Information Technology Service Management (ITSM) Market Size, Share, and Industry Trends Forecast 2026-2036
Information Technology Service Management (ITSM) Market Analytics
GDPR Article 32 is realigning the cost-of-entry calculus for ITSM vendors serving European enterprises. ServiceNow leverages its Now Platform to anchor compliance automation workflows across multinational deployments. BMC Software specializes in mainframe-integrated service management for regulated industries with legacy infrastructure burdens. HCL Technologies extends its managed services footprint through AI-augmented incident resolution capabilities.
Information Technology Service Management (ITSM) encompasses the policies, processes, and software frameworks used to design, deliver, manage, and improve IT services within organizations, typically built on ITIL 4 practices with service level agreement enforcement and configuration management database integration. Its primary purpose is to align IT service delivery with business objectives while minimizing disruption and operational cost. Cloud deployment now leads structural growth as enterprises abandon capital-intensive on-premises infrastructure, while incident management commands the largest service type revenue pool due to its universal applicability across verticals. Asset management represents the fastest-expanding segment as organizations prioritize software license optimization and hardware lifecycle tracking under tightened procurement oversight.
ISO 20000 certification requirements and the EU AI Act shape product standards for automated service desk solutions across European markets. The SEC's cybersecurity disclosure rules and HIPAA security provisions in the United States mandate audit-ready incident response documentation, directly expanding ITSM module demand. Stakeholders must evaluate whether their current platforms can absorb emerging AI governance requirements without fragmenting existing service workflows.
Market Dynamics
Federal procurement mandates for FedRAMP-authorized platforms are compressing vendor qualification timelines while cloud-native architectures displace legacy on-premises deployments across enterprise service desks.
Growth Catalysts
- SEC Operational Resilience Guidelines:Financial services institutions accelerate ITSM platform adoption to modernize service desks under mandatory operational resilience frameworks.
- AI-Augmented Incident Resolution:Machine learning capabilities reduce mean time to resolution by automating ticket classification and routing across hybrid infrastructure environments.
- Software License Optimization Mandates:Hardware lifecycle tracking requirements under tightened procurement oversight expand asset management module deployment.
Market Restraints
- Legacy Infrastructure Integration Costs:Mainframe-integrated service management deployments require specialized expertise that inflates total cost of ownership for regulated industries.
- Multi-Cloud Configuration Complexity:Fragmented API standards across hyperscaler environments create interoperability friction in hybrid ITSM implementations.
- GDPR Article 32 Compliance Burden:Data processing security requirements impose architectural constraints that lengthen deployment cycles for European enterprise customers.
Strategic Opportunities
- EU AI Act Governance Workflows:Automated compliance documentation for algorithmic decision-making creates new module demand across European public sector procurement.
- FedRAMP Authorization Acceleration:Federal agency cloud-first mandates open dedicated procurement channels for authorized ITSM platform vendors.
- Configuration Management Database Convergence:Integration between IT asset discovery and service mapping tools enables unified visibility across distributed edge deployments.
Industry Challenges
- ITIL 4 Certification Shortages:Practitioner credential gaps constrain implementation velocity for process maturity assessments in enterprise transformation programs.
- Service Level Agreement Orchestration:Multi-vendor contract management complexity increases operational overhead as organizations fragment workloads across specialized providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Information Technology Service Management (ITSM) Market |
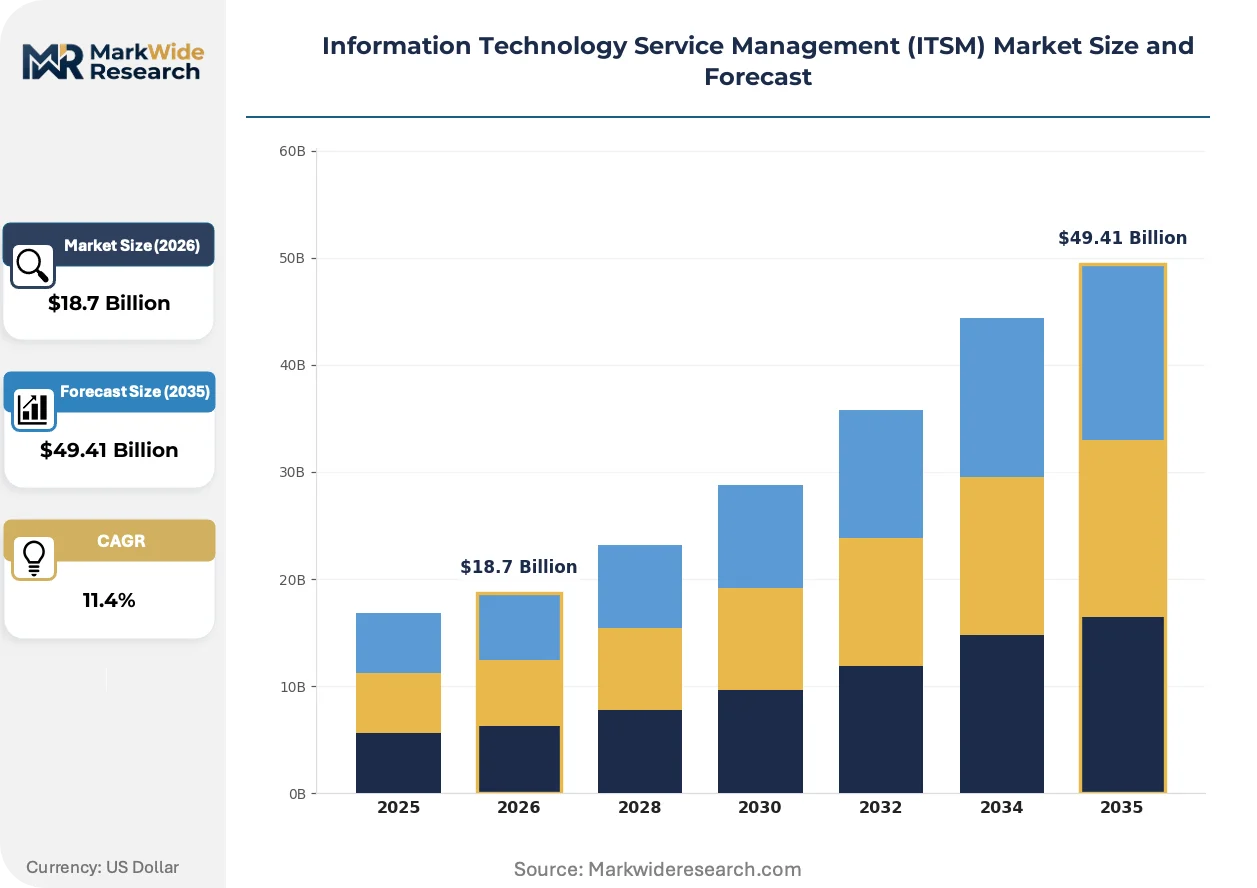
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Services Service Type: Incident Management, Change Management, Asset Management, Service Request Management Industry Vertical: Healthcare, BFSI, Telecommunications, Retail Client Type: Large Enterprises, SMEs, Government Agencies, Educational Institutions |
| Companies Covered | BMC Software, Infosys, ServiceNow, ScienceSoft, HCL Technologies, Atlassian, Micro Focus, Sage IT, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Information Technology Service Management (ITSM) Market Evolving Landscape
Agentic AI architectures are compressing traditional tiered support models while regulatory disclosure requirements reshape incident documentation standards across jurisdictions.
Large language models embedded in service desk portals are unifying knowledge base access with automated response generation. Mid-market enterprises adopt these capabilities fastest as they bypass legacy tier-one staffing models. The technology is unifying previously siloed self-service and assisted support channels into single conversational interfaces.
The EU AI Act's risk classification framework for automated decision systems imposes documentation burdens on AI-enabled ITSM deployments. Vendors must maintain audit trails for algorithmic ticket routing and priority assignment. European financial services and healthcare sectors face the steepest compliance ramps as they retrofit existing automation workflows.
Consumption-based licensing models are displacing perpetual seat agreements in enterprise procurement. Chief information officers now negotiate transaction-volume contracts aligned with actual service desk utilization rather than headcount projections. This shift is most visible in United States technology and professional services verticals where workforce volatility complicates traditional capacity planning.
Information Technology Service Management (ITSM) Market Segmentation
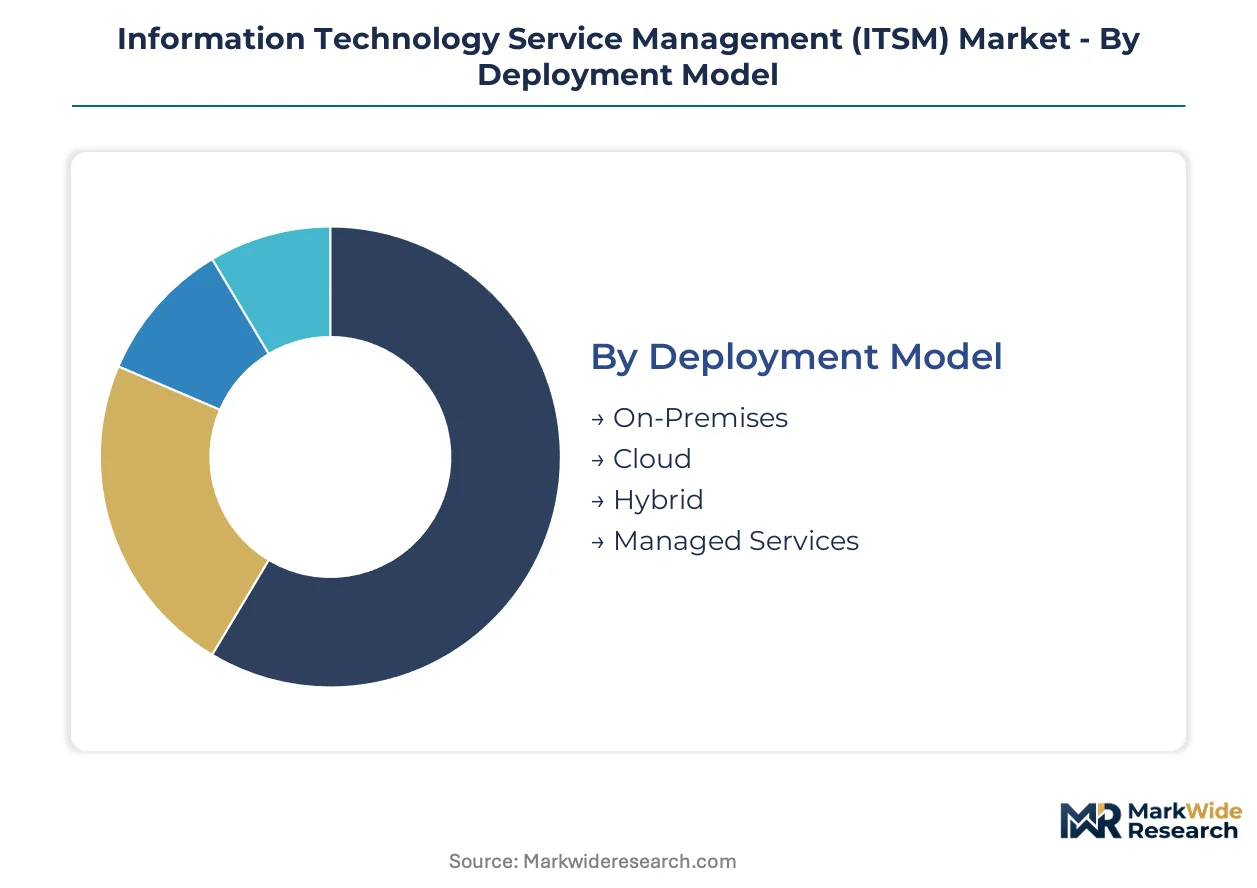
ITSM procurement patterns diverge sharply between organizations seeking standalone control and those embedding service management within broader enterprise platforms. Understanding these integration preferences reveals where vendors must architect for depth versus breadth.
Deployment Model:
Cloud-native deployments embed directly into existing SaaS ecosystems, while on-premises installations demand standalone infrastructure ownership and dedicated operational teams.
- Cloud:Multi-tenant architectures enable rapid provisioning without capital expenditure. Demand concentrates among United States technology firms and federal contractors pursuing FedRAMP authorization under accelerated procurement timelines.
- On-Premises:Organizations retain complete data sovereignty through self-hosted infrastructure. European financial institutions under GDPR Article 32 and German manufacturers prioritize this model for sensitive configuration management database deployments.
- Hybrid:Workload portability across private and public infrastructure. Healthcare systems in the United States balance HIPAA-compliant on-premises asset tracking with cloud-based incident portals.
- Managed Services:Third-party operational responsibility for platform administration. United Kingdom public sector bodies leverage this model to address ITIL 4 certification shortages without internal capability building.
Volume placements concentrate in Cloud; the faster expansion belongs to Managed Services.
Service Type:
Service modules vary in implementation maturity, with foundational capabilities already commoditized while emerging functions command implementation premiums.
- Incident Management:Automated ticket classification and routing through machine learning algorithms. Universally deployed across verticals with mean-time-to-resolution metrics driving renewal decisions in United States telecommunications.
- Asset Management:Hardware lifecycle tracking and software license optimization. Expanding most quickly under tightened procurement oversight in German automotive and United States pharmaceutical supply chains.
- Change Management:Controlled release orchestration with risk assessment workflows. Critical for French aerospace and United States defense contractors under ISO 20000 certification mandates.
- Service Request Management:Self-service catalog fulfillment with automated provisioning. Mid-market enterprises in India adopt this fastest to bypass tier-one staffing constraints.
Revenue gravity sits with Incident Management; steepest expansion trajectory belongs to Asset Management.
Industry Vertical:
Regulatory intensity and legacy infrastructure burden create distinct implementation profiles across sectors.
- BFSI:Operational resilience mandates from the SEC and European Banking Authority drive comprehensive ITSM modernization. Tier-one banks in the United States and United Kingdom lead replacement cycles.
- Healthcare:HIPAA security provisions and FDA quality system requirements mandate audit-ready documentation. United States hospital systems and German medical device manufacturers represent concentrated demand.
- Telecommunications:Service level agreement enforcement across distributed network operations. Indian and Brazilian operators prioritize incident management for customer-facing infrastructure.
- Retail:Seasonal demand volatility complicates capacity planning. Omnichannel fulfillment pressures in the United States and United Kingdom accelerate cloud migration.
Procurement scale peaks in BFSI; healthcare demonstrates the most urgent compliance-driven replacement cycle.
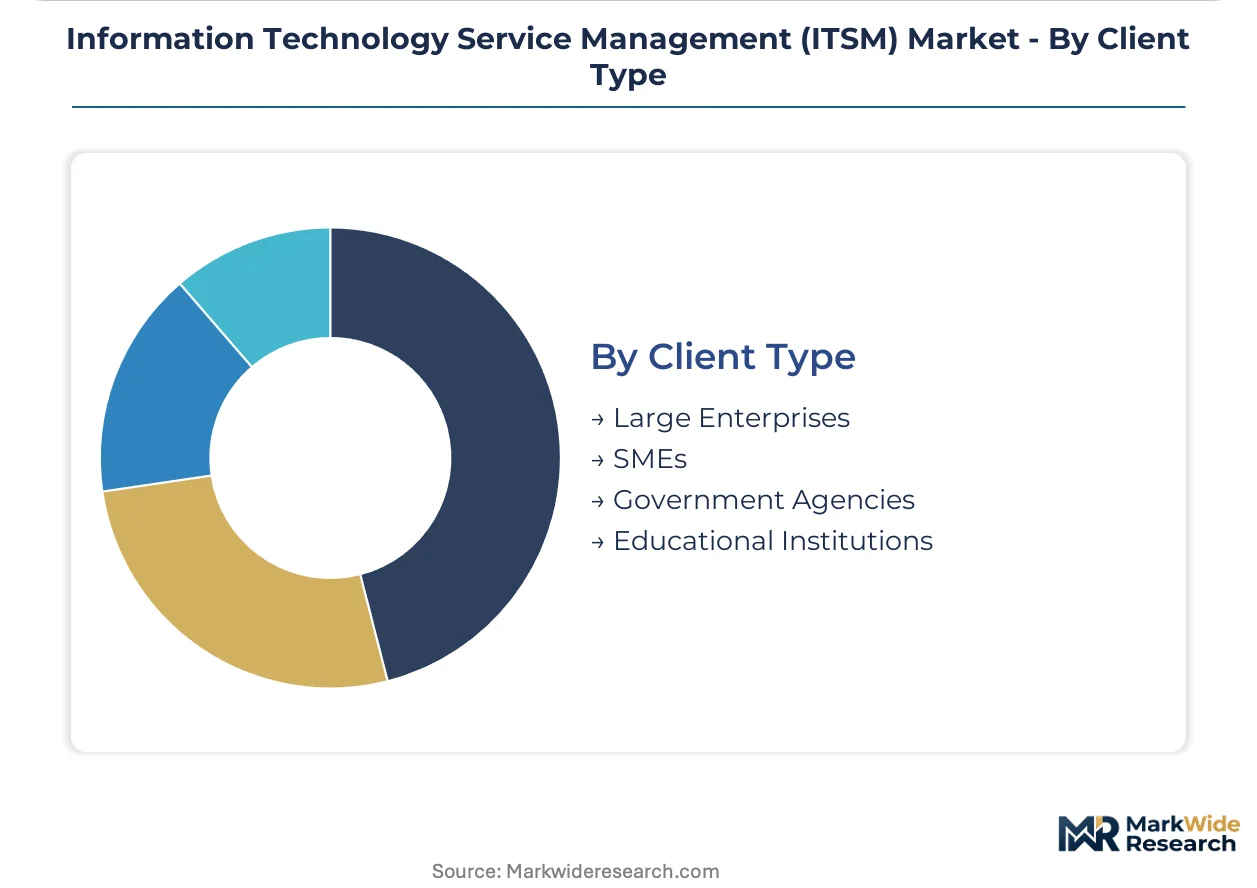
Client Type:
Organizational scale determines whether ITSM functions as integrated enterprise architecture or targeted point solution.
- Large Enterprises:Multi-module deployments with configuration management database convergence. Global manufacturers in Japan and Germany pursue unified visibility across distributed edge infrastructure.
- Government Agencies:FedRAMP-authorized procurement channels and EU public sector frameworks. United States federal and French national administrations mandate cloud-first deployment policies.
- SMEs:Rapid implementation without dedicated ITIL expertise. United Kingdom professional services and Indian technology startups adopt consumption-based licensing fastest.
- Educational Institutions:Budget-constrained modernization of legacy service desks. State university systems in the United States and technical colleges in Germany consolidate fragmented ticketing systems.
Contract value concentrates in Large Enterprises; Government Agencies show the most standardized procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and China's technology corridors concentrate ITSM demand as multinational enterprises establish captive service centers. Tax incentives in these zones accelerate platform procurement for shared services operations. Regional deployment patterns diverge sharply between FedRAMP-authorized federal contractors in the United States and GDPR-constrained European financial institutions.
United States
Federal cloud-first mandates and SEC cybersecurity disclosure rules drive FedRAMP-authorized ITSM procurement. The Department of Defense and civilian agencies compress vendor qualification timelines under accelerated acquisition pathways. Technology clusters in Northern Virginia and Seattle host concentrated demand from federal contractors modernizing service desks.
Germany
Automotive manufacturers and industrial machinery producers prioritize asset management modules for hardware lifecycle tracking. GDPR Article 32 and ISO 20000 certification requirements impose architectural constraints on cloud deployments. Manufacturing hubs in Bavaria and Baden-Württemberg retain on-premises infrastructure for sensitive configuration management database operations.
India
IT services exporters and Global Capability Centers adopt consumption-based licensing to bypass tier-one staffing constraints. The country's national software technology parks offer tax holidays that accelerate managed services adoption. Bengaluru and Hyderabad technology corridors concentrate demand for AI-augmented incident resolution capabilities.
United Kingdom
Operational resilience mandates from the Financial Conduct Authority drive comprehensive ITSM modernization among tier-one banks. ITIL 4 certification shortages push public sector bodies toward managed services arrangements. London financial services and Manchester public sector clusters represent distinct procurement segments with diverging deployment preferences.
Japan
Global manufacturers pursue unified visibility across distributed edge infrastructure through multi-module enterprise deployments. METI digital transformation incentives support legacy system modernization in regulated industries. Industrial concentrations in the Kanto and Kansai regions balance cloud migration with mainframe-integrated service management requirements.
Information Technology Service Management (ITSM) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment models and service types. The vendor base organizes into three tiers: platform-native cloud providers, legacy infrastructure integrators, and managed services specialists. Strategic differentiation hinges on FedRAMP authorization status, AI governance workflow capabilities, and mainframe integration depth. Competitive moves concentrate on M&A for compliance automation assets and strategic partnerships with hyperscaler marketplaces.
Within the platform-native tier, ServiceNow and Atlassian exemplify cloud-first architectures that anchor enterprise SaaS ecosystems. BMC Software and Micro Focus occupy positions bridging legacy mainframe environments with modern service orchestration. HCL Technologies represents the managed services archetype, extending operational responsibility through AI-augmented delivery models. These three strategic postures—platform dominance, legacy bridge-building, and operational outsourcing—define competitive positioning across procurement segments.
| Leading Market Players |
|---|
| BMC Software |
| Infosys |
| ServiceNow |
| ScienceSoft |
| HCL Technologies |
| Atlassian |
| Micro Focus |
| Sage IT |
| IBM |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure cost indices cascade through ITSM vendor pricing tiers, compressing margins for on-premises deployments while amplifying subscription premiums for FedRAMP-authorized platforms. Procurement officers in United States federal agencies and German automotive manufacturers face divergent cost pressures as hyperscaler compute pricing feeds into SaaS licensing structures.
Pricing Analysis
Expedited deployment timelines command premium SaaS licensing rates, while surplus capacity in managed services pools enables spot-market discounting for non-critical workloads. Consumption-based subscription tiers separate enterprise-grade AI governance modules from standard incident management feature sets. Pricing pressure stems from hyperscaler marketplace commoditization of core ticketing functions. Mid-market professional services firms exhibit highest price sensitivity; defense contractors pursuing FedRAMP authorization show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand, while managed services providers aggregate fragmented SME procurement through platform partnerships. Software development concentrates in India, Ireland, and Poland; hyperscaler infrastructure feeds from United States, Germany, and Singapore data center clusters. Supply chains draw from proprietary large language model APIs, container orchestration platforms, and legacy mainframe integration middleware. Single-source vulnerability in AI model provider concentration poses structural risk. Distribution runs through hyperscaler marketplaces, systems integrator consortia, and direct vendor field sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITSM procurement operates as a cost-of-compliance story where FedRAMP authorization creates a barrier-to-entry moat for vendors serving United States federal agencies. The SEC's cybersecurity disclosure rules and EU AI Act documentation mandates compound compliance investment requirements.
For Market Incumbents: Deepen mainframe integration capabilities to defend against cloud-native challengers targeting regulated industries with legacy infrastructure burdens. Fortify FedRAMP authorization pipelines to capture accelerated federal procurement timelines. Prioritize AI governance workflow modules as the priority capability investment to meet EU AI Act risk classification requirements.
For New Entrants and Emerging Players: Hyperscaler marketplace partnerships offer the fastest channel to bypass direct enterprise sales cycle friction. Target United Kingdom public sector bodies facing ITIL 4 certification shortages through managed services white-label arrangements. Lead with consumption-based pricing to displace perpetual license incumbents in mid-market professional services verticals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-automation specialists in European financial services hubs facing EU AI Act retrofitting costs. Long-term viability hinges on platform-native architectures capable of absorbing governance workflow expansion without fragmentation. Watch for inflection signals in federal procurement velocity for FedRAMP-authorized platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies ITSM modules with existing enterprise SaaS ecosystems, reducing procurement friction for CIOs. |
| Acquisition of Specialist Firm | Absorbs AI governance workflow capabilities to meet EU AI Act documentation mandates. |
| Strategic Partnership | Accelerates FedRAMP authorization through hyperscaler marketplace co-sell arrangements. |
| Product Launch | Introduces agentic AI architectures that compress traditional tiered support staffing models. |
| Geographic Expansion | Establishes captive development centers in India's Special Economic Zones to capture tax-advantaged talent pools. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CIOs, IT procurement officers, platform engineers, and systems integration specialists. SEC disclosure documents, FedRAMP authorization repositories, EU official journal procurement notices, and hyperscaler capex disclosures provided validation benchmarks. Bottom-up deployment model sizing triangulated against top-down vertical spending estimates.
Granularity-level modeling segmented the market by deployment architecture, organizational scale, industry vertical, integration complexity, and regional regulatory cluster. CAGRs derived from time-series analysis of procurement velocity indicators across the projection horizon. Forecast inputs incorporated ITIL 4 certification pipeline data, federal procurement acceleration timelines, and AI governance workflow adoption curves.
Caveats apply where FedRAMP authorization delays, GDPR Article 32 enforcement intensity, or hyperscaler pricing volatility could materially shift the outlook. Forecasts rest on assumptions regarding cloud migration velocity and regulatory disclosure rule implementation pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Freight Management Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Global Product Information Management (PIM) Software Market
Software & Services
Mining Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Embedded Operating Systems Market
Software & Services
Strategy Management Software Market
Software & Services
Mining Simulation Software Market
Software & Services
Anti-Plagiarism Software Market
Software & Services
Servicenow Tech Services Market
Software & Services
Fitness App Market
Software & Services
Search and Discovery Software Market
Software & Services
Content Creation Software Market
Software & Services
Global Investor Relationship Management Software Market