
 Global Kiosk Software Market | 2026-2036
Global Kiosk Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kiosk Software Market Foresight
PCI DSS Level 1 certification is collapsing the vendor pool to providers capable of sustaining annual third-party audits and quarterly network scans. KioWare sustains a channel-dense model across North American healthcare and municipal deployments. Oracle Corporation anchors enterprise-grade kiosk management through its embedded cloud infrastructure stack. Meridian Kiosks specializes in custom enclosure-software bundles for high-traffic transportation hubs.
Kiosk software encompasses the operating middleware, lockdown utilities, remote management agents, and payment security layers that transform generic computing hardware into dedicated self-service terminals; the stack typically integrates TPM 2.0 modules for hardware-rooted trust and runs hardened Linux or Windows IoT builds stripped of unnecessary attack surfaces. Cloud-based deployment leads solution-type distribution by offloading patch orchestration and telemetry analytics to vendor-controlled data centers. Self-service payment modules capture the densest margin pools within solution types, given their encryption overhead and recurring certification burdens. Wayfinding applications remain structurally constrained by indoor positioning accuracy limits and high custom content costs.
FDA guidelines on medical kiosk data handling, EU GDPR requirements for biometric capture at immigration terminals, and PCI SSC mandates for PIN transaction security collectively elevate compliance spending to a competitive barrier. ETSI standards in Europe further constrain wireless connectivity modules used in transportation kiosks. Stakeholders must weigh captive in-house certification teams against outsourced compliance subscriptions as regulatory fragmentation deepens across deployment geographies.
Market Dynamics
PCI DSS Level 1 certification requirements are compressing the vendor pool and elevating compliance spending into a competitive moat, forcing smaller providers toward outsourced audit subscriptions or exit.
Growth Catalysts
- GDPR biometric mandates:EU immigration terminals now require hardened data-capture stacks, pulling encryption-heavy software modules into airport and border deployments across Germany, France, and the Netherlands.
- India's banking correspondent networks:RBI-backed financial inclusion targets are driving rural kiosk density for Aadhaar-authenticated transactions and last-mile credit distribution.
- Windows IoT Enterprise lockdown utilities:Healthcare systems in the US and Japan are replacing legacy embedded OS builds with TPM 2.0-rooted trust architectures for patient check-in terminals.
Market Restraints
- Quarterly ASV scanning costs:PCI DSS network security mandates impose recurring audit burdens that disproportionately squeeze mid-tier software vendors without captive compliance teams.
- Indoor positioning accuracy limits:Wayfinding applications remain structurally constrained by BLE and UWB signal drift in complex built environments, capping deployment scale.
- Custom content production bottlenecks:High-traffic transportation hubs require localized multimedia assets that extend implementation timelines and inflate professional services attach rates.
Strategic Opportunities
- Saudi Arabia's Vision 2030 smart city builds:MOHAP and SFDA-aligned healthcare kiosks for pilgrim health screening represent underpenetrated demand with sovereign funding backing.
- ETSI EN 302 636 wireless modules:European transportation authorities are mandating harmonized V2X connectivity for roadside kiosks, opening embedded software integration contracts.
- Cloud-native patch orchestration:Vendor-controlled data centers are displacing on-premise management consoles, enabling recurring SaaS revenue models in North American quick-service restaurant chains.
Industry Challenges
- FDA 21 CFR Part 820 quality system integration:Medical kiosk developers face documentation burdens when bridging software release cycles with hardware validation protocols.
- Legacy Windows Embedded Handheld migration:End-of-life support deadlines are forcing forklift upgrades at petroleum retail and logistics terminals with constrained capex cycles.
- Biometric template interoperability:Fragmented ISO/IEC 19795-2 implementations across immigration authorities complicate multi-country kiosk deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kiosk Software Market |
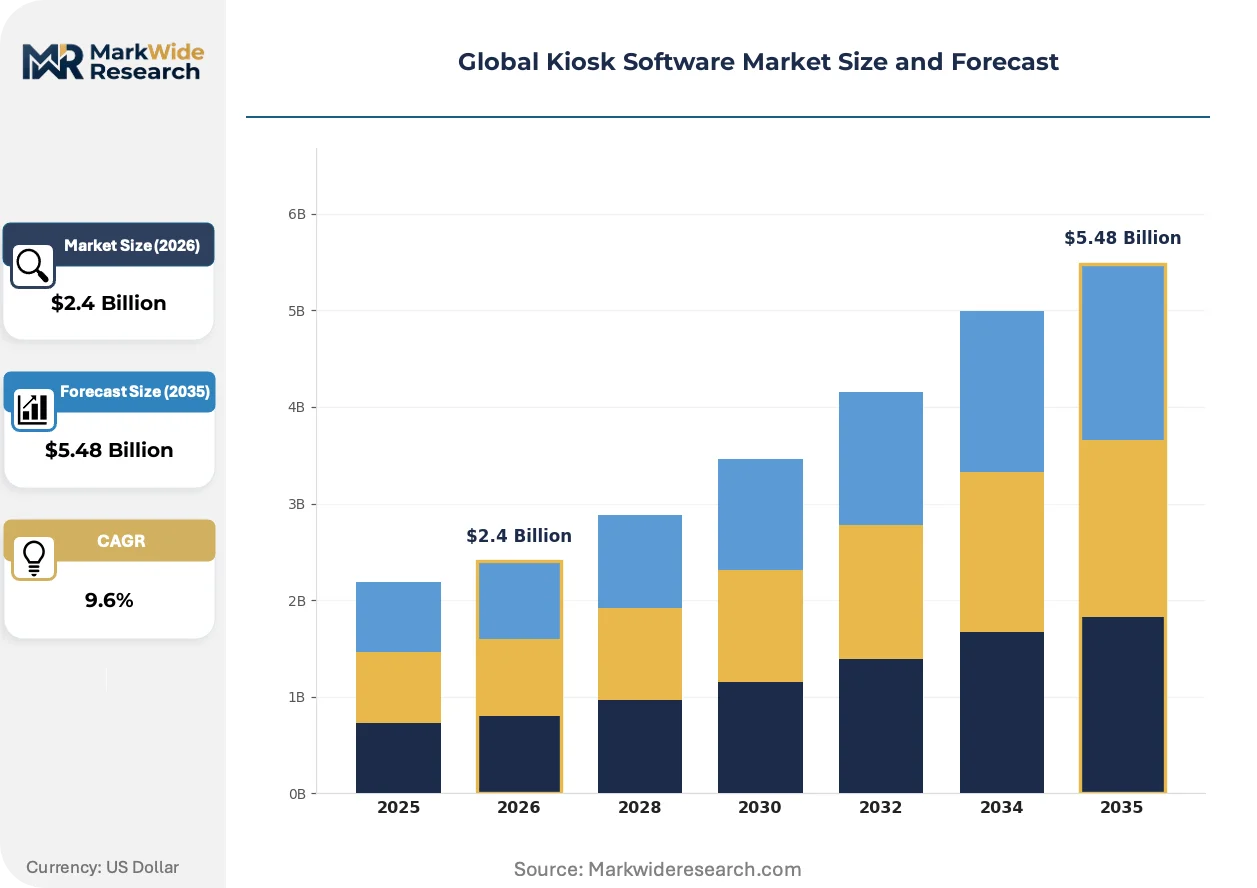
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Managed Services Solution Type: Self-service Payment, Information Dissemination, Ticketing & Reservations, Interactive Advertising, Wayfinding Use Case: Retail Checkout, Visitor Management, Event Registration, Food Ordering, Queue Management End User Industry: Banking & Finance, Hospitality, Transportation, Government Services, Education |
| Companies Covered | Provisio, KioWare, KIOSK Information Systems, Meridian Kiosks, ProMobi, Antamedia, Oracle Corporation, Toast, Advanced Kiosks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kiosk Software Market Shifts & Advancements
Edge-to-cloud telemetry architectures are redistributing where kiosk intelligence resides, while regulatory fragmentation across data sovereignty and payment security is forcing modular compliance design.
Containerized kiosk runtime environments are bifurcating the market between lightweight Linux microservices and full Windows IoT stacks. Quick-service restaurants in the US and Japan are adopting stripped-down containers for payment-only terminals, compressing hardware requirements and licensing costs. This technology shift is bifurcating vendor strategies into low-margin commodity runtime providers versus premium managed-security platforms.
EU AI Act risk-classification rules are imposing documentation and human-oversight requirements on immigration kiosks with biometric inference capabilities. Terminal manufacturers must now maintain technical files and conformity assessments for emotion-recognition and age-estimation algorithms. High-traffic Schengen airports in Germany and the Netherlands are responding by segregating AI-enabled lanes from legacy document-scanning-only corridors.
Buyers are unbundling after-sales service contracts from initial software licenses, compressing vendor recurring revenue and shifting technical support toward channel partners. North American healthcare systems now procure kiosk management through IT outsourcing firms rather than direct OEM relationships. This pattern is most visible in US hospital networks consolidating vendor relationships under single managed-service agreements.
Global Kiosk Software Market Segmentation
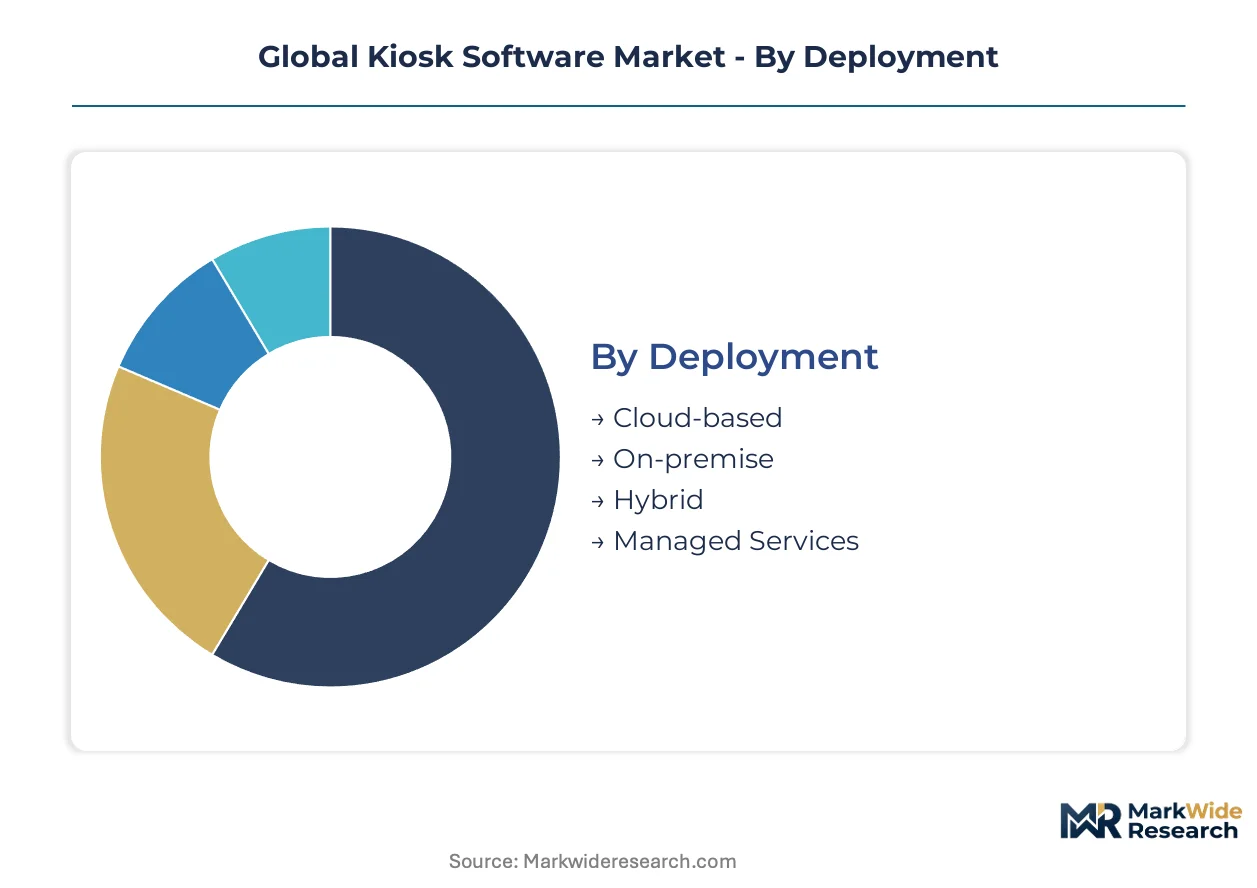
Kiosk software procurement patterns diverge sharply across deployment architectures and regulatory environments, with cloud-native stacks capturing North American quick-service restaurant chains while on-premise lockdown utilities dominate European PCI DSS Level 1 deployments. Solution type selection tracks end-use risk tolerance, as payment-integrated modules demand recurring certification investments that self-service information terminals avoid.
Deployment:
Cloud-based adoption concentrates in US and Japanese healthcare systems seeking centralized patch orchestration, while on-premise deployments anchor European retail banking where data sovereignty mandates predominate.
- Cloud-based:Vendor-controlled data centers offload telemetry analytics and security updates, with US quick-service restaurant chains and Japanese hospital networks driving density through SaaS subscription models. Indian banking correspondent networks increasingly favor this architecture for rural Aadhaar-authenticated terminals where local IT staffing is scarce.
- On-premise:Hardened Linux or Windows IoT builds run within facility-controlled perimeters, satisfying German and French PCI DSS requirements for PIN transaction isolation. Petroleum retail terminals across the US and legacy logistics hubs in Japan maintain this deployment to satisfy air-gapped security protocols.
- Hybrid:Edge-to-cloud architectures split transaction processing from analytics ingestion, finding traction in Saudi healthcare kiosks where MOHAP data residency rules meet pilgrim throughput demands.
- Managed Services:Outsourced compliance subscriptions and quarterly ASV scanning bundles attract mid-tier European vendors lacking captive certification teams.
Cloud-based deployments hold the largest share; momentum sits with hybrid architectures bridging sovereignty and scalability requirements.
Solution Type:
Margin pools correlate directly with encryption overhead and certification burden, creating tiered competitive dynamics across the stack.
- Self-service Payment:PCI DSS Level 1 certification requirements compress the vendor pool to providers sustaining annual third-party audits and quarterly network scans. US quick-service restaurants and European retail chains deploy these modules to compress labor costs while meeting PIN transaction security mandates.
- Information Dissemination:Lightweight content delivery without payment integration avoids recurring compliance spend, dominating municipal and educational deployments in India and Japan where budget constraints predominate.
- Ticketing & Reservations:Indian railway infrastructure and Saudi pilgrim management systems drive specialized queue-flow algorithms.
- Interactive Advertising:Retail media networks in US shopping centers monetize dwell time through targeted content delivery.
- Wayfinding:BLE and UWB signal drift in complex built environments constrains deployment scale across German airports and Dutch transportation hubs.
Self-service Payment commands the deepest margins; Information Dissemination is expanding most quickly in cost-constrained public sector deployments.
Use Case:
Application selection tracks labor substitution economics and throughput velocity, with food ordering and retail checkout leading capital allocation.
- Retail Checkout:Self-scanning modules with integrated payment security transform US and European grocery and convenience store footprints, compressing cashier headcount while accelerating transaction velocity.
- Food Ordering:Quick-service restaurant chains across the US and Japan deploy menu customization interfaces with kitchen display system integration, reducing order accuracy errors and labor interaction time.
- Visitor Management:Corporate campuses and healthcare facilities in Germany and the Netherlands integrate biometric capture with GDPR-compliant data handling protocols.
- Event Registration:Badge printing and session scheduling modules serve conference infrastructure in UAE and Saudi Arabia.
- Queue Management:Ticketing and line optimization systems anchor Indian railway stations and government service centers.
Retail Checkout dominates installed base; Food Ordering shows the steepest expansion trajectory as quick-service chains accelerate self-service penetration.
End User Industry:
Regulatory fragmentation across data sovereignty and payment security forces modular compliance design, with banking and transportation commanding premium security investments.
- Banking & Finance:RBI-backed rural correspondent networks in India and PCI DSS-gated European retail deployments demand hardened encryption stacks with TPM 2.0-rooted trust architectures. Aadhaar-authenticated transactions and last-mile credit distribution drive kiosk density.
- Transportation:ETSI EN 302 636 wireless mandates for V2X connectivity reshape European roadside kiosk specifications, while Indian railway ticketing and Schengen airport wayfinding create divergent technical requirements.
- Hospitality:Hotel check-in and concierge modules in US and Japanese properties integrate property management system APIs.
- Government Services:Municipal bill payment and document submission kiosks serve citizen access mandates across India and Saudi Arabia.
- Education:Campus wayfinding and library self-checkout systems deploy in US and Japanese universities with constrained capital cycles.
Banking & Finance retains the largest revenue concentration; Transportation is gaining share fastest through sovereign-funded smart city and railway modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI-backed financial inclusion mandates and PCI DSS certification requirements are redistributing procurement authority toward compliant vendors across divergent regulatory environments.
United States
Quick-service restaurant chains deploy self-service payment modules to compress labor costs and accelerate throughput. FDA guidelines on medical kiosk data handling elevate documentation burdens for patient check-in terminals. Healthcare systems in Greater Boston and the Pacific Northwest consolidate vendor relationships under single managed-service agreements.
Germany
Schengen airport immigration terminals require hardened data-capture stacks with GDPR-compliant biometric handling. ETSI EN 302 636 wireless mandates reshape roadside kiosk specifications for V2X connectivity. Frankfurt and Munich transportation hubs segregate AI-enabled lanes from legacy document-scanning corridors.
India
Rural banking correspondent networks drive kiosk density for Aadhaar-authenticated transactions and last-mile credit distribution. RBI financial inclusion targets concentrate procurement through nationalized banking infrastructure. Railway ticketing systems in Mumbai and Delhi anchor specialized queue-flow algorithm deployments.
Saudi Arabia
Vision 2030 smart city builds generate sovereign-funded demand for healthcare kiosks aligned with MOHAP and SFDA requirements. Pilgrim health screening terminals at entry points require edge-to-cloud architectures balancing data residency rules with throughput demands. Riyadh and Jeddah clusters absorb premium managed-security platform deployments.
Japan
Healthcare systems replace legacy embedded OS builds with TPM 2.0-rooted trust architectures for patient check-in terminals. METI industrial standards guide Windows IoT Enterprise adoption patterns. Tokyo and Osaka metropolitan hospital networks drive cloud-native patch orchestration subscriptions.
Global Kiosk Software Market Competitive Landscape
Listed leaders compete with private specialists across certification-capable tiers, compressing the vendor pool around PCI DSS Level 1 sustainment. Annual third-party audits and quarterly network scans now gate eligibility for European retail and North American healthcare deployments. Three archetypes dominate: cloud-native SaaS platforms, hardware-software bundle providers, and compliance-focused managed security vendors. Strategic moves concentrate on M&A for certification assets and channel partnerships for geographic density.
Within the enterprise software tier, Oracle Corporation anchors positions through embedded cloud infrastructure stacks. KioWare occupies a channel-dense model across North American healthcare and municipal deployments. Meridian Kiosks exemplifies the custom enclosure-software bundle archetype for high-traffic transportation hubs. These three represent divergent bets on where margin pools concentrate—recurring SaaS subscriptions, compliance-heavy payment modules, or specialized professional services attach rates.
| Leading Market Players |
|---|
| Provisio |
| KioWare |
| KIOSK Information Systems |
| Meridian Kiosks |
| ProMobi |
| Antamedia |
| Oracle Corporation |
| Toast |
| Advanced Kiosks |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS platforms achieve 40-60% gross margins through centralized patch orchestration, compressing price floors for on-premise competitors burdened by captive compliance teams. This scale asymmetry concentrates procurement power among three vendor archetypes while forcing mid-tier providers toward outsourced audit subscriptions or exit.
Pricing Analysis
Certification level (PCI DSS Level 1 versus self-attested) creates the primary spread between premium managed-security platforms and commodity runtime providers. Three-tier pricing structure across premium, standard, and economy levels anchors SaaS subscriptions to encryption overhead, with US quick-service restaurant chains and European retail banking driving divergent willingness-to-pay. Cost compression in mid-tier segments is intensifying because quarterly ASV scanning burdens disproportionately squeeze vendors without captive compliance teams. Municipal and educational deployments in India exhibit highest price sensitivity, while Saudi sovereign-funded healthcare kiosks absorb premium attach rates.
Supply Chain Analysis
Container availability fluctuations across Shenzhen-Shanghai trade lanes feed component lead time volatility for TPM 2.0 modules and hardened Linux builds. Taiwan, South Korea, and China concentrate semiconductor fabrication for embedded trust architectures, while India and Vietnam assemble enclosure-software bundles for transportation hubs. The supply chain rests on specialized encryption chipsets and Windows IoT Enterprise licensing pools, with single-source vulnerability concentrated in TPM module vendors. Distribution runs through channel-dense IT outsourcing firms in North American healthcare and direct OEM relationships in European PCI DSS deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat; PCI DSS certification cycles create switching costs that cement incumbent positions across European retail and North American healthcare procurement.
For Market Incumbents: Consolidate certification assets through targeted acquisition of regional compliance specialists, particularly in EU GDPR and Saudi SFDA-aligned domains. Deepen vertical integration into TPM 2.0 module sourcing to buffer Taiwan semiconductor concentration risk. Channel control represents the critical lever—North American healthcare systems increasingly procure through IT outsourcing consolidators, threatening direct OEM margins. For New Entrants and Emerging Players: Managed compliance subscriptions for mid-tier European vendors lacking captive certification teams constitute the most penetrable white-space. Saudi Vision 2030 healthcare kiosks and Indian rural banking correspondent networks offer sovereign-funded demand with lower incumbent saturation. A channel-first go-to-market through regional system integrators bypasses direct certification burden while capturing recurring revenue share. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native SaaS platforms with embedded payment security over hardware-software bundle providers facing margin compression. Long-term viability hinges on recurring revenue density and regulatory entrenchment across multiple geographies. Watch PCI DSS Level 1 vendor pool concentration as inflection signal—further compression triggers acquisition premiums for compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| PCI DSS Level 1 Certification Acquisition | Compresses vendor eligibility for European retail and US healthcare deployments. |
| Cloud-Native Patch Orchestration Platform | Enables SaaS revenue models in North American quick-service restaurant chains. |
| TPM 2.0 Module Backward Integration | Reduces Taiwan semiconductor concentration risk for trust architecture vendors. |
| Saudi Healthcare Kiosk Channel Partnership | Captures Vision 2030 sovereign funding through MOHAP-aligned system integrators. |
| Indian Banking Correspondent Network Expansion | Scales Aadhaar-authenticated terminal density through RBI-backed rural infrastructure. |
Research Methodology
The analysis maps cloud-native SaaS platforms, on-premise lockdown utilities, hybrid edge-to-cloud architectures, and managed compliance services, each validated through CTOs at quick-service restaurant chains, IT procurement officers in hospital networks, platform engineers at kiosk OEMs, and channel partners distributing enclosure-software bundles. Primary interviews combined with secondary validation against SEC filings, PCI SSC certification registries, RBI financial inclusion reports, and ETSI standardization documents. Bottom-up deployment counts triangulated against top-down vendor revenue estimates across segmentation dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment architecture, solution type, use case, and end-user industry as core segmentation dimensions, with regional regulatory cluster as an overlay. CAGRs derived from logistic adoption curves fitted to historical deployment trajectories, incorporating Windows IoT Enterprise migration timelines and GDPR biometric mandate implementation pace as industry-specific inputs.
Underlying assumptions cover sustained PCI DSS certification stringency, sovereign funding continuity for Saudi and Indian deployments, and TPM 2.0 module supply stability, with deviation risk concentrated in regulatory fragmentation acceleration or semiconductor trade restriction escalation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global MSP Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Load Balancing Software Market
Software & Services
Business Analytics Software Market
Software & Services
Attendance Management Software Market
Software & Services
Data Migration Software Services Market
Software & Services
User Retention Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Account-Based Data Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Document Capture Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Server Software Market
Software & Services
Middleware Market
Software & Services
Recruitment Software Market
Software & Services
Electronic Batch Records Market