
 Collaborative Authoring Tools Market | 2026-2036
Collaborative Authoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Collaborative Authoring Tools Market Outlook
Enterprise procurement teams are collapsing the distinction between synchronous editing suites and legacy document management systems, forcing vendors to recalibrate platform architectures. Atlassian leverages deep Jira-Confluence integration to anchor technical documentation workflows for software engineering organizations. Microsoft competes through native Office 365 meshing with Teams collaboration layers, while Notion differentiates via modular workspace blocks that absorb wikis, databases, and project trackers into unified surfaces.
Collaborative authoring tools constitute software platforms enabling multiple users to create, edit, review, and publish content through shared interfaces with real-time or asynchronous synchronization, typically operating on CRDT or OT protocols to resolve concurrent edits without version conflicts. These systems serve industrial and commercial purposes by eliminating serialization bottlenecks in document production pipelines, from regulatory filings to marketing asset development. Cloud-based tools occupy the dominant deployment mode as enterprises abandon on-premises maintenance burdens, though hybrid configurations retain traction in financial services and defense-adjacent sectors where data residency requirements fragment infrastructure decisions. API integration capabilities increasingly determine platform stickiness, with enterprises prioritizing tools that embed natively into existing CRM, ERP, and design software ecosystems rather than standalone offerings demanding context-switching.
FDA 21 CFR Part 11 compliance requirements shape demand in life sciences verticals where electronic signatures and audit trails are non-negotiable for regulatory submissions, while EU GDPR provisions constrain cross-border data flows and compel regional cloud hosting or private cloud deployments. HIPAA obligations extend similar constraints to US healthcare collaborative environments, with business associate agreements becoming standard procurement checklist items. ISO 27001 certification now functions as a baseline market-access credential rather than a differentiator, and stakeholders must monitor whether emerging EU AI Act provisions will classify certain automated content-generation features within collaborative platforms as high-risk applications subject to conformity assessments.
Market Dynamics
CRDT and OT protocol maturation is collapsing the latency gap between synchronous and asynchronous collaboration modes, forcing vendors to rebuild core synchronization engines or risk displacement by purpose-built alternatives.
Growth Catalysts
- EU AI Act Conformity Pathways:Automated content-generation modules within collaborative platforms face high-risk classification, triggering demand for audit-ready documentation workflows across European enterprise legal departments.
- HIPAA Business Associate Agreements:US healthcare systems now mandate collaborative tool vendors sign standardized data protection contracts, accelerating procurement of certified platforms over uncredentialed alternatives.
- Mittelstand Engineering Digitization:German mid-market automotive suppliers are replacing document control silos with unified technical documentation pipelines, concentrating demand in Baden-Württemberg and Bavaria manufacturing clusters.
Market Restraints
- Cross-Border Data Fragmentation:GDPR data localization requirements and China's data sovereignty rules force vendors to maintain redundant regional infrastructure, elevating operational complexity.
- ISO 27001 Certification Baseline:Information security credentials have shifted from competitive differentiator to table stakes, compressing vendor margins on compliance investments.
- On-Premises Legacy Lock-In:Financial services and defense-adjacent sectors retain hybrid configurations due to data residency mandates, fragmenting addressable cloud market share.
Strategic Opportunities
- API-Native Embedding:Deep integration with existing CRM, ERP, and design software ecosystems creates stickier revenue models than standalone offerings demanding context-switching.
- FDA 21 CFR Part 11 Vertical Expansion:Life sciences electronic signature and audit trail requirements remain underserved by generalist platforms, opening specialized compliance-first positioning.
- Japan METI Digital Transformation Incentives:Government subsidies for SME software adoption are accelerating collaborative tool procurement among Osaka and Nagoya manufacturing networks.
Industry Challenges
- CRDT/OT Engineering Talent Scarcity:Concurrent editing protocol expertise concentrates among distributed systems specialists, constraining vendor R&D velocity and inflating compensation costs.
- Legacy Document Management Migration Friction:Enterprises face multi-year reconfiguration timelines when collapsing synchronous editing suites into existing SharePoint or OpenText deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaborative Authoring Tools Market |
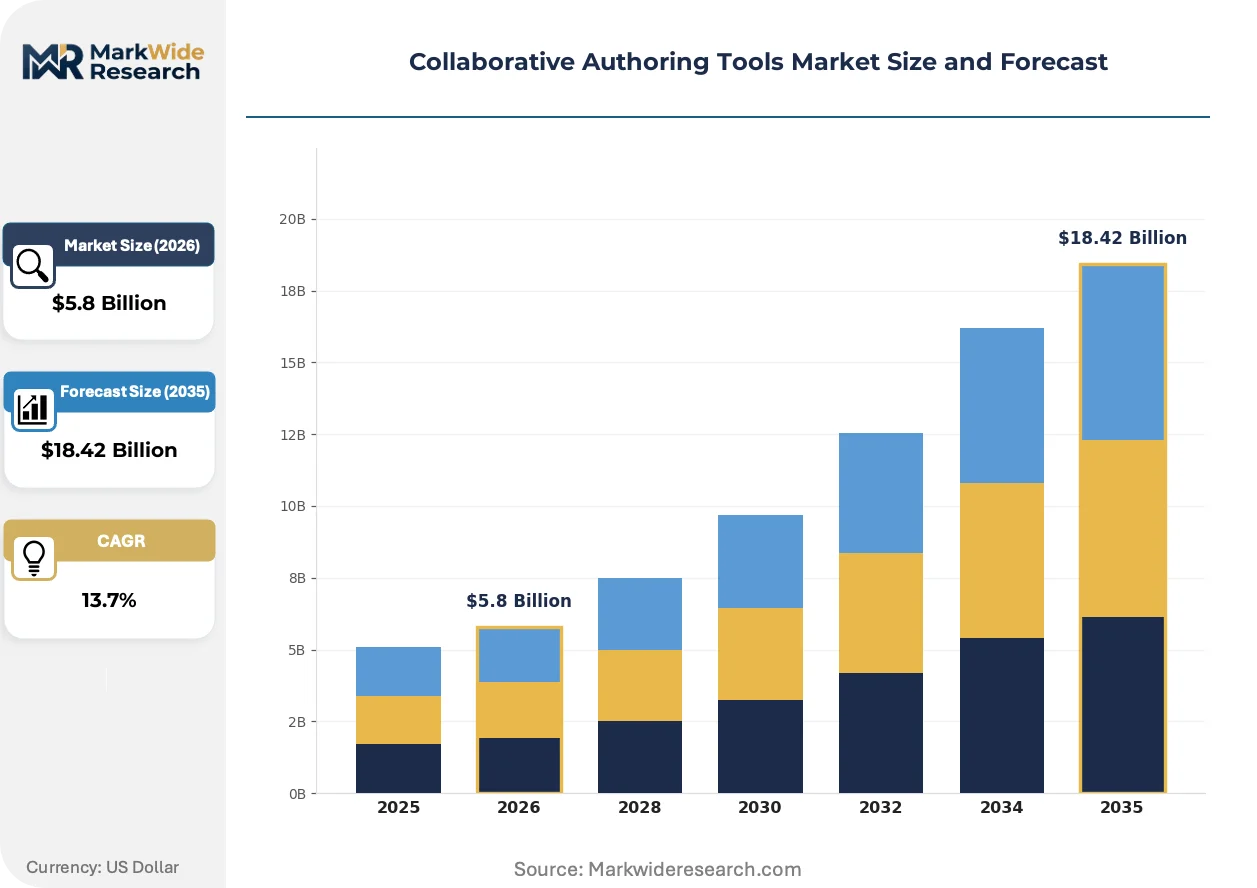
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Tools, Desktop Applications, Mobile Apps, Browser Extensions End User: Enterprises, Educational Institutions, Freelancers, Nonprofits Deployment: On-Premises, Hybrid, Fully Cloud, Private Cloud Integration Level: API Integration, Third-Party Integrations, Native Integrations, Standalone |
| Companies Covered | Atlassian, Asana, Microsoft, BridgeApp, Wrike, Google, Miro, Bynder, Notion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaborative Authoring Tools Market Strategic Shifts
Real-time synchronization protocols are commoditizing, pushing competitive differentiation toward vertical compliance modules and embedded workflow automation rather than core editing performance.
Conflict-free Replicated Data Types (CRDTs) are displacing Operational Transformation (OT) as the dominant synchronization architecture for mobile-first and offline-capable collaborative authoring. Engineering teams at software organizations now prioritize CRDT implementations for their partition tolerance and simpler server infrastructure. This shift is compressing the addressable market for OT-specialized vendors while rewarding platforms with native edge-computing capabilities.
EU AI Act high-risk application classifications are reshaping procurement criteria for automated content-generation features within collaborative platforms. Conformity assessment obligations now extend to AI-assisted drafting, summarization, and translation modules, compelling vendors to redesign product roadmaps. German enterprise legal departments and French pharmaceutical regulators are demanding documentation trails that satisfy both GDPR and emerging AI transparency mandates.
Subscription unbundling is fragmenting buyer-commitment patterns across mid-market segments. Procurement teams now evaluate modular workspace components separately rather than accepting monolithic platform contracts, pressuring vendors to expose granular pricing for wiki, database, and project-tracking functions. This behavior is most visible among Series B and C software startups in Berlin, Amsterdam, and Stockholm where finance teams scrutinize per-seat economics.
Collaborative Authoring Tools Market Segmentation
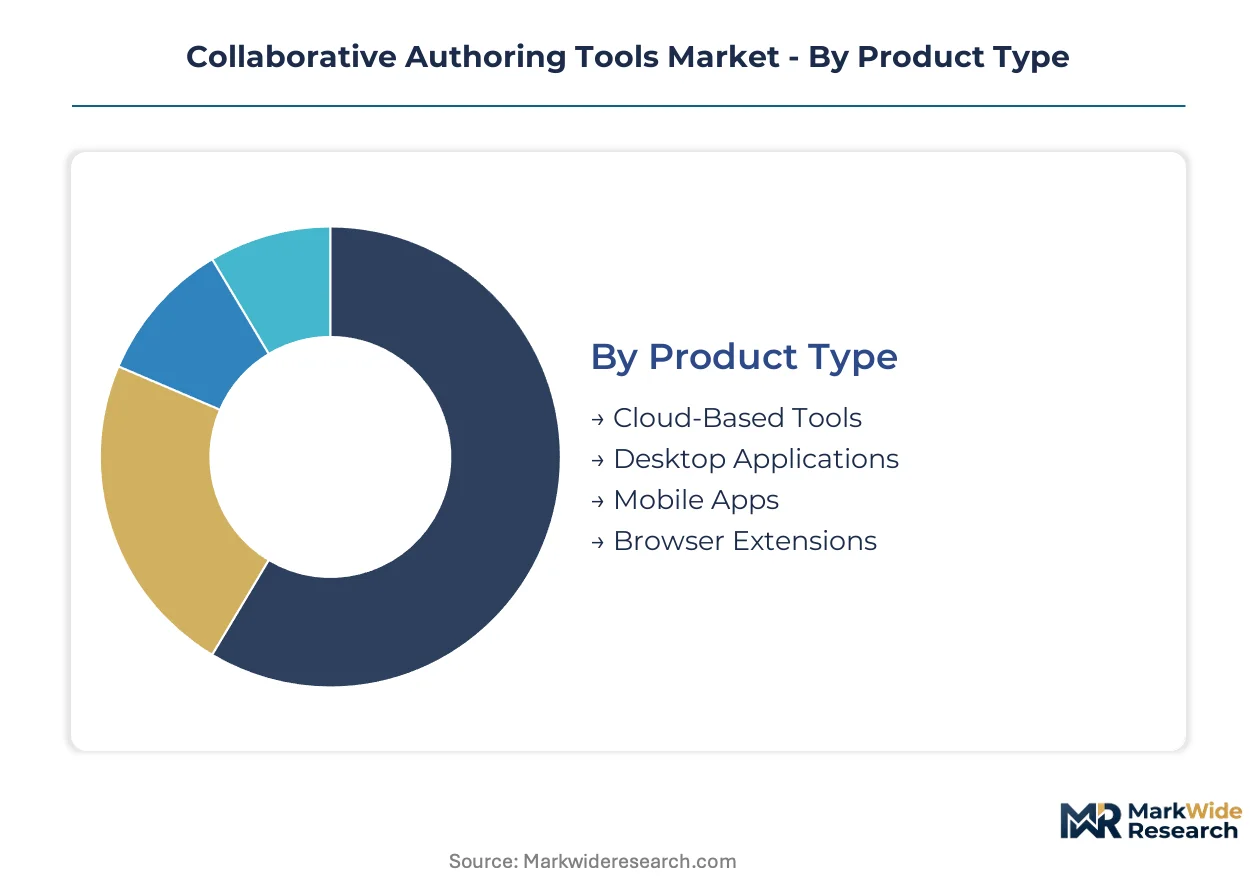
Segmentation in collaborative authoring tools reveals how procurement priorities diverge across infrastructure constraints, compliance mandates, and workflow integration depth. Buyers select deployment modes and integration architectures based on data residency requirements rather than feature parity alone.
Product Type:
Margin pools concentrate in cloud-based delivery where recurring subscription revenue outpaces perpetual licensing models.
- Cloud-Based Tools:These platforms operate on multi-tenant SaaS architectures with CRDT or OT synchronization engines handling concurrent edits across distributed teams. Demand concentrates among German Mittelstand engineering firms in Baden-Württemberg digitizing technical documentation pipelines under EU data governance pressure.
- Desktop Applications:Native-installed software retains offline editing capabilities with periodic cloud synchronization for version control. Procurement persists in financial services sectors where FERC and SEC data residency mandates fragment infrastructure decisions toward hybrid configurations.
- Mobile Apps:Touch-optimized interfaces with compressed synchronization protocols for field-based content creation.
- Browser Extensions:Lightweight add-ons embedding collaborative features directly into existing web applications without standalone platform adoption.
The dominant share belongs to Cloud-Based Tools, while Mobile Apps is closing the gap fastest.
End User:
Application patterns vary sharply between procurement sophistication and compliance burden tolerance.
- Enterprises:Large organizations mandate ISO 27001 certification, HIPAA business associate agreements, and FDA 21 CFR Part 11 audit trails for regulated content workflows. Japanese manufacturing networks in Osaka and Nagoya accelerate procurement through METI digital transformation subsidies.
- Educational Institutions:Universities and K-12 systems prioritize cost scalability and Learning Management System interoperability over advanced compliance modules.
- Freelancers:Individual contractors select modular pricing with per-seat economics scrutinized by finance teams at Berlin and Amsterdam software startups.
- Nonprofits:Grant-funded organizations favor discounted or donated licenses with basic synchronization and limited API access.
Enterprises command the largest procurement volume, though Educational Institutions are expanding most quickly as distributed learning normalizes.
Deployment:
Customer type dictates infrastructure fragmentation across residency requirements.
- On-Premises:Self-hosted installations on customer-controlled servers with complete data sovereignty. Defense-adjacent sectors and US healthcare systems under HIPAA obligations retain this mode despite maintenance burden.
- Hybrid:Split architectures with sensitive content on-premises and collaborative layers in regional cloud instances. China's data sovereignty rules and GDPR localization requirements force redundant infrastructure strategies.
- Fully Cloud:Complete SaaS delivery with vendor-managed infrastructure and automatic updates.
- Private Cloud:Single-tenant cloud deployments with dedicated resources and geographic instance selection.
Fully Cloud holds the dominant position, yet Hybrid is gaining share fastest as cross-border data fragmentation intensifies.
Integration Level:
Stickiness correlates directly with embedding depth into existing software ecosystems.
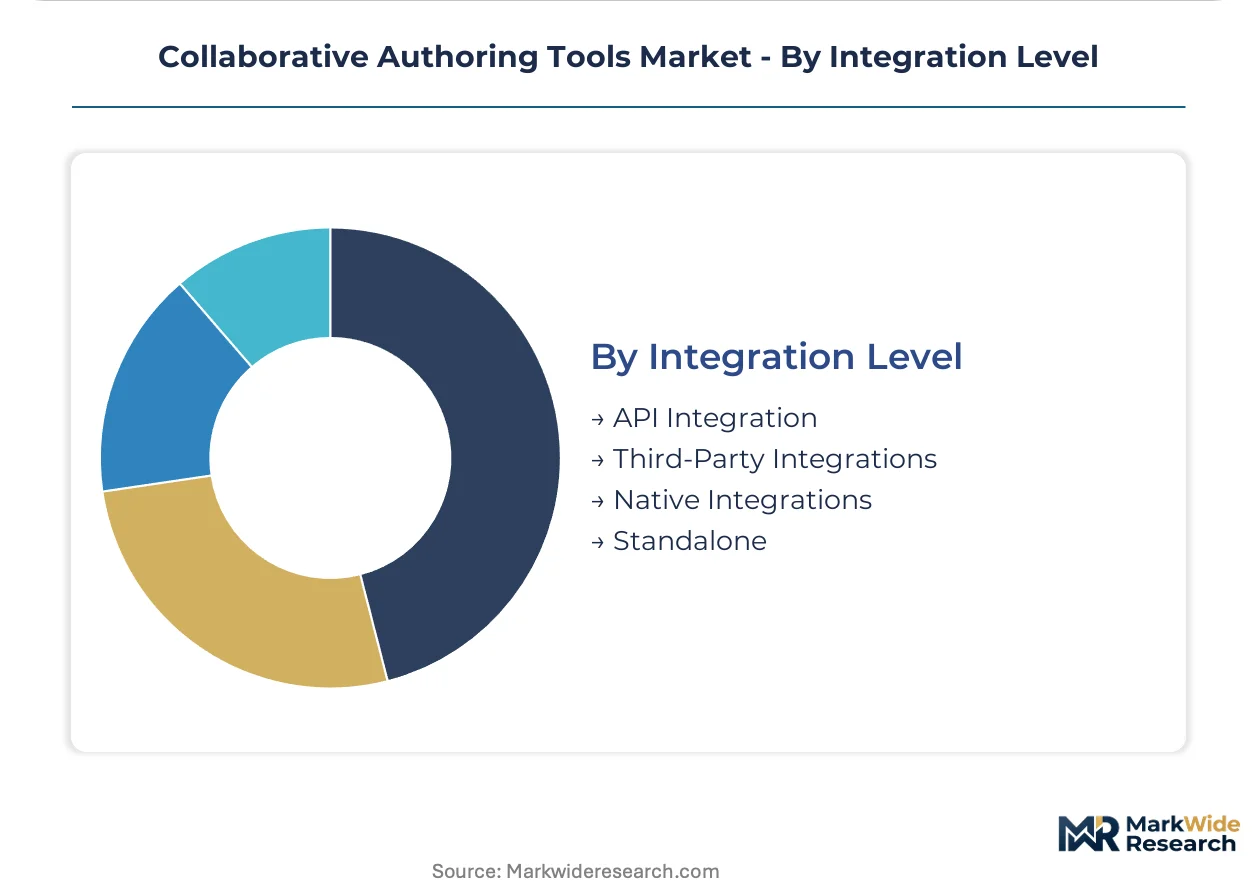
- API Integration:Programmatic interfaces enabling custom workflow automation and data exchange with CRM, ERP, and design software. Enterprise legal departments demand these capabilities for contract lifecycle management without context-switching penalties.
- Native Integrations:Pre-built connectors to specific platforms like Jira-Confluence meshes or Office 365-Teams layers. Software engineering organizations prioritize these for technical documentation pipelines.
- Third-Party Integrations:Middleware-dependent connections through integration-platform-as-a-service intermediaries.
- Standalone:Self-contained platforms requiring manual export-import for external system compatibility.
API Integration captures the dominant share, while Native Integrations are climbing the fastest as vendor ecosystem wars intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure clusters in the United States, Germany, and Japan where enterprise software ecosystems and regulatory complexity create concentrated demand for compliant collaboration platforms. Cloud hosting redundancy requirements now force multi-region deployment strategies across these jurisdictions.
United States
FDA 21 CFR Part 11 mandates shape procurement in life sciences verticals where electronic signatures and audit trails dominate vendor selection criteria. HIPAA business associate agreements function as non-negotiable procurement gatekeepers for healthcare systems nationwide. Boston and San Francisco Bay Area biotech clusters drive specialized compliance-first platform adoption.
Germany
Mittelstand engineering firms in Baden-Württemberg and Bavaria digitize technical documentation pipelines under pressure from automotive supplier consolidation. EU AI Act conformity pathways compel vendors to redesign automated content-generation modules for high-risk classification readiness. Stuttgart and Munich manufacturing networks concentrate demand for unified document control systems.
Japan
METI digital transformation subsidies accelerate SME software procurement across Osaka and Nagoya manufacturing networks. JIS standards alignment and data localization preferences favor domestic-hosted or regional cloud deployments over global SaaS offerings. Kanto and Kansai industrial corridors represent the fastest-expanding addressable segments in Asia-Pacific.
United Kingdom
Financial services regulatory frameworks from the FCA and PRA fragment infrastructure decisions toward hybrid cloud configurations. London's legal technology sector demands API-native embedding for contract lifecycle management without context-switching penalties. The Southeast England professional services cluster prioritizes GDPR-compliant cross-border data handling capabilities.
India
Bangalore and Hyderabad software services exporters drive enterprise adoption of collaborative platforms with native Jira-Confluence and Office 365 integration requirements. The country's data protection bill proposals push vendors toward local cloud hosting partnerships or private cloud alternatives. IT/ITES sector procurement concentrates in Karnataka and Telangana where distributed engineering teams require real-time synchronization protocols.
Collaborative Authoring Tools Market Competitive Environment
Concentration sits with platform conglomerates that bundle collaboration layers into broader productivity ecosystems. The vendor landscape stratifies across three tiers: enterprise suite incumbents with native integration advantages, vertical specialists targeting regulated industries, and modular workspace disruptors unbundling traditional document management. Dominant competitive moves include API-native embedding strategies that deepen ecosystem lock-in and vertical compliance module development for life sciences and legal sectors.
Within the enterprise suite tier, Microsoft and Google anchor positions through native meshing with cloud productivity stacks, while Atlassian exemplifies the vertical specialist archetype for software engineering documentation workflows. Notion occupies a position among modular workspace disruptors that absorb wikis, databases, and project trackers into unified surfaces. These three represent divergent strategic bets on whether collaboration tools function as standalone platforms or embedded infrastructure layers.
| Leading Market Players |
|---|
| Atlassian |
| Asana |
| Microsoft |
| BridgeApp |
| Wrike |
| Miro |
| Bynder |
| Notion |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification gates both vendor qualification and tiered pricing structures in enterprise procurement cycles, compressing margins for uncredentialed entrants while enabling premium positioning for audit-ready platforms serving FDA-regulated life sciences verticals.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across collaborative authoring platforms, with electronic signature and audit trail modules commanding substantial premiums over baseline synchronization offerings. Three-tier pricing structure across premium compliance, standard enterprise, and economy team levels separates vendors by certification depth and vertical specialization. Cost compression in the economy tier is intensifying because modular workspace disruptors unbundle functionality for price-sensitive Series B software startups. Freelancers and grant-funded nonprofits exhibit highest price sensitivity, while pharmaceutical regulatory affairs departments demonstrate lowest sensitivity due to non-negotiable compliance requirements.
Supply Chain Analysis
Just-in-time infrastructure deployment dominates vendor strategies, with hyperscaler partnerships enabling rapid regional scaling without captive data center investments. Cloud infrastructure concentrates in the United States, Germany, and Japan where data residency requirements and METI subsidy programs anchor regional hosting commitments. Platform engineering draws from distributed systems specialists, CRDT protocol researchers, and compliance documentation architects. Single-source vulnerability in synchronization protocol talent pools elevates compensation costs and constrains R&D velocity. Distribution runs through direct enterprise sales teams supplemented by channel partners serving mid-market manufacturing clusters in Baden-Württemberg and Osaka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collaborative authoring tools occupy an early-cycle expansion phase as CRDT protocol maturation collapses latency barriers and EU AI Act conformity pathways force procurement redesigns across European enterprise legal departments.
For Market Incumbents: Shield installed base relationships through deepening API-native embedding into existing CRM and ERP ecosystems, neutralizing modular workspace disruptors that demand context-switching penalties. Accelerate vertical compliance module development for FDA 21 CFR Part 11 and EU AI Act high-risk classification readiness, defending against specialized entrants targeting life sciences procurement cycles.
For New Entrants and Emerging Players: Differentiate on automated content-generation audit trails that satisfy both GDPR transparency mandates and emerging AI conformity assessments, capturing German Mittelstand engineering firms in Stuttgart and Munich manufacturing networks. Target underpenetrated Japanese SME segments through METI digital transformation subsidy alignment, leveraging Osaka and Nagoya industrial corridors as beachhead markets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform architectures as multi-tenant infrastructure achieves scale efficiencies, improving cash conversion timelines for SaaS revenue models. Acquisition candidates with native CRDT implementations and vertical compliance certifications in life sciences or legal sectors offer strongest long-term viability through the projection horizon. Monitor EU AI Act implementing acts as inflection signals for compliance-first platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Jira-Confluence or Office 365-Teams meshing anchors technical documentation workflows for software engineering organizations. |
| Vertical Compliance Module Development | FDA 21 CFR Part 11 and EU AI Act conformity pathways open specialized positioning in life sciences and legal procurement cycles. |
| Geographic Expansion | German Mittelstand digitization and Japanese METI subsidies concentrate demand in Stuttgart, Munich, Osaka, and Nagoya clusters. |
| Acquisition of Specialist Firm | CRDT protocol engineering talent scarcity makes distributed systems boutiques attractive targets for R&D velocity acceleration. |
| Strategic Partnership | Hyperscaler cloud hosting alliances enable rapid regional infrastructure scaling without captive data center capital deployment. |
Study Parameters
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory implementing acts preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across software engineering organizations and enterprise legal departments. Primary fieldwork combined with secondary validation from FDA guidance documents, EMA submissions, and METI subsidy program records. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from vendor revenue disclosures and channel partner interviews.
Variance decomposition across deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern shaped the analytical framework throughout the forecast period. CAGRs were synthesized from segment-level growth trajectories weighted by procurement volume concentration in German automotive supplier networks and Japanese manufacturing corridors. Modeled inputs incorporated CRDT protocol adoption curves, EU AI Act implementation timelines, and HIPAA business associate agreement penetration rates in US healthcare systems.
Material uncertainties — regulatory implementation delays, data sovereignty rule expansions, and synchronization protocol talent pool constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding compliance deadline adherence and cloud migration pace in financial services hybrid configurations. Revision becomes warranted when EU AI Act high-risk classification scope crosses thresholds beyond automated drafting and summarization modules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Photo Editing Software Market
Software & Services
Observability Platform Market
Software & Services
Staffing Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Ad Creation Software Market
Software & Services
Background Removal Software Market
Software & Services
Web Development Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Global Internal Communications Software Market
Software & Services
Global Accreditation Management Software Market