
 Family Law Software Market | 2026-2036
Family Law Software Market Size, Share, and Industry Trends Forecast 2026-2036
Family Law Software Market Insights
Subscription-based SaaS financing is reconfiguring competitive dynamics in family law technology by eliminating large upfront capital requirements for smaller practices. PracticePanther Legal Software leverages its cloud-native architecture to compete aggressively on monthly pricing tiers. Clio anchors its position through deep integration with court e-filing systems across multiple states. Filevine differentiates via workflow automation tailored to high-volume family law caseloads.
Family law software comprises specialized practice-management platforms engineered for divorce, custody, and support proceedings, typically incorporating calendaring tools compliant with court-specific deadlines and automated document generation aligned with jurisdictional form libraries. These systems serve the commercial purpose of reducing administrative overhead while ensuring procedural compliance in emotionally charged, high-stakes legal matters. Case management dominates current deployments as firms prioritize matter organization over ancillary functions, though client portal adoption accelerates fastest as courts mandate digital self-service options for document exchange. Cloud-based deployment leads new installations while on-premise solutions retain share among security-conscious practices handling sensitive custody disputes.
FCC guidelines on electronic communications privacy intersect with state bar ethics rules governing client confidentiality in cloud-stored family law records. The American Bar Association's technology competence requirements and state-level e-filing mandates collectively shape product development priorities and vendor market access. Stakeholders must monitor evolving court technology standards and bar association guidance on artificial intelligence disclosure in automated document preparation.
Market Dynamics
State-level e-filing mandates are fragmenting vendor requirements across the United States, forcing software providers to build jurisdiction-specific compliance layers rather than standardized national platforms. This regulatory patchwork is concentrating competitive advantage among vendors with dedicated court integration teams.
Growth Catalysts
- Remote Hearing Infrastructure:Permanent adoption of virtual court proceedings post-pandemic is expanding addressable market for calendaring and video-integrated case management tools.
- Solo Practitioner Cloud Migration:Subscription SaaS models are eliminating capital barriers for individual attorneys, accelerating technology refresh cycles among previously underserved micro-practices.
- Client Portal Mandates:State court systems in California, Texas, and Florida now require digital self-service document exchange, creating compulsory upgrade demand.
Market Restraints
- Jurisdictional Form Library Fragmentation:Each state maintains distinct procedural forms, forcing vendors to sustain 50+ parallel content development tracks without economies of scale.
- Data Residency Requirements:State bar ethics opinions in New York and Illinois impose geographic restrictions on cloud server locations, complicating vendor infrastructure architecture.
- Substitution by General Practice Platforms:Horizontal legal software with configurable workflows is capturing price-sensitive segments that accept reduced specialization.
Strategic Opportunities
- AI-Assisted Document Preparation:Natural language generation converging with jurisdictional rule engines offers premium pricing for automated parenting plan and support calculation drafts.
- Mediation-Adjacent Modules:Court-connected alternative dispute resolution programs in Colorado and Oregon create demand for settlement-focused workflow tools distinct from litigation platforms.
- Mobile-First Client Engagement:SMS-integrated status updates and document capture address accessibility gaps for pro se litigants and unrepresented parties in custody proceedings.
Industry Challenges
- Cross-State Bar Admission Complexity:Attorneys practicing family law across multiple jurisdictions require software that reconciles conflicting calendaring rules and ethical obligations without manual configuration.
- Legacy On-Premise Migration Friction:Security-conscious practices handling sensitive custody disputes resist cloud transitions despite feature deficits, requiring parallel support for deprecated architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Law Software Market |
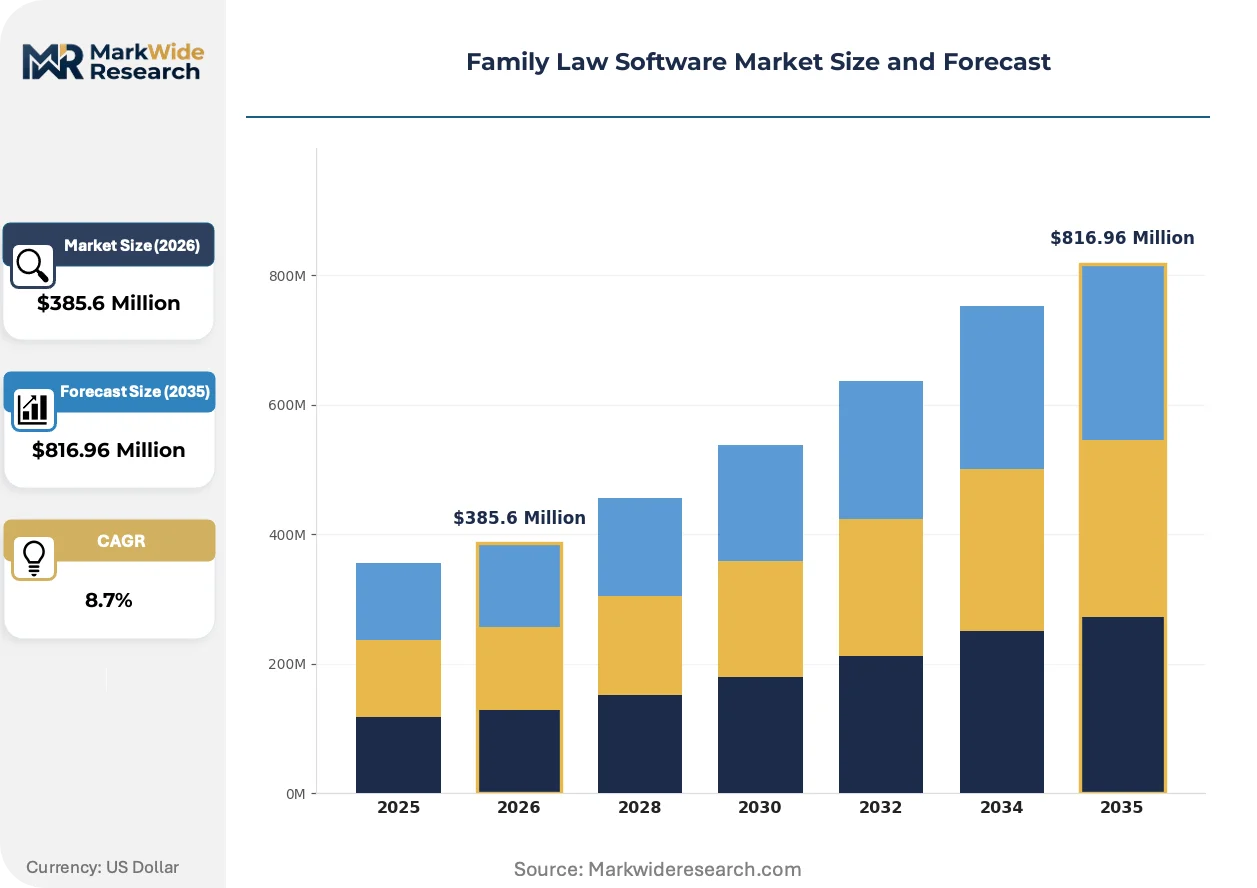
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Case Management, Document Automation, Client Portal, Billing Software Deployment: On-Premise, Cloud-Based, Hybrid Solutions, SaaS End User: Law Firms, Solo Practitioners, Legal Departments, Non-Profit Organizations Integration Level: Third-Party Integrations, Custom Integrations, API Access, Standalone Solutions |
| Companies Covered | Filevine, PracticePanther Legal Software, MyCase, Custody X Change, Family Law Software, Clio, SmartAdvocate, OurFamilyWizard, Smokeball, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Law Software Market Trends and Innovations
Automation is compressing the administrative burden that previously justified associate-level staffing in family law practices, reallocating firm economics toward client-facing advisory functions. Three distinct developments are accelerating this structural shift.
Natural language processing is collapsing the document assembly bottleneck that historically consumed paralegal hours in form-driven divorce and custody proceedings. Mid-sized firms with 5-15 attorneys are deploying these tools fastest, recognizing that automated first drafts free senior attorneys for negotiation strategy. The technology is collapsing the traditional leverage model where document volume justified hourly billing rates.
The American Bar Association's formal technology competence requirements are reshaping vendor sales cycles and product roadmaps. State disciplinary committees now sanction attorneys who fail to adopt reasonable technological efficiencies, converting ethical guidance into procurement pressure. Solo practitioners in Arizona and Washington face the steepest compliance exposure, driving rapid adoption of court-integrated platforms.
Fixed-fee service packaging is displacing hourly billing as the dominant client engagement model in uncontested divorce and modification proceedings. Firms in Texas and Georgia are restructuring workflows around predictable deliverables rather than time-based output, demanding software that tracks matter profitability against flat-rate quotes. This behavioral shift rewards platforms with built-in scope management and automated cost projection tools.
Family Law Software Market Segmentation
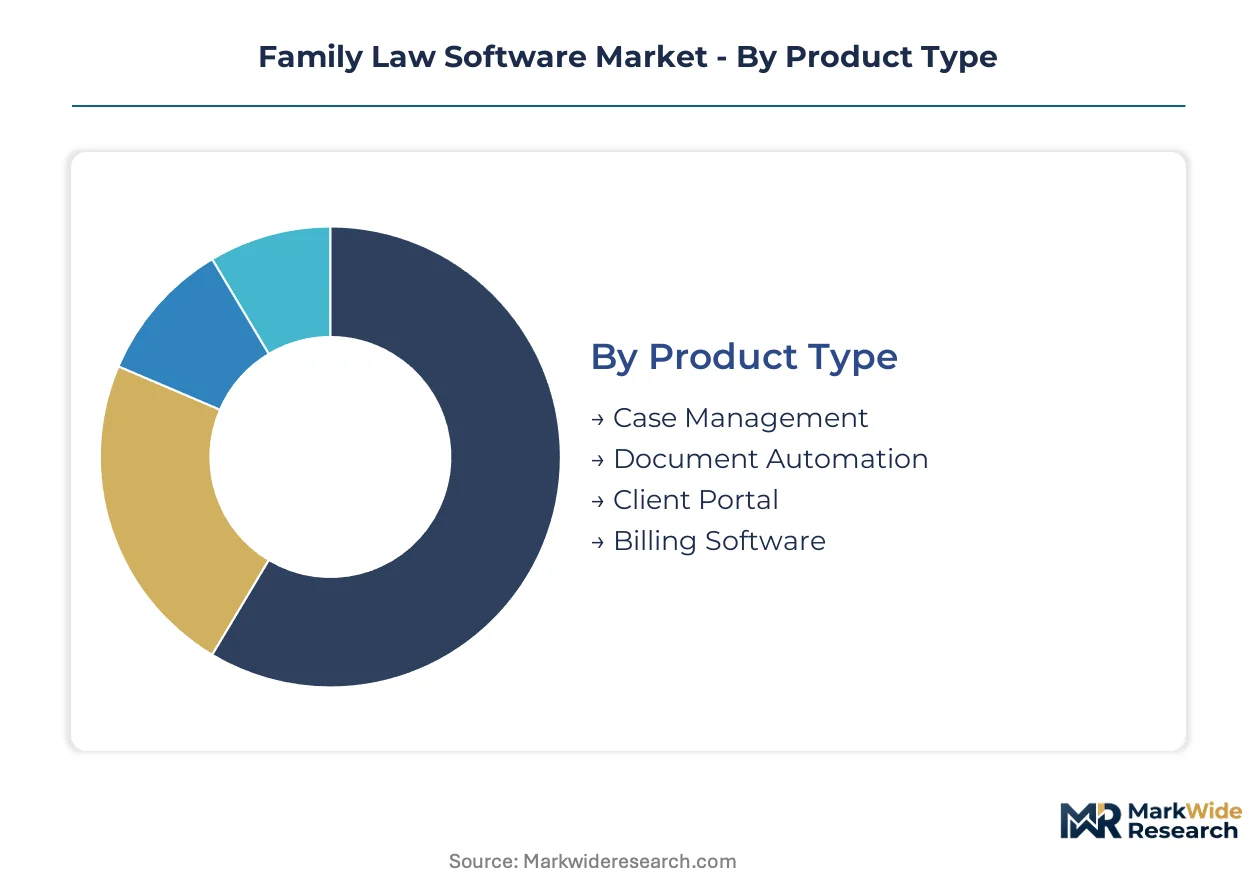
Segmentation in family law software reveals how specialized compliance requirements and practice-size economics create distinct product-market fit profiles. Vendors must architect solutions around jurisdictional form libraries, deployment security preferences, and integration depth that varies sharply across buyer types.
Product Type:
After-sales service intensity varies dramatically across product categories, with case management platforms demanding continuous court system updates while billing software requires minimal ongoing vendor intervention.
- Case Management:Core platform functionality spans calendaring, deadline tracking, and matter organization with court-specific rules engines. Demand concentrates among mid-sized law firms in Texas and Florida where high-volume dockets require automated workflow orchestration to manage compliance risk.
- Document Automation:Natural language generation tools assemble jurisdiction-specific divorce petitions, parenting plans, and support calculations. Solo practitioners in Arizona and Washington adopt these fastest under state bar technology competence mandates that sanction attorneys failing to adopt reasonable efficiencies.
- Client Portal:Secure document exchange interfaces satisfy California, Texas, and Florida court mandates for digital self-service options.
- Billing Software:Time tracking and flat-fee matter profitability tools support firms restructuring around fixed-fee uncontested divorce packaging.
By volume, Case Management leads. By growth pace, Client Portal is ahead.
Deployment:
Cost tier stratification separates enterprise-grade on-premise installations from accessible SaaS entry points, with hybrid architectures capturing firms navigating security-performance tradeoffs.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital barriers for individual attorneys and micro-practices. Solo practitioners represent the fastest-expanding adoption segment as subscription models displace perpetual license requirements.
- On-Premise:Local server installations retain preference among security-conscious practices handling sensitive custody disputes where data residency control outweighs feature velocity.
- SaaS:Single-tenant dedicated cloud instances serve firms requiring configuration isolation without physical infrastructure ownership.
- Hybrid Solutions:Split architectures keep sensitive client records on-premise while leveraging cloud calendaring and court connectivity.
Cloud-Based captures the largest installed base. Hybrid Solutions are climbing the fastest as migration friction persists.
End User:
Customer type determines integration complexity tolerance and procurement authority structures, with legal departments imposing enterprise IT standards that conflict with practitioner-driven firm purchases.
- Solo Practitioners:Individual attorneys operating without support staff drive demand for all-in-one platforms with minimal configuration overhead. This segment is expanding most quickly as cloud SaaS eliminates upfront capital requirements previously blocking technology access.
- Law Firms:Partnership-governed practices with 5-50 attorneys prioritize workflow automation that reallocates paralegal hours toward client-facing advisory functions.
- Legal Departments:Corporate and government legal divisions impose procurement standards requiring SOC 2 compliance and dedicated security reviews.
- Non-Profit Organizations:Legal aid societies and pro bono networks seek grant-funded deployments with volunteer coordinator functionality.
Law Firms dominate current revenue. Solo Practitioners are gaining share fastest.
Integration Level:
Supply concentration among vendors with dedicated court integration teams creates competitive moats, as state-level e-filing fragmentation forces specialized compliance layer development rather than standardized national platforms.
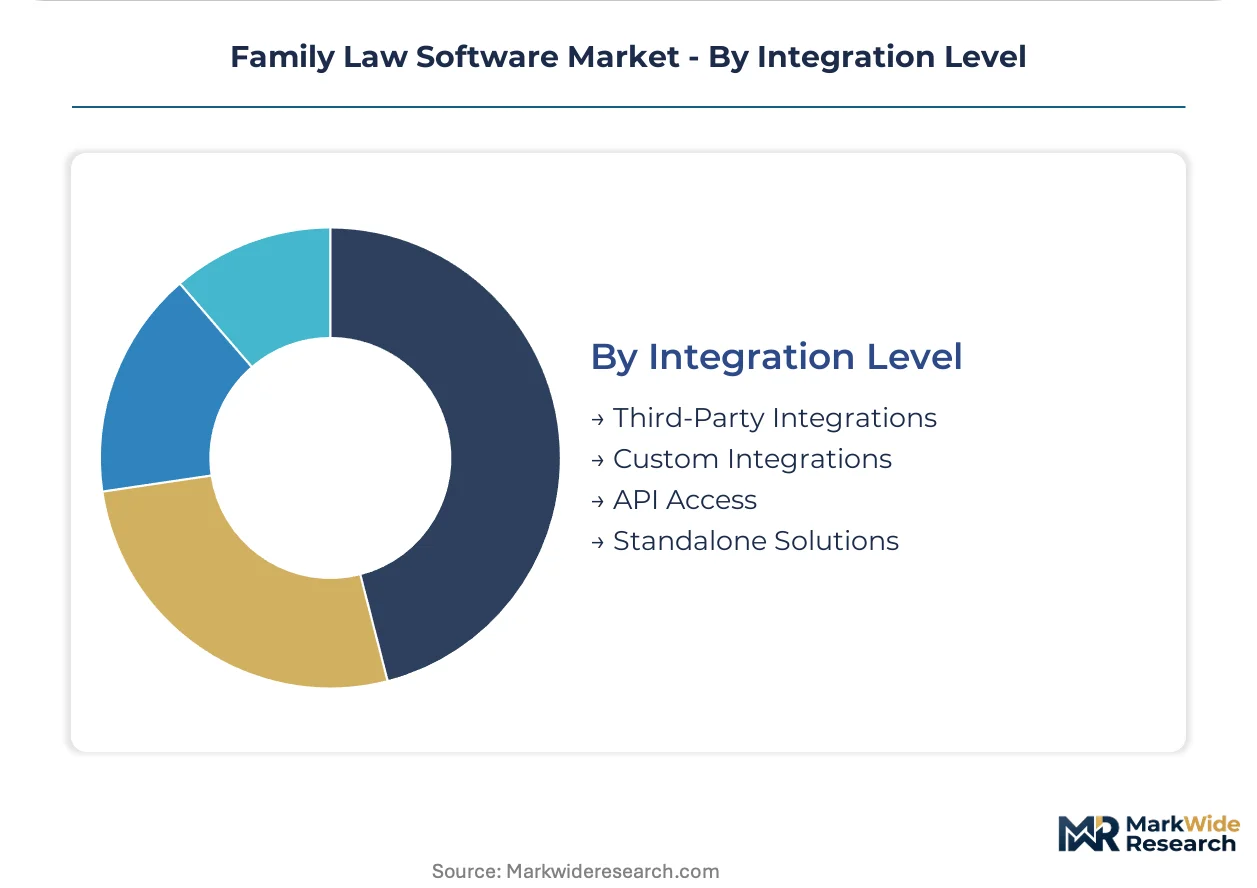
- Third-Party Integrations:Pre-built connectors to court e-filing systems, accounting software, and payment processors. Demand concentrates among practices seeking rapid deployment without custom development.
- Custom Integrations:Bespoke API development for firms with unique workflow requirements or proprietary legacy systems.
- API Access:Developer-facing endpoints enabling practice-specific automation and reporting tool construction.
- Standalone Solutions:Closed-system platforms serving practices with limited interoperability requirements or security policies restricting external connections.
Third-Party Integrations lead by deployment count. API Access shows the steepest expansion trajectory as firms demand workflow flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The family law software sector exhibits pronounced import-export asymmetry in intellectual property and data infrastructure, with the United States exporting SaaS platforms while importing specialized compliance engineering talent from Canada and the United Kingdom to address fragmented state-level court requirements.
United States
State court e-filing mandates in California, Texas, and Florida drive concentrated platform demand from solo practitioners and mid-sized firms. The American Bar Association's technology competence requirements pressure attorneys in Arizona and Washington to accelerate cloud adoption. Dallas-Fort Worth and Miami legal tech clusters host vendor integration teams building jurisdiction-specific compliance layers for county court systems.
United Kingdom
Family court modernization programs and HM Courts & Tribunals Service digital reform initiatives expand addressable market for cloud-based case management. The Solicitors Regulation Authority's guidance on technology and legal practice shapes procurement standards for London-based family law chambers. Manchester and Birmingham legal service hubs attract SaaS vendors targeting alternative dispute resolution workflows.
Canada
Provincial court system fragmentation between Ontario, British Columbia, and Quebec creates specialized localization requirements similar to the US state-level pattern. The Federation of Law Societies of Canada's model code on technology competence influences adoption timelines. Toronto's legal technology corridor hosts development operations serving both domestic and US cross-border compliance engineering needs.
Australia
Family Court of Australia and Federal Circuit Court consolidation drives demand for unified practice management platforms handling property settlement and parenting matters. The Law Council of Australia's technology and the legal profession guidance shapes ethical compliance frameworks. Sydney and Melbourne legal tech clusters concentrate vendor implementation resources for eastern seaboard family law practices.
Germany
Specialized family court procedures and mandated mediation prerequisites create demand for workflow tools distinct from common-law jurisdictions. The Federal Bar Association's digitalization initiatives accelerate technology refresh cycles among German family law practitioners. Munich and Frankfurt legal service centers host European headquarters operations for international SaaS providers adapting products to civil law requirements.
Family Law Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying document automation engines and calendaring rule libraries. The vendor landscape concentrates around cloud-native architectures with court integration capabilities, while fragmented point-solution providers serve niche compliance requirements. Three archetypes dominate: full-practice platforms, document automation specialists, and client communication tools. Competitive intensity manifests through jurisdiction-specific feature development and strategic partnerships with state bar associations.
Within the full-practice platform tier, Clio and Filevine exemplify scale-driven positioning through deep court system integration and workflow automation respectively. PracticePanther Legal Software anchors the aggressively-priced SaaS entry segment targeting capital-constrained solo practitioners. These three entities collectively represent the competitive fault lines between premium integration depth and accessible pricing tiers that define current market segmentation.
| Leading Market Players |
|---|
| Filevine |
| PracticePanther Legal Software |
| MyCase |
| Custody X Change |
| Family Law Software |
| Clio |
| SmartAdvocate |
| OurFamilyWizard |
| Smokeball |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in US-based court integration engineering teams is forcing SaaS vendors to extend implementation timelines and attach premium pricing to jurisdiction-specific compliance modules. This utilization squeeze simultaneously elevates vendor pricing power in high-demand states and accelerates offshore talent sourcing from Canadian and British development hubs.
Pricing Analysis
Solo practitioner buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the family law software market. Price differentiation rests on court integration depth and automated document library breadth, with California and Texas practitioners showing lowest price sensitivity due to mandatory e-filing compliance deadlines. Cost compression in the economy tier is intensifying because horizontal legal platforms are bundling basic family law functionality at reduced rates. Micro-practices with sub-$500K annual revenue exhibit highest price sensitivity and drive demand for sub-$50 monthly entry subscriptions.
Supply Chain Analysis
Upstream feedstock for family law software development concentrates in cloud infrastructure provisioning from the United States, Canada, and Ireland, with jurisdictional rule engine content sourcing from domestic legal publishers. Raw material dependencies include API connectivity frameworks, natural language processing libraries, and court system authentication protocols. Single-source vulnerability in state-specific e-filing gateway access creates supply chain risk when court technology vendors alter integration requirements. Distribution runs through direct vendor sales teams serving metropolitan legal clusters, supplemented by state bar association endorsement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
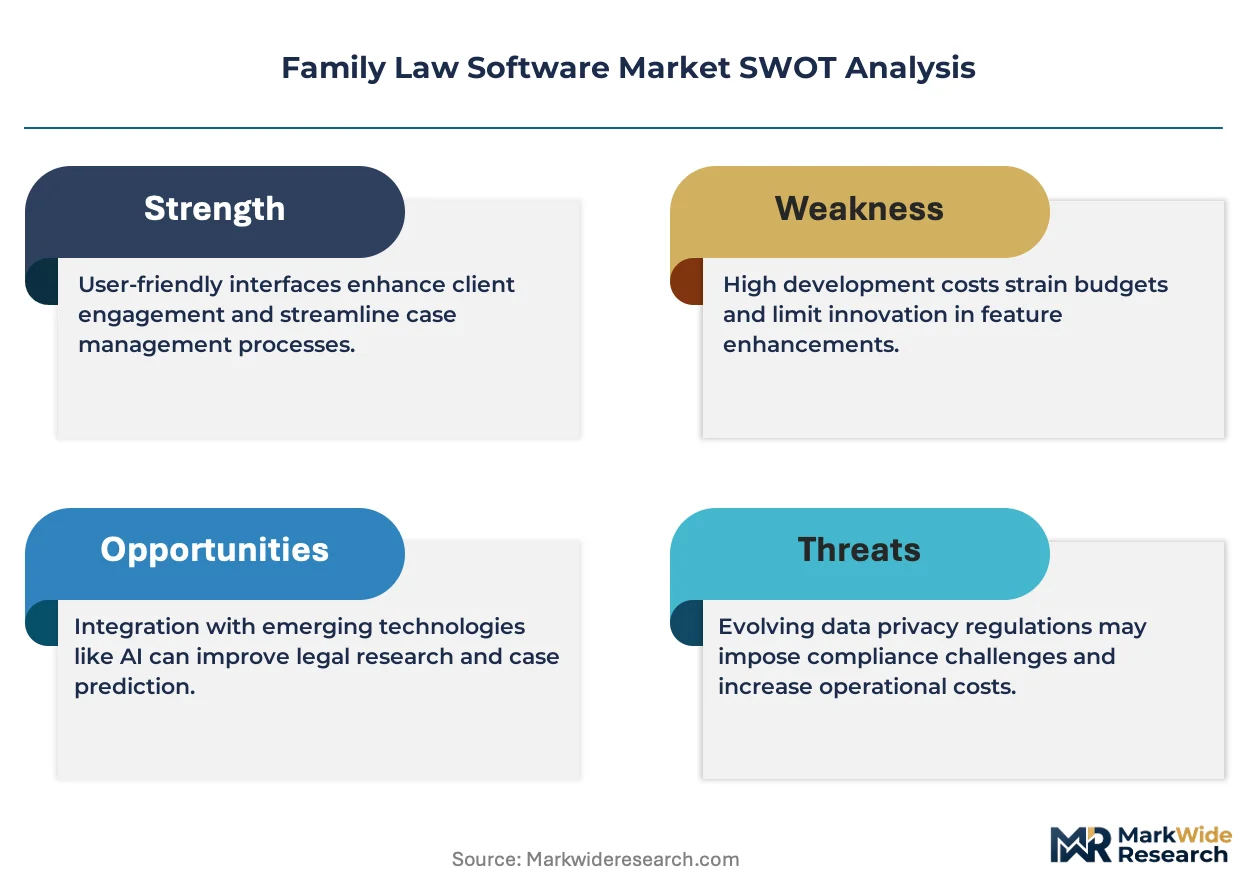
State-level procedural fragmentation creates a fragmentation opportunity in family law software, as divergent court mandates prevent national platform standardization and sustain niche vendor viability across multiple jurisdictions.
For Market Incumbents: Insulate market position by deepening vertical integration into court system API maintenance teams in Florida and Texas, where e-filing mandate complexity creates switching costs. Prioritize certification investment in SOC 2 Type II and state bar ethics opinion compliance to defend against horizontal legal platform substitution threatening mid-market share.
For New Entrants and Emerging Players: Build out mediation-adjacent workflow modules targeting Colorado and Oregon court-connected alternative dispute resolution programs, the most penetrable segment given limited incumbent specialization. Pursue grant-funded legal aid society deployments as a go-to-market angle to establish reference accounts before commercial expansion.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because persistent jurisdictional fragmentation prevents commoditization and sustains pricing power for compliance-deep platforms. Target acquisition archetypes are single-tenant SaaS providers with dedicated court integration teams in high-mandate states. Watch state bar technology competence enforcement intensity as the inflection signal for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Court System API Integration | Deep e-filing connectivity in California and Texas locks in practitioner switching costs. |
| AI-Assisted Document Generation | Natural language processing for parenting plans commands premium pricing from mid-sized firms. |
| Mobile-First Client Portal Development | SMS-integrated status updates address accessibility gaps for pro se custody litigants. |
| State Bar Association Partnership | Endorsement channels accelerate trust formation with technology-mandated solo practitioners. |
| Hybrid Deployment Architecture | Split cloud-on-premise solutions capture security-conscious custody dispute practices. |
Research Methodology
Cross-validation between primary fieldwork and regulatory filing analysis anchors the qualitative findings in this study. Interviews with family law practice managers, state court technology officers, legal aid organization directors, and SaaS vendor product leads were combined with secondary validation against state bar ethics opinions, court administrative rule filings, and e-filing mandate documentation. Bottom-up practitioner adoption modeling and top-down market sizing triangulate volume estimates across deployment modes and practice size segments.
Calibration against historical technology refresh cycles in legal services informs the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, practice size tier, integration complexity level, and regional court mandate intensity. CAGRs were derived from fitted adoption curves weighted by state-level e-filing implementation timelines. Forecast inputs include solo practitioner cloud migration velocity and state bar technology competence enforcement patterns.
Stress conditions across regulatory mandate acceleration, horizontal platform competitive intensity, and data residency requirement expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about court technology standardization timelines. Cross-checking against state court administrative budget appropriations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Output Management Software Market
Software & Services
Data Integration Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Communication Software Market
Software & Services
Global Email Management Software Market
Software & Services
Global UIUX Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Business Email Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Global Architecture Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Video Management Software (VMS) Market
Software & Services
House Cleaning App Market