
 Family Office Software Solutions Market | 2026-2036
Family Office Software Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Family Office Software Solutions Market Insights
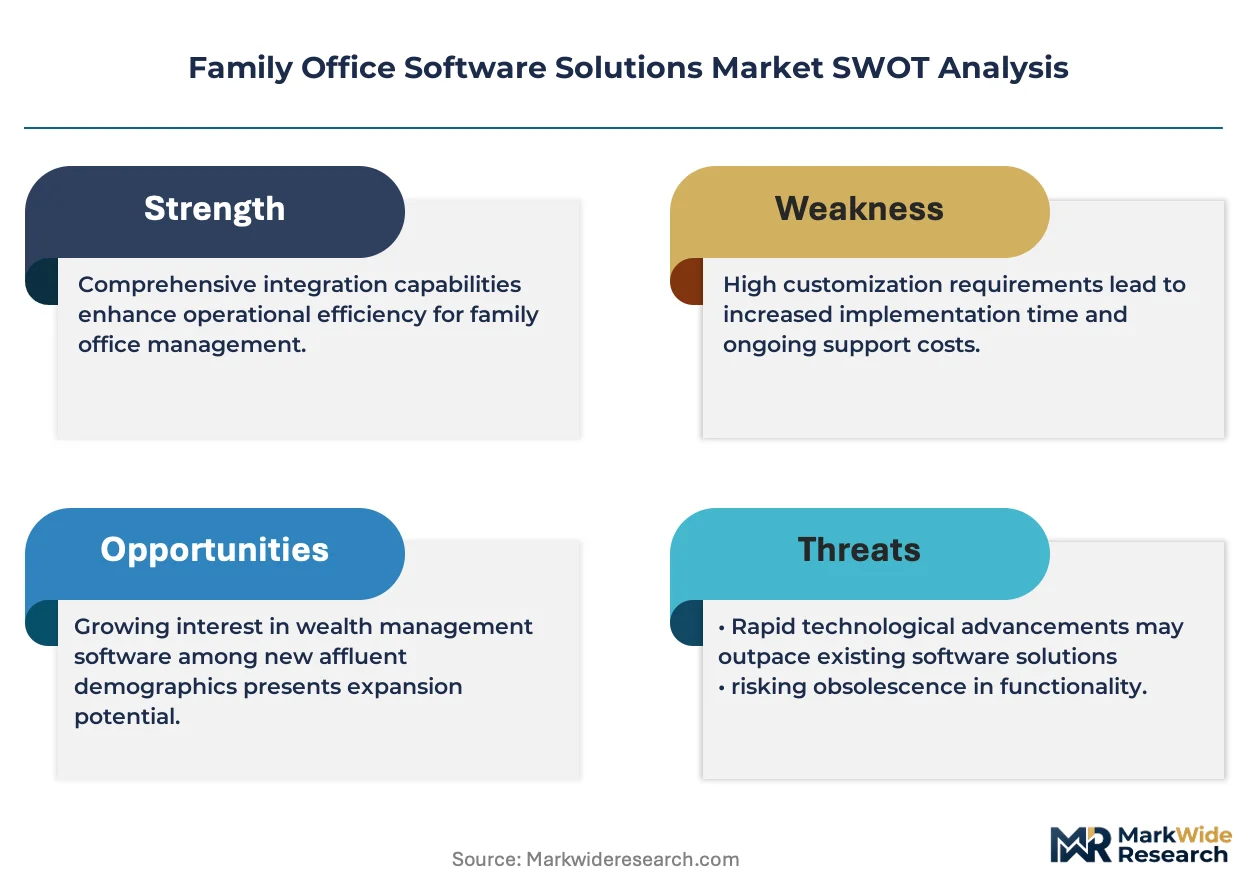
Direct-to-family-office software licensing is tilting away from traditional wealth management intermediaries. Addepar leverages data aggregation architecture to anchor institutional-caliber analytics for ultra-high-net-worth principals. Eton Solutions competes through workflow automation that spans entity management across complex family structures. FundCount specializes in partnership accounting functionality that occupies a narrow but defensible niche among multi-generational wealth holders.
Family office software solutions constitute integrated technology platforms that consolidate investment reporting, entity governance, and generational wealth transfer administration through multi-currency, multi-asset data architectures. These systems process illiquid alternative investments, private fund cash flows, and consolidated balance sheets across legal entities to deliver real-time visibility to principals and their advisors. Cloud-based deployment leads segment expansion as family offices abandon on-premises infrastructure maintenance, while portfolio analytics commands premium pricing due to complexity in private market benchmarking. API integration represents the fastest-growing configuration as families demand connectivity between custodial banks, fund administrators, and tax preparation systems.
SEC disclosure requirements shape product development priorities for vendors serving United States family offices, while GDPR data residency rules constrain cloud architecture choices for European deployments. The UK's Financial Conduct Authority oversight of wealth management intermediaries indirectly elevates software audit trail standards. Stakeholders must monitor how evolving tax transparency frameworks across jurisdictions alter data retention and cross-border reporting specifications.
Market Dynamics
SEC disclosure mandates around alternative asset reporting are forcing multi-family offices to abandon spreadsheet-based tracking in favor of integrated platforms that automate Form PF and Schedule 13F filings.
Growth Catalysts
- Alternative Investment Complexity:Family offices now allocate substantial capital to private equity, venture funds, and direct co-investments that demand specialized partnership accounting modules unavailable in generic wealth platforms.
- GDPR and CSRD Compliance:European family offices face intensified data residency requirements and sustainability disclosure obligations that cloud-native architectures address more efficiently than legacy on-premises systems.
- Generational Wealth Transfer:The impending intergenerational transfer of trillions in assets is creating demand for entity governance tools that map complex ownership structures across trusts, holding companies, and philanthropic vehicles.
Market Restraints
- Implementation Cost Structure:Data migration from legacy systems and specialized consultant fees for alternative asset configuration create six-figure onboarding barriers for smaller single-family offices.
- Talent Concentration Risk:The scarcity of professionals combining software engineering expertise with partnership accounting knowledge concentrates in New York, London, and Singapore, inflating implementation timelines.
- Regulatory Fragmentation:Divergent tax transparency frameworks across Switzerland, Luxembourg, and the Cayman Islands complicate cross-border reporting standardization for vendors.
Strategic Opportunities
- Asia-Pacific Expansion:Singapore and Hong Kong family offices remain underpenetrated by specialized software relative to their assets under management, presenting first-mover advantages for localized deployment.
- AI-Driven Document Parsing:Machine learning models trained on private fund capital call notices and K-1 statements can automate data extraction that currently requires manual entry by family office staff.
- Open Banking APIs:Regulatory mandates for custodial data sharing in the United Kingdom and European Union enable real-time portfolio aggregation without proprietary bank feeds.
Industry Challenges
- Integration Complexity:Connecting new platforms to decades-old trust accounting systems and bespoke Excel models requires expensive custom development that erodes vendor margins.
- Cybersecurity Certification Burden:SOC 2 Type II and ISO 27001 audits demand eighteen-month compliance timelines that delay product launches and strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Family Office Software Solutions Market |
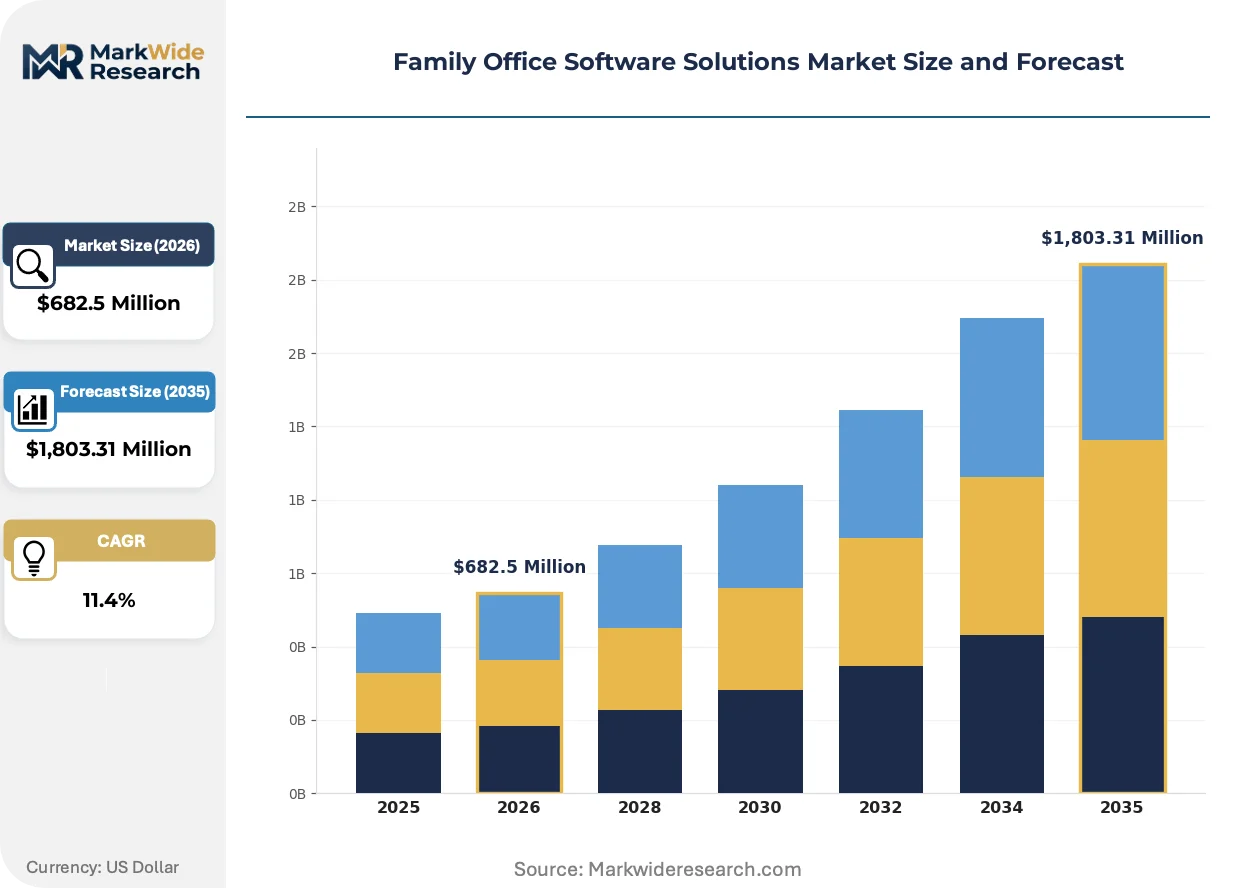
| Market Size in 2026 | $682.5 Million |
| Market Size in 2035 | $1,803.31 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Investment Management, Wealth Planning, Risk Management, Portfolio Analytics Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: Single Family Offices, Multi Family Offices, Wealth Advisors, Family Members Integration Level: API Integration, Standalone Solutions, Multi-System Integration, Custom Integrations |
| Companies Covered | Aleta, Masttro, Addepar, Eton Solutions, FundCount, Landytech, Asora, Altoo, Asset Vantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Family Office Software Solutions Market Trends and Innovations
Cloud-native architectures are displacing on-premises infrastructure as family offices prioritize operational agility over capital expenditure control. Vendors now compete through API ecosystems rather than monolithic feature sets.
API-first data aggregation is rendering obsolete the manual reconciliation workflows that family office staff previously performed across custodial portals and fund administrator reports. Ultra-high-net-worth principals in the United States and United Kingdom are demanding real-time visibility into illiquid positions. This connectivity compression is collapsing the traditional quarterly reporting cycle into continuous monitoring.
The SEC's Form PF amendments and expanded private fund adviser rules are mandating granular exposure reporting that legacy systems cannot accommodate. Vendors serving United States family offices must now embed automated regulatory filing modules. Multi-family offices with over $150 million in regulatory assets under management face the steepest compliance burden and are accelerating procurement timelines accordingly.
Direct licensing to family offices is displacing the traditional wealth management intermediary channel that historically bundled software into advisory relationships. Principals now procure platforms independently and demand unbundled pricing transparency. This disintermediation is most pronounced among single-family offices in the United States with dedicated investment staff who bypass external advisors entirely.
Family Office Software Solutions Market Segmentation
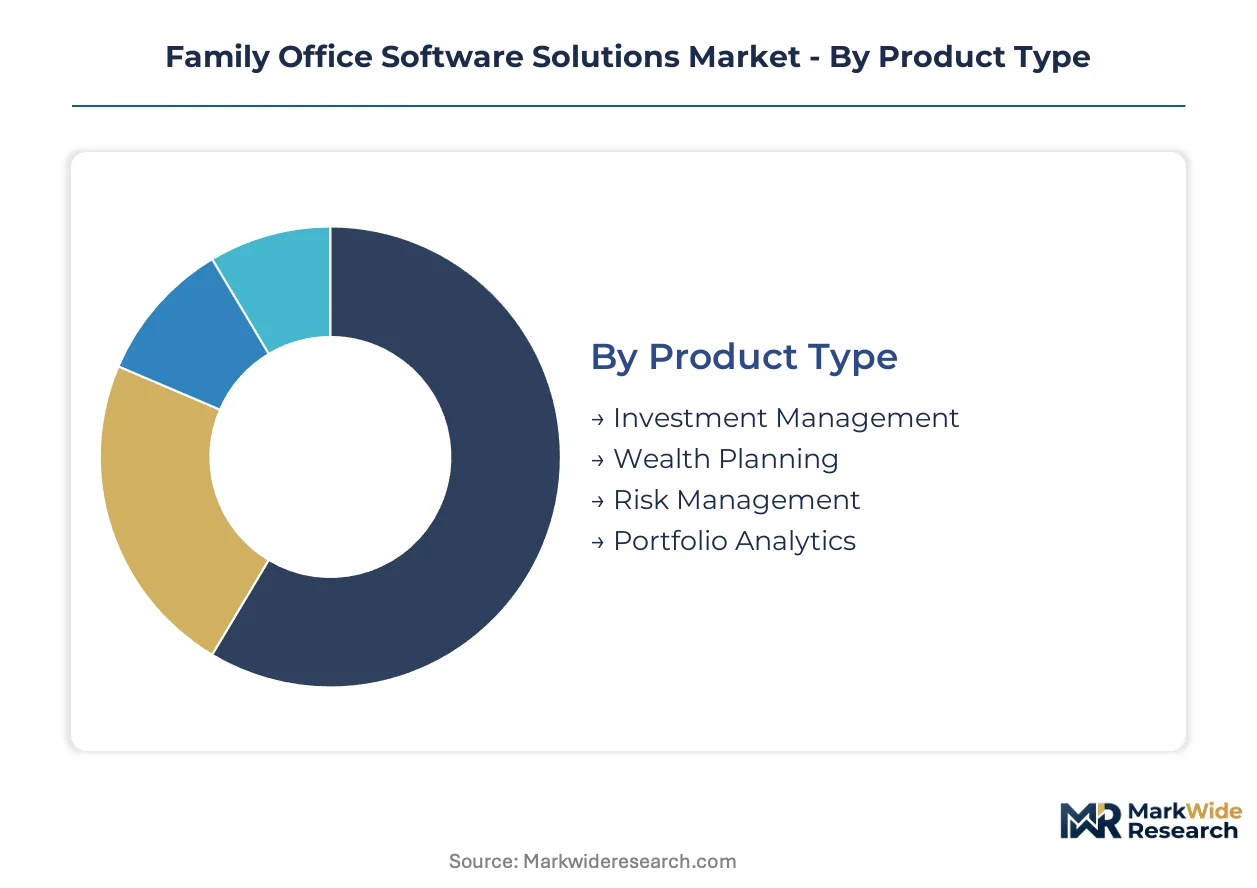
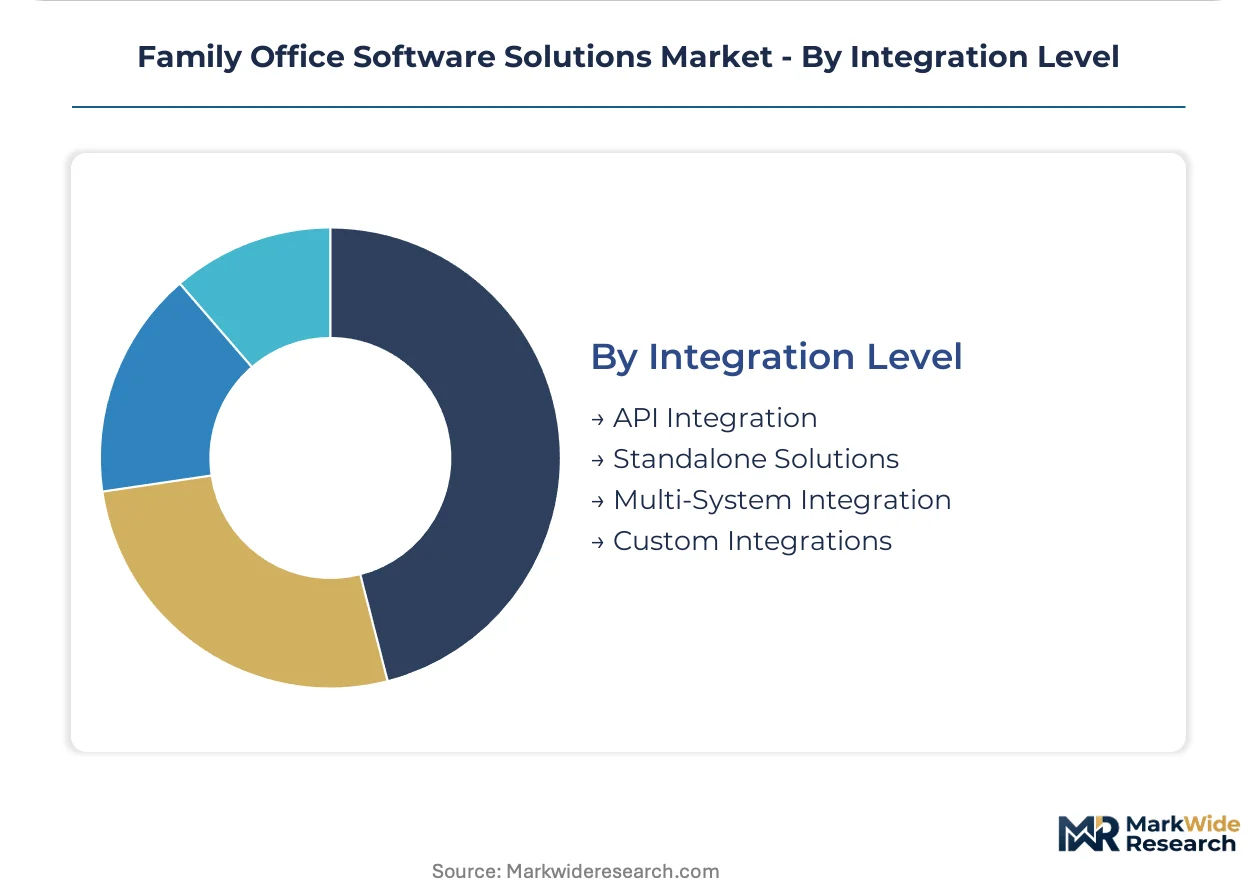
Segmentation in family office software reflects divergent operational maturity levels and regulatory exposure across principal types. Deployment architecture and integration depth determine total cost of ownership more than feature breadth alone.
Product Type:
After-sales service intensity varies dramatically across product categories, with portfolio analytics demanding continuous calibration and investment management requiring ongoing regulatory updates.
- Investment Management:Core modules track multi-asset positions across custodians, automate corporate action processing, and generate tax-lot reporting. Demand concentrates among multi-family offices in the United States facing SEC Form PF filing obligations, where automation replaces manual spreadsheet compilation.
- Portfolio Analytics:Advanced benchmarking engines handle private market IRR calculations and risk-adjusted attribution across illiquid holdings. Ultra-high-net-worth principals in the United Kingdom drive procurement here, seeking real-time visibility into alternative asset exposure that custodial banks cannot provide.
- Wealth Planning:Tools map generational transfer scenarios across trust structures and jurisdictional boundaries.
- Risk Management:Modules monitor concentration limits and counterparty exposure across fragmented family entity structures.
Investment Management holds the largest share; momentum sits with Portfolio Analytics.
Deployment:
Cost tier stratification separates enterprise cloud contracts from constrained on-premises installations at smaller single-family offices.
- Cloud-Based:SaaS architectures eliminate infrastructure maintenance burdens and enable automatic regulatory compliance updates. United States and United Kingdom family offices dominate adoption, prioritizing operational agility over capital expenditure control and data residency flexibility.
- On-Premises:Legacy installations persist where data sovereignty concerns or bespoke security requirements override convenience. Swiss and Cayman Islands structures favor this model due to strict confidentiality protocols and limited trust in third-party hosting.
- Hybrid:Split configurations keep sensitive entity data local while pushing portfolio analytics to cloud environments.
- Mobile:Principal-facing applications deliver consolidated dashboards for travel-intensive ultra-wealthy families.
Cloud-Based deployments command the dominant revenue position; Hybrid configurations are climbing the fastest as transitional families seek intermediate solutions.
End User:
Customer type determines pricing elasticity and implementation complexity more than any other segmentation dimension.
- Multi Family Offices:Shared infrastructure models spread software costs across multiple principal families while standardizing reporting formats. These entities in the United States are accelerating procurement fastest due to SEC disclosure rule tightening around alternative asset reporting.
- Single Family Offices:Dedicated staff and bespoke workflows demand extensive customization and direct vendor relationships. Singapore and Hong Kong structures increasingly favor independent platforms over wealth advisor intermediation.
- Wealth Advisors:Intermediary channels bundle software access into advisory fee structures, though this model is losing share to direct licensing.
- Family Members:Direct principal access drives demand for simplified interfaces and educational tooling around complex holdings.
Multi Family Offices represent the largest addressable base; Single Family Offices are gaining share fastest through direct procurement.
Integration Level:
Supply concentration among API-first vendors is displacing monolithic platform incumbents across all principal categories.
- API Integration:Modular connectivity enables real-time data flows between custodial banks, fund administrators, and tax preparation systems. United States family offices lead adoption, leveraging open banking momentum and demanding continuous rather than quarterly portfolio visibility.
- Custom Integrations:Bespoke development connects legacy trust accounting systems and decades-old Excel models to modern platforms. These projects concentrate among multi-generational European families with complex entity hierarchies spanning Luxembourg, Switzerland, and the United Kingdom.
- Standalone Solutions:Self-contained platforms serve smaller offices with limited legacy infrastructure to reconcile.
- Multi-System Integration:Middleware layers harmonize data across disparate vendor ecosystems without full replacement.
API Integration holds the dominant position; Custom Integrations are expanding most quickly as legacy modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States substantially exceeds that in Switzerland, where data sovereignty mandates compress vendor margins. United Kingdom deployments command mid-tier rates. Singapore and Hong Kong represent emerging premium markets.
United States
Multi-family offices drive procurement volume as SEC Form PF amendments mandate automated alternative asset disclosure. The SEC's expanded private fund adviser rules force platform upgrades for offices managing over $150 million in regulatory assets. New York and Boston clusters concentrate implementation expertise, with Connecticut hedge fund country extending demand into adjacent family office structures.
United Kingdom
Ultra-high-net-worth principals demand real-time portfolio visibility that custodial banks fail to deliver. The Financial Conduct Authority's oversight of wealth management intermediaries elevates software audit trail standards. London's Mayfair and Knightsbridge districts host dense concentrations of single-family offices procuring direct licensing arrangements.
Switzerland
Strict confidentiality protocols and limited trust in third-party hosting sustain on-premises deployment preference. FINMA guidelines on operational risk management shape vendor certification requirements. Geneva and Zurich private banking centers anchor demand for hybrid configurations that keep sensitive entity data local.
Singapore
Family offices remain underpenetrated by specialized software relative to assets under management. The Monetary Authority of Singapore's family office incentive schemes accelerate entity formation without corresponding platform adoption. The Marina Bay financial district and Tanglin residential enclave concentrate newly established single-family office operations.
Germany
GDPR data residency requirements and CSRD sustainability disclosure obligations favor cloud-native architectures. BaFin supervision of investment advisors indirectly mandates enhanced reporting capabilities. Frankfurt's financial center and Munich's industrial family headquarters generate demand for multi-generational wealth transfer administration tools.
Family Office Software Solutions Market Competitive Landscape
Data-aggregation specialists and workflow-automation platforms split the market along functional lines. The vendor landscape concentrates around three strategic archetypes: institutional-caliber analytics providers, entity-management workflow specialists, and partnership-accounting niche players. Consolidation pressure operates through strategic partnerships between core platform vendors and regional system integrators, plus technology licensing arrangements that extend geographic reach without direct expansion costs.
Within the analytics-focused tier, Addepar anchors institutional-grade data architecture positioning. Eton Solutions and FundCount occupy complementary workflow and accounting specializations. These three exemplify how vendor differentiation now depends on integration depth rather than feature breadth alone, with each representing distinct approaches to the alternative asset complexity that dominates family office technology procurement.
| Leading Market Players |
|---|
| Aleta |
| Masttro |
| Addepar |
| Eton Solutions |
| FundCount |
| Landytech |
| Asora |
| Altoo |
| Asset Vantage |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in partnership accounting expertise across New York, London, and Singapore concentrates vendor pricing power while inflating implementation timelines for family office software deployments. This talent scarcity enables premium pricing for configured-to-order platforms while compressing margins on standardized SaaS tiers that compete through volume.
Pricing Analysis
The customization-premium spread separates standard SaaS subscriptions from configured-to-order implementations requiring specialized alternative asset module development. Pricing stratifies across premium, standard, and economy tiers based on integration depth and after-sales service intensity, with portfolio analytics commanding the highest premiums due to private market benchmarking complexity. Cost compression in the standard tier is intensifying because cloud-native entrants compete on operational agility rather than feature breadth. Multi-family offices in the United States exhibit the lowest price sensitivity as SEC disclosure mandates accelerate procurement timelines regardless of cost.
Supply Chain Analysis
Contract manufacturing concentration in software development rests on specialized engineering talent pools in the United States, United Kingdom, and India, with implementation partners anchoring delivery capacity in Singapore and Switzerland. The supply chain draws from cloud infrastructure providers, regulatory compliance content libraries, and API connectivity modules to platform ecosystems. Single-source vulnerability concentrates in partnership accounting expertise that feeds from a narrow pipeline of professionals combining software engineering with alternative investment knowledge. Distribution runs through direct vendor relationships with family office principals, displacing traditional wealth management intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The family office software market rewards vendors possessing rare combinations of alternative investment accounting knowledge and modern API architecture capabilities. Firms bridging this skill gap capture disproportionate pricing power and implementation velocity.
For Market Incumbents: Harden defensive moats by embedding automated SEC Form PF filing modules that emerging entrants cannot replicate without eighteen-month compliance timelines. Deepen upstream control over partnership accounting talent pipelines through university recruiting partnerships in New York and London. Cloud-native challengers with AI-driven document parsing capabilities represent the primary substitution threat requiring continuous R&D investment in machine learning infrastructure. For New Entrants and Emerging Players: Build out localized deployment capabilities targeting Singapore and Hong Kong family offices that remain underpenetrated relative to assets under management. The single-family office segment in Asia-Pacific offers the most penetrable entry point due to accelerating entity formation without corresponding software adoption. A direct-to-principal go-to-market angle bypassing wealth advisor intermediation aligns with procurement pattern shifts in the United States and United Kingdom. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as SaaS architectures eliminate infrastructure maintenance burdens and enable automatic regulatory compliance updates. Acquisition targets should display API-first integration depth rather than monolithic feature breadth, with demonstrated connectivity to custodial banks and fund administrators. The signal to watch is Monetary Authority of Singapore family office incentive scheme uptake accelerating without proportional software procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Document Parsing Development | Machine learning models trained on private fund K-1 statements automate data extraction that currently requires manual entry by family office staff. |
| API Ecosystem Expansion | Modular connectivity enables real-time data flows between custodial banks, fund administrators, and tax preparation systems demanded by United States principals. |
| Regulatory Filing Module Integration | Automated SEC Form PF and Schedule 13F compliance addresses disclosure mandates forcing multi-family offices to abandon spreadsheet-based tracking. |
| Asia-Pacific Localization Investment | Singapore and Hong Kong family offices remain underpenetrated by specialized software relative to their assets under management. |
| Partnership Accounting Talent Acquisition | Scarcity of professionals combining software engineering expertise with alternative investment knowledge concentrates in New York, London, and Singapore. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, vendor product documentation, and regulatory disclosure databases to construct bottom-up and top-down triangulation. Primary interviews engaged family office technology officers, private fund administrators, wealth management compliance leads, and platform integration specialists across the United States, United Kingdom, Switzerland, and Singapore. Secondary validation incorporated Financial Conduct Authority guidance documents, FINMA operational risk circulars, and Monetary Authority of Singapore family office scheme disclosures.
Forecast inputs considered deployment architecture transitions, integration complexity tiers, end-user segmentation across multi-family and single-family offices, and regional regulatory cluster variations. The analytical framework modeled product type splits across investment management, portfolio analytics, wealth planning, and risk management modules. CAGRs were derived from penetration rate assumptions tied to SEC disclosure mandate timelines and GDPR data residency requirement enforcement patterns.
Stress conditions across alternative asset allocation shifts, cloud migration velocity, and partnership accounting talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory compliance timeline adherence and principal technology procurement autonomy trends. Quarterly review of SEC Form PF amendment implementation rates and Singapore family office entity formation data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Device Tracking Software Market
Software & Services
Global Award Management Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
Global Document Management Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
India Software Services Export Market
Software & Services
Software Licensing Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
Global Translation Software Market
Software & Services
Global Calendar Scheduling Software Market