
 Content Moderation Software Market | 2026-2036
Content Moderation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Moderation Software Market Insights
AI-native inference silicon is hardening the cost structure of real-time video moderation pipelines. Microsoft sustains R&D intensity across multimodal foundation models for content classification. Amazon Web Services dominates cloud-hosted moderation API throughput with tight integration into its broader compute stack. Hive differentiates through vertical specialization in synthetic media detection, where model freshness determines commercial viability.
Content moderation software comprises algorithmic systems that classify, flag, or remove user-generated material against policy frameworks, typically processing text, image, audio, and video through machine learning classifiers operating at latencies under 200 milliseconds for live-streaming contexts. Its primary commercial purpose is to reduce brand risk and regulatory exposure for platforms hosting third-party content. Cloud-based deployment captures the majority of new procurement, since elastic scaling aligns cost with traffic spikes across viral content events. AI-powered services represent the fastest-expanding service type, though hybrid moderation—combining automated triage with human review for edge cases—retains the largest revenue pool due to premium pricing for high-stakes decisions.
The EU AI Act imposes conformity obligations on high-risk AI systems used for content ranking and removal, directly shaping product roadmaps for vendors serving European platforms. The FCC's Section 230 deliberations in the United States create demand uncertainty that moderates near-term investment timelines. India's MeitY intermediary rules mandate traceability and grievance redressal mechanisms, opening a distinct compliance-driven market segment. Stakeholders must monitor how divergent national liability frameworks fragment product standardization and force region-specific engineering investments.
Market Dynamics
The EU AI Act's risk-based classification for automated content removal is forcing platform operators to rebuild compliance architectures around explainable AI requirements, while India's MeitY intermediary guidelines simultaneously accelerate domestic vendor development across the Global South.
Growth Catalysts
- EU AI Act Conformity Obligations:High-risk system designations for content ranking algorithms mandate auditable decision trails, expanding procurement of hybrid moderation stacks with embedded documentation layers.
- Live-Streaming Latency Requirements:Sub-200 millisecond inference demands are hardening real-time video pipelines, pulling investment toward edge-deployed silicon and model compression techniques.
- Synthetic Media Proliferation:Generative AI output detection now sits at the center of trust and safety roadmaps, with freshness-dependent model updates becoming a recurring revenue anchor for specialized vendors.
Market Restraints
- Inference Cost Volatility:GPU cluster pricing fluctuations and energy input costs compress margins on cloud-hosted moderation APIs, particularly for smaller platform operators without volume-committed contracts.
- Liability Fragmentation:Divergent national frameworks—Section 230 deliberations in the United States versus strict intermediary liability in Germany—force redundant engineering investments that resist product standardization.
- Human Review Bottlenecks:Premium-priced hybrid moderation retains dependence on trained moderator workforces, where attrition rates and content exposure limits create capacity ceilings during viral content surges.
Strategic Opportunities
- India's Compliance-Driven Market:MeitY's grievance redressal and traceability mandates open a distinct procurement segment where domestic vendors hold regulatory relationship advantages over foreign competitors.
- Multimodal Foundation Model Convergence:Unified text-image-audio-video classifiers are collapsing point-solution vendor stacks, creating white space for platforms that integrate cross-modal reasoning into single inference endpoints.
- Elastic Cloud Scaling Models:Viral event traffic patterns favor consumption-based pricing over provisioned infrastructure, rewarding vendors with tight integration into hyperscaler compute stacks.
Industry Challenges
- Explainability Engineering Talent:The shortage of ML engineers capable of building interpretable classification systems with documented decision trails limits vendor capacity to serve EU-regulated platforms.
- Legacy CMS Integration Friction:Content management system heterogeneity across platform estates forces costly custom adapter development, delaying time-to-value for new moderation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Moderation Software Market |
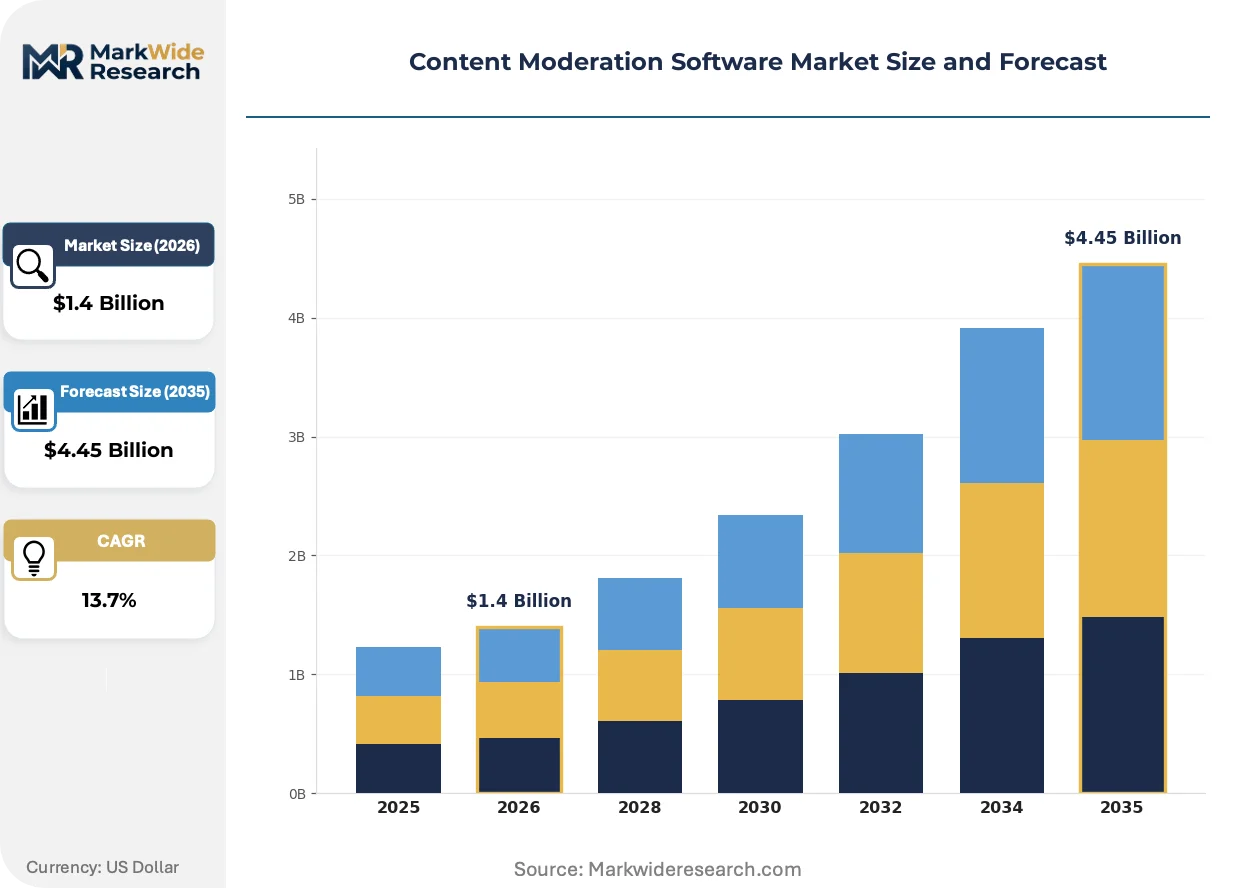
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automated Moderation, Manual Moderation, Hybrid Moderation, AI-Powered Services Deployment: On-Premises, Cloud-Based, SaaS, Managed Hosting End User: Social Media Platforms, E-Commerce Sites, Gaming Companies, Online Communities Functionality: Image Filtering, Text Moderation, Video Analysis, Real-Time Monitoring |
| Companies Covered | Amazon Web Services, Microsoft, Clarifai, Sift Science, Hive, Appen Limited, TaskUs, Telus International, Checkstep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Moderation Software Market Trends and Innovations
Foundation model architectures are collapsing the historical separation between text, image, and video moderation pipelines, while regulatory pressure on algorithmic transparency accelerates investment in interpretable classification systems.
Multimodal transformer architectures are rewriting how platforms approach content classification. Social media operators with diverse media mixes are deploying unified inference endpoints at accelerating pace. This convergence is compressing the addressable market for point-solution vendors who historically specialized in single-modality detection.
The EU AI Act's high-risk system obligations are reshaping product roadmaps for vendors serving European platforms. Mandatory conformity assessments and post-market monitoring requirements are extending sales cycles. French and German platform operators are now demanding built-in audit logging and human oversight interfaces as standard procurement requirements.
Platform procurement teams are unbundling after-sales service from core software licenses, moving toward usage-calibrated support tiers. This shift disrupts traditional enterprise software pricing and is most visible among mid-sized platforms in India and Southeast Asia, where capital efficiency pressures favor operational expenditure models over upfront capital deployment.
Content Moderation Software Market Segmentation
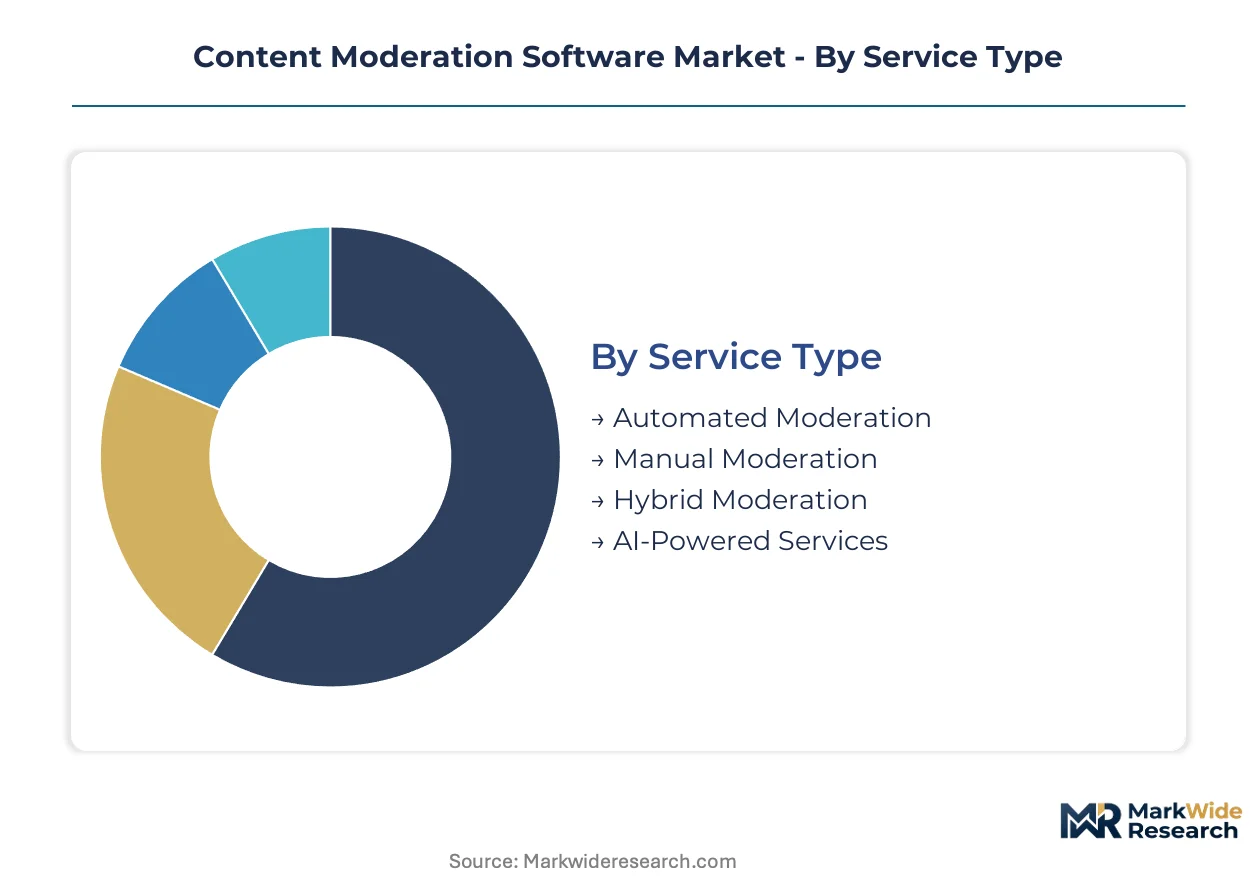
Content moderation software segments reflect divergent integration depths, from embedded API layers to standalone enterprise systems. Procurement patterns vary sharply by deployment complexity and regulatory exposure.
Service Type:
Standalone moderation services command premium pricing for specialized compliance needs, while embedded AI layers integrate directly into platform infrastructure.
- Automated Moderation:Rule-based classifiers and keyword filters process high-volume content streams with deterministic outputs. Social media platforms in India deploy these systems to satisfy MeitY's traceability mandates at scale.
- Hybrid Moderation:Automated triage routes edge cases to human reviewers, combining latency efficiency with judgment for high-stakes decisions. EU AI Act conformity obligations are accelerating procurement of these stacks with embedded audit trails.
- Manual Moderation:Trained human reviewers handle nuanced policy violations requiring contextual interpretation. Attrition rates and content exposure limits constrain capacity during viral surges.
- AI-Powered Services:Foundation model classifiers enable multimodal detection across text, image, and video. Freshness-dependent model updates create recurring revenue for specialized vendors in synthetic media detection.
Volume placements concentrate in Hybrid Moderation; the faster expansion belongs to AI-Powered Services.
Deployment:
Cost tier stratification separates capital-intensive on-premises estates from consumption-calibrated cloud models.
- Cloud-Based:Elastic scaling aligns infrastructure cost with traffic spikes across viral content events. AWS dominates API throughput through tight integration with its broader compute stack.
- SaaS:Subscription licensing with usage-calibrated tiers reduces upfront capital deployment. Mid-sized platforms in India and Southeast Asia favor this operational expenditure model.
- On-Premises:Dedicated hardware estates serve platforms with data sovereignty requirements or latency-sensitive live-streaming pipelines. GPU cluster pricing volatility compresses margins for operators without volume-committed contracts.
- Managed Hosting:Vendor-operated infrastructure with custom SLAs bridges control and outsourcing. French and German platform operators demand built-in audit logging as standard procurement requirements.
Cloud-Based deployments capture majority new procurement; SaaS is climbing the fastest among capital-constrained operators.
End User:
Application intensity varies by content velocity and regulatory scrutiny across platform categories.
- Social Media Platforms:Diverse media mixes drive unified multimodal inference endpoints at accelerating pace. EU AI Act high-risk system designations mandate auditable decision trails for content ranking algorithms.
- E-Commerce Sites:Product listing verification and review authenticity detection reduce brand risk. Synthetic media proliferation has elevated generative AI output detection to center of trust and safety roadmaps.
- Gaming Companies:Real-time voice and text moderation in multiplayer environments demands sub-200 millisecond inference. Edge-deployed silicon investment is hardening these latency-sensitive pipelines.
- Online Communities:Niche platforms with limited engineering resources rely on third-party API integration. Legacy content management system heterogeneity forces costly custom adapter development.
Social Media Platforms anchor procurement volume; Gaming Companies show steepest expansion trajectory from live-streaming demands.
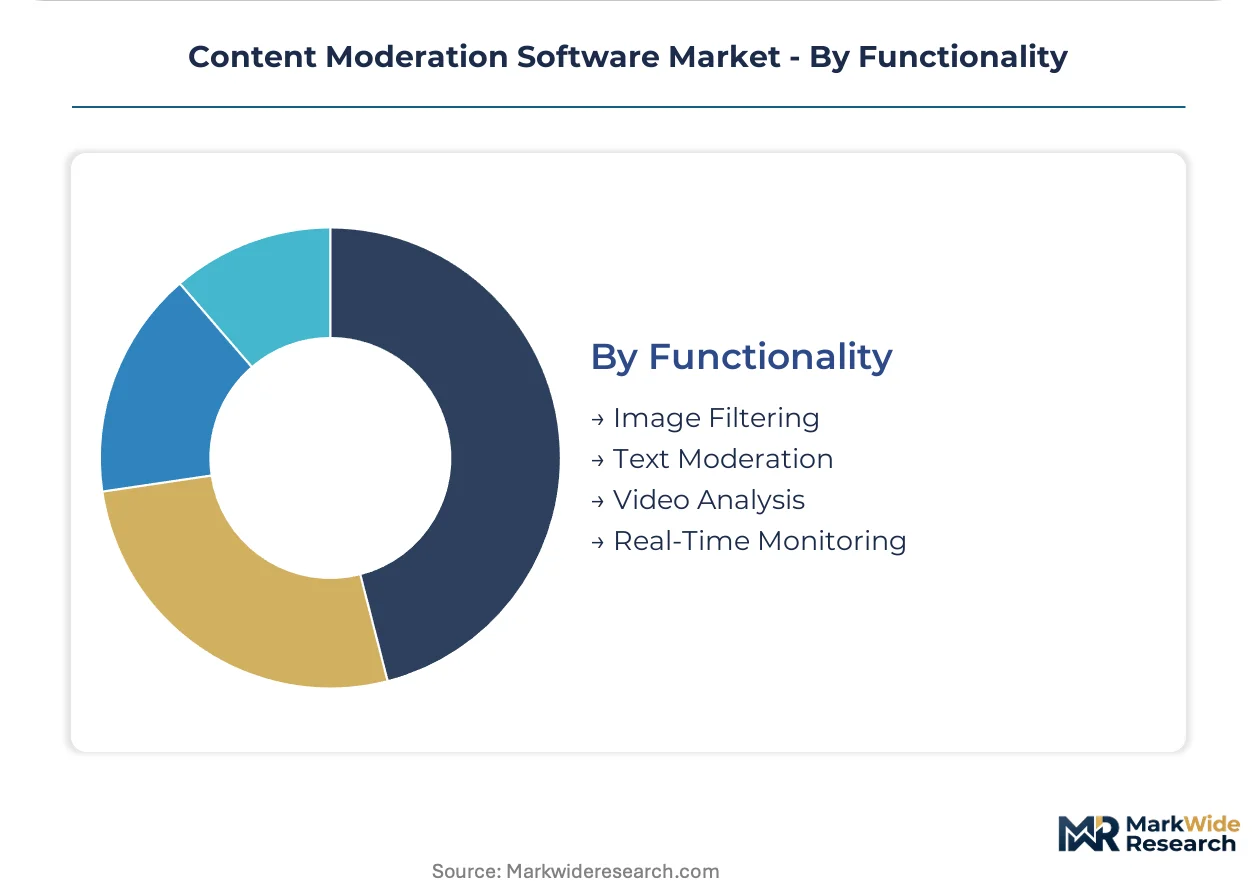
Functionality:
Technology maturity separates established text and image pipelines from emerging video and real-time modalities.
- Video Analysis:Frame-by-frame classification with temporal coherence modeling processes hours of content per minute. Sub-200 millisecond inference requirements are pulling investment toward model compression techniques.
- Real-Time Monitoring:Live-streaming moderation operates at latencies under 200 milliseconds for immediate intervention. Edge-deployed inference silicon is hardening cost structures for these pipelines.
- Text Moderation:Natural language classifiers detect policy violations across multilingual corpora. Foundation model architectures are collapsing historical separation between text and multimodal pipelines.
- Image Filtering:Convolutional and transformer-based detectors classify visual content against policy frameworks. Point-solution vendors face compression as platforms deploy unified inference endpoints.
Image Filtering retains largest installed base; Real-Time Monitoring is gaining share fastest from live-streaming proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform procurement for content moderation software clusters in jurisdictions with strict intermediary liability frameworks, where regulatory enforcement creates immediate compliance expenditure. India, Germany, the United States, Brazil, and the United Kingdom concentrate distinct demand profiles shaped by local enforcement regimes.
United States
Social media platforms headquartered in California and New York Metro drive substantial procurement volumes for real-time video moderation pipelines. FCC Section 230 deliberations create demand uncertainty that moderates near-term investment timelines. Seattle and Austin host expanding engineering clusters developing edge-deployed inference silicon for latency-sensitive applications.
Germany
French and German platform operators now mandate built-in audit logging and human oversight interfaces as standard procurement requirements under EU AI Act conformity obligations. The NetzDG intermediary liability framework predates Brussels harmonization and established precedent for strict content removal timelines. Berlin and Munich anchor vendor development centers serving DACH-region compliance architectures.
India
MeitY's intermediary guidelines accelerate domestic vendor development across trust and safety technology procurement. Grievance redressal and traceability mandates open a distinct compliance-driven market segment where local vendors hold regulatory relationship advantages. Bengaluru and Hyderabad concentrate engineering talent for hybrid moderation stacks serving South Asian platform operators.
Brazil
The Marco Civil da Internet establishes intermediary liability principles that platform operators address through automated classification investments. São Paulo anchors Latin American procurement decisions for Portuguese-language content moderation services. Rio de Janeiro hosts regional headquarters for global vendors calibrating models to local cultural context.
United Kingdom
Ofcom's Online Safety Bill enforcement timeline drives platform preparation for enhanced duty of care obligations across user-generated content. London concentrates fintech and gaming platform procurement for real-time moderation infrastructure. Manchester and Edinburgh host specialized vendor operations serving UK-specific regulatory interpretation requirements.
Content Moderation Software Market Competitive Landscape
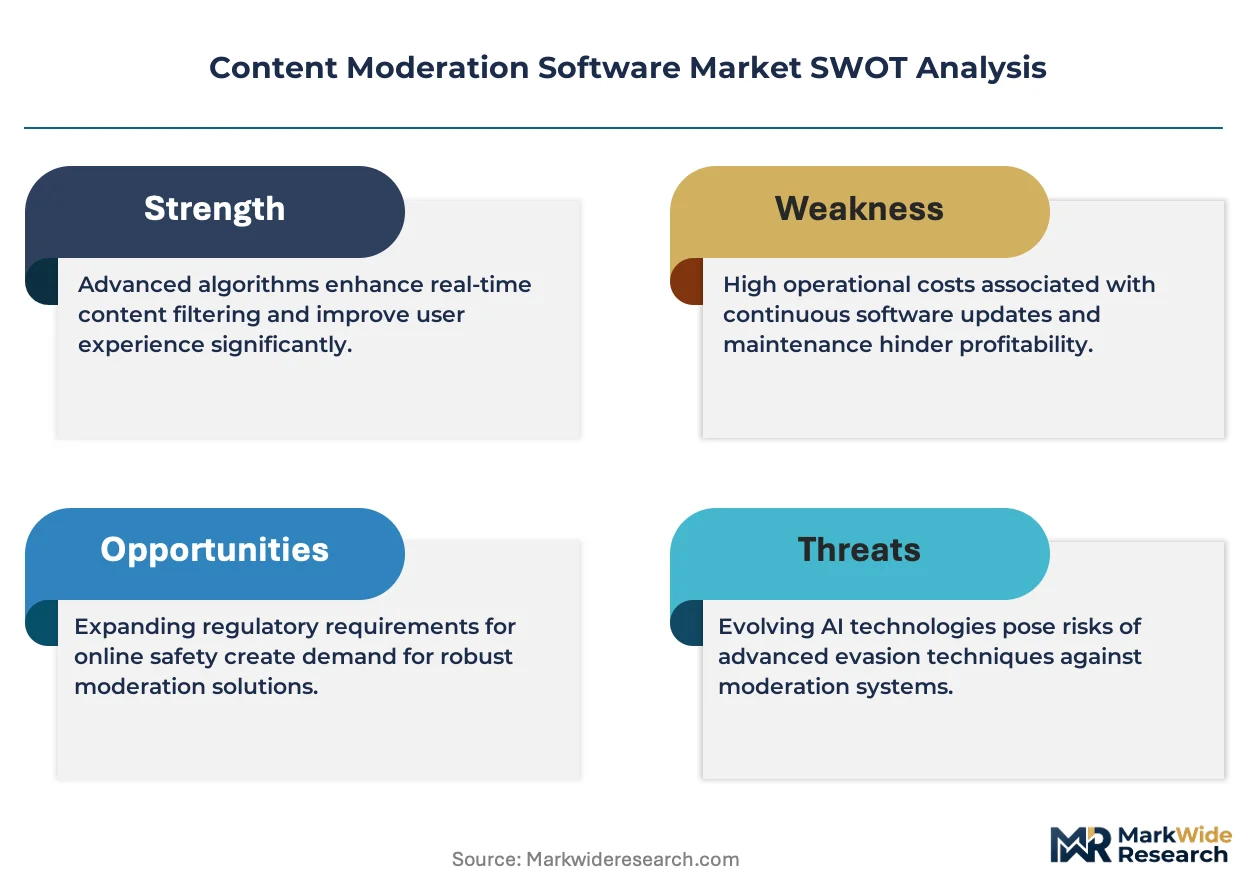
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing API throughput through compute stack integration while boutique vendors defend positions in synthetic media detection. The vendor base organizes around three strategic archetypes: infrastructure-integrated platforms, vertical specialists, and human-in-the-loop service operators. Consolidation pressure concentrates among point-solution vendors facing multimodal foundation model convergence. Geographic expansion and technology licensing represent dominant competitive vectors as regulatory fragmentation forces region-specific engineering investments.
Within the infrastructure-integrated tier, Amazon Web Services and Microsoft exemplify scale-driven positioning through tight coupling of moderation APIs to broader cloud compute offerings. Hive occupies a specialist position in synthetic media detection where model freshness determines commercial viability. These three anchors illustrate how competitive advantage stratifies between horizontal platform leverage and vertical expertise depth.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Clarifai |
| Sift Science |
| Hive |
| Appen Limited |
| TaskUs |
| Telus International |
| Checkstep |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up human-in-the-loop service operators are consolidating fragmented moderator workforces across India and Southeast Asia, tightening cost discipline while cloud-native API vendors compete on consumption-based elasticity. This ownership pattern concentrates pricing power among scaled hybrid moderation providers and hyperscaler-integrated platforms, compressing margins for standalone point-solution vendors caught between volume commitments and GPU cluster pricing volatility.
Pricing Analysis
Volume placements concentrate in SaaS-tiered subscription models with usage-calibrated tiers, while premium hybrid moderation commands project-based fees for high-stakes decisions requiring embedded audit trails. Price differentiation rests on certification grade—EU AI Act conformity assessments carry substantial premiums—and volume scale, with enterprise platforms securing committed-use discounts unavailable to mid-sized operators. Pricing pressure stems from GPU energy input costs compressing cloud-hosted API margins. Gaming companies and live-streaming platforms show highest price sensitivity due to latency-hardened infrastructure requirements; social media incumbents with regulatory exposure demonstrate lowest sensitivity to secure compliance architectures.
Supply Chain Analysis
Reverse-logistics flows are minimal in digital-first content moderation, though model retraining pipelines and synthetic media detection freshness cycles create circular dependency on labeled dataset refreshes from annotation vendors. Supply concentrates in the United States for foundation model development, India for human review workforce scale, and Taiwan for AI inference silicon fabrication. Raw material dependencies span NVIDIA GPU clusters, cloud compute credits, and multilingual training corpora. Supply chain risk centers on single-source vulnerability in frontier model access. Distribution runs through direct enterprise sales for hybrid moderation stacks and marketplace API integrations for embedded AI layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race into labeled data generation and edge inference silicon, as control over training pipeline quality and latency-hardened infrastructure separates scalable platforms from margin-compressed API resellers.
For Market Incumbents: Deploy in-house synthetic media detection model development to defend against freshness-dependent revenue erosion from specialized vendors like Hive. Consolidate human review operations through captive BPO acquisitions in Bengaluru and Hyderabad to reduce dependency on third-party annotation vendors. Build explainability engineering teams to capture EU AI Act-mandated procurement from French and German platform operators. For New Entrants and Emerging Players: Begin with India's compliance-driven market segment, where MeitY grievance redressal mandates create procurement urgency and domestic regulatory relationships outweigh foreign vendor scale advantages. Target mid-sized gaming companies in Southeast Asia with edge-deployed inference solutions priced on consumption-based elasticity rather than provisioned infrastructure. Pursue channel partnerships with AWS and Microsoft marketplace integrations to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid moderation service operators with captive workforce scale in South Asia, where attrition-rate volatility has compressed valuations below replacement cost for trained moderator pipelines. Long-term viability hinges on automation substitution curves for human review tasks. Watch synthetic media detection model freshness update frequency as an inflection indicator—vendors falling behind quarterly refresh cycles face rapid commercial obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Multimodal Foundation Model Integration | Unified text-image-audio-video classifiers collapse point-solution vendor stacks into single inference endpoints. |
| Edge Inference Silicon Deployment | Sub-200 millisecond latency requirements harden cost structures for live-streaming moderation pipelines. |
| EU AI Act Conformity Certification | Mandatory audit logging and human oversight interfaces become standard procurement requirements in Germany. |
| Captive Annotation Workforce Acquisition | Control over labeled data generation secures model training pipeline quality and reduces third-party dependency. |
| Consumption-Based Pricing Migration | Operational expenditure models align vendor revenue with viral event traffic patterns across Indian and Southeast Asian platforms. |
Research Methodology
Document review covered hyperscaler capex disclosures, SEC filings from public trust and safety vendors, and EU regulatory implementation guidance, complemented by interviews with platform trust and safety executives, AI engineering leads at social media operators, procurement officers at gaming companies, and compliance directors navigating MeitY and EU AI Act obligations. Secondary validation drew from App Annie usage data, cloud infrastructure spending reports, and intermediary liability framework analyses. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and service types.
Historical revenue trajectories from public vendor filings were cross-referenced against panel input from procurement officers regarding budget allocation shifts. The analytical framework modeled deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion. Industry-specific forecast inputs included synthetic media detection model update frequency and live-streaming infrastructure capex cycles.
Underlying measurement precision varies by segment; cloud-based deployment and social media platform end-use carry tighter precision due to transparent vendor reporting, while on-premises gaming installations and manual moderation services exhibit wider confidence intervals. Forecasts reflect assumptions regarding regulatory enforcement timelines and GPU cluster pricing stability. Practitioners should monitor EU AI Act conformity assessment completion rates and NVIDIA supply allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Warehouse Software Market
Software & Services
Employee Referral Software Market
Software & Services
Warranty Management Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Software Containers Market
Software & Services
Geophysical Software Service Market
Software & Services
Queue Manager Market
Software & Services
Apache Spark Market
Software & Services
Global Online Community Management Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Camp Management Software Market
Software & Services
Office Productivity Software Market
Software & Services
Global Architecture Design Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Legal Software Market
Software & Services
Lifecycle Management Software Market