
 Global Subscription Billing Software Market | 2026-2036
Global Subscription Billing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subscription Billing Software Market Outlook
North American cloud infrastructure investment is hardening as the primary supply-side capacity anchor for subscription billing platforms. Zuora leverages enterprise-grade monetization suites to sustain its position among Fortune 500 SaaS adopters. Chargebee competes aggressively in mid-market segments with localized tax automation capabilities. Stripe anchors payment orchestration layers that extend billing functionality into embedded finance workflows across developer ecosystems.
Subscription billing software automates recurring revenue collection, invoice generation, and subscriber lifecycle management through rule-based engines that handle proration, dunning, and revenue recognition compliance. Cloud-based deployment leads structural adoption as enterprises abandon on-premises maintenance overhead for elastic infrastructure that scales with subscriber volatility. Usage-based payment models represent the fastest-growing segment as IoT providers and API platforms seek granular consumption metering that native integrations alone cannot orchestrate without real-time data pipelines.
GDPR in Europe mandates granular subscriber consent tracking that billing platforms must embed at the contract level, while PCI-DSS requirements govern payment data architecture across all deployment modes. India's RBI guidelines on recurring payment mandates force platform redesigns for card-on-file authentication workflows. Stakeholders must monitor how ISO 27001 certification requirements evolve as procurement teams weight security posture against speed-to-implement in vendor selection.
Market Dynamics
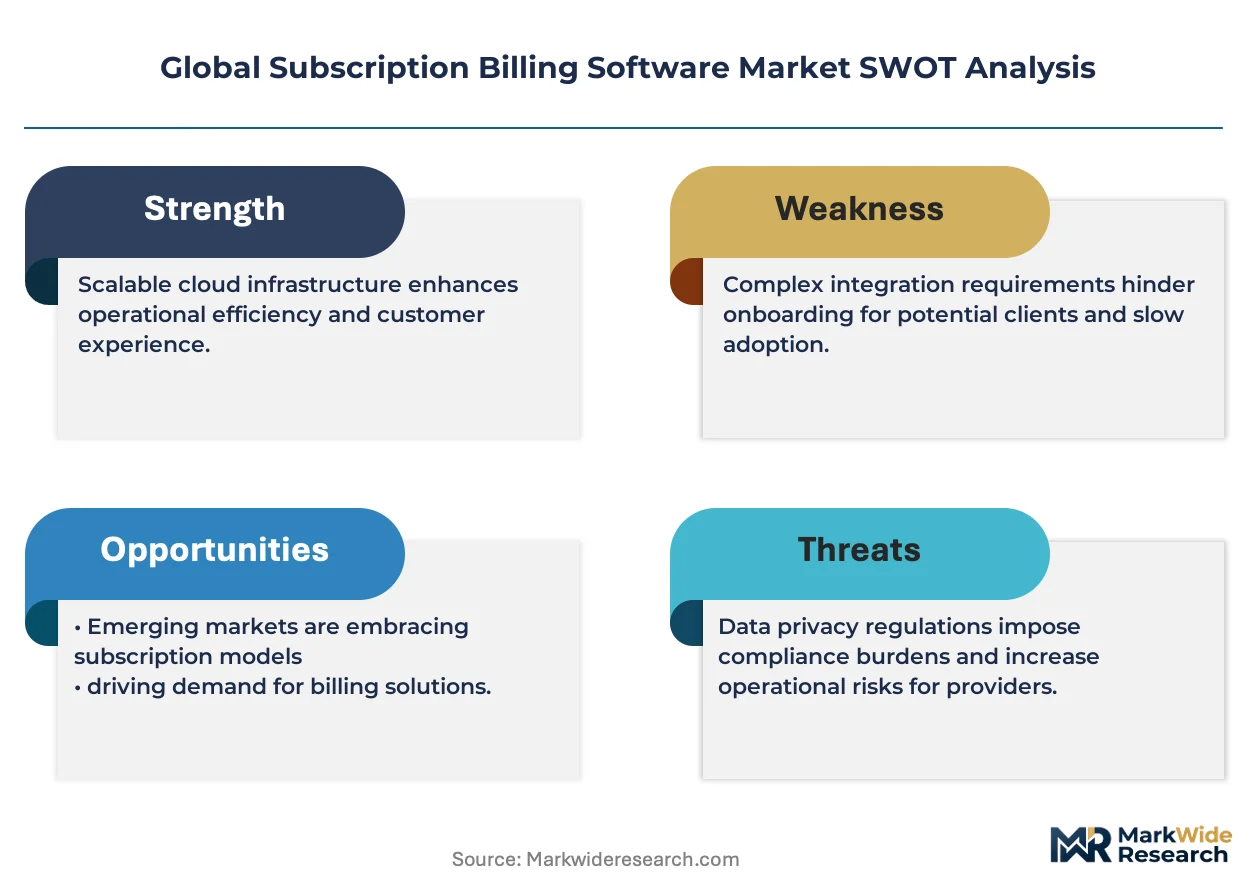
API-first architectures are compressing deployment timelines for subscription billing platforms while fragmenting vendor competitive moats across enterprise and mid-market tiers.
Growth Catalysts
- Cloud Migration:Enterprises abandon on-premises maintenance overhead for elastic infrastructure that scales with subscriber volatility.
- GDPR Mandates:Granular subscriber consent tracking requirements force billing platforms to embed compliance at the contract level across European deployments.
- Usage-Based Pricing:IoT providers and API platforms seek granular consumption metering that native integrations cannot orchestrate without real-time data pipelines.
Market Restraints
- PCI-DSS Compliance Costs:Payment data architecture requirements impose heavy audit and certification burdens regardless of deployment mode.
- India's RBI Guidelines:Recurring payment mandate rules force platform redesigns for card-on-file authentication workflows, delaying market entry.
- Technical Debt:Legacy ERP integrations require custom middleware development that extends implementation cycles by months.
Strategic Opportunities
- Embedded Finance Convergence:Payment orchestration layers extend billing functionality into developer ecosystems through native API integrations.
- Latin America Expansion:Underpenetrated SaaS markets in Brazil and Mexico present first-mover advantages for localized tax automation.
- ISO 27001 Certification:Evolving procurement weighting of security posture against speed-to-implement creates differentiation for certified vendors.
Industry Challenges
- Revenue Recognition Expertise:Shortage of accountants fluent in ASC 606 and IFRS 15 compliance creates implementation bottlenecks for enterprise clients.
- Multi-Currency Complexity:Real-time exchange rate handling and localized tax calculation require engineering resources that strain mid-market vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subscription Billing Software Market |
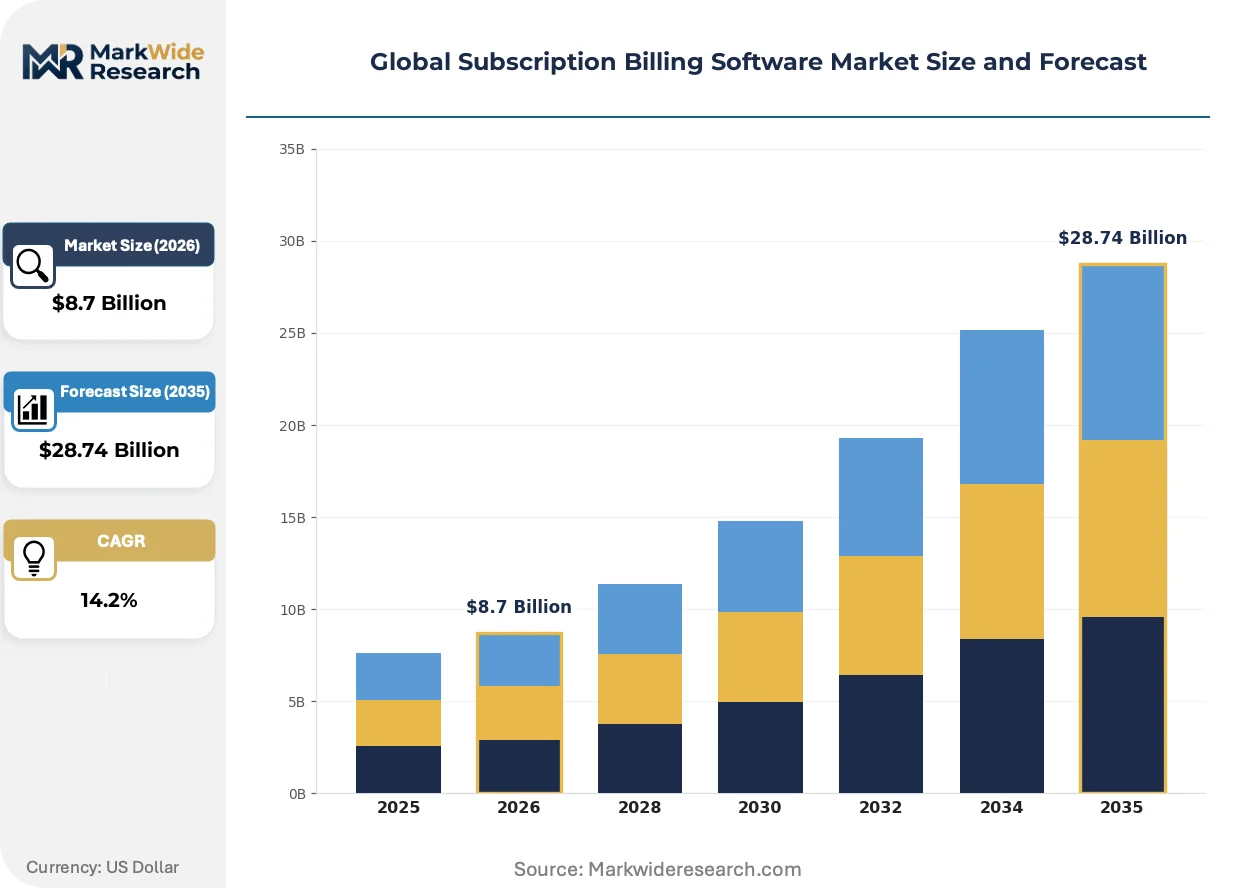
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Large Enterprises, SMEs, Startups, Freelancers Payment Model: Recurring Billing, One-Time Payment, Usage-Based, Variable Pricing Integration Level: API-Based, Native Integrations, Third-Party, Manual |
| Companies Covered | Zuora, Chargebee, Recurly, Salesforce, SAP, Stripe, Aria Systems, Fusebill, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subscription Billing Software Market Strategic Shifts
Distributed ledger technologies and real-time data streaming are restructuring how subscription platforms handle trust, transparency, and transaction finality across decentralized subscriber networks.
Blockchain-based subscription verification is decentralizing identity and payment authorization across peer-to-peer billing networks. SaaS providers in media and telecommunications are piloting smart contracts for automated proration and dunning. This architecture is decentralizing trust mechanisms that previously required centralized payment processors, compressing intermediary fee structures.
The EU AI Act imposes algorithmic transparency requirements on automated billing decisions that affect subscriber pricing or service tiers. Platforms must now document and audit machine learning models used for churn prediction and dynamic pricing. European digital media platforms are responding by segregating AI-driven billing functions into explainable rule-based modules.
Enterprise buyers now demand consumption-based contracts with monthly true-up provisions rather than annual commitments with overage penalties. This pattern disrupts traditional SaaS sales compensation structures and forces billing platforms to support daily metering with real-time invoicing. Financial services and API infrastructure sectors in the United States exhibit the most aggressive adoption of this model.
Global Subscription Billing Software Market Segmentation
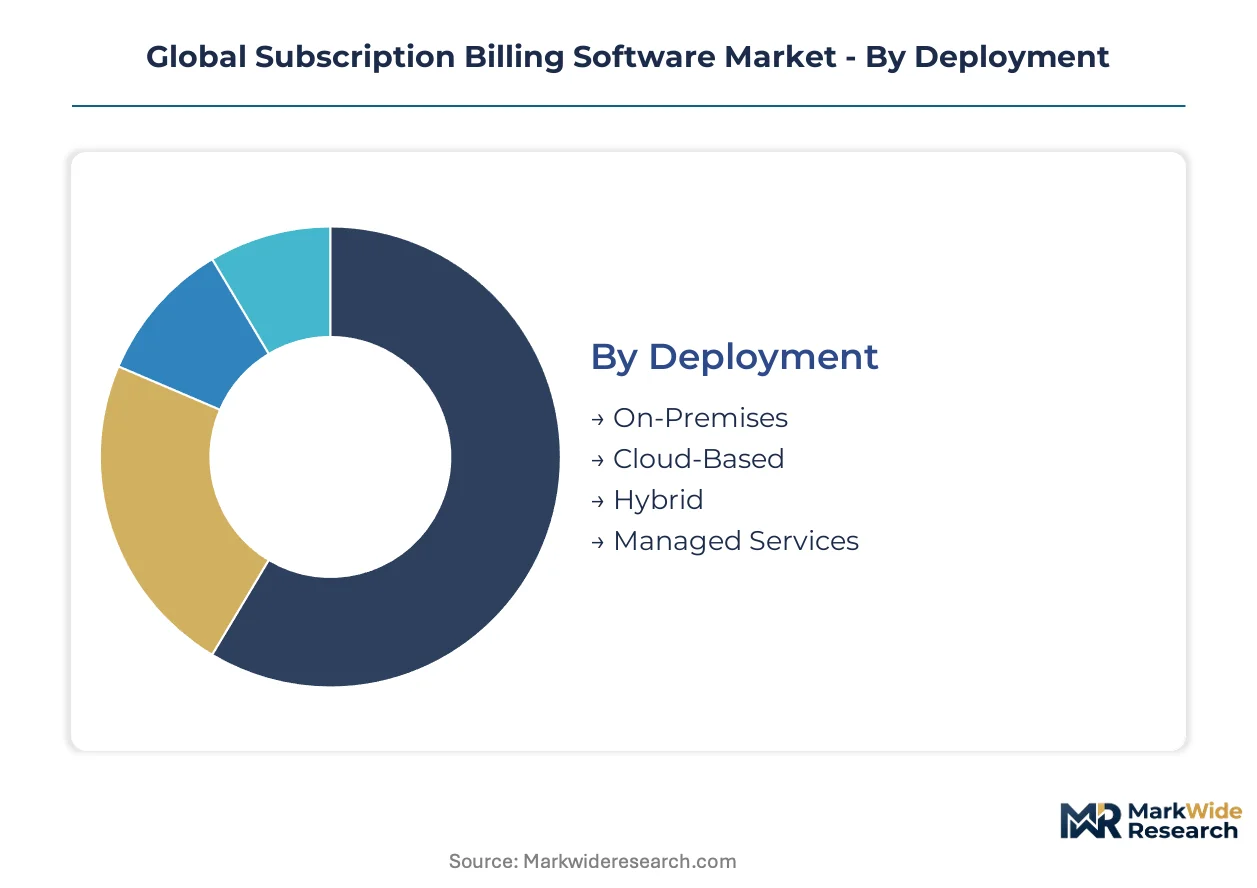
Subscription billing software segments diverge sharply by buyer technical maturity, regulatory exposure, and integration complexity. Deployment mode and payment model choices determine compliance architecture and revenue recognition workflows. Vendor positioning depends on matching segment-specific requirements for scalability, audit trails, and geographic tax automation.
Deployment:
Buyer infrastructure strategy—cloud migration urgency versus data sovereignty constraints—drives deployment selection and implementation timelines.
- On-Premises:Self-hosted installations on enterprise servers with full data control. Financial services firms in Germany and Switzerland favor this mode for GDPR Article 44 cross-border transfer restrictions, accepting higher capital expenditure and maintenance overhead.
- Cloud-Based:Multi-tenant SaaS platforms with elastic scaling and automatic updates. Demand concentrates among mid-market SaaS providers in the United States and India seeking rapid deployment without infrastructure teams; API-first architectures accelerate onboarding.
- Hybrid:Split architectures keeping sensitive payment data on-premises while routing billing logic through cloud orchestration. Healthcare and telecommunications sectors in Japan adopt this for METI data localization guidelines combined with real-time invoicing needs.
- Managed Services:Third-party operated infrastructure with dedicated support and compliance management. Resource-constrained enterprises in Brazil and Mexico leverage this to bypass internal DevOps hiring gaps while meeting ANVISA and local tax authority requirements.
Volume sits with Cloud-Based; growth tilts toward Hybrid as data sovereignty regulations harden across European and Asia-Pacific jurisdictions.
End User:
Organizational scale dictates feature depth, with procurement complexity and compliance mandates escalating nonlinearly across employee thresholds.
- Large Enterprises:Complex multi-entity billing with ASC 606 and IFRS 15 revenue recognition automation. Fortune 500 technology and media companies in the United States demand dedicated customer success teams and custom SLA terms.
- SMEs:Standardized subscription management with pre-built integrations for CRM and accounting platforms. Mid-market SaaS vendors across Germany and France prioritize localized tax engines and multi-currency support without enterprise implementation cycles.
- Startups:Low-code configuration and rapid time-to-first-invoice. Venture-backed software companies in India and Singapore select platforms with free tiers and automatic scaling to minimize burn rate.
- Freelancers:Individual practitioner tools with simple recurring invoice generation and payment link distribution. Creative professionals and consultants in Canada and Australia favor mobile-first interfaces with minimal setup friction.
Revenue concentrates with Large Enterprises; subscriber expansion accelerates fastest among Startups as venture funding stabilizes.
Payment Model:
Monetization architecture selection determines metering infrastructure requirements and financial reporting complexity.
- Recurring Billing:Fixed-interval subscription charges with automated renewal and dunning management. Traditional SaaS and digital media platforms across the United States and United Kingdom rely on this for predictable cash flow and simplified forecasting.
- One-Time Payment:Single transaction licensing with optional maintenance add-ons. Perpetual software vendors in Germany transitioning to subscription models use this as a bridge to reduce customer friction.
- Usage-Based:Granular consumption metering tied to API calls, data volume, or compute resources. IoT providers and infrastructure-as-a-service companies in Japan and South Korea adopt this for alignment with customer value realization.
- Variable Pricing:Tiered or negotiated rates adjusting to volume commitments or market conditions. Enterprise procurement teams in India and Brazil leverage this for contract flexibility amid currency volatility.
Transaction volume clusters around Recurring Billing; Usage-Based models gain share fastest as API-first businesses proliferate.
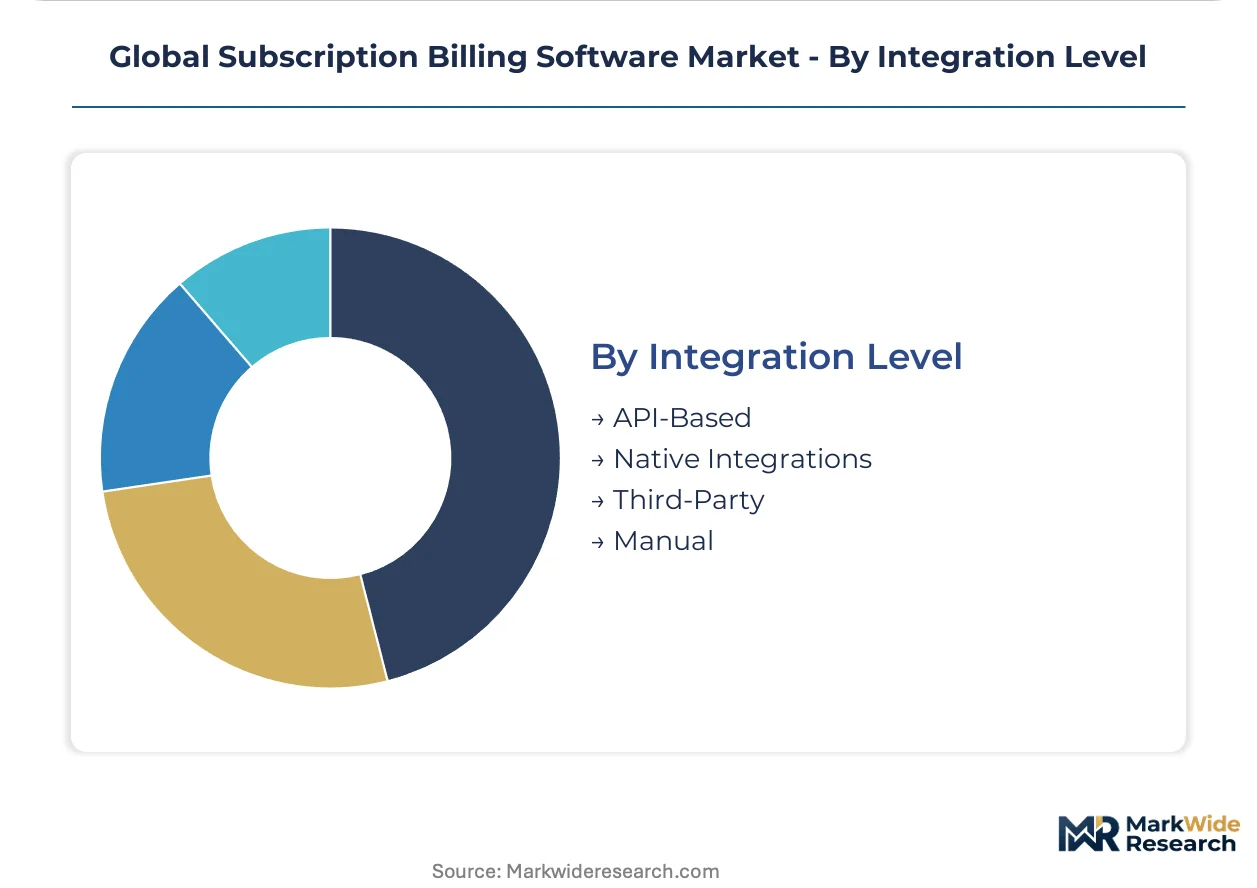
Integration Level:
Technical sophistication and existing software ecosystem density shape integration architecture decisions.
- API-Based:RESTful and GraphQL endpoints enabling custom workflow construction. Developer-centric platforms in the United States and Israel attract engineering-led organizations building embedded finance products.
- Native Integrations:Pre-built connectors for Salesforce, NetSuite, and HubSpot with minimal configuration. Mid-market sales and marketing technology stacks across Australia and Canada standardize on this for rapid deployment.
- Third-Party:Middleware and iPaaS connections bridging legacy ERP and modern billing platforms. Manufacturing and logistics enterprises in Germany and Japan with SAP investments require this for phased modernization.
- Manual:Spreadsheet uploads and CSV imports without system connectivity. Micro-businesses and transitional users in emerging markets tolerate this for zero implementation cost.
Deployment volume favors Native Integrations; API-Based connections expand most quickly as composable enterprise architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure density in Northern Virginia anchors enterprise subscription billing deployment capacity. Data center investment patterns concentrate platform engineering talent within specific metropolitan clusters.
United States
Enterprise SaaS providers in San Francisco and Seattle drive demand for API-first billing orchestration. The SEC enforces revenue recognition disclosure standards that shape platform compliance architecture. Northern Virginia's data center corridor hosts the elastic infrastructure enabling real-time metering for fintech and media platforms.
Germany
Industrial software vendors in Munich and Stuttgart seek hybrid deployment models balancing GDPR Article 44 constraints with cloud scalability. The BSI mandates ISO 27001 certification for federal procurement eligibility. Berlin's startup ecosystem accelerates mid-market adoption of localized tax automation engines.
India
Bengaluru's SaaS unicorns and Mumbai's fintech clusters generate concentrated demand for recurring payment infrastructure. The RBI's recurring payment mandate rules force card-on-file authentication redesigns. Hyderabad's cloud engineering centers support platform localization for GST compliance and multi-currency handling.
Japan
Tokyo-based telecommunications and IoT providers pioneer usage-based metering for connected device fleets. METI data localization guidelines push healthcare and manufacturing toward hybrid architectures. Osaka's enterprise software distributors bridge legacy ERP integrations for phased billing modernization.
United Kingdom
London's financial services technology sector demands consumption-based contracts with daily true-up provisions. The FCA's operational resilience requirements influence vendor selection criteria for critical payment systems. Manchester's emerging SaaS cluster prioritizes rapid deployment over custom implementation cycles.
Global Subscription Billing Software Market Competitive Environment
Global majors compete with regional champions across payment orchestration and tax automation capabilities. The vendor base separates into three tiers: enterprise-grade monetization suites, mid-market subscription platforms, and embedded finance infrastructure providers. Dominant competitive moves include API-first architecture investments and geographic expansion through localized compliance modules.
Within the enterprise monetization tier, Zuora and Oracle Corporation occupy positions emphasizing revenue recognition automation and multi-entity billing complexity. Chargebee exemplifies the mid-market archetype with rapid-deployment subscription management. Stripe anchors the embedded finance convergence, extending billing functionality through developer-centric payment orchestration layers.
| Leading Market Players |
|---|
| Zuora |
| Chargebee |
| Recurly |
| Salesforce |
| SAP |
| Stripe |
| Aria Systems |
| Fusebill |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification requirements gate both qualified supply and premium-tier pricing access, as enterprise procurement teams weight security posture against speed-to-implement in vendor selection. Buyers without certification face exclusion from federal contracts in Germany and Fortune 500 RFP shortlists in the United States, compressing margins for uncertified vendors while anchoring premium pricing for compliant platforms.
Pricing Analysis
Warranty and service-level bundling separates enterprise-grade subscription billing platforms from stripped-down economy offerings, with dedicated customer success teams and custom SLA terms commanding substantial premiums over self-service deployments. Price differentiation hinges on revenue recognition automation depth and geographic tax engine coverage, with ASC 606 and IFRS 15 compliance modules carrying material premiums. Cost compression in mid-market tiers intensifies as Chargebee and Recurly compete on localized tax automation capabilities. Startups and freelancers exhibit highest price sensitivity, gravitating toward free-tier entry points with automatic scaling to minimize burn rate.
Supply Chain Analysis
Reverse-logistics flows for billing platform data center hardware concentrate refurbishment and remanufacturing operations in Taiwan, South Korea, and the United States, where specialized semiconductor recycling facilities process decommissioned server components. Cloud infrastructure supply draws from NVIDIA GPU clusters, Intel Xeon processors, and Samsung memory modules, with single-source vulnerability concentrated in advanced node semiconductor fabrication. Tariff exposure on Chinese-manufactured networking equipment strains cost structures for hardware-dependent hybrid deployments. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels, with AWS Marketplace and Azure Marketplace capturing growing share of mid-market customer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architectures are displacing legacy ERP-integrated billing stacks, as real-time data pipelines and microservices orchestration replace batch-processed invoice generation. This technology transition compresses implementation timelines while fragmenting vendor competitive moats across enterprise and mid-market tiers.
For Market Incumbents: Hedge against embedded finance convergence by deepening payment orchestration capabilities through native developer integrations, as Stripe's billing functionality extension threatens traditional subscription platform margins. Prioritize ISO 27001 certification maintenance and FedRAMP authorization investments to defend federal procurement eligibility against emerging compliance-focused challengers. Expand revenue recognition automation depth to capture ASC 606 implementation bottlenecks that strain enterprise client accounting teams.
For New Entrants and Emerging Players: The price-point gap between premium enterprise suites and economy self-service tiers creates white-space opportunity for mid-market platforms with rapid-deployment localization. Target Brazil and Mexico's underpenetrated SaaS markets with ANVISA-compliant managed service offerings, bypassing internal DevOps hiring gaps that constrain enterprise adoption. Pursue vertical-specific tax automation in India and Germany as the primary go-to-market wedge, leveraging RBI mandate redesigns and GDPR Article 44 constraints that delay incumbent platform adaptation.
For Investors and Strategic Acquirers: RBI recurring payment mandate enforcement acceleration is the leading indicator that card-on-file authentication workflow specialists will command acquisition premiums. Long-term viability favors platforms with hybrid deployment architecture capabilities, as data sovereignty regulations harden across European and Asia-Pacific jurisdictions. Monitor EU AI Act algorithmic transparency enforcement patterns for early signals of compliance-driven vendor consolidation in automated billing decision systems.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | RESTful and GraphQL endpoints enable embedded finance convergence across developer ecosystems. |
| Geographic Expansion via Localization | ANVISA and GST compliance modules unlock Brazilian and Indian mid-market SaaS procurement. |
| Acquisition of Specialist Firm | Revenue recognition automation expertise addresses ASC 606 implementation bottlenecks for enterprise clients. |
| Strategic Partnership | Hyperscaler marketplace listings compress customer acquisition costs for cloud-native deployments. |
| Product Launch | Usage-based metering capabilities capture IoT provider demand for granular consumption tracking. |
Study Parameters
Independent corroboration across platform engineering leads, enterprise IT procurement officers, SaaS CFOs, and integration specialists underwrites the qualitative findings in this study. Primary interviews with billing software vendors, channel partners, and implementation consultants combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie platform adoption data, and regulatory filing databases established demand-side and supply-side ground truth. Bottom-up deployment mode segmentation triangulated against top-down regional cloud infrastructure investment patterns.
Comparable-period anchoring to historical subscription billing adoption curves calibrated the forecast window against prior SaaS monetization platform diffusion rates. The analytical framework modeled deployment mode, organization size, payment model architecture, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR enforcement intensity, RBI mandate implementation pace, and API-first platform proliferation rates. Forecast inputs included real-time metering infrastructure deployment data and revenue recognition automation module attach rates.
Inputs from platform vendors and enterprise implementers were available through the study window; gaps in private company pricing disclosure and unannounced product roadmap commitments introduce uncertainty bands around competitive positioning assessments. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cloud migration velocity. Practitioners should monitor EU AI Act algorithmic transparency audit requirements and METI data localization guideline expansion for early signals of compliance-driven architectural shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Data Mining Software Market
Software & Services
Test Automation Market
Software & Services
Global Electronic Design Automation Tools (EDA) Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Application Server Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Product Analytics Software Market
Software & Services
Software Testing Company Market
Software & Services
Global Presentation Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Data Integration Software/Tool Market
Software & Services
North America IT Services Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
HSM-As-A-Service Market