
 IT Asset Management (ITAM) Software Market | 2026-2036
IT Asset Management (ITAM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
IT Asset Management (ITAM) Software Market Intelligence
Market Context
Platform licensing revenue is fragmenting across modular subscription tiers and consumption-based metering. ServiceNow leverages workflow automation to anchor enterprise IT service management suites that embed asset tracking. Ivanti competes through unified endpoint management that converges ITAM with security operations. IBM sustains mainframe-era client relationships by extending mainframe asset governance into hybrid cloud estates.
Technical Definition and Segment Structure
IT Asset Management (ITAM) Software comprises systems that inventory, track, and optimize hardware and software assets across discovery, procurement, deployment, maintenance, and disposal phases, typically employing agent-based or agentless scanning protocols to maintain configuration management databases. Cloud-based deployment leads solution type adoption as organizations retire on-premises data centers, while software license management commands premium pricing due to vendor audit exposure and compliance penalties. The BFSI industry focus generates outsized demand because Basel III operational risk frameworks and SEC cybersecurity disclosure rules mandate precise asset lineage documentation.
Regulatory Environment and Outlook
ISO 19770-1 software asset management standards, the EU's CSRD sustainability reporting requirements, and HIPAA security rule provisions for covered entities collectively shape product roadmaps by mandating automated discovery, encryption status verification, and end-of-life tracking. The EU AI Act adds algorithmic inventory obligations that ITAM platforms must accommodate. Stakeholders should monitor how NIS2 directive scope expansion reclassifies ITAM from cost-center tooling to regulated critical infrastructure.
Market Dynamics
The IT Asset Management Software market is compressing procurement cycles as zero-trust mandates force federal agencies and healthcare networks to maintain real-time visibility into every endpoint, cloud instance, and software license across distributed estates.
Growth Catalysts
- DORA compliance deadlines:EU financial institutions must implement automated asset discovery and audit trails by January 2025, creating immediate procurement urgency for governance platforms that map critical ICT third-party dependencies.
- Agentless scanning protocols:Cloud-native discovery tools eliminate deployment friction in containerized environments, accelerating adoption among DevOps teams managing ephemeral infrastructure across multi-tenant Kubernetes clusters.
- United States federal zero-trust mandates:OMB memorandum M-22-09 requires civilian agencies to inventory all hardware and software assets with continuous verification, driving consolidated ITAM-ITSM procurement decisions.
Market Restraints
- SaaS subscription cost accumulation:Modular pricing across discovery, license optimization, and workflow modules creates budget unpredictability for mid-market enterprises with limited ITAM dedicated headcount.
- Data residency fragmentation:Divergent national cloud sovereignty laws in Germany, France, and China force vendors to maintain region-segregated infrastructure, inflating operational overhead and complicating unified dashboard delivery.
- Legacy CMDB entrenchment:Decades-old configuration management databases in Fortune 500 enterprises resist migration, creating integration tax that slows cloud-native platform displacement.
Strategic Opportunities
- Algorithmic inventory obligations:EU AI Act Article 52 requires documentation of AI system training data lineage and model versions, extending ITAM scope into MLOps asset tracking for regulated deployers.
- India's digital public infrastructure:UIDAI and NPCI expansion creates demand for ITAM solutions that trace biometric device fleets and payment terminal hardware across state-level health and welfare programs.
- FinOps convergence:Cloud cost optimization platforms are merging with ITAM discovery engines, enabling unified visibility into software license consumption and infrastructure spend for hybrid cloud estates.
Industry Challenges
- ITAM-Security operations skill scarcity:Organizations struggle to hire professionals who bridge asset governance with vulnerability management, particularly for OT-IT convergence in critical infrastructure sectors.
- Multi-cloud API heterogeneity:Disparate discovery interfaces across AWS, Azure, and GCP require continuous connector maintenance, straining vendor engineering resources and creating coverage gaps in asset visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Asset Management (ITAM) Software Market |
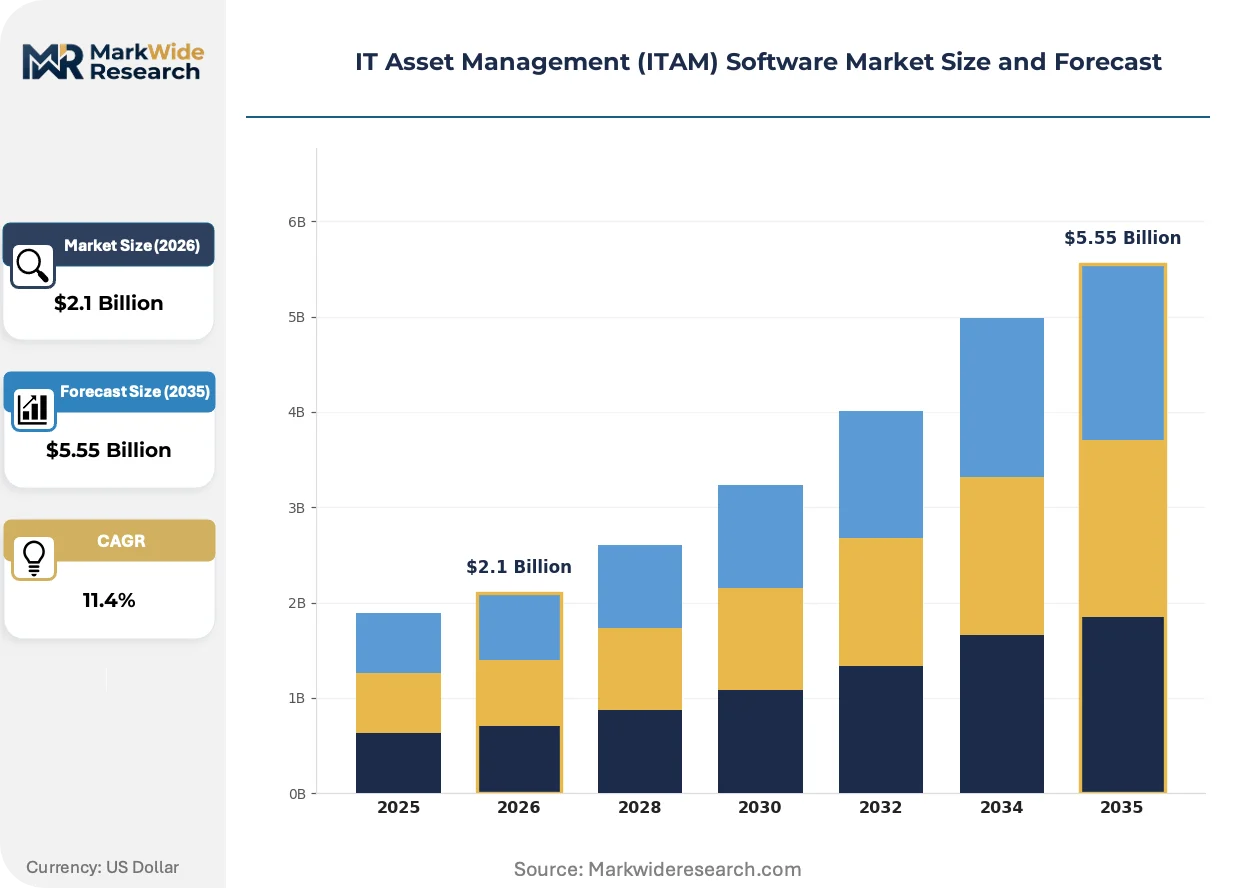
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Services Solution Type: Software Discovery, Software License Management, Hardware Asset Management, IT Procurement Management, Contract Management Use Case: Compliance Management, Cost Optimization, Security & Risk Mitigation, Inventory Tracking, Lifecycle Management, Performance Monitoring Industry Focus: BFSI, Telecommunications, Government Agencies, Manufacturing, Education, Energy & Utilities |
| Companies Covered | Ivanti, Asset Panda, ServiceNow, Snipe-IT, NinjaOne, IBM, Asset Infinity, Atera, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Asset Management (ITAM) Software Market Strategic Shifts & Innovations
Automated discovery engines are expanding beyond traditional endpoints to encompass IoT sensors, medical devices, and industrial control systems, compressing the definition of what constitutes a managed asset.
Graph-based dependency mapping is digitizing the relationships between software components, cloud services, and third-party APIs. Financial services institutions in London and Singapore are deploying these tools to satisfy DORA and MAS operational resilience requirements. The technology is digitizing how compliance teams visualize systemic risk concentrations across their technology supply chains.
CSRD sustainability reporting mandates in the European Union now require documented end-of-life tracking for all ICT hardware. Asset disposition workflows must capture carbon footprint data and circular economy metrics. German automotive and French luxury goods manufacturers are retrofitting ITAM platforms with e-waste chain-of-custody modules to satisfy auditor scrutiny.
Subscription unbundling is fragmenting how enterprises acquire ITAM capabilities. Buyers increasingly procure discovery, normalization, and optimization functions from separate vendors rather than accepting monolithic suites. This pattern is most pronounced in the United States healthcare sector, where specialized software license management tools displace bundled offerings from incumbent ITSM providers.
IT Asset Management (ITAM) Software Market Segmentation
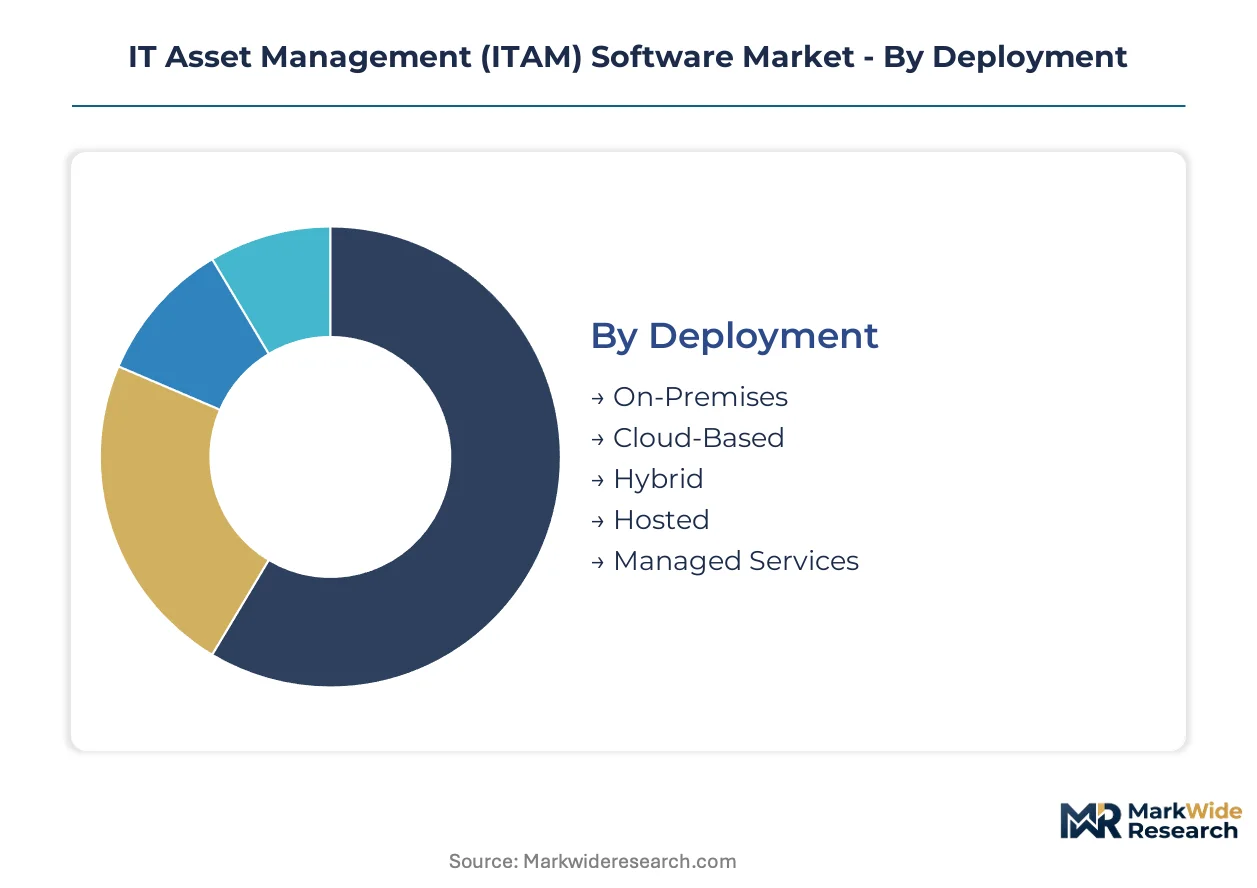
ITAM software segmentation reflects divergent buyer maturity levels and compliance burdens across deployment architectures, solution types, and industry verticals. Procurement patterns cluster around cloud-native capabilities in financial services while federal agencies retain legacy hybrid configurations.
Deployment:
Mature on-premises installations coexist with emerging serverless architectures as organizations navigate data sovereignty constraints.
- On-Premises:Legacy data center installations maintain air-gapped asset registries for classified environments and defense contractors subject to CMMC requirements. Demand concentrates in United States federal agencies and defense industrial base suppliers where export-controlled technical data mandates physical infrastructure control.
- Cloud-Based:Multi-tenant SaaS platforms deliver elastic discovery capacity for ephemeral container workloads and serverless functions. Financial services institutions in London and Singapore prioritize these deployments to satisfy DORA and MAS operational resilience timelines without capital expenditure commitments.
- Hybrid:Split architectures preserve sensitive asset data on-premises while extending discovery to public cloud estates. Manufacturing conglomerates with OT-IT convergence requirements favor this model for industrial control system segmentation.
- Hosted:Single-tenant dedicated instances address data residency mandates in Germany, France, and Switzerland where banking regulators prohibit multi-tenant co-location.
- Managed Services:Outsourced ITAM operations transfer license optimization and audit defense to third-party specialists. Mid-market enterprises without dedicated SAM teams contract these services to manage Microsoft and Oracle vendor negotiations.
Cloud-Based deployments retain volume leadership; Managed Services holds the steepest expansion curve.
Solution Type:
Cost tier differentiation separates premium license optimization modules from standardized discovery tooling.
- Software Discovery:Automated scanning protocols inventory installed applications across endpoints, servers, and cloud instances. Agentless discovery tools gain traction among DevOps teams managing Kubernetes clusters where traditional agent deployment fails.
- Software License Management:Entitlement reconciliation engines compare purchased rights against actual consumption to identify true-up exposure and shelfware. BFSI procurement teams prioritize these capabilities given SEC cybersecurity disclosure rules and Basel III operational risk frameworks.
- Hardware Asset Management:Physical device tracking spans procurement, deployment, maintenance, and disposition workflows. CSRD sustainability reporting requirements in the European Union now mandate carbon footprint capture at end-of-life for all ICT hardware.
- IT Procurement Management:Purchase order integration and vendor catalog management streamline acquisition processes. Healthcare systems implementing zero-trust architectures deploy these tools to maintain continuous asset verification from procurement through retirement.
- Contract Management:Entitlement storage and renewal alert systems prevent lapsed maintenance agreements. Telecommunications operators with distributed infrastructure portfolios use these capabilities to manage multi-year enterprise agreements across regional subsidiaries.
Software License Management commands premium pricing; Software Discovery shows the most rapid adoption velocity among cloud-native enterprises.
Use Case:
Application priority varies by organizational stress — compliance deadlines versus cost pressure versus security incidents.
- Compliance Management:Automated audit trail generation and regulatory mapping satisfy ISO 19770-1, HIPAA, and EU AI Act documentation requirements. EU financial institutions facing DORA deadlines drive concentrated demand for ICT third-party dependency mapping.
- Cost Optimization:License reharvesting, SaaS subscription rationalization, and cloud spend attribution eliminate redundant expenditure. Manufacturing enterprises with thin IT margins prioritize these capabilities to defend procurement budgets.
- Security & Risk Mitigation:Vulnerability correlation with asset ownership and encryption status verification support zero-trust implementation. United States federal agencies under OMB M-22-09 mandates require continuous verification of every hardware and software asset.
- Inventory Tracking:Real-time configuration management database maintenance provides foundational visibility for service management integration. Education institutions with dispersed campus environments deploy these capabilities to manage bring-your-own-device proliferation.
- Lifecycle Management:Stage-gate workflows govern procurement, deployment, maintenance, refresh, and disposition decisions. German automotive manufacturers retrofit these modules with e-waste chain-of-custody tracking for CSRD auditor scrutiny.
- Performance Monitoring:Asset health telemetry and utilization analytics inform refresh timing and capacity planning. Energy and utilities operators with critical infrastructure obligations integrate these signals with SCADA monitoring systems.
Compliance Management dominates current procurement urgency; Cost Optimization demonstrates the strongest expansion trajectory as recessionary pressures persist.
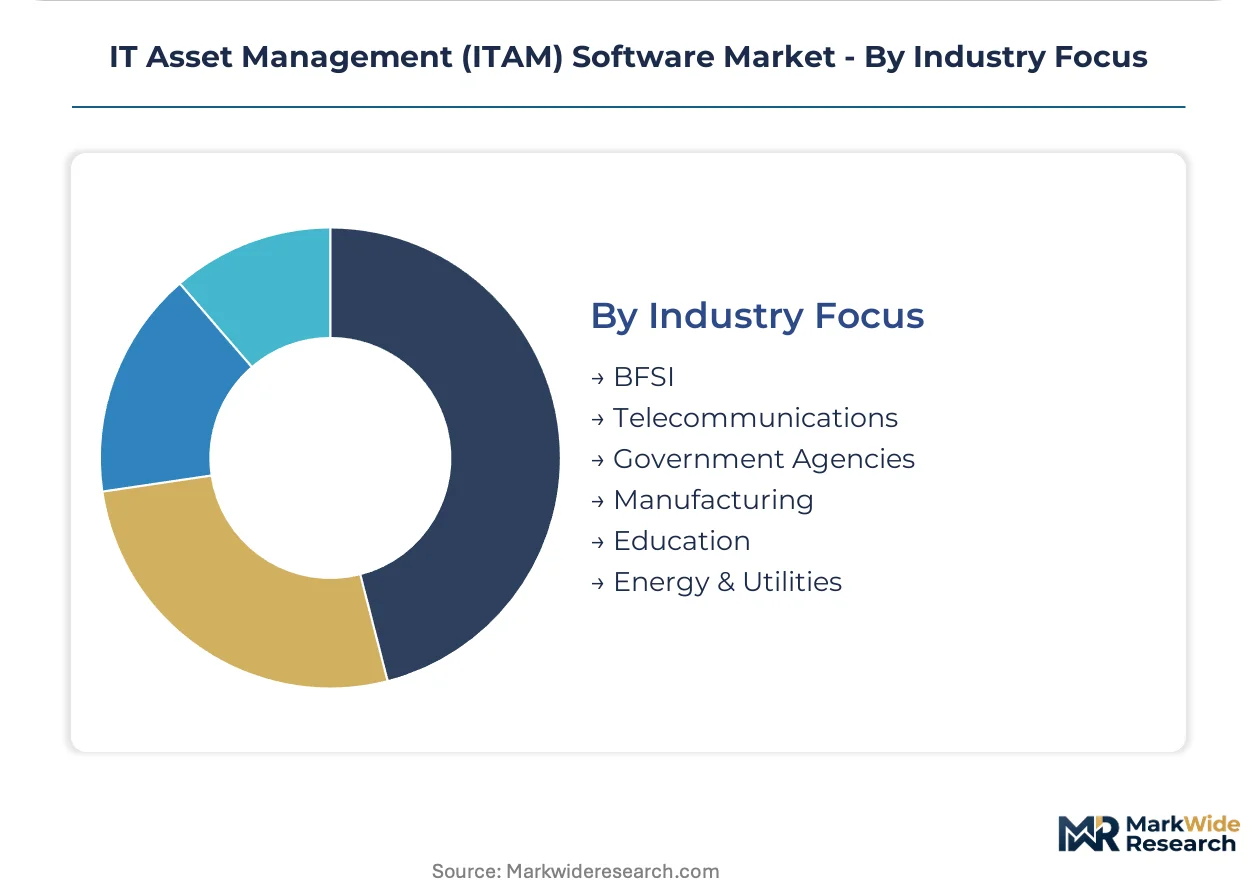
Industry Focus:
Customer type concentration maps directly to regulatory intensity and asset complexity.
- BFSI:Basel III operational risk frameworks, SEC cybersecurity disclosure rules, and DORA compliance deadlines create simultaneous pressure for precise asset lineage. London and Singapore financial centers generate outsized demand for graph-based dependency mapping tools.
- Telecommunications:Distributed infrastructure portfolios spanning cell towers, data centers, and customer premises equipment require scalable discovery architectures. 5G network rollouts expand managed asset populations exponentially.
- Government Agencies:Zero-trust mandates and classified environment requirements sustain hybrid deployment preferences. United States civilian agencies consolidate ITAM-ITSM procurement decisions under OMB direction.
- Manufacturing:OT-IT convergence and industrial IoT sensor proliferation extend ITAM scope beyond traditional endpoints. German and Japanese automotive manufacturers lead CSRD hardware sustainability tracking adoption.
- Education:Dispersed campus environments and student device diversity challenge centralized asset governance. State university systems in the United States balance open access policies with cybersecurity insurance requirements.
- Energy & Utilities:Critical infrastructure designation under NIS2 and similar frameworks elevates ITAM to regulated operational technology. European grid operators and North American pipeline operators face converged IT-OT asset management mandates.
BFSI retains revenue concentration; Energy & Utilities exhibits the most accelerated regulatory-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources concentrate disproportionately in the United States, United Kingdom, and Germany where enterprise software development ecosystems mature alongside stringent regulatory compliance cultures. These three markets generate the majority of platform R&D investment and anchor cloud-native ITAM deployment patterns.
United States
Civilian federal agencies under OMB M-22-09 mandates drive consolidated ITAM-ITSM procurement decisions with continuous verification requirements. HIPAA security rule provisions compel large healthcare systems to maintain precise hardware and software asset lineage. Silicon Valley vendors and Washington DC-area systems integrators dominate cloud-native solution deployment for zero-trust architectures.
United Kingdom
London financial centers generate concentrated demand for graph-based dependency mapping tools satisfying operational resilience requirements. The Financial Conduct Authority's operational resilience rules mandate ICT third-party dependency documentation by March 2025. Edinburgh and Manchester technology clusters specialize in SaaS delivery models for mid-market enterprises.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg retrofit ITAM platforms with e-waste chain-of-custody modules for CSRD auditor scrutiny. The national banking regulator prohibits multi-tenant co-location, forcing hosted single-tenant deployments. Frankfurt financial institutions prioritize automated audit trail generation for Basel III operational risk frameworks.
India
UIDAI and NPCI expansion creates demand for ITAM solutions tracing biometric device fleets across state-level health programs. The RBI's operational resilience guidelines for financial institutions mandate asset governance documentation. Bangalore and Hyderabad technology corridors anchor offshore development centers for global ITAM vendors.
Singapore
Monetary Authority of Singapore operational resilience requirements accelerate procurement for cloud-native discovery platforms. The city-state's data center concentration supports multi-tenant SaaS delivery across Southeast Asian financial institutions. Fintech clusters in the Central Business District deploy agentless scanning for containerized workloads.
IT Asset Management (ITAM) Software Market Key Industry Players
Enterprise workflow platforms and specialized endpoint management vendors split the market between integrated suites and modular best-of-breed solutions. Consolidation pressure intensifies as buyers demand unified visibility across ITAM, ITSM, and security operations functions. Two strategic archetypes dominate: horizontal platform extenders embedding asset tracking within broader service management workflows, and vertical specialists converging ITAM with unified endpoint management or mainframe governance. Competitive moves center on API ecosystem expansion and FinOps capability integration.
Within the platform extender tier, ServiceNow and IBM occupy positions representing contrasting heritage strategies—cloud-native workflow automation versus mainframe-era client relationship extension. Ivanti exemplifies the convergence archetype, unifying endpoint management with security operations. These three vendors anchor competitive dynamics as buyers evaluate whether integrated suites or specialized modules better serve hybrid cloud estate complexity.
| Leading Market Players |
|---|
| Ivanti |
| Asset Panda |
| ServiceNow |
| Snipe-IT |
| NinjaOne |
| IBM |
| Asset Infinity |
| Atera |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure provisioning in the United States, United Kingdom, and Germany concentrates margin pools in SaaS delivery tiers rather than perpetual license models. Platform vendors extract value through consumption-based metering modules that scale with enterprise asset volumes, while professional services margins compress under automation pressure.
Pricing Analysis
After-sales revenue from managed services and audit defense retainers drives lifetime value beyond initial subscription bookings. Three-tier pricing structure across enterprise, mid-market, and SMB levels segments buyers by integration complexity and compliance burden. Pricing pressure stems from modular unbundling as specialized discovery tools displace monolithic suites. Mid-market enterprises exhibit highest price sensitivity due to limited dedicated ITAM headcount, while BFSI institutions prioritize audit readiness over cost minimization.
Supply Chain Analysis
Upstream feedstock from hyperscaler infrastructure providers in the United States, Ireland, and Singapore anchors cloud-native ITAM delivery. Engineering talent pipelines in Bangalore and Hyderabad support offshore development centers, while Frankfurt and London data centers address EU data residency mandates. Supply chain risk centers on single-source vulnerability for AI-powered discovery engines trained on proprietary asset datasets. Distribution runs through direct enterprise sales teams and systems integrator partnerships with regional specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as federal agencies and healthcare systems consolidate ITAM-ITSM procurement decisions under zero-trust mandates, fragmenting vendor pricing autonomy.
For Market Incumbents: Pre-empt displacement by cloud-native entrants through backward integration into FinOps cost optimization engines and API ecosystem expansion. Defend against modular unbundling by embedding graph-based dependency mapping as core platform capability rather than premium add-on. Prioritize certification investment for ISO 19770-1 compliance automation to maintain BFSI anchor accounts.
For New Entrants and Emerging Players: Build out agentless scanning protocols for Kubernetes and serverless environments where legacy agent deployment fails. Target India's digital public infrastructure programs tracing biometric device fleets across state health programs. Pursue channel partnerships with hyperscaler marketplaces for frictionless procurement discovery.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as containerized infrastructure reduces per-customer provisioning costs. Long-term viability favors platforms converging ITAM with security operations and MLOps asset tracking. Monitor DORA compliance deadline acceleration as signal for European financial services procurement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified ITAM-ITSM-FinOps visibility satisfies OMB M-22-09 continuous verification mandates. |
| Acquisition of Specialist Firm | Graph-based dependency mapping capabilities address DORA and MAS operational resilience requirements. |
| Strategic Partnership | Hyperscaler marketplace listings accelerate procurement discovery for cloud-native enterprises. |
| Product Launch | AI system inventory modules capture EU AI Act algorithmic documentation obligations. |
| Geographic Expansion | Single-tenant hosted instances satisfy German banking regulator data residency prohibitions. |
Research Approach
Initial hypotheses were tested against primary input from CIOs, IT procurement officers, SAM practitioners, and DevOps platform engineers and refined through secondary validation. Primary fieldwork encompassed structured interviews across financial services, healthcare, and federal agency verticals. Secondary sources included SEC filings, hyperscaler capex disclosures, and regulatory implementation guidance from EU supervisory authorities. Bottom-up deployment model sizing and top-down enterprise software spending analysis were triangulated for coherence.
Demand-supply balance across cloud infrastructure provisioning and engineering talent availability shaped the analytical framework. Segmentation dimensions modeled encompassed deployment architecture, organization size, vertical compliance intensity, and regional regulatory cluster. CAGRs were derived from installation base expansion rates and annual recurring revenue per account trajectories. Forecast inputs incorporated DORA compliance deadline acceleration and zero-trust mandate implementation timelines.
Sensitivities concentrate around regulatory deadline shifts, hyperscaler pricing volatility, and AI Act scope expansion. Forecasts reflect assumptions regarding cloud migration velocity and modular procurement acceptance. Cross-checking against vendor earnings call commentary and federal IT spending disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Device As a Service (Daas) Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Trade Management Software Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Digital Signage Market
Digital Solutions
Global Online Classifieds Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
US Digital Twin Market