
 Business Spend Management (BSM) Software Market | 2026-2036
Business Spend Management (BSM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Business Spend Management (BSM) Software Market Analysis
North American cloud infrastructure expansion is reshaping how finance teams deploy procurement technology. SAP Concur leverages its enterprise travel and expense heritage to sustain dominance in Fortune 500 accounts. Coupa anchors its position through deep supplier network effects across manufacturing verticals. Ramp competes aggressively on speed-to-implement for mid-market firms seeking real-time spend controls.
Business Spend Management Software comprises integrated cloud-native and on-premise platforms that automate procurement workflows, enforce policy compliance, and analyze enterprise expenditure patterns through API-connected data pipelines. These systems centralize purchase orders, supplier invoices, employee reimbursements, and contract spend into unified dashboards for CFOs and procurement officers. Cloud-based deployment leads adoption as IT teams prioritize zero-maintenance SaaS architectures over legacy server installations. Expense management and spend analysis represent the fastest-growing solution categories as organizations seek granular visibility into tail spend and maverick purchasing behavior.
US enterprises navigate SOX compliance requirements and SEC disclosure rules that mandate auditable spend trails and internal control documentation. European adopters face GDPR constraints on supplier data processing plus CSRD sustainability reporting obligations that extend to Scope 3 emissions tracking through procurement systems. Procurement leaders must evaluate whether native AI capabilities or partner ecosystems deliver superior predictive analytics for supplier risk and price benchmarking.
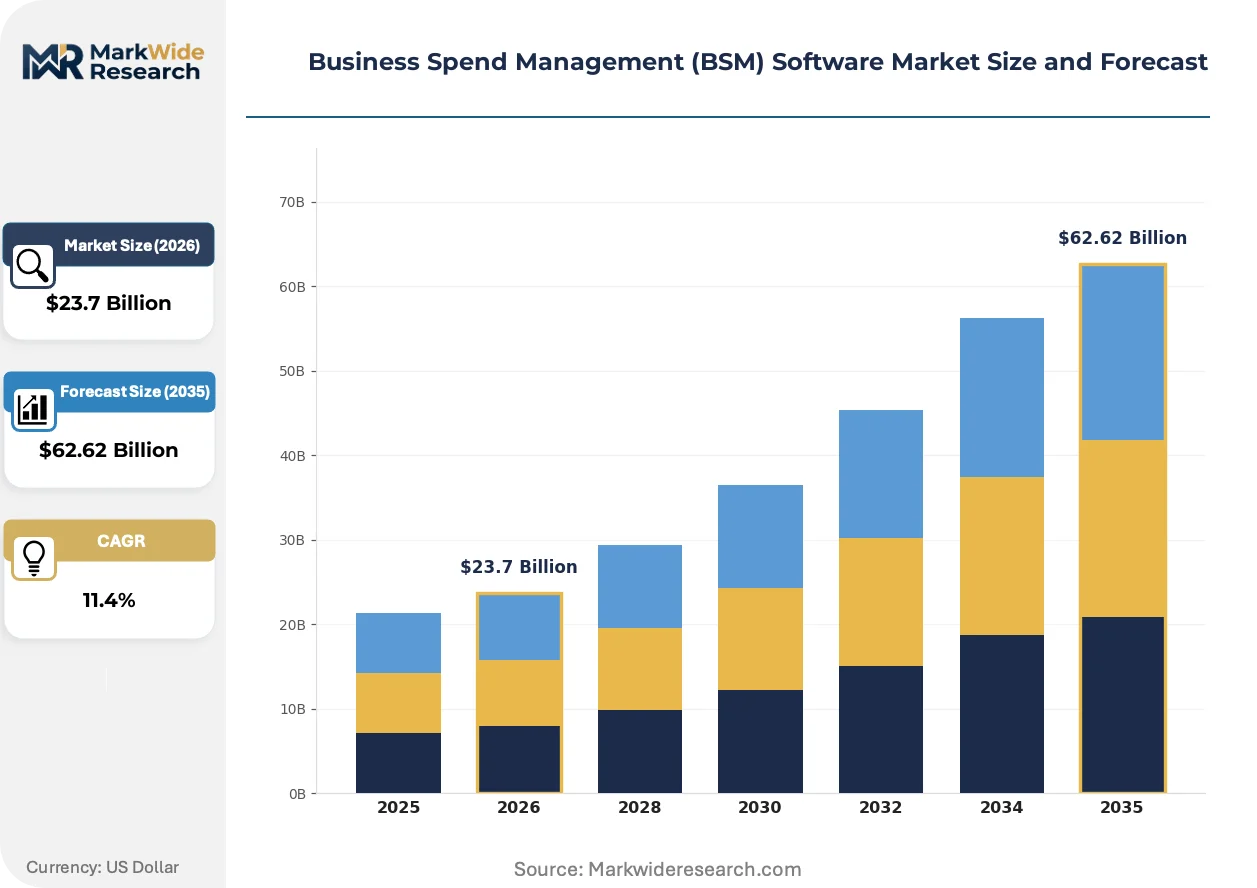
Market Dynamics
AI-powered spend analytics is compressing procurement decision cycles from months to days, forcing CFOs to abandon legacy ERP modules that cannot deliver real-time visibility into indirect expenditure patterns.
Growth Catalysts
- CSRD sustainability mandates:European enterprises must track Scope 3 emissions through procurement systems, creating mandatory demand for carbon-aware spend platforms that integrate supplier environmental data.
- Manufacturing supplier network effects:Dense ecosystems of tier-one and tier-two suppliers in German automotive and industrial machinery clusters accelerate platform adoption through mandatory electronic invoicing requirements.
- API-first architecture:Cloud-native data pipelines enable instant synchronization between procurement workflows, accounting systems, and banking rails, eliminating manual reconciliation bottlenecks that plagued on-premise deployments.
Market Restraints
- GDPR compliance friction:Cross-border supplier data processing requires expensive legal review and technical safeguards, slowing platform rollouts for multinational enterprises with complex vendor footprints.
- Legacy system entrenchment:Decades-old SAP and Oracle ERP installations in Fortune 500 accounts create switching costs that extend implementation timelines and dilute SaaS migration ROI.
- Technical talent scarcity:Shortage of procurement-technology specialists who combine finance domain expertise with API integration skills restricts deployment velocity for mid-market buyers.
Strategic Opportunities
- India's PLI scheme beneficiaries:Electronics and pharmaceutical manufacturers receiving production-linked incentives require spend management platforms to document domestic value-add for compliance audits.
- Embedded finance convergence:Integration of corporate card issuance, virtual accounts, and automated reconciliation within procurement workflows creates new revenue streams for platform vendors.
- United Kingdom post-Brexit procurement reform:New public sector buying regulations mandate transparent supplier performance tracking, opening government and NHS contract opportunities for compliant BSM providers.
Industry Challenges
- Multi-entity consolidation complexity:Enterprises with dozens of legal entities across jurisdictions struggle to harmonize chart-of-accounts structures and approval hierarchies within unified platforms.
- Supplier onboarding friction:Manual KYC verification and banking detail validation for thousands of vendors creates bottlenecks that delay realized savings from negotiated contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Spend Management (BSM) Software Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Service End User: SMEs, Large Enterprises, Government Agencies, Non-Profit Organizations Solution Type: Procurement Management, Expense Management, Invoice Management, Spend Analysis Industry Vertical: Retail, Manufacturing, Healthcare, Technology |
| Companies Covered | Airbase, Brex, SAP Concur, Spendesk, Pleo, Coupa, Ramp, Payhawk, BILL Spend & Expense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Spend Management (BSM) Software Market Emerging Trajectories
Generative AI is rewriting how procurement teams interact with spend data, replacing static dashboards with conversational interfaces that surface anomalies and recommendations through natural language queries.
Machine learning-based invoice matching is hybridizing traditional optical character recognition with semantic understanding of contract terms, enabling three-way matching between purchase orders, receipts, and supplier invoices without human intervention. Mid-market finance teams in professional services and technology sectors are adopting these capabilities fastest, compressing month-end close cycles from ten days to under seventy-two hours. The structural consequence is collapsing demand for offshore business process outsourcing centers that previously handled manual data entry.
CSRD sustainability disclosure rules in Europe are mandating granular emissions tracking through procurement systems, extending reporting obligations to Scope 3 indirect emissions from supplier networks. Industrial manufacturers in Germany and chemical processors in Belgium face the steepest compliance burdens, retrofitting existing platforms with carbon calculation engines or switching to native ESG-capable alternatives. The regulatory pressure is spawning new certification categories for procurement carbon accountants and supplier sustainability auditors.
Self-service purchasing portals are displacing traditional requisition workflows, empowering department managers to execute spot buys within pre-authorized guardrails without procurement team involvement. Healthcare systems in the United States and United Kingdom are leading this shift, unbundling purchasing authority to clinical units while maintaining spend controls through real-time budget visibility. The behavioral change reduces cycle times for non-strategic purchases from weeks to hours but requires sophisticated policy engines to prevent maverick spending leakage.
Business Spend Management (BSM) Software Market Segmentation
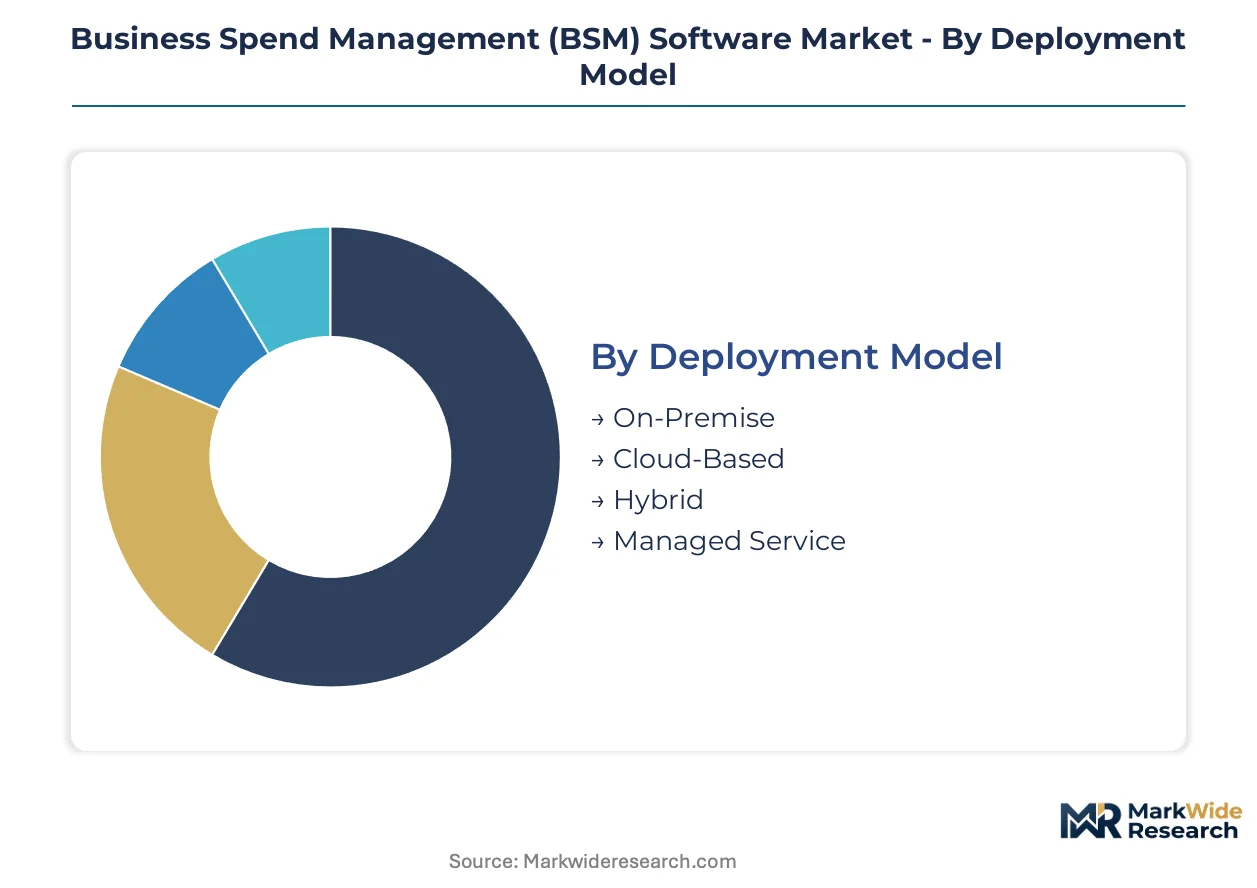
BSM software segmentation reveals how deployment preferences, organizational scale, and industry-specific compliance requirements fragment purchasing criteria across buyer cohorts. Procurement leaders evaluate platforms through divergent lenses: IT teams prioritize integration architecture, CFOs demand real-time analytics, and compliance officers scrutinize audit trails.
Deployment Model:
Use-case spectrum spans legacy ERP-dependent multinationals requiring data sovereignty to cloud-native startups seeking zero-maintenance SaaS economics.
- Cloud-Based:Multi-tenant SaaS architectures with API-native connectivity to banking rails and accounting systems dominate new procurement. United States mid-market firms in professional services verticals drive fastest adoption, prioritizing seventy-two-hour implementation windows over customization depth.
- On-Premise:Single-tenant installations behind corporate firewalls serve defense contractors and financial institutions with classified data requirements. German automotive manufacturers with proprietary supplier networks maintain these deployments despite higher total cost of ownership.
- Hybrid:Split architectures keep sensitive spend data on-premise while routing transactional workflows through cloud interfaces. Healthcare systems in the United Kingdom adopt this model to balance NHS data residency rules with remote clinical purchasing needs.
- Managed Service:Third-party operated platforms with dedicated infrastructure and support staff appeal to resource-constrained SMEs. India's PLI scheme beneficiaries in electronics manufacturing leverage these deployments to accelerate compliance documentation without internal IT expansion.
The dominant share belongs to Cloud-Based deployments, while Hybrid configurations are closing the gap fastest among regulated industries.
End User:
Organizational scale dictates platform complexity, with procurement maturity and compliance burden varying sharply across entity types.
- Large Enterprises:Global implementations spanning hundreds of legal entities require multi-currency, multi-entity consolidation with sophisticated approval hierarchies. Fortune 500 manufacturers in the United States prioritize supplier risk analytics and carbon tracking capabilities for CSRD-aligned disclosure.
- SMEs:Rapid deployment templates with pre-configured workflows and limited customization address constrained implementation budgets. United Kingdom professional services firms adopt these platforms to automate expense reimbursement without dedicated procurement staff.
- Government Agencies:Public sector procurement regulations mandate transparent supplier performance tracking and competitive bidding documentation. United States federal contractors navigate FAR compliance requirements through specialized BSM modules.
- Non-Profit Organizations:Grant-funded entities require donor-restricted spend tracking and programmatic budget allocation. German development NGOs leverage these capabilities to satisfy Bundesministerium audit requirements for public funding.
Large Enterprises command the revenue concentration, though SME adoption is expanding most quickly as self-service onboarding reduces sales friction.
Solution Type:
Functional specialization reflects where procurement pain points concentrate across the source-to-pay lifecycle.
- Spend Analysis:AI-powered pattern recognition and anomaly detection transform raw transaction data into actionable procurement intelligence. United States CFOs prioritize these tools for tail spend visibility and maverick purchasing identification.
- Expense Management:Corporate card integration, receipt capture, and automated reimbursement workflows compress month-end close cycles. Technology sector adopters in Germany lead deployment velocity, eliminating manual reconciliation bottlenecks.
- Procurement Management:Requisition-to-purchase order workflows with catalog management and supplier onboarding anchor strategic sourcing operations. Manufacturing verticals with dense supplier networks require these capabilities for electronic invoicing compliance.
- Invoice Management:Three-way matching automation between purchase orders, receipts, and supplier invoices eliminates manual data entry. Belgium chemical processors adopt machine learning-based solutions to handle high-volume, complex contract terms.
Expense Management holds the installed base leadership, while Spend Analysis is gaining share fastest as AI capabilities mature.
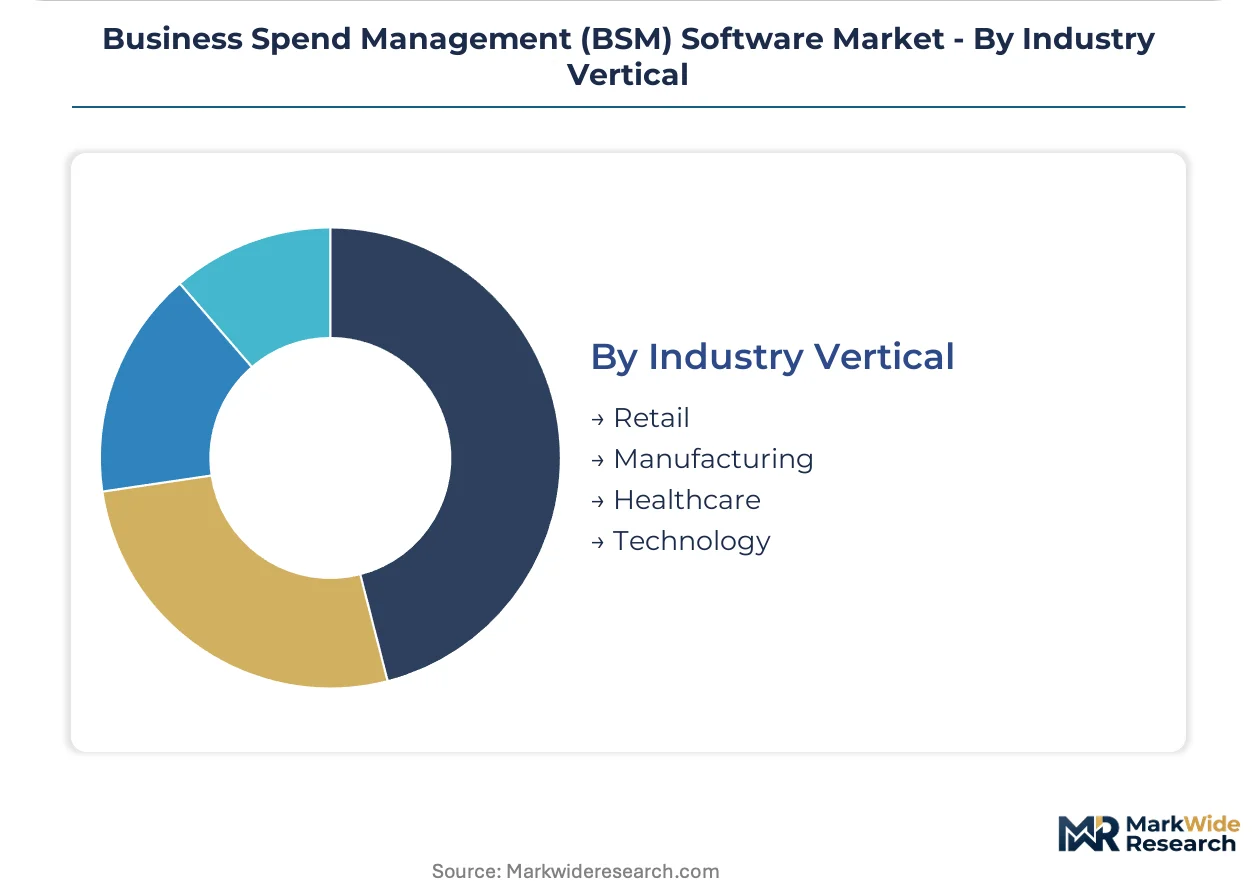
Industry Vertical:
Sector-specific regulatory and operational requirements shape platform configuration priorities and integration complexity.
- Manufacturing:Supplier network density, quality certification tracking, and materials cost volatility demand robust procurement orchestration. German automotive clusters mandate electronic data interchange integration for tier-one supplier compliance.
- Healthcare:Clinical procurement autonomy, pharmaceutical traceability, and patient data protection create unique workflow requirements. United States hospital systems balance physician purchasing authority with infection control and formulary compliance.
- Technology:Rapid scaling, distributed workforces, and cloud infrastructure spending patterns favor agile, API-first platforms. Software companies in the United Kingdom prioritize real-time budget visibility for project-based resource allocation.
- Retail:Seasonal demand fluctuations, private label sourcing, and margin compression drive demand for predictive analytics. Omnichannel operators require inventory-aware procurement to synchronize online and physical store replenishment.
Manufacturing retains the deepest penetration, though Healthcare is climbing fastest as post-pandemic supply chain resilience investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States enterprises prioritize real-time spend visibility for SOX compliance, while European adopters embed carbon tracking for CSRD disclosure. Indian manufacturers leverage BSM platforms to document domestic value-add for PLI scheme audits.
United States
Fortune 500 manufacturers and healthcare systems drive demand for AI-powered spend analytics and automated invoice matching. SEC disclosure rules and SOX mandates require auditable spend trails with internal control documentation. Boston's biotech cluster and Houston's energy corridor anchor adoption, with CFOs prioritizing supplier risk dashboards for indirect spend visibility.
Germany
Automotive and industrial machinery manufacturers mandate electronic invoicing compliance across dense tier-one supplier networks. CSRD sustainability reporting obligations extend to Scope 3 emissions tracking through procurement systems. Stuttgart's automotive cluster and Munich's industrial technology corridor lead platform deployment for carbon-aware supplier management.
United Kingdom
Post-Brexit procurement reform mandates transparent supplier performance tracking for government and NHS contracts. Professional services firms in London adopt rapid-deployment expense management to automate reimbursement without dedicated procurement staff. The Southeast technology corridor accelerates API-first platform adoption for real-time budget visibility.
India
Electronics and pharmaceutical manufacturers receiving PLI scheme incentives require spend management platforms to document domestic value-add for compliance audits. DGFT regulations and RBI oversight shape cross-border payment workflows. Bangalore's technology cluster and Hyderabad's pharmaceutical corridor drive managed service deployments to accelerate compliance documentation.
France
Industrial manufacturers and luxury goods houses integrate carbon calculation engines for CSRD-aligned supplier sustainability disclosure. ANSM and CNIL oversight shapes pharmaceutical and data processing compliance requirements. Paris-based headquarters operations and Lyon's chemical processing cluster anchor demand for multi-entity consolidation capabilities.
Business Spend Management (BSM) Software Market Vendor Landscape
Capability concentration sits with established enterprise suites; scale advantage sits with cloud-native challengers. The market structures around three tiers: legacy ERP-integrated incumbents, API-first mid-market specialists, and vertical-focused expense management disruptors. Dominant competitive moves include supplier network expansion through electronic invoicing mandates and embedded finance convergence integrating corporate card issuance with procurement workflows.
Within the enterprise heritage tier, SAP Concur and Coupa exemplify scale-driven positions anchored in Fortune 500 travel-expense and manufacturing procurement workflows. Ramp occupies the velocity-focused archetype, competing on implementation speed for mid-market firms seeking real-time spend controls. Airbase represents the integrated finance convergence pattern, combining corporate card programs with automated reconciliation within unified platforms.
| Leading Market Players |
|---|
| Airbase |
| Brex |
| SAP Concur |
| Spendesk |
| Pleo |
| Coupa |
| Ramp |
| Payhawk |
| BILL Spend & Expense |
| Others |
Supply Flow & Price Mechanics
Frankfurt-Dubai cloud infrastructure corridors transmit SaaS deployment costs across tier-one data centers, concentrating platform delivery economics in Germany and the United Arab Emirates while compressing margins for mid-market vendors competing on implementation speed.
Pricing Analysis
Long-term enterprise subscription contracts anchor pricing for Fortune 500 deployments, while spot-based transactional tiers serve mid-market buyers seeking per-invoice economics. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and AI capability depth. Cost compression in the standard tier intensifies because API-native challengers undercut legacy ERP-integrated suites. SMEs exhibit highest price sensitivity, deferring procurement automation until self-service onboarding reduces implementation labor costs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days strain cash conversion for implementation partners serving the United States, Germany, and United Kingdom markets. Cloud infrastructure draws from hyperscaler facilities in Virginia, Frankfurt, and London, while specialized AI talent feeds from Bangalore and Tel Aviv development centers. Single-source vulnerability concentrates in banking API providers that gate payment rail access. Distribution runs through direct enterprise sales teams with overlay channel partners penetrating mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in CSRD compliance tooling as European manufacturers retrofit procurement systems for carbon accounting, creating vertical specialization niches that generalist platforms cannot address.
For Market Incumbents: Insulate core enterprise accounts by embedding supplier network lock-in through mandatory electronic invoicing mandates that raise switching costs. Acquire carbon calculation engine specialists to neutralize ESG-native challengers before CSRD deadlines harden procurement requirements. Prioritize API ecosystem control as the defensive lever against mid-market velocity players. For New Entrants and Emerging Players: India's PLI scheme compliance documentation represents the most penetrable white-space target, as electronics manufacturers lack internal IT capacity for spend audit trails. Target managed service deployment models to accelerate time-to-value without implementation friction. Lead with pre-configured domestic value-add reporting templates that satisfy DGFT audit requirements. For Investors and Strategic Acquirers: AI-powered invoice matching specialists with manufacturing vertical penetration present the most compelling acquisition archetype for platform consolidation. Long-term viability hinges on embedding finance convergence capabilities that capture interchange revenue streams. Watch for inflection when corporate card issuance volumes exceed traditional procurement transaction values in mid-market accounts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native connectivity to SAP and Oracle ERP installations accelerates Fortune 500 migration timelines. |
| Acquisition of Specialist Firm | Carbon calculation engine providers extend CSRD compliance capabilities into Scope 3 emissions tracking. |
| Strategic Partnership | Banking rail partnerships with JPMorgan and Stripe embed corporate card issuance within procurement workflows. |
| Geographic Expansion | United Kingdom NHS procurement reform opens public sector contracts for compliant BSM providers. |
| Product Launch | Conversational AI interfaces replace static dashboards for natural language spend anomaly detection. |
Methodological Framework
Initial hypotheses were tested against primary input from CFOs, procurement officers, platform engineers, and integration specialists and refined through secondary validation against SEC filings, hyperscaler capex disclosures, App Annie deployment data, and GPO procurement databases. Bottom-up segment sizing triangulated against top-down market boundary analysis to constrain variance.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling deployment model, organization size, vertical, and integration complexity dimensions. CAGRs derived from segment-level growth rate reconciliation with aggregate market boundary constraints. AI capability maturity curves and electronic invoicing mandate timelines served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and enterprise software budget cycles would shift the trajectory of SaaS procurement decisions. Forecasts reflect assumptions about regulatory compliance deadlines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software-Defined Machine Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Global Virtualization Software Market
Software & Services
Global Ad Server Software Market
Software & Services
Global Membership Management Software Market
Software & Services
MRP Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Media Planning Software Market
Software & Services
North America Deck Design Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Global Document Management Software Market
Software & Services
Document Capture Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Online Recruitment Software Market