
 IT Operations Management Market | 2026-2036
IT Operations Management Market Size, Share, and Industry Trends Forecast 2026-2036
IT Operations Management Market Insights
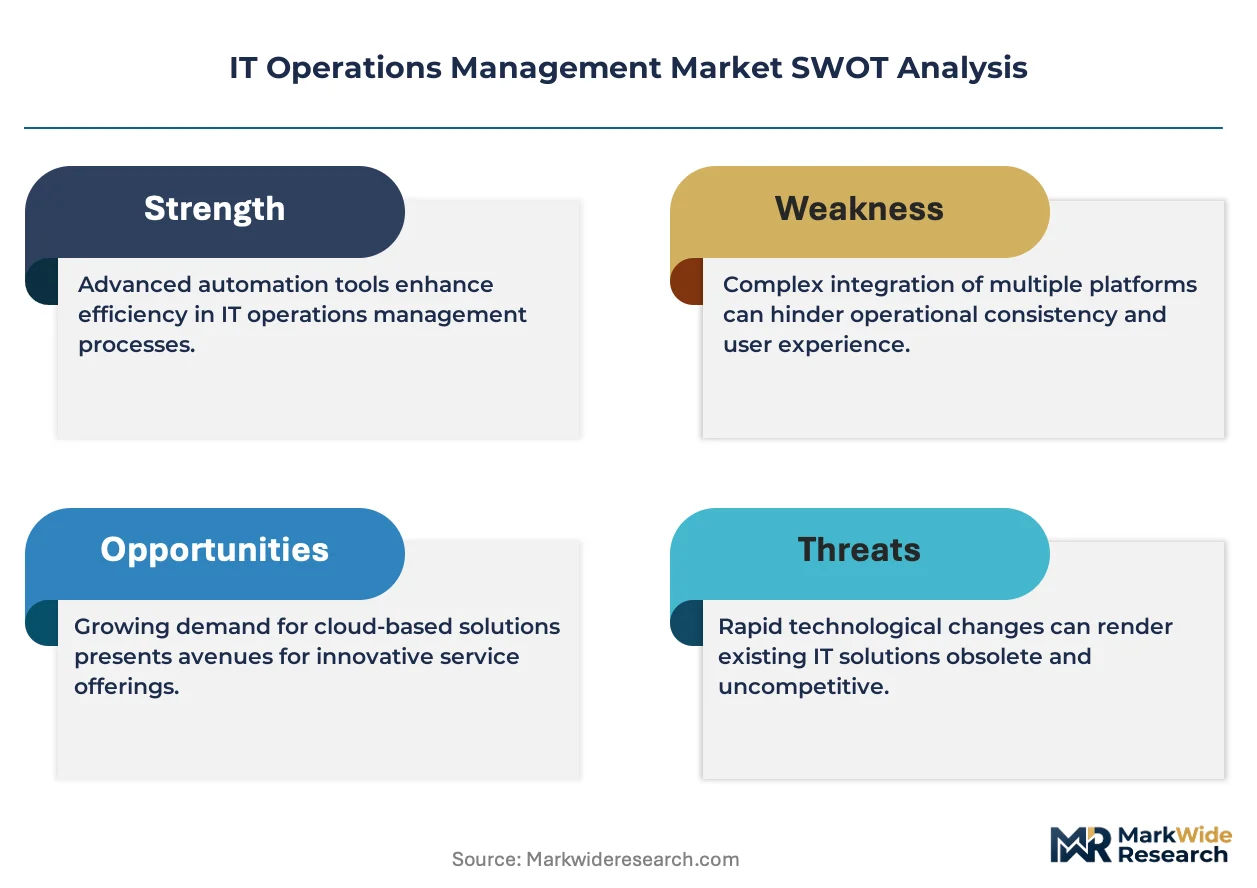
Cloud-native observability stacks are repositioning traditional on-premises monitoring economics. ServiceNow leverages workflow automation to anchor enterprise IT service management contracts across North America. Dynatrace sustains differentiation through its Davis AI engine for full-stack application intelligence. BMC Software competes in mainframe-centric environments where hybrid deployment complexity creates durable account stickiness.
IT Operations Management encompasses the integrated processes, tools, and methodologies used to administer, monitor, and optimize enterprise technology infrastructure, typically leveraging agent-based or agentless data collection with sub-second telemetry granularity and automated remediation playbooks. Its primary commercial purpose is to minimize service downtime, enforce SLA compliance, and reduce mean-time-to-resolution across distributed computing environments. Cloud deployment models now capture the fastest expansion as enterprises migrate workload orchestration to hyperscaler environments. AI/ML technology segments concentrate margin pools where predictive anomaly detection commands premium pricing. Incident Management services retain the largest revenue base due to mandatory 24/7 operational coverage requirements in regulated industries.
NIST cybersecurity frameworks and the EU AI Act impose algorithmic transparency mandates on automated IT operations tooling, forcing vendors to document decision-audit trails. ISO/IEC 20000 service management standards shape procurement qualification criteria for government and healthcare buyers evaluating vendor eligibility. Stakeholders must monitor how evolving cross-border data sovereignty rules affect cloud-hosted observability architectures and customer deployment preferences.
Market Dynamics
AI-driven observability platforms are compressing traditional monitoring economics as financial services firms demand predictive anomaly detection with sub-second telemetry granularity across distributed cloud environments.
Growth Catalysts
- EU AI Act Algorithmic Mandates:Compliance requirements for automated decision-audit trails are accelerating procurement of transparent AI operations tooling across European banking and insurance sectors.
- Hybrid Cloud Orchestration:Enterprise workload migration to hyperscaler environments is expanding demand for cloud-native observability stacks with automated remediation playbooks.
- NIST Cybersecurity Framework:Federal and healthcare buyers in the United States are embedding ISO/IEC 20000 service management standards into vendor qualification criteria.
Market Restraints
- Legacy Mainframe Integration Costs:Hybrid deployment complexity in BMC Software's core accounts creates durable switching costs that also constrain greenfield SaaS adoption.
- Cross-Border Data Sovereignty Rules:Evolving regulations in Germany, Japan, and the United States are fragmenting cloud-hosted observability architectures and complicating multi-tenant platform design.
- Specialized Talent Scarcity:Shortages of Site Reliability Engineers with Davis AI engine expertise limit enterprise deployment velocity for full-stack application intelligence.
Strategic Opportunities
- Japan METI Digital Transformation Incentives:Government-backed infrastructure modernization programs are creating procurement windows for predictive operations platforms in manufacturing and telecommunications.
- Agentless Telemetry Convergence:Integration of eBPF kernel instrumentation with OpenTelemetry standards is opening new deployment paths in security-sensitive government environments.
- Incident Management Service Unbundling:24/7 operational coverage requirements in regulated industries are enabling specialized vendors to carve out premium managed service niches.
Industry Challenges
- Multi-Cloud Observability Fragmentation:Engineering teams struggle to correlate telemetry across AWS, Azure, and Google Cloud environments without unified data models.
- Certification Timeline Compression:Accelerated EU AI Act and NIST compliance deadlines are forcing vendors to re-architect product roadmaps while maintaining service continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Operations Management Market |
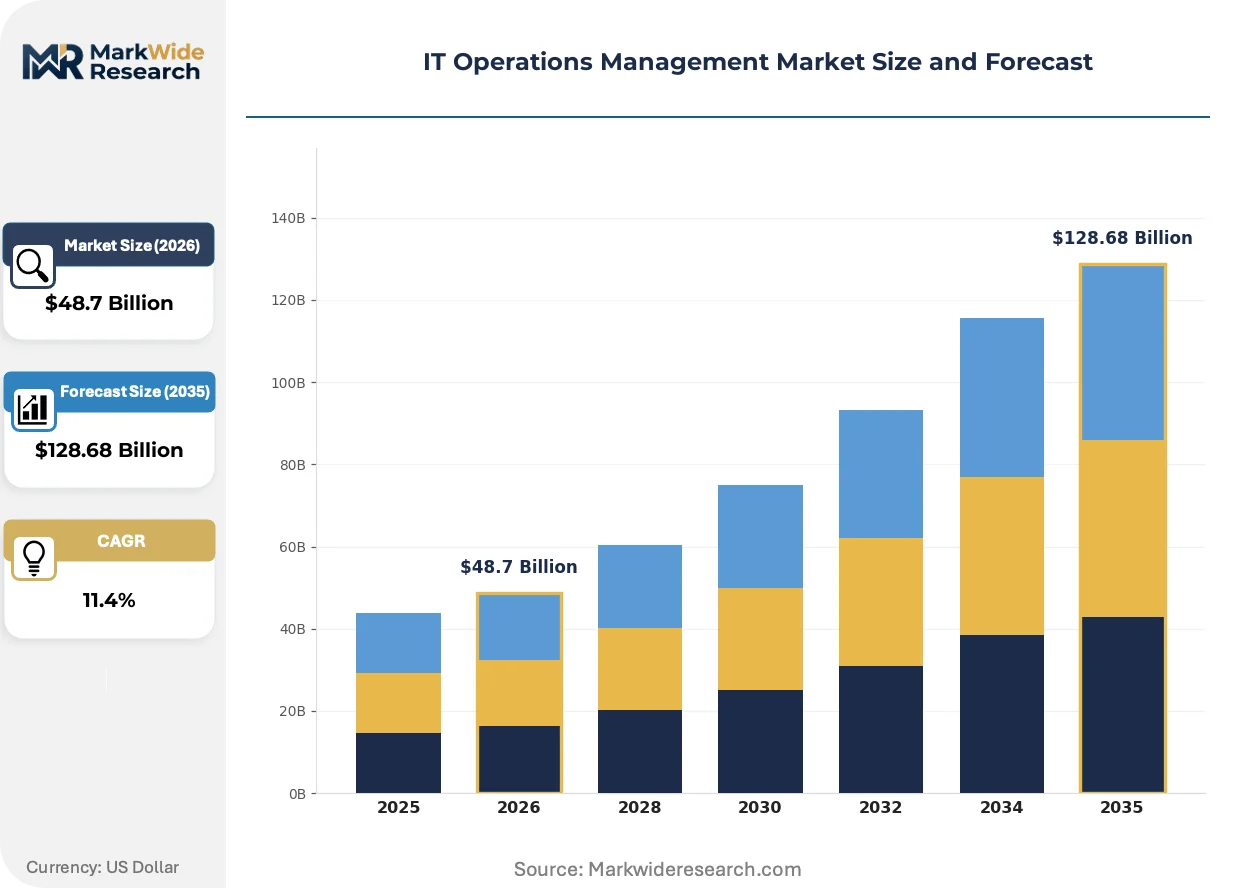
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Managed Service Type: Incident Management, Performance Monitoring, Change Management, Capacity Planning End User: IT Departments, Managed Service Providers, Enterprises, Government Agencies Technology: AI/ML, Automation Tools, Monitoring Solutions, ITSM Software |
| Companies Covered | ServiceNow, Dynatrace, Datadog, Splunk, BMC Software, SolarWinds Worldwide, IBM, Cisco Systems, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Operations Management Market Trends and Innovations
Open-source telemetry standards and kernel-level instrumentation are dismantling proprietary agent economics across enterprise monitoring contracts.
eBPF-based kernel observability is overtaking traditional agent-based data collection in cloud-native environments. Financial services and SaaS providers are deploying these tools at production scale within eighteen-month procurement cycles. This shift is compressing margin pools for legacy monitoring vendors dependent on per-agent licensing models.
The EU AI Act's algorithmic transparency requirements are mandating explainable AI documentation for automated remediation systems. Vendors must now maintain decision-audit trails that satisfy both European regulators and internal risk committees. Banking and healthcare buyers in Germany and France are prioritizing vendors with pre-built compliance tooling over feature-rich alternatives.
Outcome-based platform contracts are displacing seat-based SaaS subscriptions in enterprise IT service management negotiations. Channel partners and direct sales teams are restructuring compensation around mean-time-to-resolution guarantees rather than user count. This transformation is most visible in United States federal contracting and German automotive supplier networks.
IT Operations Management Market Segmentation
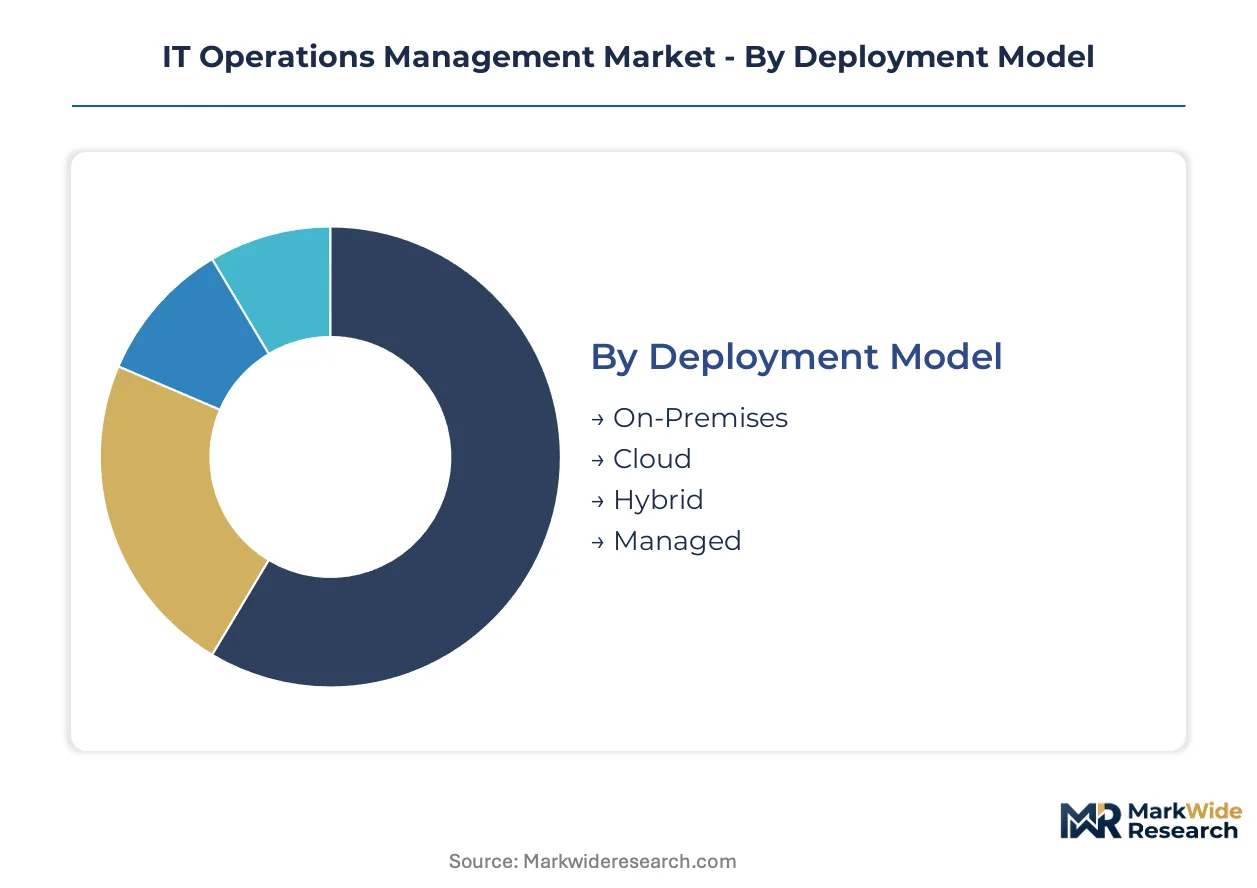
IT Operations Management procurement decisions hinge on deployment architecture, service specialization, and technology sophistication. Buyers segment investments across infrastructure models, operational workflows, and intelligence capabilities to align tooling with legacy constraints and modernization roadmaps.
Deployment Model:
Deployment architecture dictates integration complexity, data sovereignty compliance, and total cost of ownership across enterprise technology estates.
- Cloud:Hyperscaler-native observability stacks deliver auto-scaling telemetry ingestion with sub-second granularity. Financial services firms in the United States and Germany are consolidating procurement around AWS, Azure, and Google Cloud environments to satisfy EU AI Act audit-trail mandates while reducing capital expenditure.
- Hybrid:Workload orchestration spanning on-premises data centers and public cloud environments requires unified control planes with automated remediation playbooks. Manufacturing and telecommunications buyers in Japan leverage METI-backed modernization incentives to fund hybrid transitions without disrupting mainframe-dependent operations.
- On-Premises:Air-gapped deployments in defense and classified government facilities retain mandatory status where cross-border data flows face prohibition.
- Managed:Third-party operational coverage addresses Site Reliability Engineer scarcity through 24/7 incident response commitments in regulated healthcare and banking sectors.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud.
Service Type:
Service specialization correlates directly with operational risk exposure and contractual penalty structures in SLA-governed environments.
- Incident Management:Mandatory round-the-clock coverage for regulated industries commands premium pricing through outcome-based contracts tied to mean-time-to-resolution guarantees. United States federal contractors and German automotive suppliers are unbundling these services from platform subscriptions to secure specialized vendor accountability.
- Performance Monitoring:Full-stack application intelligence with predictive anomaly detection compresses downtime windows in high-velocity SaaS environments. eBPF kernel instrumentation is displacing traditional agent-based collection in cloud-native deployments across financial services.
- Change Management:Automated approval workflows and rollback orchestration reduce deployment failure rates in CI/CD pipelines.
- Capacity Planning:Predictive resource forecasting prevents over-provisioning in elastic cloud environments with volatile workload patterns.
Revenue concentration sits with Incident Management. Technology differentiation is concentrated in Performance Monitoring.
End User:
Buyer organizational structure determines procurement authority, integration requirements, and compliance scope for IT Operations Management tooling.
- Enterprises:Multi-divisional technology estates with heterogeneous infrastructure drive demand for unified observability platforms spanning legacy mainframe and containerized workloads. NIST cybersecurity framework compliance shapes vendor qualification in United States healthcare and federal sectors.
- Managed Service Providers:Multi-tenant platform architectures require granular tenant isolation and cross-customer analytics to deliver differentiated operational services at scale.
- IT Departments:Internal technology organizations prioritize workflow automation integration with existing ServiceNow or BMC ecosystem investments.
- Government Agencies:Sovereign cloud mandates and classified processing requirements impose air-gap and encryption standards beyond commercial specifications.
Procurement volume sits with Enterprises. Contract complexity is concentrated in Government Agencies.
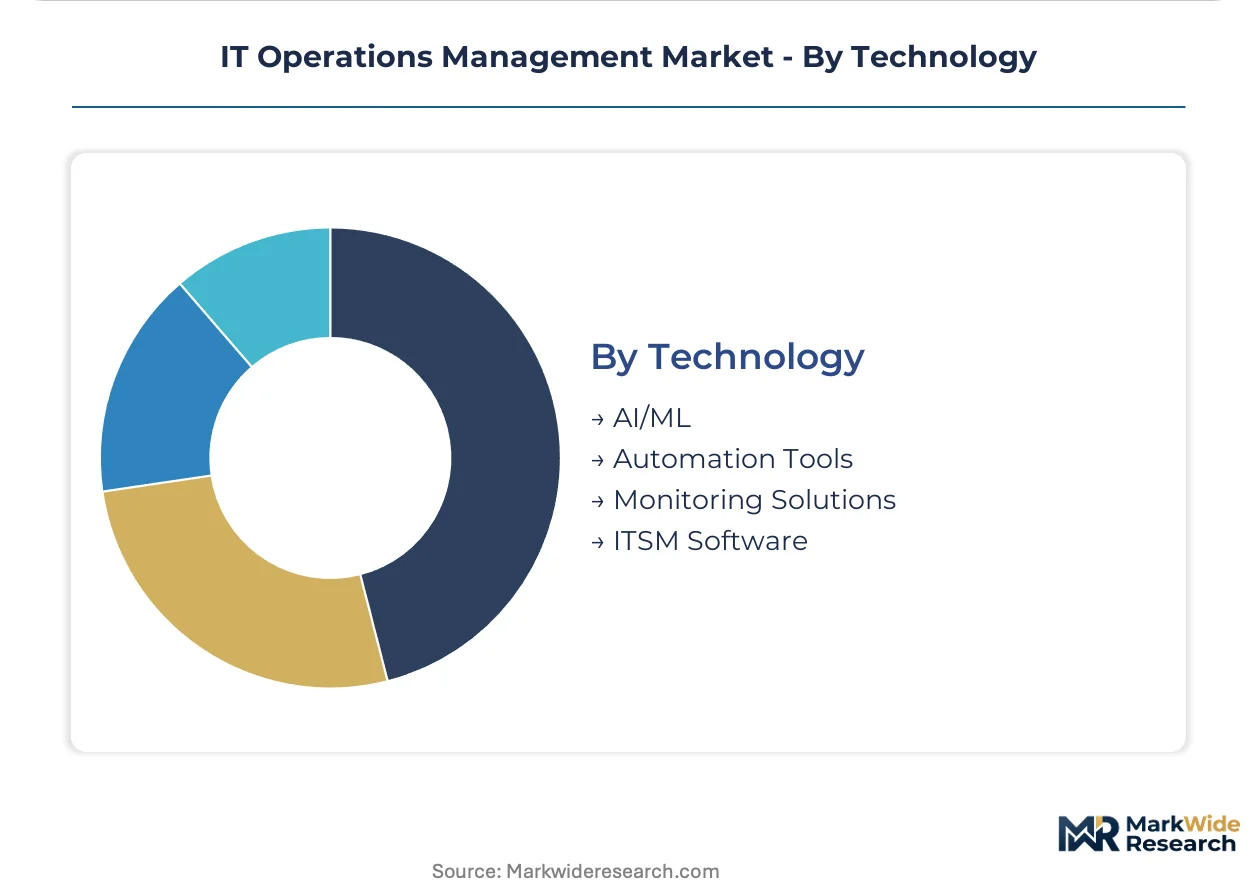
Technology:
Intelligence layer sophistication separates commodity monitoring from premium predictive operations capabilities.
- AI/ML:Explainable anomaly detection with documented decision-audit trails commands pricing premiums under EU AI Act algorithmic transparency mandates. Banking and insurance buyers in France and Germany disqualify vendors lacking pre-built compliance tooling regardless of feature breadth.
- Automation Tools:Self-healing remediation playbooks reduce human intervention for known failure patterns in distributed microservices architectures.
- Monitoring Solutions:OpenTelemetry standardization and eBPF kernel instrumentation are dismantling proprietary agent economics across enterprise contracts.
- ITSM Software:Workflow orchestration platforms anchor enterprise service management with CMDB integration and change advisory board automation.
Margin expansion sits with AI/ML. Standardization pressure is concentrated in Monitoring Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of IT Operations Management tooling concentrates in the United States, Germany, and Japan as financial services and manufacturing sectors modernize legacy infrastructure. NIST cybersecurity frameworks, EU AI Act mandates, and METI digital transformation incentives are reshaping vendor qualification criteria across these markets.
United States
Federal healthcare agencies and defense contractors drive demand for air-gapped observability stacks with NIST-compliant audit trails. The Department of Defense imposes zero-trust architecture mandates on IT service management vendors. Virginia's Dulles Technology Corridor hosts concentrated procurement activity for classified cloud-native monitoring deployments.
Germany
Automotive suppliers and banking consortia prioritize explainable AI tooling that satisfies EU AI Act algorithmic transparency requirements. The Federal Financial Supervisory Authority (BaFin) embeds ISO/IEC 20000 standards into vendor eligibility assessments. Munich and Frankfurt clusters concentrate procurement for predictive anomaly detection platforms in manufacturing and insurance.
Japan
Telecommunications carriers and electronics manufacturers accelerate cloud migration under METI-backed infrastructure modernization programs. The Ministry of Economy, Trade and Industry (METI) subsidizes hybrid observability transitions that preserve mainframe-dependent operations. Tokyo-Osaka industrial corridors dominate procurement for 24/7 incident management services.
United Kingdom
Financial services regulators in London mandate operational resilience frameworks that exceed baseline EU requirements. The Financial Conduct Authority (FCA) enforces strict SLA documentation for automated remediation systems. The City of London and Canary Wharf clusters drive premium pricing for outcome-based platform contracts.
France
Healthcare systems and nuclear energy operators require sovereign cloud observability with CNIL-certified data processing. The National Commission for Information Technology and Civil Liberties (CNIL) imposes encryption standards beyond commercial specifications. Paris-Saclay research clusters incubate specialized vendors for regulated industry deployments.
IT Operations Management Market Competitive Landscape
Platform consolidation dominates the current landscape as workflow automation vendors acquire specialized observability capabilities to anchor enterprise service management contracts. The vendor base separates into three tiers: hyperscaler-integrated platforms, independent full-stack specialists, and legacy mainframe-centric incumbents. Strategic archetypes include AI-first challengers, ecosystem-anchored incumbents, and managed service unbundlers. M&A activity and outcome-based contract restructuring represent the dominant competitive moves reshaping pricing models.
Among ecosystem-anchored incumbents, ServiceNow and BMC Software exemplify divergent positioning strategies. ServiceNow occupies a position within the workflow automation tier where CMDB integration creates durable account stickiness across North American federal contracts. BMC Software represents the mainframe-centric archetype where hybrid deployment complexity generates switching costs that constrain competitive displacement. Dynatrace sits within the AI-native specialist tier, anchoring premium positioning through full-stack application intelligence capabilities. These three entities collectively illustrate how technology differentiation and legacy integration depth determine competitive mobility across procurement segments.
| Leading Market Players |
|---|
| ServiceNow |
| Dynatrace |
| Datadog |
| Splunk |
| BMC Software |
| SolarWinds Worldwide |
| IBM |
| Cisco Systems |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up observability specialists have consolidated fragmented monitoring vendors across North America and Europe, creating pricing discipline through platform bundling while compressing margins for pure-play agent-based tools. This ownership pattern concentrates supply-side negotiation leverage with hyperscaler-aligned platforms and forces legacy vendors into defensive pricing postures.
Pricing Analysis
Volume concentrates in seat-based SaaS subscriptions while margin pools shift toward outcome-based contracts with mean-time-to-resolution guarantees. Price differentiation rests on AI explainability certification under EU AI Act mandates and OpenTelemetry standardization breadth. Cost compression in agent-based licensing is intensifying because eBPF kernel instrumentation dismantles per-node economics. Managed service providers exhibit highest price sensitivity; federal healthcare buyers show lowest due to NIST compliance lock-in.
Supply Chain Analysis
ISO/IEC 20000 and EU AI Act algorithmic transparency certifications gate vendor eligibility for German banking and United States federal procurement channels. Engineering talent concentrates in the United States, Germany, and Japan where Site Reliability Engineer scarcity constrains deployment velocity. Supply chain risk centers on single-source dependency for Davis AI engine expertise and specialized compliance documentation. Distribution runs through hyperscaler marketplaces and systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IT Operations Management sector sits in a technology-transition phase where eBPF-based kernel observability displaces proprietary agent architectures. This substitution pattern reconfigures competitive mobility across procurement segments.
For Market Incumbents: Deploy workflow automation depth to anchor CMDB-integrated service management contracts against AI-native challengers. Consolidate around automated remediation playbooks that satisfy EU AI Act audit-trail mandates. Defensive moves must address hyperscaler marketplace distribution erosion and talent scarcity in full-stack application intelligence.
For New Entrants and Emerging Players: Launch via sovereign cloud partnerships targeting Japan METI-subsidized manufacturing modernization programs. White-space targets include agentless telemetry for security-sensitive government environments and unbundled 24/7 incident management services for German automotive supplier networks. Go-to-market leverage rests on pre-built EU AI Act compliance tooling.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mainframe-centric specialists with durable hybrid deployment switching costs in United States federal accounts. Long-term viability hinges on AI explainability certification moats and OpenTelemetry standardization control. The signal to watch is accelerated outcome-based contract restructuring in healthcare and banking procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CMDB-anchored workflow automation secures multi-year federal healthcare contracts under NIST frameworks. |
| Acquisition of Specialist Firm | eBPF instrumentation capabilities dismantle legacy agent economics in financial services procurement. |
| Geographic Expansion | Japan METI incentive alignment opens manufacturing and telecommunications modernization budgets. |
| Product Launch | Pre-built EU AI Act compliance tooling disqualifies feature-rich competitors in German banking RFPs. |
| Strategic Partnership | Hyperscaler marketplace placement captures cloud-native observability demand in elastic workload environments. |
Research Methodology
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory submission databases formed the secondary backbone for vendor revenue and deployment trend validation. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with bottom-up and top-down triangulation across deployment model, service type, and technology segmentation dimensions.
Bottom-up modeling anchored volume estimates in documented procurement activity while top-down cross-checks validated aggregate market scale across the analysis window. Segmentation dimensions spanned deployment architecture, operational workflow specialization, end-user organizational structure, and intelligence layer sophistication. CAGRs derived from trend extrapolation of cloud migration velocity and AI/ML pricing premium sustainability.
Regulatory deadline acceleration, cross-border data sovereignty rule changes, and Site Reliability Engineer supply constraints are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in EU AI Act enforcement intensity or hyperscaler marketplace commission structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Stylus Pen for Education Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Context Rich Systems Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Global Data Collection and Labeling Market