
 IT Asset Management Market | 2026-2036
IT Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
IT Asset Management Market Insights
The EU Corporate Sustainability Reporting Directive is decoupling IT procurement from pure cost metrics across European enterprises. ServiceNow leverages its integrated platform architecture to anchor cloud-based asset tracking workflows for multinational clients. BMC Software competes through deep mainframe heritage and specialized hardware management modules for regulated industries.
IT Asset Management encompasses the systematic tracking, financial valuation, and lifecycle governance of hardware, software, and network infrastructure across enterprise environments, typically integrating with CMDBs and discovery agents that scan IP-addressable devices at configurable intervals. Its primary commercial purpose is to eliminate shadow IT expenditures, ensure license compliance, and optimize refresh cycles across distributed technology estates. Cloud-based deployment is capturing the fastest expansion as organizations retire on-premises discovery servers, while license management concentrates margin pools due to punitive vendor audit exposure. Government agencies represent a structurally distinct end-user segment where procurement regulations and security classification requirements sustain longer implementation timelines.
The US SEC climate disclosure rules, EU CSRD, and ISO 19770 software asset management standards collectively reshape vendor qualification criteria and enterprise RFP weightings across North America and Europe. SAMR certification requirements in China and BIS IT hardware standards in India add further compliance layers for multinational deployments. Stakeholders must monitor whether sustainability-linked procurement mandates expand from disclosure into binding refresh-cycle regulations.
Market Dynamics
Cloud migration is compressing refresh cycles while EU CSRD mandates force hardware lifecycle emissions disclosure into procurement workflows, fundamentally altering how enterprises value asset longevity against carbon accounting.
Growth Catalysts
- CSRD Disclosure Mandates:The EU Corporate Sustainability Reporting Directive requires granular IT hardware emissions tracking, pulling automated discovery tools into mandatory compliance stacks across European enterprises.
- Container Orchestration:Kubernetes-native asset agents now scan ephemeral cloud workloads at sub-minute intervals, eliminating visibility gaps in multi-tenant environments.
- German Industrial Compliance:Bundesregierung environmental deadlines for machinery OEMs are accelerating sensor-based asset monitoring deployments in manufacturing headquarters.
Market Restraints
- Mainframe Integration Costs:Legacy IBM z/OS environments resist API-based discovery, forcing parallel agent architectures that inflate implementation budgets.
- Silicon Supply Concentration:Taiwan-based chip fabrication bottlenecks delay hardware refresh telemetry, degrading depreciation forecast accuracy.
- SAMR Certification Friction:China's State Administration for Market Regulation mandates local data residency for discovery agents, fragmenting multinational deployment architectures.
Strategic Opportunities
- India BIS Standards Alignment:Bureau of Indian Standards IT hardware certification creates first-mover advantage for vendors embedding automated compliance documentation.
- Edge Device Convergence:5G-connected industrial IoT sensors merging with traditional CMDB feeds unlocks unified asset intelligence for oil and gas field operations.
- ISO 19770-1 Tailwinds:The software asset management standard's 2024 revision elevates automated license reconciliation from best practice to audit defense requirement.
Industry Challenges
- ITAM-Sustainability Skill Fusion:Enterprises lack personnel combining carbon accounting expertise with discovery tool administration, slowing CSRD-ready deployments.
- Multi-Cloud API Drift:AWS, Azure, and GCP release conflicting metadata schemas quarterly, forcing continuous connector redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Asset Management Market |
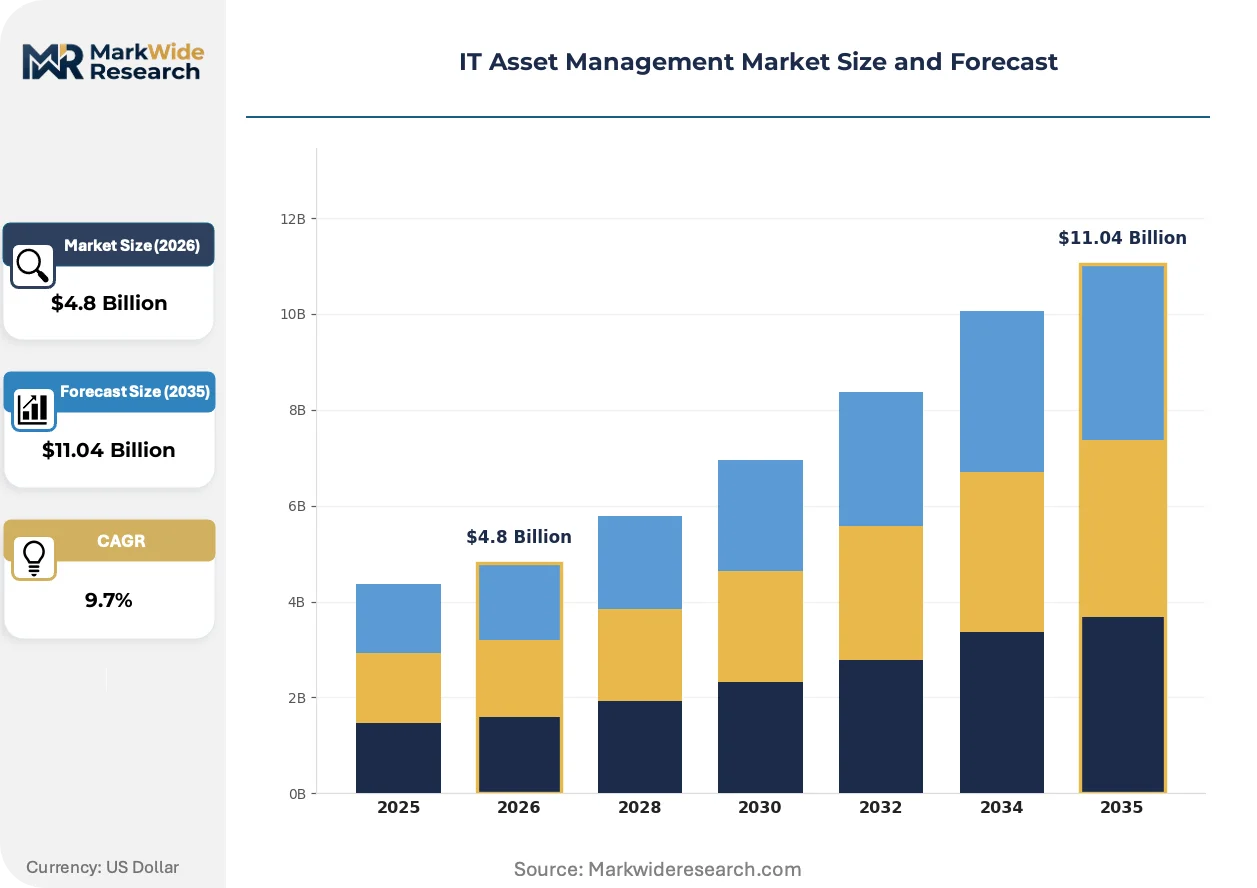
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: IT Departments, Enterprises, SMEs, Government Agencies Solution: Hardware Management, Software Management, License Management, Configuration Management Service Type: Implementation, Consulting, Support, Maintenance |
| Companies Covered | ServiceNow, BMC Software, Ivanti, Flexera, Snow Software, Microsoft, ManageEngine, IBM, Freshworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Asset Management Market Trends and Innovations
Agentless discovery protocols are displacing persistent endpoint software, while sustainability-linked financing instruments tie hardware procurement to verified lifecycle emissions data.
Agentless network scanning using passive traffic analysis is electrifying asset visibility in zero-trust environments. Financial services firms deploy these tools across SWIFT-connected infrastructure within 90-day windows. The technology is electrifying competitive differentiation for vendors eliminating endpoint performance overhead.
REACH substance restrictions on critical raw materials in IT hardware are forcing OEMs to redesign server chassis for recyclability traceability. Component-level material passports must now integrate with asset management platforms for EU market access. German automotive suppliers face the steepest compliance timelines, accelerating blockchain-based provenance tracking adoption.
Subscription-based discovery pricing is displacing perpetual license models in mid-market accounts. Managed service providers bundle asset tracking with FinOps dashboards, capturing procurement decision-making authority from internal IT teams. This shift concentrates most rapidly in Netherlands and Nordics markets where outsourcing penetration already exceeds continental averages.
IT Asset Management Market Segmentation
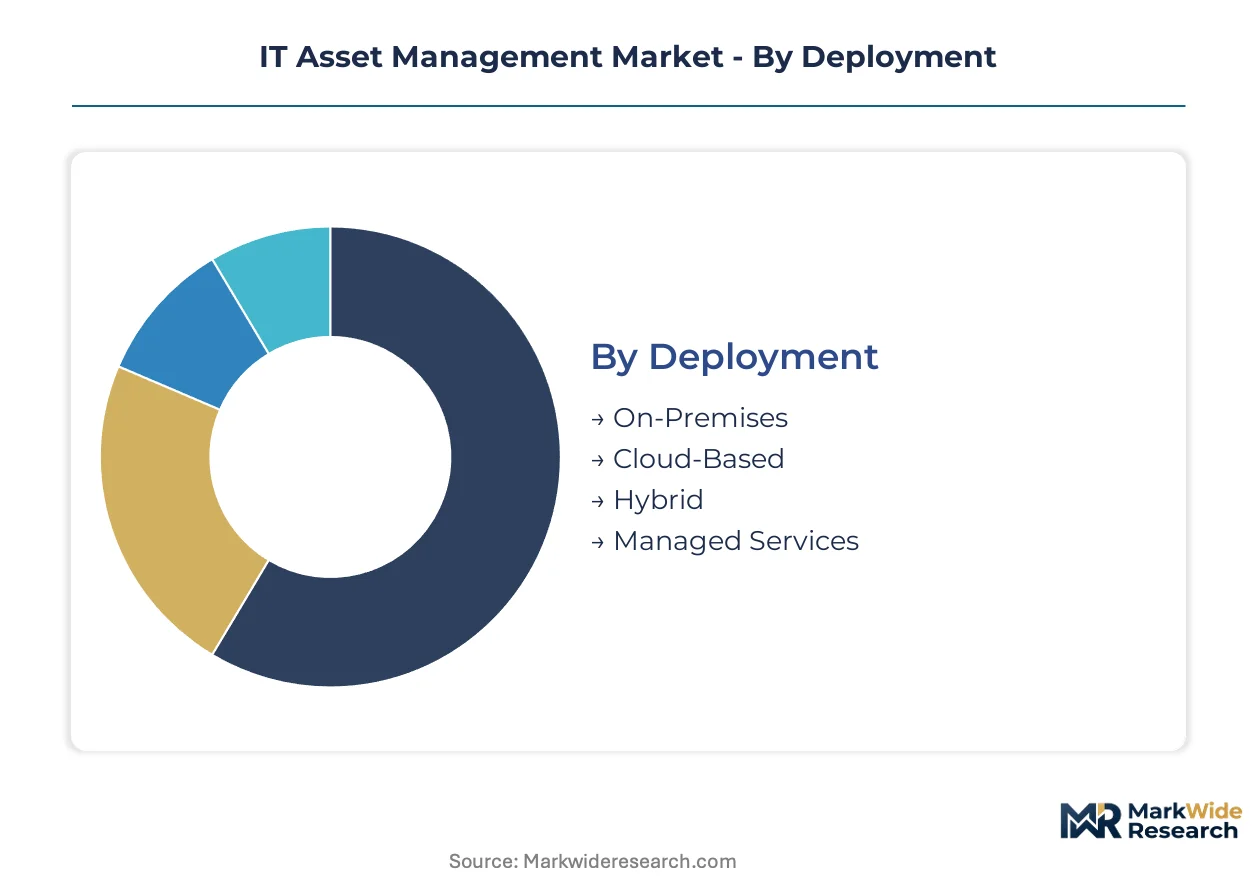
Segmentation reveals how IT asset management procurement splits across infrastructure maturity, organizational scale, and compliance burden. Each dimension carries distinct upgrade-cycle pressures and vendor qualification thresholds.
Deployment:
Refresh-cycle urgency varies sharply by deployment architecture, with cloud-native environments demanding continuous discovery while legacy on-premises estates face extended deprecation timelines.
- Cloud-Based:Multi-tenant discovery platforms scan containerized workloads through API-native agents. German automotive manufacturers and Netherlands financial services firms drive demand as CSRD disclosure deadlines compress hardware visibility requirements into quarterly reporting cycles.
- On-Premises:Persistent agent architectures dominate air-gapped government facilities and regulated healthcare networks. IBM z/OS mainframe integration costs inflate implementation budgets where legacy COBOL inventory systems resist API-based telemetry.
- Hybrid:Bridging architectures synchronize on-premises CMDBs with cloud-native discovery feeds. SAMR certification requirements in China fragment deployment patterns for multinational enterprises.
- Managed Services:Outsourced discovery operations bundle asset tracking with FinOps dashboards. Subscription pricing displaces perpetual licenses fastest in Nordics markets where outsourcing penetration exceeds continental averages.
Cloud-Based sits at the top of the volume ranking, with Managed Services climbing the fastest.
End User:
Organizational scale dictates solution complexity, with procurement authority concentrating differently across internal IT teams versus external service providers.
- IT Departments:Centralized technology teams operate integrated discovery platforms tied to enterprise CMDBs. US federal agencies sustain longer implementation timelines due to security classification requirements and FISMA compliance checkpoints.
- Enterprises:Distributed technology estates spanning multiple jurisdictions demand unified asset intelligence. REACH substance tracking mandates force component-level material passport integration for EU market access.
- SMEs:Mid-market accounts prioritize subscription-based discovery pricing over capital-intensive perpetual licenses. Managed service providers capture procurement decision-making authority through bundled offerings.
- Government Agencies:Public-sector procurement regulations sustain specialized vendor qualification criteria. India's BIS IT hardware standards create first-mover advantage for vendors embedding automated compliance documentation.
Enterprises dominate absolute spend, while SMEs gain share fastest as cloud-native tools democratize enterprise-grade discovery capabilities.
Solution:
Functional modules align with distinct risk exposures, from punitive software vendor audits to hardware emissions disclosure mandates.
- License Management:Automated reconciliation engines defend against Oracle, Microsoft, and SAP audit exposure. ISO 19770-1's 2024 revision elevates license tracking from best practice to formal audit defense requirement.
- Hardware Management:Sensor-based monitoring tracks server refresh cycles against carbon accounting baselines. EU CSRD mandates pull automated discovery tools into mandatory compliance stacks across European enterprises.
- Software Management:Discovery agents catalog installed applications across endpoint populations. Container orchestration platforms now scan ephemeral Kubernetes workloads at sub-minute intervals.
- Configuration Management:CMDB integration maintains authoritative system-of-record for IT service management workflows. BMC Software and ServiceNow compete through divergent architectural approaches to configuration data federation.
License Management commands premium pricing, with Hardware Management expanding most quickly under sustainability-linked procurement mandates.
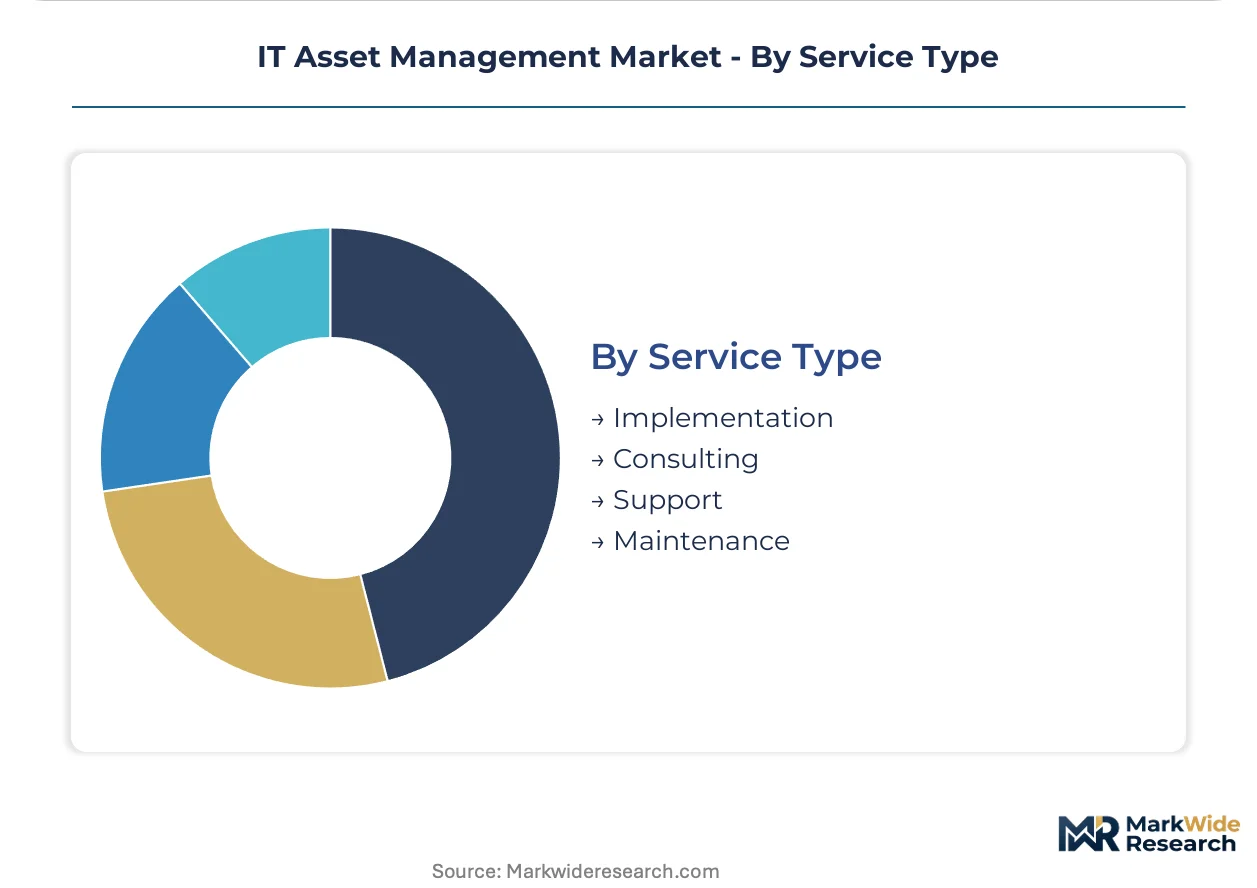
Service Type:
Professional services intensity correlates with deployment complexity and regulatory overlay thickness.
- Implementation:Deployment services configure discovery agents, normalize CMDB schemas, and establish automated reconciliation workflows. Mainframe integration projects inflate timelines where legacy environments resist API-based telemetry.
- Consulting:Advisory engagements align asset management maturity with CSRD disclosure readiness and ISO 19770 certification pathways. ITAM-sustainability skill scarcity slows consulting revenue recognition.
- Support:Technical assistance maintains discovery platform operations across multi-cloud environments. AWS, Azure, and GCP API drift forces continuous connector redevelopment.
- Maintenance:Ongoing platform updates address security patches, discovery protocol enhancements, and regulatory template expansions. REACH substance restriction updates drive recurring maintenance engagement.
Implementation generates the largest service revenue pool, though Consulting shows the steepest expansion trajectory as disclosure mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IT asset management systems first achieved enterprise scale in the United States during the 1990s data center consolidation wave. The industry subsequently diffused through European regulatory corridors and Asia-Pacific manufacturing hubs. Today's procurement patterns reflect this layered diffusion, with compliance mandates now driving divergence in regional adoption trajectories.
United States
Federal cloud-first mandates and SEC climate disclosure rules pull automated discovery tools into government and financial services procurement stacks. FISMA compliance checkpoints extend implementation timelines for agencies modernizing legacy COBOL inventory systems. Greater Boston's cybersecurity cluster anchors specialized CMDB integration services for defense contractors.
Germany
Industrial manufacturers face Bundesregierung environmental deadlines that compress hardware refresh telemetry into quarterly carbon accounting cycles. REACH substance restrictions force component-level material passport integration for server chassis traceability. Baden-Württemberg's automotive supplier network drives blockchain-based provenance tracking adoption.
China
State-owned enterprise digital transformation budgets sustain demand for hybrid discovery architectures bridging on-premises and cloud-native workloads. SAMR certification mandates local data residency for discovery agents, fragmenting multinational deployment patterns. Yangtze River Delta manufacturing headquarters accelerate sensor-based asset monitoring for supply chain visibility.
India
BIS IT hardware standards create procurement differentiation for vendors embedding automated compliance documentation into discovery platforms. Mid-market outsourcing penetration exceeds continental averages, concentrating subscription-based pricing adoption in Mumbai and Bangalore technology corridors. Karnataka's software services exporters drive ISO 19770 certification consulting demand.
Netherlands
Financial services firms deploy agentless discovery protocols across SWIFT-connected infrastructure within compressed implementation windows. CSRD disclosure readiness elevates automated reconciliation from operational convenience to audit defense requirement. Amsterdam's fintech cluster anchors sustainability-linked financing instruments tied to verified hardware lifecycle emissions data.
IT Asset Management Market Competitive Landscape
Capital-heavy platform vendors compete with asset-light specialists in IT asset management, creating a tiered structure where integrated suites face modular point solutions. The vendor base clusters around three strategic archetypes: cloud-native workflow platforms, heritage mainframe integration specialists, and compliance-focused license optimization engines. Consolidation pressure intensifies as sustainability mandates force capability bundling, while strategic partnerships between discovery tool vendors and carbon accounting platforms reshape alliance structures.
Within the integrated platform tier, ServiceNow and BMC Software occupy positions that exemplify divergent architectural approaches to configuration data federation. ServiceNow leverages its cloud-native foundation to anchor multi-tenant asset tracking workflows for multinational clients, while BMC Software represents heritage mainframe integration capabilities that persist in regulated industries. Snow Software sits within the license optimization specialist archetype, its positioning reflecting punitive vendor audit exposure that concentrates margin pools in automated reconciliation engines.
| Leading Market Players |
|---|
| ServiceNow |
| BMC Software |
| Ivanti |
| Flexera |
| Snow Software |
| Microsoft |
| ManageEngine |
| IBM |
| Freshworks |
| Others |
Pricing and Supply Chain Analysis
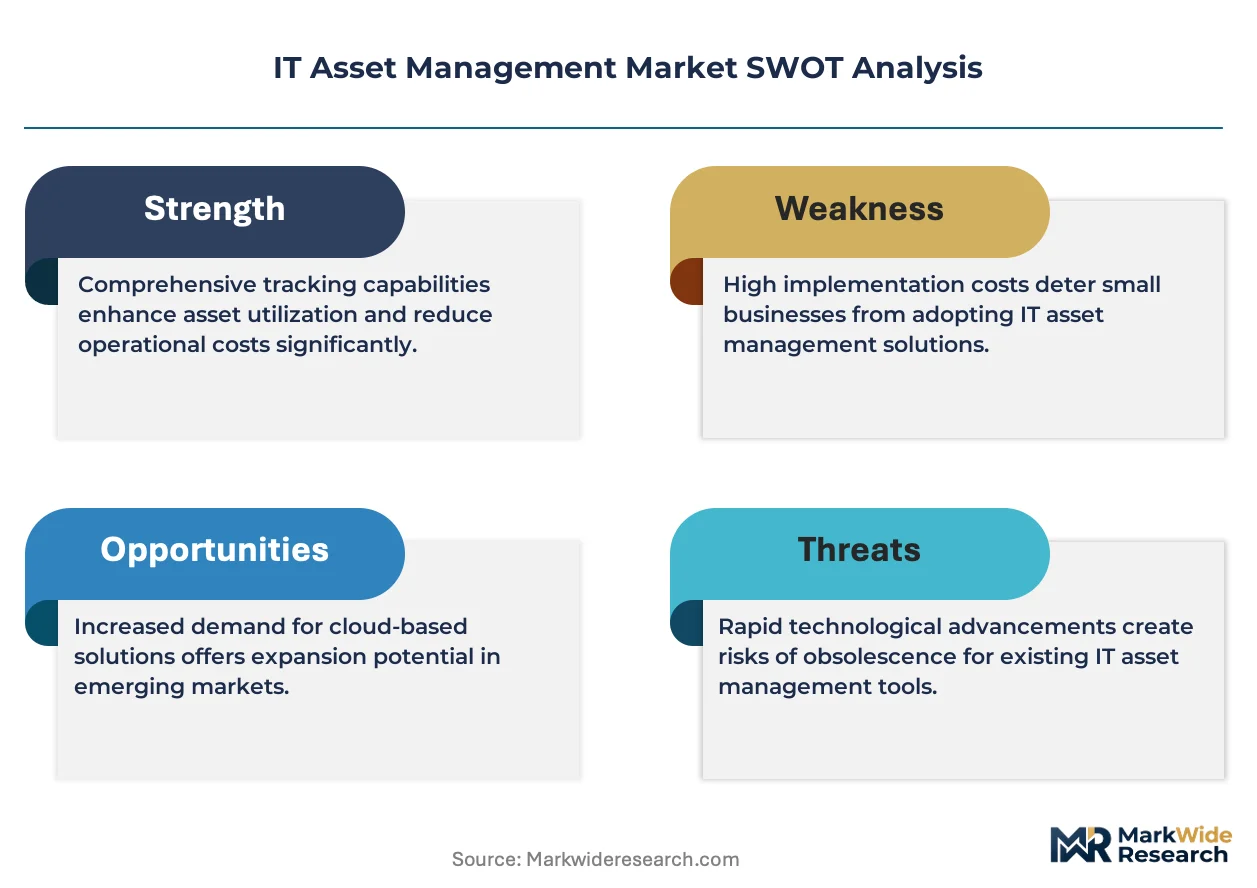
Enterprise-midmarket capability divergence splits IT asset management procurement into premium integrated suites and subscription-based point solutions, with pricing power concentrating in vendors bundling CSRD-compliant carbon accounting while supply chains fragment around regional data residency mandates.
Pricing Analysis
Subscription-based SaaS tiers dominate IT asset management pricing, with premium-mid-economy pricing differentiation anchored by CSRD disclosure automation and mainframe integration depth. Price differentiation rests on ISO 19770 certification grade and multi-cloud connector breadth. Cost compression in midmarket accounts intensifies as managed service providers bundle discovery with FinOps dashboards. SMEs exhibit highest price sensitivity, while German automotive manufacturers and US federal agencies accept premium positioning for compliance-grade telemetry.
Supply Chain Analysis
Dual-sourcing requirements for discovery agents now mandate qualification of both cloud-native and on-premises deployment partners across US, Germany, and India supply bases. Component dependencies span Taiwan-based chip fabrication for sensor hardware, Ireland-hosted EU data centers for CSRD compliance, and China-localized infrastructure for SAMR certification. Single-source vulnerability concentrates in API connector development talent pools. Distribution runs through hyperscaler marketplaces and direct enterprise sales with implementation service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IT asset management vendors capture margin expansion through sustainability-linked pricing premiums and automated compliance module attach rates, with cost-down drivers centering on agentless architecture eliminating endpoint deployment overhead.
For Market Incumbents: Acquire carbon accounting software assets to preempt CSRD-native competitors from unseating integrated platform positioning. Consolidate API connector development teams in India and Germany to compress multi-cloud integration timelines. Defend against Snow Software and Flexera in license optimization through deeper ServiceNow CMDB workflow embedding. For New Entrants and Emerging Players: Begin with agentless discovery protocols targeting Netherlands financial services firms facing compressed SWIFT infrastructure implementation windows. Penetrate India's BIS standards compliance segment through automated documentation modules. Pursue channel partnerships with managed service providers in Nordics markets where outsourcing penetration exceeds continental benchmarks. For Investors and Strategic Acquirers: Consolidation pressure builds where CSRD disclosure mandates force capability bundling across asset tracking, carbon accounting, and material passport provenance. Long-term viability favors platforms with Kubernetes-native architectures and blockchain-integrated supply chain modules. Monitor SAMR certification timeline acceleration in China as inflection indicator for multinational deployment fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Module Launch | Automated carbon accounting integration captures German automotive manufacturer procurement mandates. |
| Agentless Discovery Protocol Development | Passive traffic analysis eliminates endpoint overhead for Netherlands SWIFT-connected financial infrastructure. |
| India BIS Standards Certification | Embedded compliance documentation creates first-mover procurement advantage in Mumbai-Bangalore corridors. |
| Blockchain Provenance Partnership | Component-level material passport integration addresses REACH substance tracking for EU market access. |
| Multi-Cloud API Connector Expansion | Continuous AWS-Azure-GCP schema synchronization defends against quarterly metadata drift degradation. |
Research Methodology
Direct dialogue with IT procurement officers, sustainability compliance leads, CMDB integration specialists, and managed service provider executives grounded qualitative findings, cross-referenced against SEC climate disclosure filings, EU CSRD implementation guidance, ISO 19770-1 revision documentation, and hyperscaler capex allocation reports. Bottom-up deployment model sizing triangulated with top-down enterprise technology spend estimates.
Segment-level projections across cloud-based, on-premises, hybrid, and managed services deployments integrated organization scale, vertical compliance burden, and geographic regulatory intensity dimensions. CAGRs derived from adoption curve modeling against CSRD deadline proximity and mainframe refresh cycle timing. Forecast inputs incorporated Kubernetes workload growth trajectories and REACH substance restriction update schedules.
Several conditions sit outside the modeled scope, including abrupt SAMR certification requirement changes, Taiwan semiconductor supply disruptions, and unanticipated ISO 19770 standard revision scope expansion. Deviation in EU CSRD enforcement intensity or US SEC climate rule implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Mexico Digital Showers Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Global Application Container Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
North America API Management Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Global Mesh App and Service Architecture Market