
 Europe API Management Market | 2026-2036
Europe API Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe API Management Market Insights
Enterprise-grade security certification is rotating toward the center of procurement decisions in the Europe API Management Market. Microsoft Corp leverages its Azure-native gateway portfolio to anchor public-sector contracts across Nordic member states. Software AG competes through specialized on-premises-to-hybrid migration tooling that sustains loyalty among German manufacturing conglomerates. Google LLC differentiates via Anthos-backed multi-cloud orchestration that positions its platform for financial institutions navigating fragmented sovereign-cloud requirements.
API management encompasses the lifecycle governance, security mediation, traffic control, and analytics instrumentation of application programming interfaces operating at throughput thresholds exceeding 50,000 requests per second in production financial environments. The discipline enables regulated data exchange between banks, insurers, healthcare providers, and third-party developers under standardized consent frameworks. Cloud-based deployment now leads solution uptake as enterprises retire capital-intensive gateway appliances, while API Security commands the strongest margin pool due to mandatory encryption-in-transit and token-validation requirements under PSD2 and the EU AI Act. API Analytics represents the fastest-expanding solution category as real-time latency monitoring becomes essential for SLA enforcement in open-banking corridors.
The European Banking Authority, EBA, enforces PSD2 technical standards that mandate strong customer authentication and qualified certificate issuance for all payment initiation APIs. The EU AI Act, administered by national market-surveillance authorities, imposes risk-classification obligations on API pipelines feeding automated credit-decision systems. The EU Cybersecurity Act and ENISA certification schemes shape product standards for cross-border data exchange infrastructure. Stakeholders must monitor how the forthcoming Digital Operational Resilience Act, DORA, reporting timelines will recalibrate support-service pricing and integration partner liability structures.
Market Dynamics
Cloud-native gateway architectures are compressing procurement cycles across European financial services as PSD2-mandated open banking interfaces force incumbent banks to retire decade-old middleware stacks.
Growth Catalysts
- PSD2 Technical Standards:The European Banking Authority's strong customer authentication mandates compel payment service providers to deploy API security layers, creating baseline demand across Germany, France, and the Netherlands.
- Manufacturing IoT Integration:German automotive and industrial equipment producers are exposing operational data streams via managed APIs to enable predictive maintenance partnerships with third-party analytics vendors.
- Healthcare Data Exchange:The European Health Data Space initiative is accelerating API deployment among Dutch and French hospital networks to enable cross-border patient record portability.
Market Restraints
- Certificate Authority Concentration:Qualified trust service provider scarcity under eIDAS regulation creates single-point-of-failure risk for payment API authentication chains.
- Legacy Gateway Stranding:Capital-intensive on-premises appliance investments from 2015-2019 continue to absorb IT budget that would otherwise migrate to elastic cloud consumption models.
- Sovereign Cloud Fragmentation:National data localization requirements in France, Germany, and emerging EU member states force vendors to maintain parallel infrastructure footprints.
Strategic Opportunities
- Digital Operational Resilience Act (DORA):The 2025 incident reporting timeline creates immediate demand for real-time API monitoring and automated compliance documentation tools among EU-regulated financial entities.
- Nordic Public Sector:Sweden, Denmark, and Finland government digitization programs represent underpenetrated procurement channels for citizen-facing service APIs.
- AI Pipeline Governance:Convergence of API management with ML model serving infrastructure addresses EU AI Act risk-classification requirements for automated credit-decision systems.
Industry Challenges
- Identity Federation Expertise:Shortage of engineers proficient in OAuth 2.0, OpenID Connect, and eIDAS certificate binding slows implementation timelines for mid-tier banks.
- Hybrid Integration Complexity:Maintaining consistent policy enforcement across Kubernetes-native gateways and remaining IBM DataPower or Oracle SOA Suite installations demands specialized architecture labor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe API Management Market |
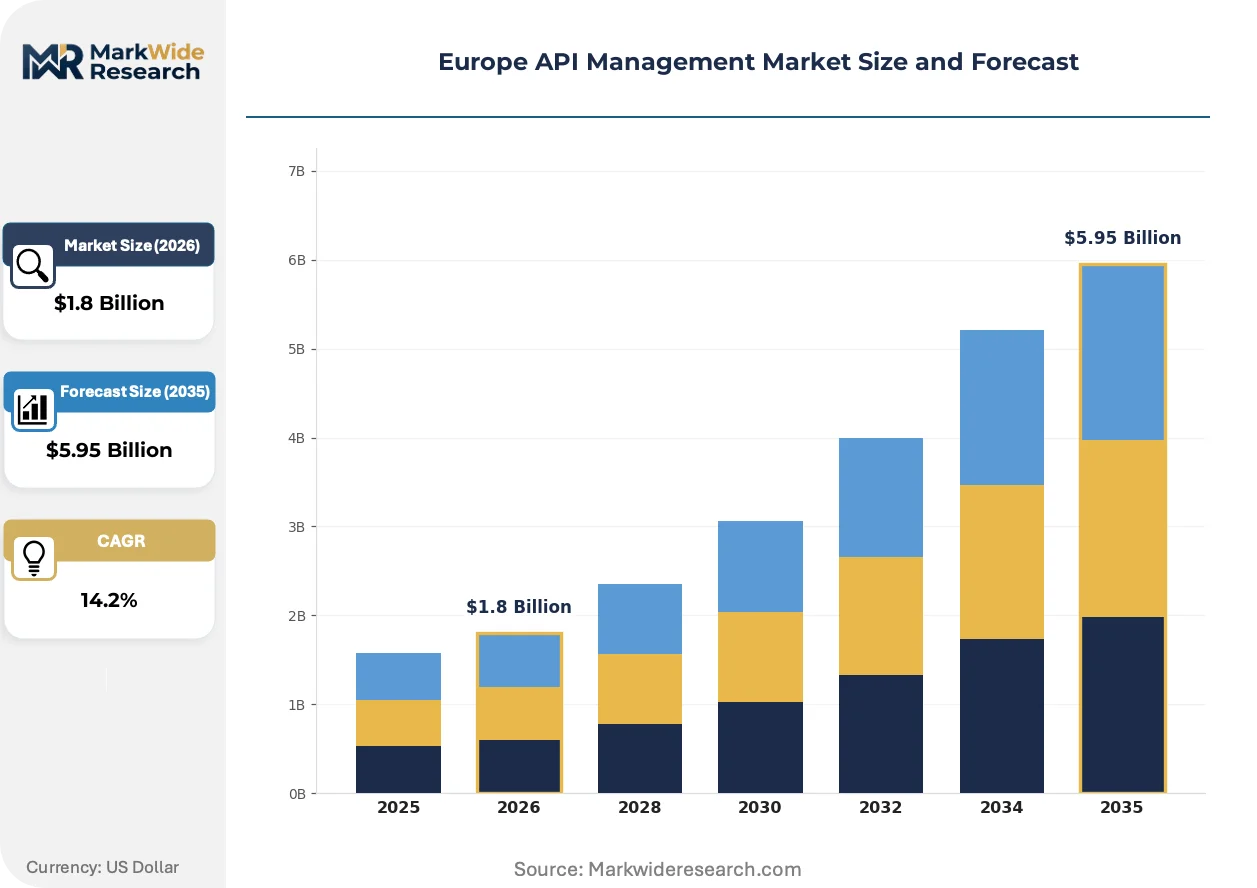
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Financial Services, Retail, Healthcare, Telecommunications Solution: API Gateway, API Analytics, API Security, API Development Service Type: Consulting, Integration, Support & Maintenance, Training |
| Companies Covered | International Business Machines Corp, Microsoft Corp, Oracle Corp, Google LLC, Broadcom Inc, Software AG, Akamai Technologies Inc, SAP SE, Axway Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe API Management Market Trends and Innovations
API management tooling is bifurcating between hyperscaler-native suites and specialized security-first platforms as buyer sophistication around token lifecycle governance matures.
GraphQL query languages are fragmenting REST API standardization in high-velocity financial environments. Dutch neobanks and Berlin-based fintechs are adopting GraphQL federation to reduce over-fetching latency in mobile payment interfaces. This fragmentation is compressing gateway vendor roadmaps toward multi-protocol support.
The EU AI Act risk-classification framework is forcing API pipeline redesign for automated underwriting systems. National market-surveillance authorities in Germany and France are interpreting high-risk system definitions to include credit-scoring API endpoints. Financial institutions are responding by embedding audit logging and model-version tagging directly into API gateway configurations.
Consumption-based pricing is displacing perpetual license models among European enterprises. German manufacturing conglomerates and French insurers are negotiating throughput-tiered contracts that align vendor revenue with actual API call volume. This shift is most visible in Frankfurt and Paris, where procurement teams prioritize operational expenditure treatment over capital allocation cycles.
Europe API Management Market Segmentation
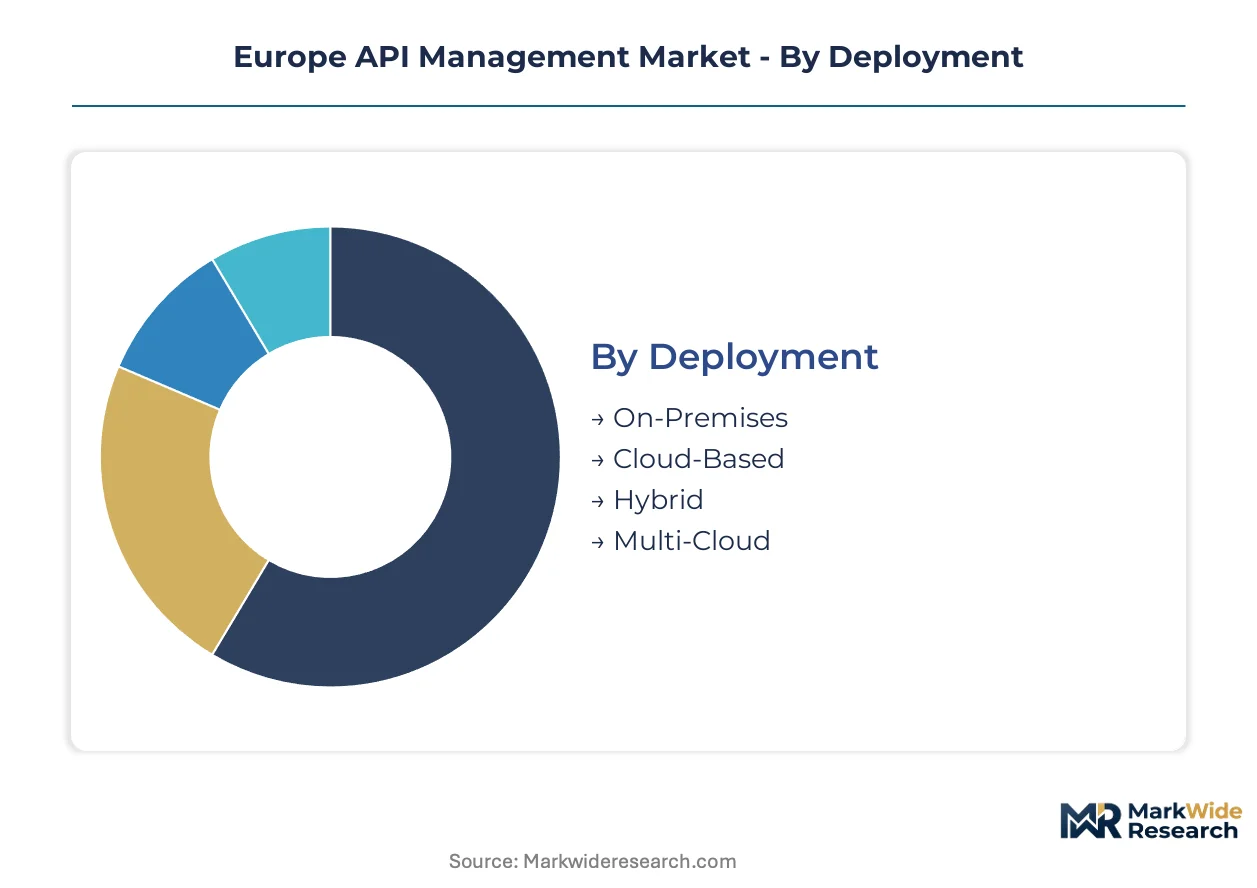
Deployment architecture choices in the Europe API Management Market determine regulatory compliance pathways and operational elasticity. End-user concentration across financial services and healthcare shapes solution bundling strategies for vendors competing under PSD2 and EHDS mandates.
Deployment:
German and French financial institutions favor on-premises and sovereign-cloud configurations, while Dutch fintechs and Nordic public-sector buyers drive cloud-native uptake.
- On-Premises:Dedicated hardware installations within client data centers enforce complete data sovereignty. German automotive conglomerates and Frankfurt-based banks retain these configurations to satisfy Bundesbank operational risk guidelines and internal audit requirements.
- Cloud-Based:Fully managed SaaS gateway platforms provision elastic throughput scaling without capital expenditure. French insurers and Amsterdam neobanks are migrating here to align with ACPR cloud guidance and reduce fixed infrastructure costs.
- Hybrid:Split traffic routing between private data centers and public cloud zones. This architecture addresses transitional compliance for Dutch banks navigating legacy core system constraints.
- Multi-Cloud:Gateway federation across AWS, Azure, and GCP regions. Belgian and Luxembourg financial institutions deploy this to avoid single-vendor concentration risk under DORA outsourcing rules.
On-Premises retains the largest installed base; momentum sits with Cloud-Based configurations as sovereign-cloud certifications expand.
End User:
Regulatory intensity varies sharply across sectors, with financial services facing mandatory authentication standards that healthcare and retail encounter only selectively.
- Financial Services:Banks, insurers, and payment processors managing PSD2-mandated open banking interfaces. Berlin and Paris host the densest procurement activity, driven by EBA technical standards and national competent authority enforcement.
- Healthcare:Hospital networks and health information exchanges enabling cross-border patient data portability. Dutch university medical centers and French regional health agencies are deploying APIs under the European Health Data Space roadmap.
- Retail:Omnichannel merchants integrating inventory and payment systems with marketplace partners. German e-commerce platforms lead adoption here, prioritizing checkout latency reduction.
- Telecommunications:Operators exposing network capabilities to enterprise customers via standardized interfaces. Nordic carriers are advancing fastest, embedding API monetization into 5G enterprise service bundles.
Financial Services commands dominant procurement volume; Healthcare is climbing fastest as EHDS implementation timelines accelerate.
Solution:
Margin structures diverge significantly, with security modules capturing premium pricing due to mandatory encryption and token-validation requirements.
- API Security:Authentication, authorization, and threat protection layers including OAuth 2.0, OpenID Connect, and eIDAS certificate binding. German banks prioritize this segment to satisfy PSD2 strong customer authentication mandates and qualified certificate issuance rules.
- API Analytics:Real-time latency monitoring, SLA enforcement dashboards, and usage metering. French asset managers and Dutch pension funds are expanding deployments here to meet DORA incident reporting requirements.
- API Gateway:Core traffic management, protocol translation, and rate limiting infrastructure. This foundational layer sees replacement demand as cloud-native architectures displace legacy appliances.
- API Development:Design-time tooling, developer portals, and lifecycle governance workflows. Berlin fintech clusters drive adoption of GraphQL federation capabilities within this category.
API Security generates the highest margins; API Analytics is expanding most quickly as real-time compliance monitoring becomes mandatory.
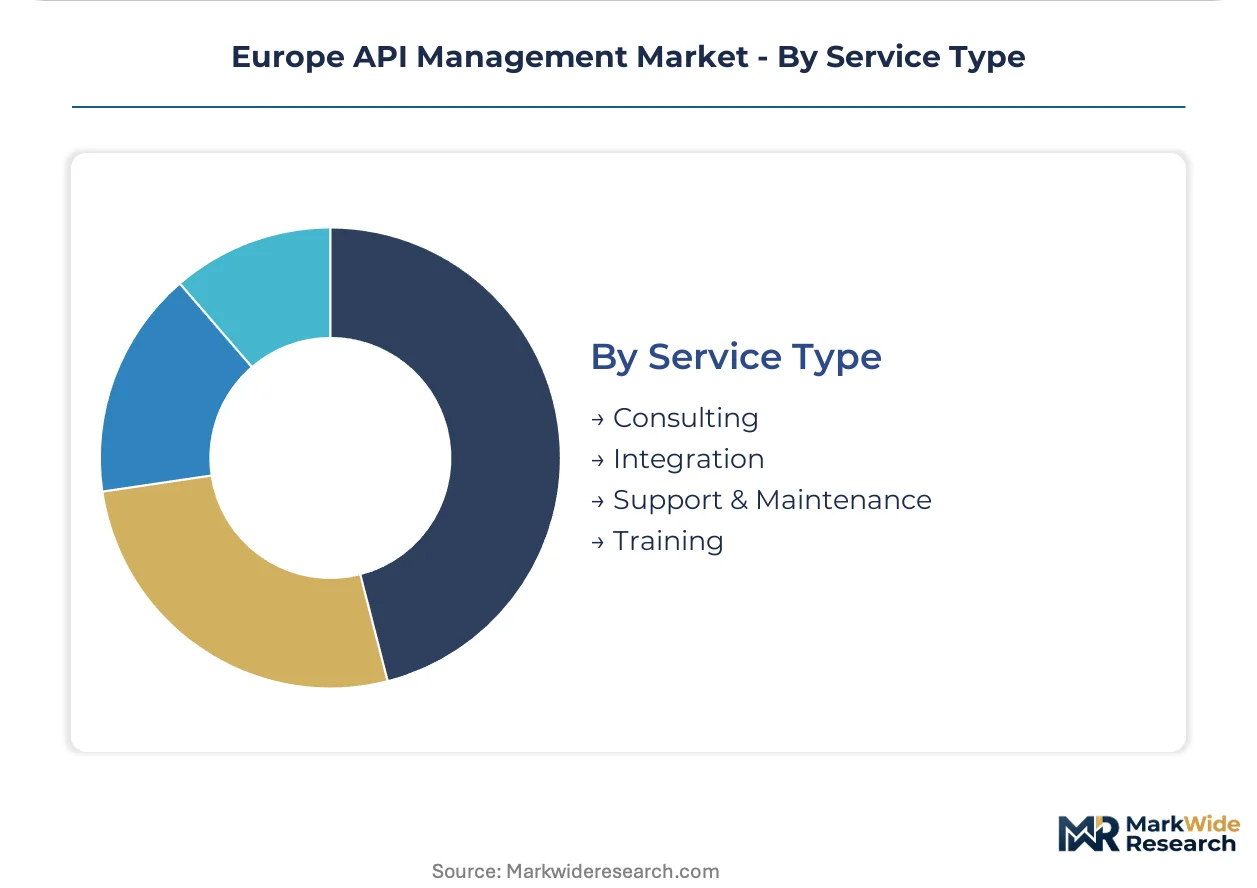
Service Type:
Vendor revenue mix is shifting toward recurring integration and support contracts as cloud deployments reduce upfront implementation complexity.
- Integration:Professional services for gateway deployment, legacy middleware migration, and multi-protocol configuration. German manufacturing conglomerates require extensive hybrid integration labor to bridge Kubernetes-native gateways with remaining IBM DataPower installations.
- Support & Maintenance:24/7 operational assistance, patch management, and compliance update delivery. This segment captures growing share as DORA incident response timelines demand guaranteed vendor availability.
- Consulting:Architecture assessment, security policy design, and regulatory readiness evaluation. French banks engage these services to interpret EU AI Act risk-classification obligations for credit-scoring API pipelines.
- Training:Developer certification programs and administrator workshops. Identity federation expertise shortages are expanding demand here, particularly for OAuth 2.0 and eIDAS certificate binding competencies.
Integration services hold the largest revenue share; Support & Maintenance is gaining share fastest as operational resilience requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German API gateway vendors export managed security services to French and Dutch financial institutions navigating PSD2 compliance deadlines. Cross-border procurement corridors concentrate between Frankfurt, Paris, and Amsterdam as regulatory harmonization accelerates.
Germany
Bundesbank operational risk guidelines and DORA incident reporting timelines compel Frankfurt-based banks to upgrade legacy middleware stacks. The Federal Financial Supervisory Authority enforces strict outsourcing controls on cloud-native gateway deployments. Berlin's fintech cluster drives GraphQL federation adoption among neobanks seeking mobile latency reduction.
France
ACPR cloud guidance and EU AI Act risk-classification obligations shape procurement at Parisian asset managers and insurers. The French Prudential Supervision and Resolution Authority mandates audit logging for credit-scoring API pipelines. Île-de-France hosts dense concentrations of consulting demand for hybrid integration architecture.
Netherlands
Dutch neobanks and pension funds prioritize elastic throughput scaling under European Health Data Space implementation timelines. The Dutch Data Protection Authority interprets GDPR requirements for cross-border patient record APIs. Amsterdam's technology corridor leads cloud-native migration away from capital-intensive appliance investments.
United Kingdom
Post-Brexit regulatory divergence creates dual-compliance burdens for London-based banks maintaining EU market access. The Financial Conduct Authority enforces open banking standards that parallel PSD2 technical requirements. The City of London and Manchester financial centers sustain demand for multi-cloud gateway federation.
Sweden
Nordic government digitization programs generate underpenetrated procurement channels for citizen-facing service APIs. The Swedish Post and Telecom Authority certifies qualified trust service providers under eIDAS regulation. Stockholm's public-sector technology clusters advance API monetization within 5G enterprise service bundles.
Europe API Management Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native and hybrid deployment vectors. Microsoft Corp leverages hyperscaler scale to anchor public-sector contracts, while Software AG sustains loyalty through specialized migration tooling. Strategic archetypes include hyperscaler-native suites, security-first platforms, and legacy-to-hybrid specialists. Competitive moves concentrate on sovereign-cloud certification acquisition and consumption-based pricing model adoption.
Within the legacy-to-hybrid tier, Software AG and Axway Inc occupy positions anchored to German manufacturing conglomerates requiring bridge architectures between Kubernetes-native gateways and remaining IBM DataPower installations. Microsoft Corp exemplifies the hyperscaler-native archetype through Azure-native gateway portfolios securing Nordic public-sector contracts. Google LLC sits within the multi-cloud orchestration segment, positioning Anthos-backed platforms for Belgian and Luxembourg financial institutions navigating DORA outsourcing concentration rules.
| Leading Market Players |
|---|
| International Business Machines Corp |
| Microsoft Corp |
| Oracle Corp |
| Google LLC |
| Broadcom Inc |
| Software AG |
| Akamai Technologies Inc |
| SAP SE |
| Axway Inc |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler-scale infrastructure utilization in Frankfurt and Amsterdam data centers compresses unit economics for cloud-native gateway provisioning, concentrating supply-side pricing power among vendors with certified sovereign-cloud deployments while forcing smaller players toward niche security modules.
Pricing Analysis
Cloud-native generation pricing gaps against legacy appliance models exceed three-to-one in total cost of ownership calculations, with on-premises configurations carrying premium maintenance burdens. Three-tier pricing structure across enterprise-grade security bundles, standard gateway throughput tiers, and developer-tier SaaS entry points dominates vendor contract negotiations. Cost compression in mid-market segments intensifies as Dutch neobanks and German insurers negotiate consumption-based contracts tied to actual API call volumes. Financial services procurement teams exhibit lowest price sensitivity due to mandatory PSD2 compliance budgets, while retail omnichannel merchants drive hardest bargain for basic gateway functionality.
Supply Chain Analysis
Qualified trust service provider scarcity under eIDAS regulation creates a chokepoint that constrains authentication certificate issuance for payment API deployments across Germany, France, and the Netherlands. Gateway hardware fabrication draws from Taiwan semiconductor foundries, German industrial automation component suppliers, and Irish data center infrastructure specialists. Single-source vulnerability concentrates in qualified certificate authority concentration, where only a handful of providers meet EBA technical standards for strong customer authentication. Distribution runs through direct enterprise sales forces for on-premises deployments and hyperscaler marketplaces for cloud-native configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent gateway vendors face substitution pressure from hyperscaler-native suites that bundle API management into broader cloud consumption contracts, eroding standalone pricing power.
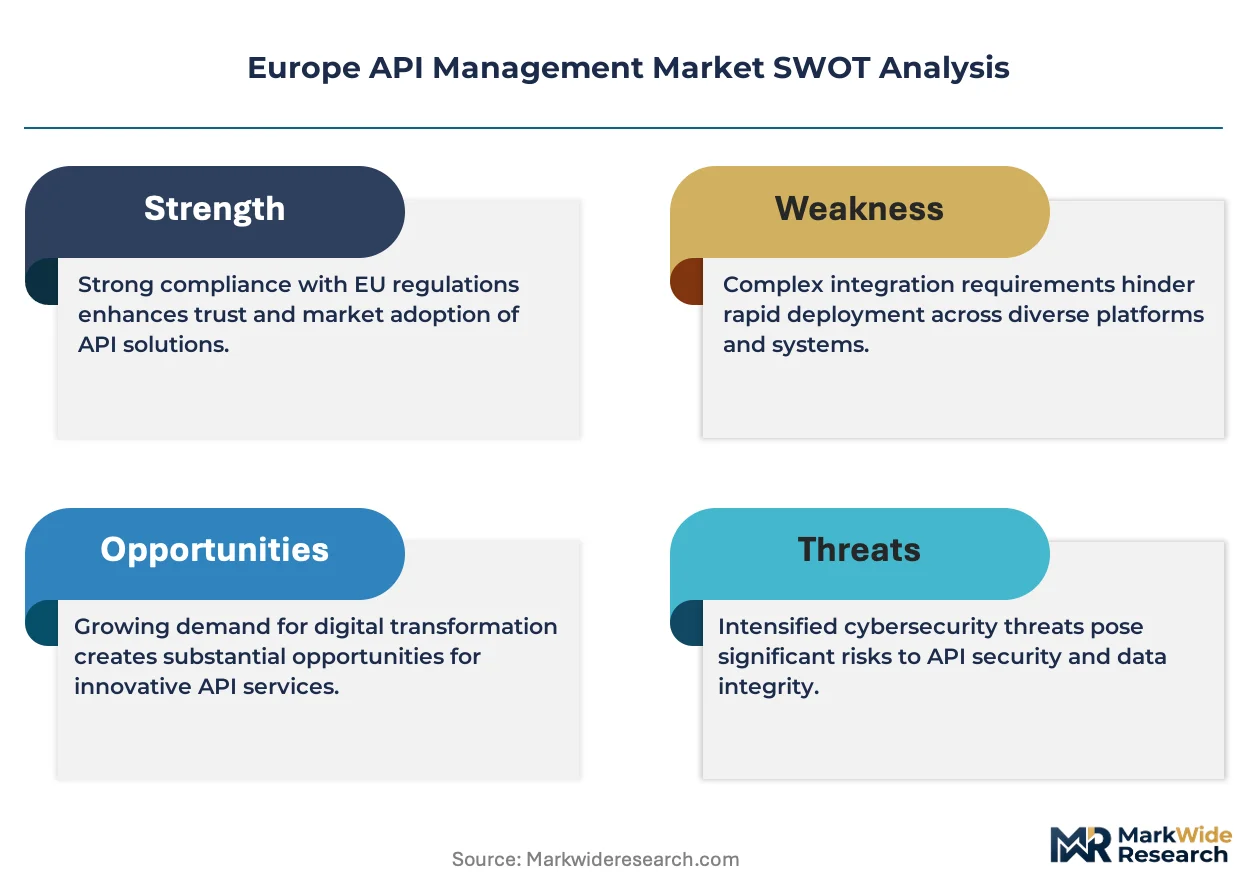
For Market Incumbents: Fortify hybrid integration capabilities to capture German manufacturing conglomerates stranded between Kubernetes-native architectures and remaining IBM DataPower installations. Deepen vertical integration into sovereign-cloud certification pipelines to defend against Microsoft Azure's public-sector anchoring across Nordic member states. For New Entrants and Emerging Players: Anchor in API Analytics white space where real-time DORA compliance monitoring creates immediate procurement urgency among French asset managers and Dutch pension funds. Target healthcare data exchange corridors under European Health Data Space implementation timelines, positioning GraphQL federation expertise as differentiated entry wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors security-first platform specialists with embedded EU AI Act risk-classification tooling over generic gateway providers. Long-term viability hinges on multi-cloud orchestration capabilities that address DORA outsourcing concentration rules. Watch for hyperscaler bundling intensity as inflection signal for standalone vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Certification Acquisition | Unlocks German and French financial institution procurement under Bundesbank and ACPR guidelines. |
| API Security Module Specialization | Captures premium pricing from PSD2-mandated strong customer authentication and eIDAS certificate binding. |
| GraphQL Federation Capability Buildout | Addresses Dutch neobank and Berlin fintech demand for mobile latency reduction in payment interfaces. |
| Consumption-Based Pricing Transition | Aligns vendor revenue with actual API throughput, matching Frankfurt and Paris procurement team priorities. |
| DORA Compliance Tooling Integration | Embeds real-time incident reporting and automated documentation for 2025 regulatory deadlines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EBA technical standard publications, ENISA certification scheme documentation, and hyperscaler capex disclosures. Interviews with bank CTOs, IT procurement officers at German insurers, platform engineers at Dutch fintechs, and integration specialists supporting healthcare data exchanges inform demand-side calibration. Secondary validation draws from PSD2 implementation reports, EU AI Act risk-classification guidance, and sovereign-cloud certification registers. Bottom-up deployment volume estimates triangulate against top-down vendor revenue segmentation.
Segmentation dimensions modeled span deployment architecture, end-user vertical, solution module, and service type across the projection horizon. Deployment splits between on-premises, cloud-based, hybrid, and multi-cloud configurations anchor capacity forecasting. End-user concentration weights financial services, healthcare, retail, and telecommunications procurement patterns. CAGRs derive from elasticity-adjusted adoption curves and regulatory deadline acceleration effects. Forecast inputs incorporate DORA incident reporting timeline compliance spending and European Health Data Space implementation pacing.
Material uncertainties — regulatory interpretation divergence across national competent authorities, hyperscaler bundling intensity, qualified trust service provider capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about PSD2 enforcement continuity and sovereign-cloud certification expansion without guarantee. Practitioners should keep alternative scenarios live as EU AI Act risk-classification guidance and DORA outsourcing rule implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Crop Management Software Market
Digital Solutions
Product Information Management Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Bangladesh ICT Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Shipping Software Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Graph Technology Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Global Intelligent Platform Management Interface (IPMI) Market