
 Electronic Contract Manufacturing and Design Services Market | 2026-2036
Electronic Contract Manufacturing and Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Contract Manufacturing and Design Services Market Intelligence
The scarcity of specialized firmware and embedded systems engineers is collapsing the traditional boundaries between original equipment manufacturers and their outsourcing partners. This skills gap forces OEMs to seek integrated design and manufacturing services. Foxconn leverages its immense scale for high-volume consumer electronics. Jabil differentiates through complex supply chain management for industrial clients, while Celestica specializes in high-reliability solutions.
Electronic contract manufacturing and design services encompass the outsourced production, assembly, and lifecycle management of electronic products for OEMs. This includes intricate processes like surface-mount technology (SMT) on multi-layer printed circuit boards (PCBs) to accelerate time-to-market. Box build assembly and full turnkey solutions represent higher-value service offerings compared to basic printed circuit assembly. Demand from the telecommunications and medical devices sectors requires strict adherence to quality standards and regulatory compliance, shaping vendor selection.
Regulations such as the EU's RoHS directive and REACH framework dictate material composition and restrict the use of hazardous substances. In the United States, conflict minerals disclosure rules under the Dodd-Frank Act impose significant supply chain due diligence requirements on sourcing tin, tungsten, tantalum, and gold. Decisions on the geographic diversification of production footprints to mitigate geopolitical and supply chain risks will define future competitive advantage.
Market Dynamics
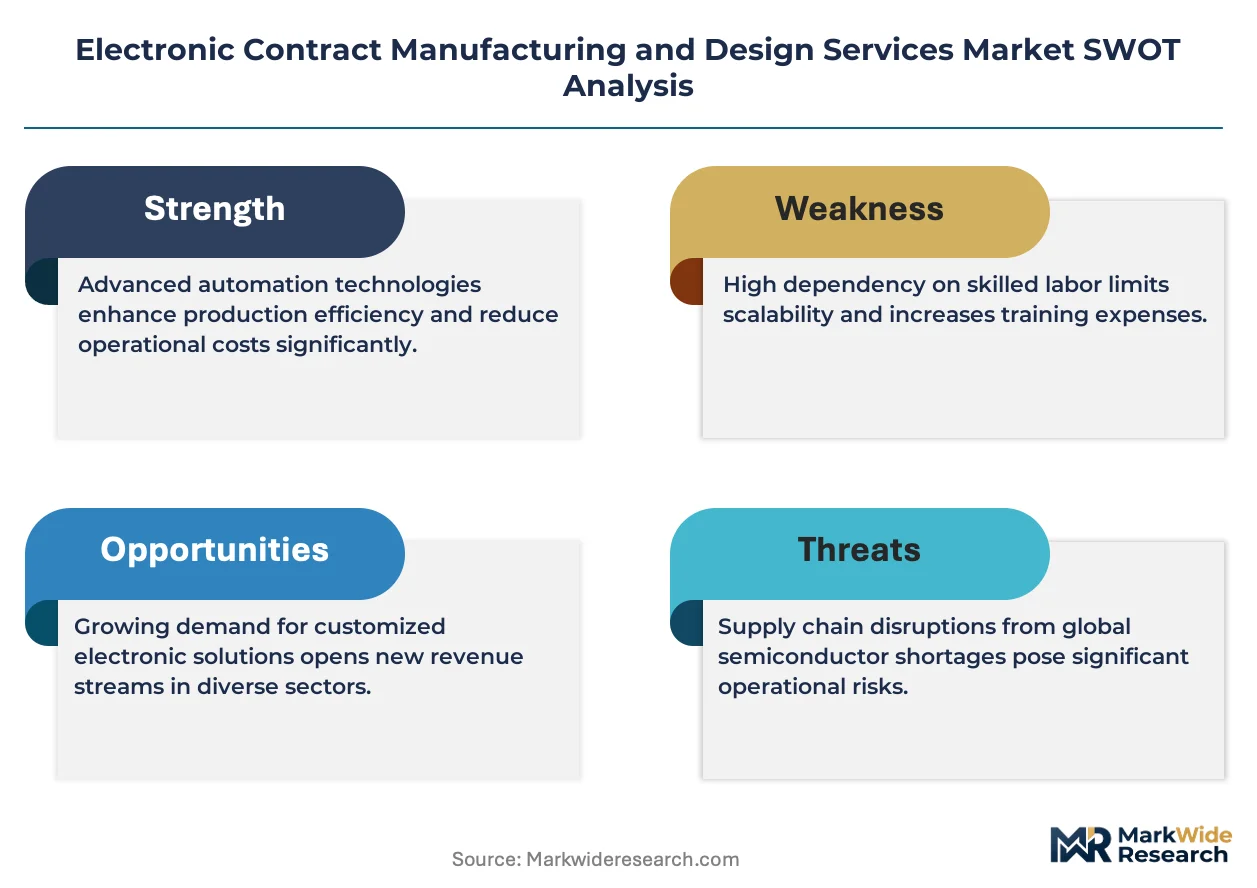
The convergence of design and manufacturing services is the central structural force in the market. A systemic shortage of specialized firmware and embedded systems engineers is forcing original equipment manufacturers to outsource integrated product development, collapsing the traditional separation between design and production partners.
Growth Catalysts
- 5G Integration:The incorporation of 5G connectivity into industrial equipment and automotive systems requires sophisticated electronic design and assembly, driving demand for specialized contract manufacturing services.
- Medical Device Complexity:Original equipment manufacturers in the medical sector increasingly outsource development of complex products to ensure adherence to stringent regulatory standards like the EU's MDR and the FDA's quality system regulations.
- Geopolitical Diversification:Efforts to de-risk supply chains are steering manufacturing investment towards new hubs in Mexico and Vietnam, creating localized demand for full turnkey electronic manufacturing and design service providers.
Market Restraints
- Material Price Volatility:Fluctuations in the cost of key raw materials such as tin, tungsten, tantalum, and gold, exacerbated by regulations like the Dodd-Frank Act, create significant margin pressure and pricing instability.
- Semiconductor Bottlenecks:The heavy geographic concentration of advanced semiconductor fabrication creates a critical dependency, exposing the entire electronics value chain to supply disruptions and component allocation challenges.
- Intellectual Property Risks:Concerns over the protection of proprietary designs and firmware code during collaborative development processes can deter OEMs from engaging in deeper design-led outsourcing partnerships.
Strategic Opportunities
- Aftermarket Services:Expanding service offerings to include repair, refurbishment, and end-of-life management for high-value electronics in the aerospace and industrial sectors provides a recurring, high-margin revenue stream.
- AI in Quality Assurance:The deployment of artificial intelligence and machine learning in automated optical inspection (AOI) systems offers a pathway to improve manufacturing yields, reduce defect rates, and lower quality control costs.
- EV Battery Management Systems:The electric vehicle transition, particularly in markets like India with its Production Linked Incentive (PLI) scheme, opens a substantial opportunity for manufacturing sophisticated battery management system (BMS) electronics.
Industry Challenges
- Talent Scarcity:A persistent deficit of engineers with combined expertise in radio frequency (RF) design, power management, and embedded software development constrains the ability of service providers to scale complex projects.
- Compliance Overhead:Adhering to a complex web of international environmental regulations, including the EU's RoHS and REACH directives, necessitates significant investment in supply chain traceability and compliance management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Contract Manufacturing and Design Services Market |
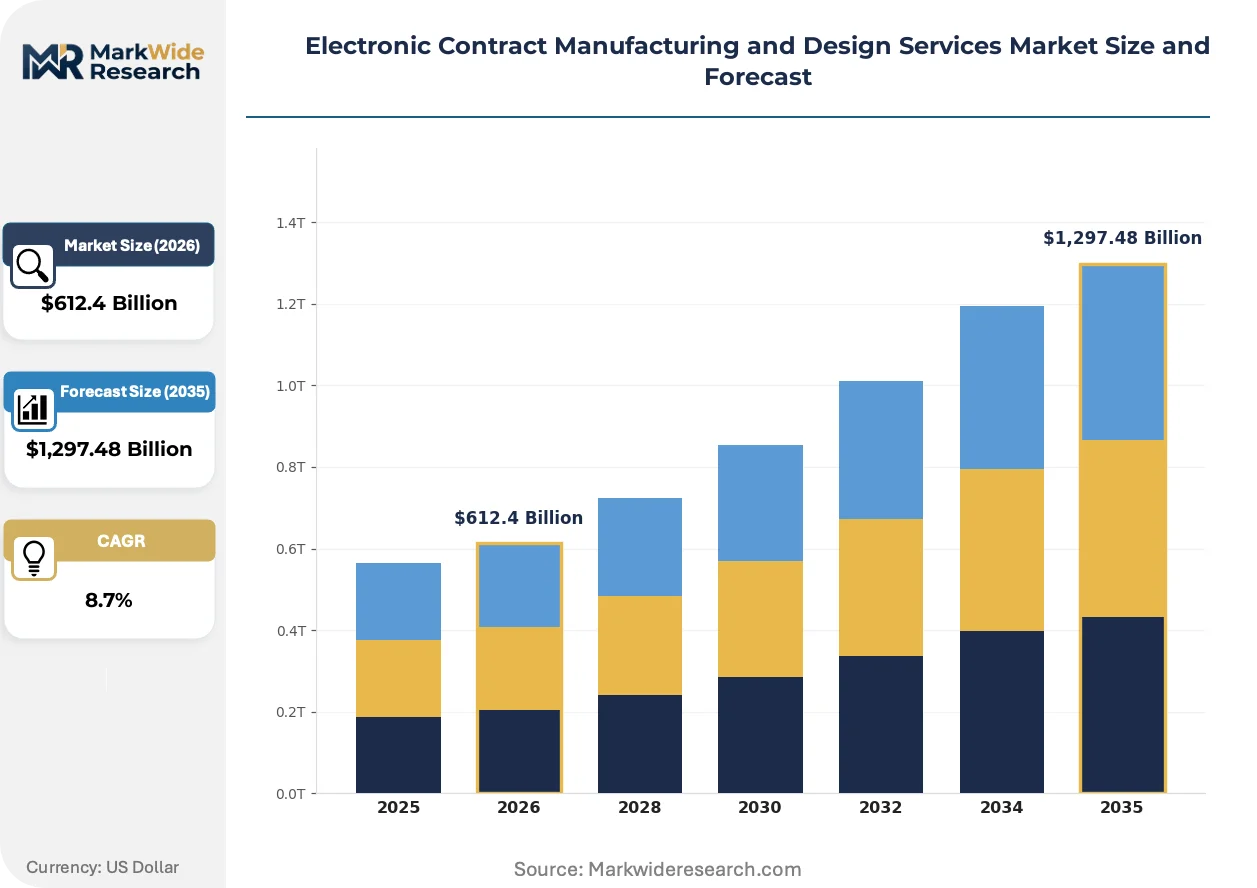
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Printed Circuit Assembly, Box Build, Surface Mount Technology, Through-Hole Technology, Testing & Inspection End User Industry: Consumer Electronics, Aerospace & Defense, Telecommunications, Medical Devices, Industrial Equipment Design Offering: Embedded System Design, Firmware Development, PCB Layout, Product Prototyping, Signal Integrity Analysis Deployment Model: Onsite Engineering, Remote Collaboration, Turnkey Solutions, Build-to-Order, Just-In-Time Manufacturing |
| Companies Covered | Celestica, Sanmina Corporation, Foxconn, Zollner Elektronik, Benchmark Electronics, Flex, Pegatron Corporation, Fabrinet, Jabil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Contract Manufacturing and Design Services Market Strategic Shifts & Innovations
Intelligent automation and data-driven manufacturing processes are redefining the value proposition of electronic contract services. The focus is shifting from simple assembly to providing integrated systems that combine hardware, embedded software, and lifecycle data analytics to deliver superior product performance for OEMs.
Digital twin technology enables the creation of a virtual replica of a physical electronic assembly. Industrial and medical OEMs are adopting this for simulation and predictive maintenance. This continuous data feedback loop from the field back to the virtual model is decomposing the traditional, sequential product lifecycle into an iterative process of real-time optimization.
Regulatory frameworks focused on sustainability are directly influencing supply chain architecture. The EU's Corporate Sustainability Reporting Directive (CSRD) compels OEMs to provide detailed disclosures on environmental and social impacts. This requirement cascades down to EMS providers, who must now furnish granular data on material provenance and energy usage, making transparency a competitive differentiator.
Product development models are pivoting to a "design-for-resilience" approach. This model supplants a sequential process where sourcing follows design finalization, instead integrating supply chain analysis as an upfront design input. The practice is most visible within the automotive and telecommunications sectors, where component availability dictates product architecture and launch schedules.
Electronic Contract Manufacturing and Design Services Market Segmentation
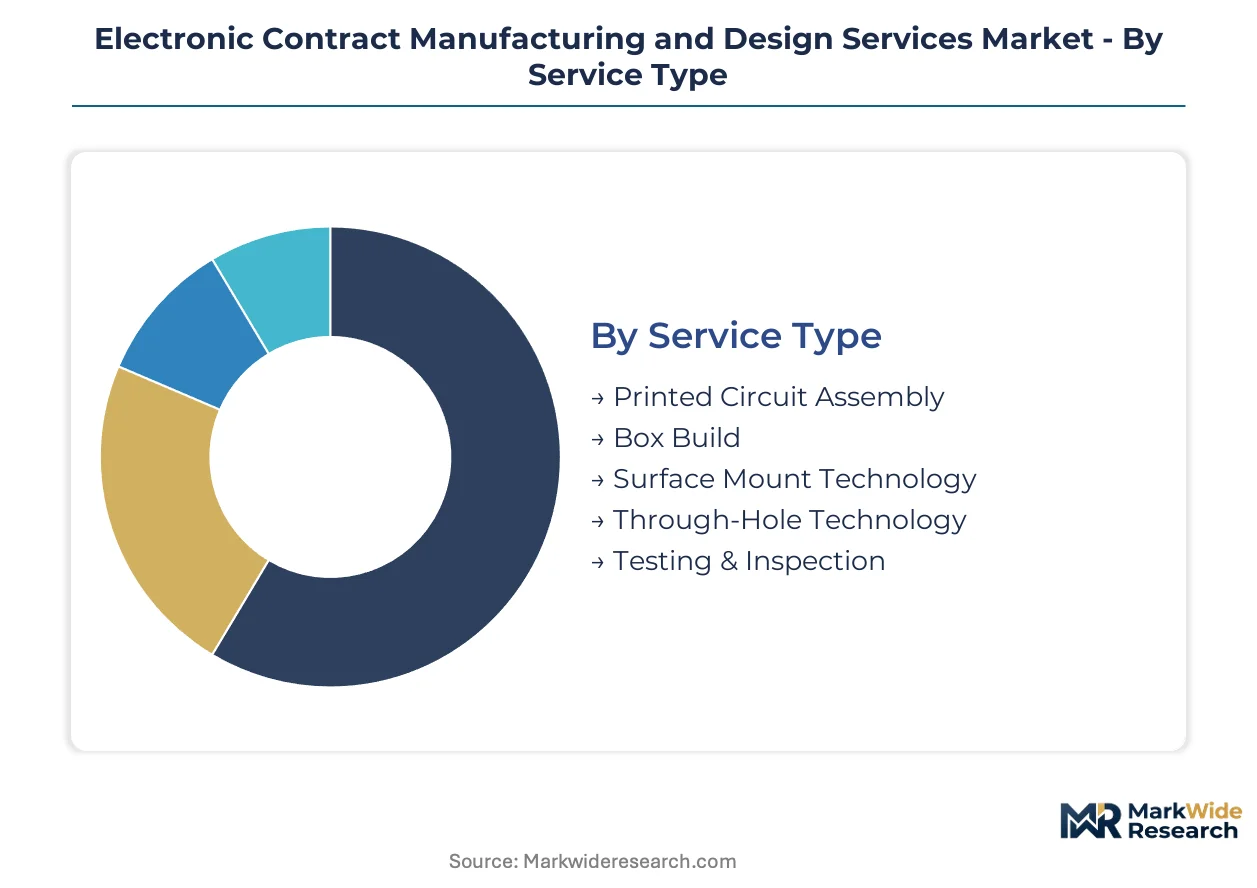
The electronic contract manufacturing and design services market segments across distinct service types, end-user industries, design offerings, and deployment models. Understanding these divisions highlights the specialized capabilities required by original equipment manufacturers. This segmentation reveals how providers tailor their extensive engineering and production expertise to diverse client needs across the value chain.
Service Type:
Margin pools within electronic contract manufacturing services are highest in complex assembly and testing. Providers differentiate through their ability to manage intricate processes and ensure product reliability.
- Box Build:This service encompasses complete assembly, integrating PCBs with enclosures, wiring, and sub-assemblies. Demand concentrates in industrial equipment and medical devices due to the need for fully functional, tested units.
- Printed Circuit Assembly:Populating bare PCBs with electronic components, using surface-mount and through-hole processes, defines printed circuit assembly. Demand is robust across consumer electronics and telecommunications, driven by sheer volume and device complexity.
- Surface Mount Technology:SMT mounts components directly onto PCBs, enabling miniaturization and higher density for electronic devices.
- Through-Hole Technology:This traditional assembly method inserts component leads through PCB holes, soldering them on the opposite side, suitable for robust components.
- Testing & Inspection:These services ensure product quality and functionality via automated optical inspection (AOI) and in-circuit testing, crucial for regulatory compliance.
The dominant share belongs to Printed Circuit Assembly, while Box Build is closing the gap fastest.
End User Industry:
Application complexity and regulatory requirements heavily influence vendor selection and service depth within the market. Each industry demands specific certifications and quality control protocols from its manufacturing partners.
- Medical Devices:This sector requires extreme precision and adherence to stringent regulatory standards like the EU's MDR and FDA quality system regulations. Demand concentrates in advanced diagnostic and therapeutic equipment, necessitating high-reliability manufacturing.
- Telecommunications:Telecommunications demands high-volume production for network infrastructure and 5G-enabled devices, often requiring specialized radio frequency (RF) expertise. Demand is robust for base station components and communication hardware.
- Consumer Electronics:This segment involves high-volume production of devices like smartphones and wearables, where cost-efficiency and rapid time-to-market are critical.
- Aerospace & Defense:This sector mandates ultra-high reliability and long product lifecycles for mission-critical systems, often with specialized materials.
- Industrial Equipment:Manufacturers seek durable electronic assemblies for factory automation and control systems, operating in challenging environments.
The medical devices sector is expanding most quickly, driven by an aging global population and technological advancements.
Design Offering:
The technology focus in design offerings determines the depth of engineering partnership between OEMs and service providers. Specialized expertise in embedded systems and firmware is particularly valuable.
- Embedded System Design:This involves developing integrated hardware and software solutions that perform dedicated functions within larger systems. Demand concentrates in automotive systems and industrial automation, where real-time control is essential.
- Firmware Development:Firmware development entails writing low-level software that directly controls hardware components, bridging hardware and higher-level applications. Demand is strong in medical devices and telecommunications equipment, requiring precise hardware interaction.
- PCB Layout:PCB layout translates electronic schematics into physical board designs, optimizing for signal integrity and manufacturability.
- Product Prototyping:Prototyping creates initial functional models for design validation, significantly accelerating the product development cycle.
- Signal Integrity Analysis:This analysis ensures electrical signal quality on high-speed PCBs, preventing data errors and ensuring reliable system performance.
Embedded System Design and Firmware Development are climbing the fastest due to the increasing complexity of integrated products.
Deployment Model:
Operational efficiency and supply chain integration define the effectiveness of various deployment models. These models dictate how electronic manufacturing services are delivered and managed.
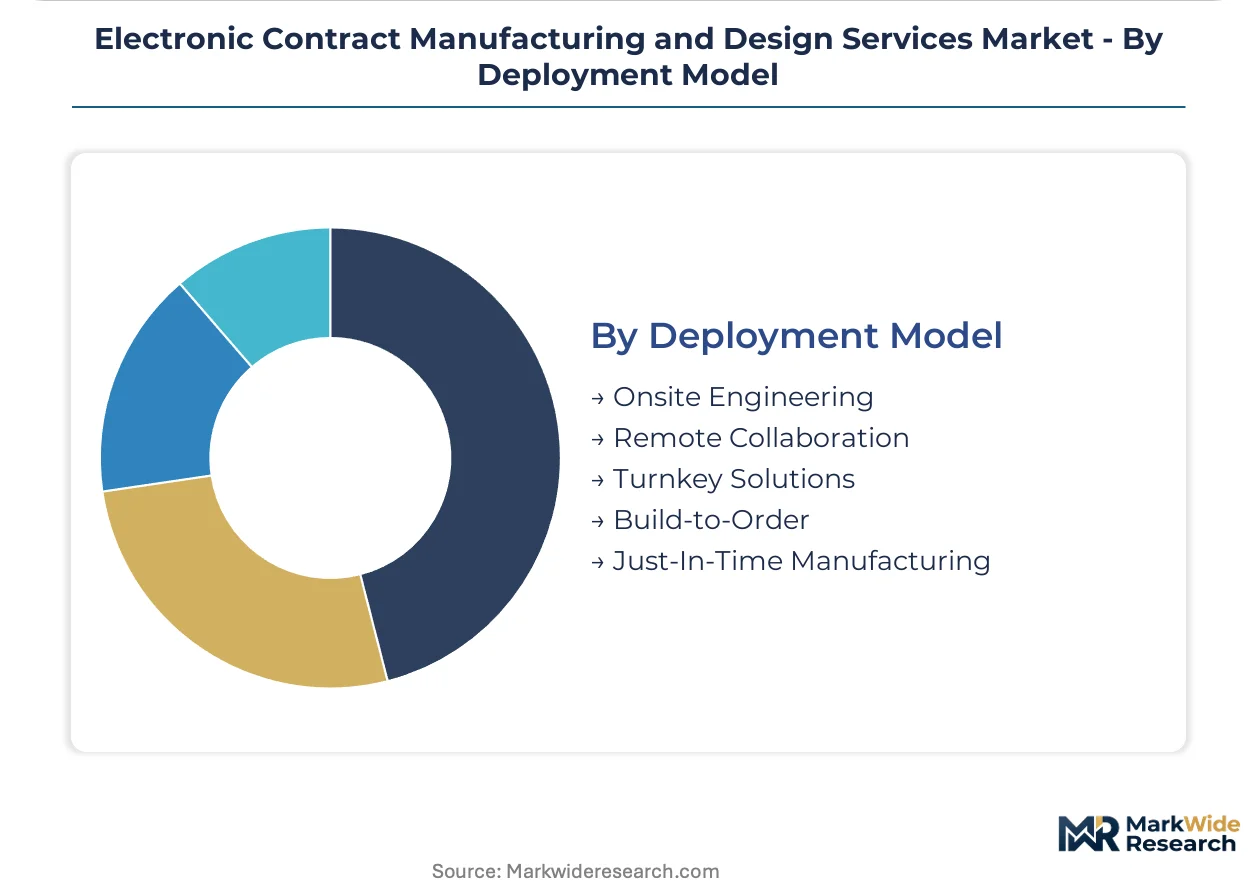
- Turnkey Solutions:Turnkey solutions provide comprehensive services from design to manufacturing, testing, and logistics, offering OEMs a single point of contact. Demand concentrates in clients seeking full outsourcing of product development and production.
- Just-In-Time Manufacturing:JIT manufacturing minimizes inventory costs by producing components or products only as needed for immediate use. Demand is pronounced in high-volume, dynamic markets like consumer electronics.
- Onsite Engineering:Onsite engineering deploys service provider engineers directly at the OEM's facility, fostering closer collaboration and problem resolution.
- Remote Collaboration:Remote collaboration uses digital tools to facilitate design and engineering work across geographically dispersed teams.
- Build-to-Order:Build-to-order allows customization based on specific customer requirements, reducing waste and catering to niche market demands.
Turnkey Solutions exhibit the steepest expansion trajectory, reflecting OEMs' desire for integrated, end-to-end service partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Food and Drug Administration (FDA) regulations heavily influence the electronic contract manufacturing and design services market, particularly for medical devices and complex integrated systems. This landscape drives demand for specialized services focusing on quality and compliance. Production and design expertise concentrate across key global hubs.
United States
United States OEMs drive demand for high-reliability electronic manufacturing, particularly in advanced medical diagnostics and aerospace systems. Adherence to FDA quality system regulations is paramount for market entry and product commercialization. Clusters in Silicon Valley and Boston innovate in embedded systems design and advanced prototyping.
Germany
Germany's robust industrial equipment and automotive sectors necessitate sophisticated electronic design and manufacturing services. Compliance with the EU's Medical Device Regulation (MDR) and CE marking is critical for medical technology providers. Production hubs in Bavaria and Baden-Württemberg focus on precision engineering for high-reliability applications.
Mexico
Mexico is emerging as a critical manufacturing hub for automotive electronics and telecommunications hardware, serving North American markets. The USMCA trade agreement facilitates cross-border supply chains, encouraging investment in local production capabilities. Tijuana and Guadalajara are developing into significant centers for box build assembly and printed circuit board manufacturing.
Vietnam
Vietnam attracts significant foreign direct investment for consumer electronics and telecommunications equipment, offering competitive manufacturing costs. Government incentives and participation in free trade agreements enhance its appeal as a production base. Industrial parks around Hanoi and Ho Chi Minh City rapidly expand capabilities in high-volume electronic assembly.
China
China remains a dominant force in electronic contract manufacturing, driven by massive domestic demand for consumer devices and industrial automation. Adherence to stringent GB standards and evolving environmental regulations like dual carbon goals shapes local operations. The Yangtze River Delta and Pearl River Delta regions concentrate immense production capacity for global OEMs.
Electronic Contract Manufacturing and Design Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the electronic contract manufacturing and design services market. The industry exhibits a tiered structure, with a few large global players dominating high-volume consumer electronics and complex industrial projects. Mid-sized specialists carve out niches in high-reliability sectors like medical devices and aerospace. Strategic partnerships and geographic expansion are primary competitive moves as firms seek to optimize supply chains and access specialized talent pools.
Specialists in high-reliability solutions, such as Celestica Inc., differentiate through stringent quality controls and advanced engineering for aerospace and medical applications. Foxconn, a Taiwanese Corporation, exemplifies the immense scale required for high-volume consumer electronics production, leveraging its vast global footprint. Jabil Inc., a US-based provider, anchors the complex supply chain management segment, serving industrial and telecommunications clients with integrated design and manufacturing services and robust lifecycle support. These firms represent distinct approaches to market penetration and value creation.
| Leading Market Players |
|---|
| Celestica |
| Sanmina Corporation |
| Foxconn |
| Zollner Elektronik |
| Benchmark Electronics |
| Flex |
| Pegatron Corporation |
| Fabrinet |
| Jabil |
| Others |
Cost & Logistics Intelligence
Immense scale economies in high-volume production, particularly for consumer electronics, shape both supply concentration and drive aggressive price floors. These efficiencies allow major players to dominate large segments while influencing overall market pricing.
Pricing Analysis
Geographic price spreads reflect regional labor costs and regulatory compliance burdens across the electronic contract manufacturing market. Pricing models primarily follow project-based and long-term contract structures for complex engagements. Price differentiation stems from certification levels, particularly for medical devices requiring FDA adherence, and the customization level for integrated design services. Cost compression in basic printed circuit assembly intensifies due to high-volume competition and material price volatility. Consumer electronics OEMs exhibit the highest price sensitivity, while medical and aerospace clients prioritize reliability over cost.
Supply Chain Analysis
China anchors global supply for consumer devices and industrial automation, leveraging its vast production capacity and established infrastructure. The market relies heavily on critical raw materials such as tin, tungsten, tantalum, and gold, alongside advanced semiconductors. A key structural risk is the geographic concentration of advanced semiconductor fabrication, exposing the value chain to supply disruptions. Downstream distribution typically flows through full turnkey solutions, integrating design, manufacturing, and logistics directly for OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the convergence of design and manufacturing services and the systemic shortage of specialized engineering talent.
For Market Incumbents: Fortify core competencies in complex project management and high-reliability manufacturing. Invest significantly in AI-driven automated optical inspection to enhance quality control and mitigate rising compliance costs. Expand aftermarket service offerings for high-value industrial and aerospace electronics, creating recurring revenue streams. This strategy helps counter margin pressure from material price volatility and talent scarcity.
For New Entrants and Emerging Players: Anchor in specialized niches that leverage specific technological expertise, such as EV battery management systems, especially in markets with government incentives like India's PLI scheme. Target OEMs struggling with the scarcity of embedded systems and firmware engineers by offering integrated design-to-manufacturing partnerships. A go-to-market angle could involve rapid prototyping and agile development for advanced diagnostic medical devices.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service providers offering integrated lifecycle management and aftermarket support. Evaluate mid-sized specialists possessing deep regulatory compliance expertise, particularly in medical devices or aerospace, as acquisition targets. A signal to watch is the increasing proportion of OEM R&D budgets allocated to external design and engineering services, indicating a deeper outsourcing trend.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Aftermarket Services | Provides recurring, high-margin revenue streams for high-value electronics. |
| Invest in AI-driven AOI | Improves manufacturing yields and reduces defect rates in complex assemblies. |
| Geographic Diversification | Mitigates geopolitical and supply chain risks by expanding production in new hubs like Mexico. |
| Develop EV BMS Capabilities | Captures substantial opportunity in the electric vehicle transition, especially in markets like India. |
| Deepen Embedded Design Expertise | Addresses the critical talent scarcity and OEM demand for integrated product development. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, industry reports, and financial disclosures. Primary interviews engaged OEM procurement leads, EMS engineering managers, supply chain directors, and regulatory compliance officers. Secondary sources included EU RoHS directive, REACH framework, Dodd-Frank Act disclosures, and FDA quality system regulations. This approach ensured robust bottom-up and top-down triangulation of market data.
Segmentation dimensions modeled included service type, end-user industry, design offering, deployment model, and regional manufacturing capacity. The analytical framework extrapolated compound annual growth rates from historical trends and projected technological adoption rates across the analysis window. Key industry-specific forecast inputs included 5G infrastructure build-out timelines and medical device regulatory changes like the EU's MDR.
Material uncertainties—geopolitical shifts, severe semiconductor supply disruptions, or rapid changes in material costs—sit outside the modeled envelope, potentially revising forecasts. Forecasts reflect assumptions documented through extensive primary and secondary research. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Global Metadata Management Tools Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Community Forum Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Transit Station Display Board Market
Digital Solutions
Virtual Office Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
North America Smart Card Market