
 Saudi Arabia ICT Market | 2026-2036
Saudi Arabia ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia ICT Market Analytics
Software-defined networking features bundled into managed service contracts is repositioning how enterprises procure connectivity across the Kingdom. Saudi Business Machines leverages its long-standing IBM partnership to dominate mainframe-to-cloud migration projects for large financial institutions. NourNet anchors its competitive stance through deep fiber infrastructure across commercial zones in Jeddah and Dammam. ELM differentiates by specializing in digital government platforms that integrate directly with national identity and payment systems.
Information and communications technology in Saudi Arabia encompasses the design, deployment, and operation of digital infrastructure including data centers with Tier III redundancy specifications, fiber-optic backbone networks exceeding 100 Gbps transmission capacity, and enterprise software systems enabling real-time transaction processing across distributed architectures. Cloud Computing services command the largest revenue pool as government entities migrate legacy workloads to compliant sovereign cloud environments. Cybersecurity demand is accelerating fastest among Financial Institutions responding to SAMA's operational resilience directives. AI adoption within Big Data Analytics segments is concentrating margin pools where vendors combine predictive modeling with Arabic natural language processing capabilities.
SAMA enforces mandatory cybersecurity frameworks for banking and insurance entities, while CITC governs spectrum allocation and data localization requirements that shape vendor qualification criteria. The National Data Management Office establishes classification protocols determining which ICT workloads must remain on-premises versus eligible for public cloud deployment. Stakeholders must monitor evolving sovereign cloud certification standards and alignment between procurement rules and emerging AI governance policies.
Market Dynamics
Sovereign cloud certification requirements under Saudi Arabia's National Data Management Office are compressing vendor qualification timelines while redirecting procurement toward domestic data center operators. This regulatory pivot is forcing international hyperscalers into joint venture structures with local license holders.
Growth Catalysts
- Vision 2030 Digital Transformation Mandates:Government agencies must migrate 60% of eligible workloads to compliant cloud environments by statutory deadlines, creating guaranteed demand pipelines for certified service providers.
- SAMA Operational Resilience Directives:Financial institutions face mandatory cybersecurity framework compliance, accelerating procurement of threat detection and incident response capabilities across Riyadh's banking district.
- AI-Native Arabic NLP:Predictive modeling combined with Arabic natural language processing capabilities is unlocking public sector automation contracts previously inaccessible to generic AI vendors.
Market Restraints
- Data Localization Hardware Costs:Tier III data center construction in the Kingdom requires imported cooling and power redundancy systems subject to supply chain volatility.
- Spectrum Allocation Bottlenecks:CITC licensing timelines for 5G enterprise private networks extend deployment schedules for industrial IoT projects in Eastern Province manufacturing zones.
- Technical Talent Scarcity:Domestic supply of cloud architects and cybersecurity specialists remains insufficient to execute the projected volume of public sector migrations.
Strategic Opportunities
- Eastern Province Industrial Corridor:Petrochemical and logistics clusters in Jubail and Dammam remain underpenetrated for edge computing and private 5G deployments.
- Converged AI-Governance Platforms:Integration of predictive analytics with national identity and payment systems creates white space for vendors combining biometric authentication with real-time fraud detection.
- Sovereign Cloud Certification:NDMO workload classification protocols favor vendors achieving early compliance, locking out uncertified competitors from government procurement pools.
Industry Challenges
- Legacy Mainframe Integration:Financial institutions running IBM zSystems require specialized migration expertise to maintain transaction integrity during cloud transitions.
- Multi-Cloud Orchestration Complexity:Government entities procuring services across multiple sovereign cloud providers face interoperability gaps in identity federation and data portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia ICT Market |
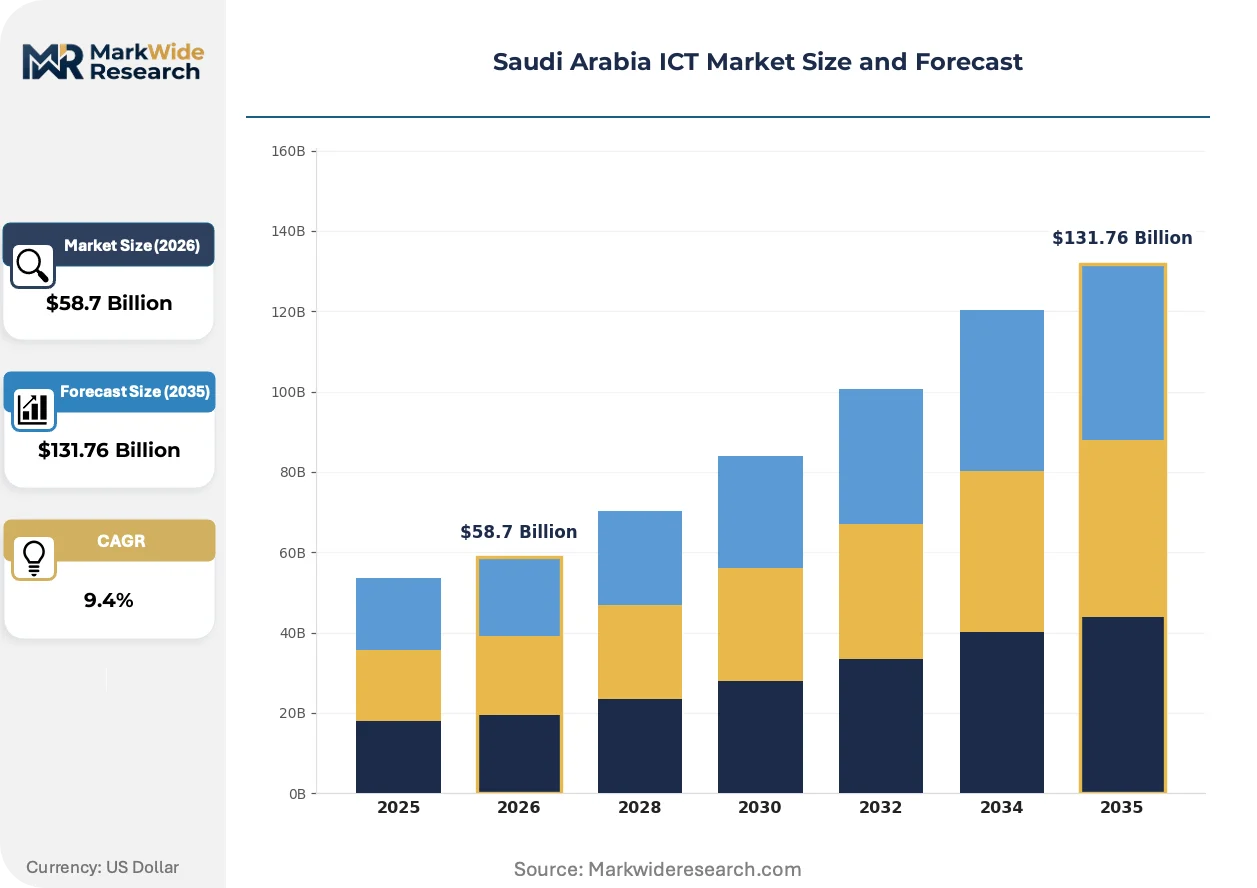
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Computing, Cybersecurity, Managed Services, Network Infrastructure Technology: AI, Big Data Analytics, IoT, Blockchain End User: Government, Healthcare Providers, Financial Institutions, Educational Institutions Deployment: On-Premises, Hybrid, Public Cloud, Private Cloud |
| Companies Covered | Al Moammar Information Systems, NourNet, TFORCE, THIQAH, Sahara Net, Esferasoft Solutions, Saudi Business Machines, Dirayaah Smart Technologies, ELM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia ICT Market Evolving Landscape
Software-defined infrastructure is dissolving traditional boundaries between network, compute, and storage procurement in Saudi enterprise environments. Vendors are bundling these capabilities into unified service contracts that displace capital-heavy ownership models.
Hyperscale edge computing deployments are electrifying latency-sensitive applications across the Kingdom. Aramco and SABIC manufacturing facilities are adopting sub-10 millisecond processing nodes for predictive maintenance and safety monitoring. This infrastructure compression is enabling real-time Arabic voice analytics in industrial control rooms without routing traffic through centralized Riyadh facilities.
SAMA's mandatory cybersecurity framework for banking entities is tightening operational resilience requirements. Financial institutions must demonstrate 24-hour incident recovery capabilities and quarterly penetration testing. Riyadh-based banks are responding by consolidating vendor relationships with managed security service providers holding local sovereign cloud certifications.
Enterprise buyers are unbundling hardware procurement from managed service obligations. Large government entities now contract connectivity and compute as separate line items, enabling multi-vendor environments. This pattern is most visible in NEOM and Red Sea Project developments where infrastructure consortiums negotiate independent relationships with fiber operators and cloud platform providers.
Saudi Arabia ICT Market Segmentation
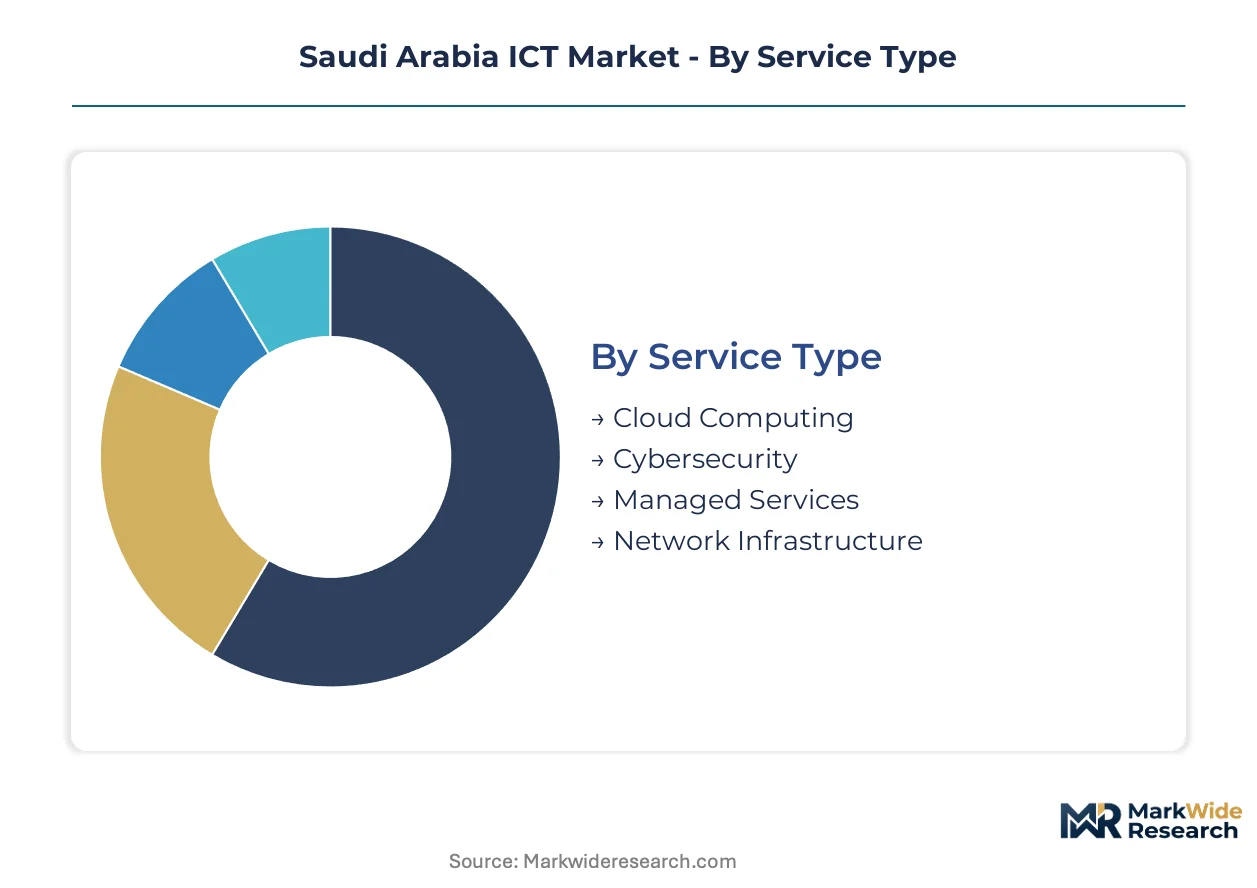
Segmentation in Saudi Arabia's ICT market reveals how regulatory certification requirements fragment procurement pathways across service types and deployment models. Understanding these divides helps vendors align qualification investments with addressable revenue pools.
Service Type:
Cloud Computing and Cybersecurity segments carry the heaviest certification burdens under SAMA and NDMO frameworks, while Managed Services and Network Infrastructure face lighter compliance thresholds.
- Cloud Computing:Sovereign cloud environments with Tier III redundancy specifications dominate government procurement. NDMO workload classification protocols mandate domestic data center presence for sensitive workloads, compressing vendor qualification timelines for international hyperscalers.
- Cybersecurity:Threat detection and incident response capabilities face mandatory SAMA operational resilience compliance. Financial institutions in Riyadh's banking district consolidate vendor relationships with providers holding local sovereign cloud certifications.
- Managed Services:Bundled software-defined networking contracts displace capital-heavy ownership models across enterprise environments.
- Network Infrastructure:Fiber-optic backbone investments exceeding 100 Gbps transmission capacity concentrate in Riyadh's technology corridor and Jeddah commercial zones.
Cloud Computing sits at the top of the volume ranking, with Cybersecurity climbing the fastest.
Technology:
Cost tier differentiation separates AI and Big Data Analytics as premium-margin segments from IoT and Blockchain as emerging investment categories with longer payback horizons.
- AI:Arabic natural language processing capabilities unlock public sector automation contracts previously inaccessible to generic vendors. Predictive modeling combined with biometric authentication creates converged AI-governance platform opportunities.
- Big Data Analytics:Real-time transaction processing across distributed architectures serves financial institutions migrating legacy workloads. Margin pools concentrate where vendors combine predictive modeling with Arabic NLP capabilities.
- IoT:Industrial deployments in Jubail and Dammam petrochemical clusters face CITC spectrum allocation bottlenecks for 5G private networks.
- Blockchain:National identity and payment system integration creates specialized demand from digital government platform vendors.
AI commands the steepest expansion trajectory, while Blockchain remains concentrated in pilot deployments.
End User:
Application intensity varies sharply across end users, with Government and Financial Institutions driving compliance-heavy procurement against Healthcare and Educational Institutions' slower digitization timelines.
- Government:Vision 2030 mandates require 60% workload migration to compliant cloud environments. Agencies procure connectivity and compute as separate line items, enabling multi-vendor environments in NEOM and Red Sea Project developments.
- Financial Institutions:SAMA's mandatory cybersecurity framework tightens operational resilience requirements with 24-hour incident recovery mandates. IBM zSystems mainframe-to-cloud migration projects demand specialized transaction integrity expertise.
- Healthcare Providers:Electronic health record systems and telemedicine infrastructure expand under Ministry of Health digitization programs.
- Educational Institutions:Learning management systems and campus connectivity upgrades proceed through phased procurement schedules.
Government represents the largest addressable base, with Financial Institutions gaining share fastest on regulatory pressure.
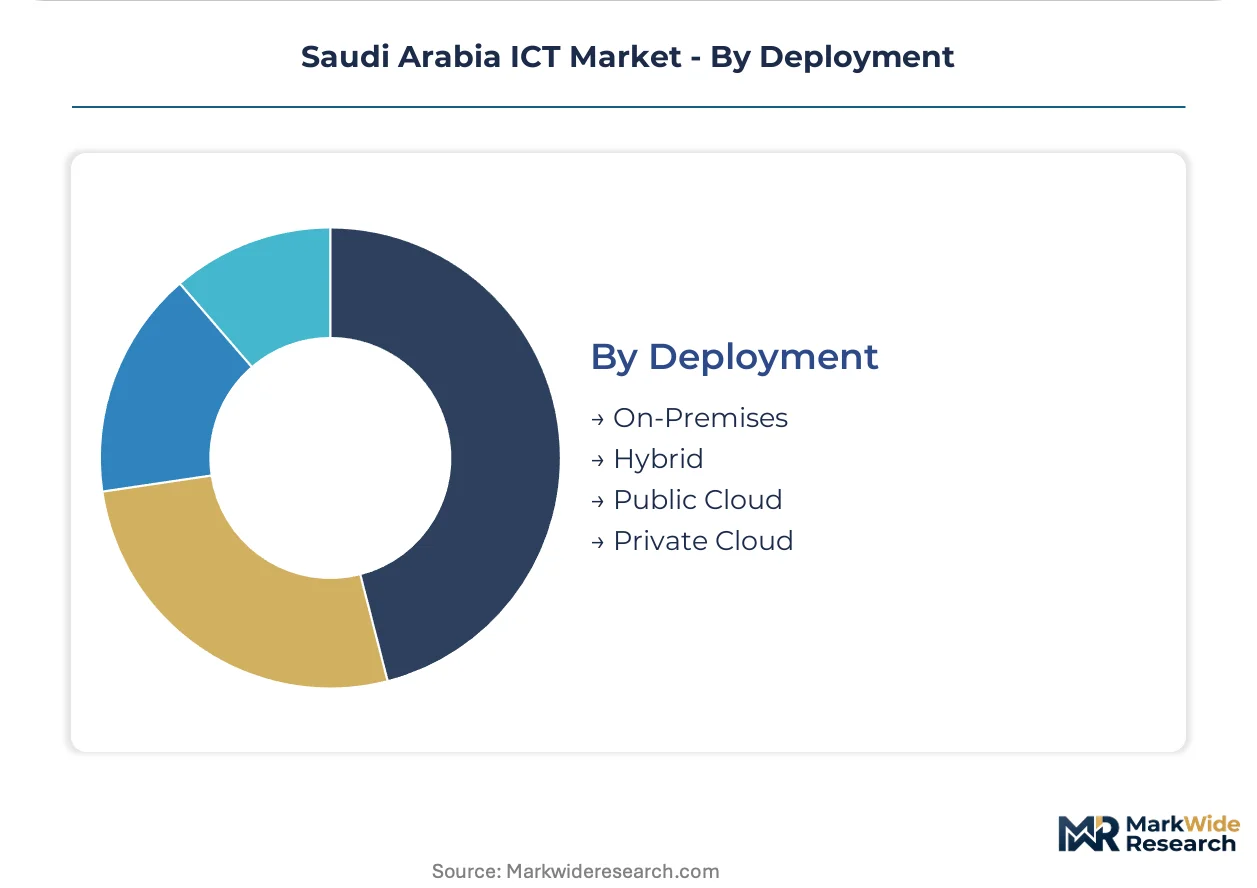
Deployment:
Customer type segmentation separates Public Cloud and Hybrid as preferred models for government and large enterprises from On-Premises and Private Cloud as residual categories for classified workloads.
- On-Premises:NDMO classification protocols mandate domestic data center presence for sensitive national security workloads. Tier III construction requires imported cooling and power redundancy systems subject to supply chain volatility.
- Hybrid:Government entities procuring across multiple sovereign cloud providers face interoperability gaps in identity federation and data portability. Multi-cloud orchestration complexity challenges centralized IT governance.
- Public Cloud:International hyperscalers enter joint venture structures with local license holders to satisfy data localization requirements.
- Private Cloud:Aramco and SABIC manufacturing facilities adopt sub-10 millisecond edge processing nodes for predictive maintenance without routing traffic through centralized Riyadh facilities.
Hybrid deployment captures the dominant procurement pattern, with Private Cloud expanding most quickly in industrial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Arab Emirates channels comparable sovereign cloud investment volumes through Dubai's Internet City cluster, yet Saudi Arabia's Eastern Province petrochemical corridor generates distinct edge computing demand patterns that diverge from Gulf Cooperation Council neighbors.
Riyadh
Government digital service consolidation and financial sector cybersecurity upgrades concentrate procurement volume in the capital region. SAMA's operational resilience directives mandate 24-hour incident recovery capabilities for banking entities headquartered in Riyadh's King Abdullah Financial District. Tier III data center construction accelerates in the technology corridor as international hyperscalers form joint ventures with local license holders to satisfy NDMO data localization requirements.
Eastern Province
Industrial IoT deployments across Jubail and Dammam petrochemical facilities drive private 5G network demand alongside sub-10 millisecond edge computing nodes. CITC spectrum allocation timelines extend deployment schedules for manufacturing automation projects in the industrial corridor. Aramco and SABIC facilities adopt predictive maintenance platforms that process Arabic voice analytics locally without routing traffic through centralized Riyadh infrastructure.
Western Region
Jeddah's commercial zones anchor fiber-optic backbone investments exceeding 100 Gbps transmission capacity for enterprise connectivity. NourNet maintains deep fiber infrastructure across this geography to serve logistics and trade finance digitization needs. Red Sea Project developments contract connectivity and compute as separate procurement line items, enabling multi-vendor infrastructure consortiums independent of single-source technology stacks.
NEOM Northwest
Greenfield smart city construction creates demand for converged AI-governance platforms integrating biometric authentication with real-time payment systems. NEOM's infrastructure procurement unbundles hardware from managed service obligations, establishing precedent for multi-cloud orchestration across sovereign cloud providers. Edge computing deployment in the northwest corridor bypasses traditional Riyadh-centric traffic routing patterns entirely.
Saudi Arabia ICT Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with systems integrators holding concentrated positions in government migration projects while connectivity providers fragment across geographic zones. The vendor base organizes around three strategic archetypes: legacy mainframe migration specialists leveraging long-standing technology partnerships, fiber infrastructure operators anchoring regional commercial zones, and digital government platform builders integrating with national identity systems. Competitive moves center on sovereign cloud certification acquisition and joint venture formation with international hyperscalers to satisfy data localization mandates.
Within the government platform specialization tier, ELM occupies a position exemplifying deep integration with national payment and identity infrastructure. Saudi Business Machines represents the legacy systems migration archetype through its established IBM partnership channel. NourNet anchors the regional infrastructure operator category with fiber concentration across Jeddah and Dammam commercial zones. These three patterns illustrate how qualification requirements under SAMA and NDMO frameworks stratify competitive positioning across the Kingdom's ICT procurement landscape.
| Leading Market Players |
|---|
| Al Moammar Information Systems |
| NourNet |
| TFORCE |
| THIQAH |
| Sahara Net |
| Esferasoft Solutions |
| Saudi Business Machines |
| Dirayaah Smart Technologies |
| ELM |
| Others |
Value Network & Pricing Analysis
Imported cooling equipment and power redundancy system indices cascade through Tier III data center construction costs, stratifying service pricing across sovereign cloud certification tiers as domestic operators absorb supply volatility while international hyperscalers joint-venture into compliance.
Pricing Analysis
Capacity additions in Riyadh's technology corridor are reshaping price floors for managed connectivity services. Three-tier pricing structure across premium sovereign-certified, standard compliant, and economy non-certified levels separates procurement pools. Certification grade and volume scale drive price differentiation, with cost compression in standard tiers intensifying as domestic operators expand capacity. Government entities show lowest price sensitivity due to mandated compliance deadlines, while mid-market enterprises exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from NDMO and SAMA frameworks mandate multi-supplier qualification for critical infrastructure components. Hardware supply concentrates in the United States, Germany, and Japan for precision cooling and power systems. Raw material dependencies span semiconductor chips, rare earth elements for magnetics, and copper for high-capacity fiber. Single-source vulnerability persists for specialized mainframe migration expertise. Distribution runs through systems integrators holding sovereign cloud certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi Arabia's ICT market rests on certification-driven tier premiums and operational leverage from workload consolidation, compressing cost-to-serve as automation scales across Arabic NLP-enabled platforms.
For Market Incumbents: Anticipate hyperscaler joint-venture pressure by deepening sovereign cloud certification portfolios and locking multi-year government migration contracts before qualification windows compress. Vertical integration into edge computing infrastructure across the Eastern Province industrial corridor defends position against fiber operators expanding beyond connectivity. For New Entrants and Emerging Players: Begin with underpenetrated petrochemical automation in Jubail and Dammam, where CITC spectrum allocation delays have stalled incumbent 5G private network deployments. Target converged AI-governance platforms integrating biometric authentication with SAMA-compliant fraud detection as the most penetrable wedge, using sovereign cloud certification as the go-to-market anchor. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier systems integrators possessing NDMO certification pathways and established government contracting relationships. Long-term viability favors vendors combining mainframe migration expertise with sovereign cloud operational scale. Watch CITC spectrum allocation acceleration for Eastern Province industrial zones as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acquisition | NDMO compliance locks vendors into guaranteed government procurement pipelines under Vision 2030 migration mandates. |
| Hyperscaler Joint Venture Formation | International cloud operators partner with local license holders to satisfy data localization requirements and compress market entry timelines. |
| Edge Computing Infrastructure Buildout | Sub-10 millisecond processing nodes in Aramco and SABIC facilities bypass Riyadh-centric routing for predictive maintenance. |
| Arabic NLP Capability Development | Predictive modeling combined with natural language processing unlocks public sector automation contracts inaccessible to generic AI vendors. |
| Multi-Cloud Orchestration Platform Launch | Identity federation and data portability solutions address interoperability gaps as government entities procure across sovereign cloud providers. |
Research Methodology
Direct dialogue with cloud platform engineers, government IT procurement officers, cybersecurity specialists at financial institutions, and systems integration architects combined with secondary validation from CITC regulatory filings, SAMA operational resilience directives, NDMO workload classification protocols, and hyperscaler capex disclosures. Bottom-up service provider revenue aggregation triangulates against top-down government budget allocation analysis.
Segment-level outputs across the projection horizon reflect modeled deployment patterns by service type, technology tier, end-user vertical, and regional adoption cluster. CAGRs derive from regression analysis against Vision 2030 milestone timelines and SAMA compliance deadline schedules. Forecast inputs incorporate sovereign cloud certification pipeline visibility and spectrum allocation timeline probability distributions.
Several conditions sit outside the modeled scope, including CITC regulatory acceleration or delay, geopolitical disruption to semiconductor supply chains, and SAMA cybersecurity framework scope expansion. Deviation in hyperscaler joint-venture formation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Data Catalog Market
Digital Solutions
Global Metadata Management Tools Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Australia ICT Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Canada ICT Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Revenue Management Software Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
North America Managed Mobility Service Market