
 Master Data Management Market | 2026-2036
Master Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Master Data Management Market Intelligence
Cloud-native, business-led adoption is unwinding the historical dominance of large-scale, IT-centric implementations in the master data management space. Informatica leverages its comprehensive suite for complex, enterprise-wide deployments. In contrast, Semarchy specializes in agile, user-focused solutions that empower business departments. Oracle competes through deep integration with its existing database and application ecosystem, offering a bundled value proposition to its large installed base.
Master Data Management involves creating a single, authoritative source of truth for critical business data like customer, product, or supplier information. This process utilizes data modeling, synchronization, and governance rules to ensure consistency and accuracy across disparate enterprise systems. Solutions for Data Governance and Data Quality are foundational, while Customer Data Management applications see high investment. Cloud-based deployment models are rapidly gaining share over traditional on-premises installations due to superior scalability and operational flexibility.
Data privacy regulations, including Europe's GDPR and California's CCPA, mandate accurate and auditable master data for compliance. In the financial sector, adherence to frameworks like the Sarbanes-Oxley Act (SOX) in the United States also necessitates robust financial data management. Consequently, vendor selection increasingly hinges on the platform's ability to manage data sovereignty and navigate complex cross-border data flow requirements.
Market Dynamics
The central force shaping the market is the decentralization of data ownership from central IT departments to individual business units. This shift is driven by the availability of cloud-native, user-friendly MDM platforms that empower non-technical users to manage their own data domains.
Growth Catalysts
- Stringent Data Privacy Mandates:Regulations like the EU's GDPR require organizations to maintain a single, accurate, and auditable record for every individual. This directly compels investment in customer data management solutions to ensure compliance and manage consent.
- BFSI Sector Compliance:Financial institutions adopt MDM to meet strict regulatory reporting standards, such as those stipulated by the Sarbanes-Oxley Act (SOX) in the United States, which demand impeccable accuracy in financial and customer data.
- Cloud Model Accessibility:The proliferation of cloud-based deployment models lowers the barrier to entry for small and medium-sized enterprises. These scalable, subscription-based solutions eliminate the need for large upfront capital expenditure on on-premises infrastructure.
Market Restraints
- High Total Cost of Ownership:Large-scale, on-premises MDM implementations involve significant costs beyond software licensing, including hardware, integration services, and ongoing maintenance, which can be prohibitive for many organizations.
- Legacy System Integration:The complexity of synchronizing master data across a heterogeneous landscape of decades-old legacy applications and modern cloud services presents a significant technical barrier and can delay project timelines.
- Point Solution Substitution:The market faces competition from specialized tools like Customer Data Platforms (CDPs) or Product Information Management (PIM) systems, which are perceived as simpler, faster-to-deploy alternatives for a single data domain.
Strategic Opportunities
- ESG Data Management:An emerging opportunity exists in providing MDM solutions tailored for Environmental, Social, and Governance data. This supports new corporate reporting requirements, such as the EU's Corporate Sustainability Reporting Directive (CSRD).
- AI-Powered Data Stewardship:The integration of artificial intelligence and machine learning offers significant potential for automating data quality checks, anomaly detection, and the resolution of data conflicts, reducing manual effort.
- Expansion in Southeast Asia:Rapid digitalization and e-commerce growth in Southeast Asian economies present an underpenetrated market for MDM solutions as local enterprises seek to centralize customer and product information.
Industry Challenges
- Data Architect Talent Scarcity:A persistent shortage of skilled data architects and experienced data stewards capable of designing and governing complex, enterprise-wide MDM programs remains a primary operational constraint for adopters.
- Hybrid Environment Complexity:Maintaining data consistency and synchronization between on-premises systems and multiple public cloud environments creates significant architectural and governance challenges for IT teams.
- Navigating Data Sovereignty:Managing master data across jurisdictions with conflicting data residency and cross-border transfer laws, particularly between the United States, Europe, and China, adds legal and operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Master Data Management Market |
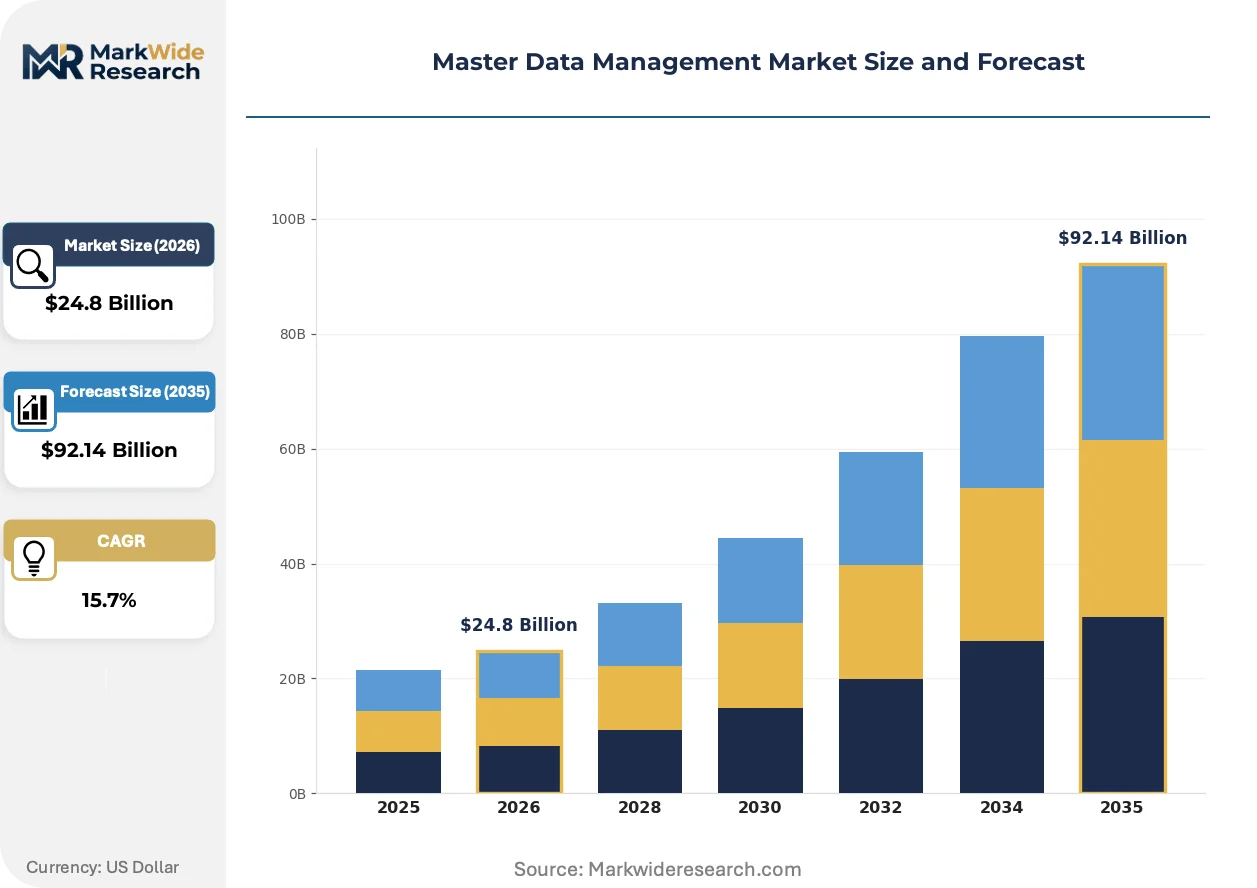
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $92.14 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
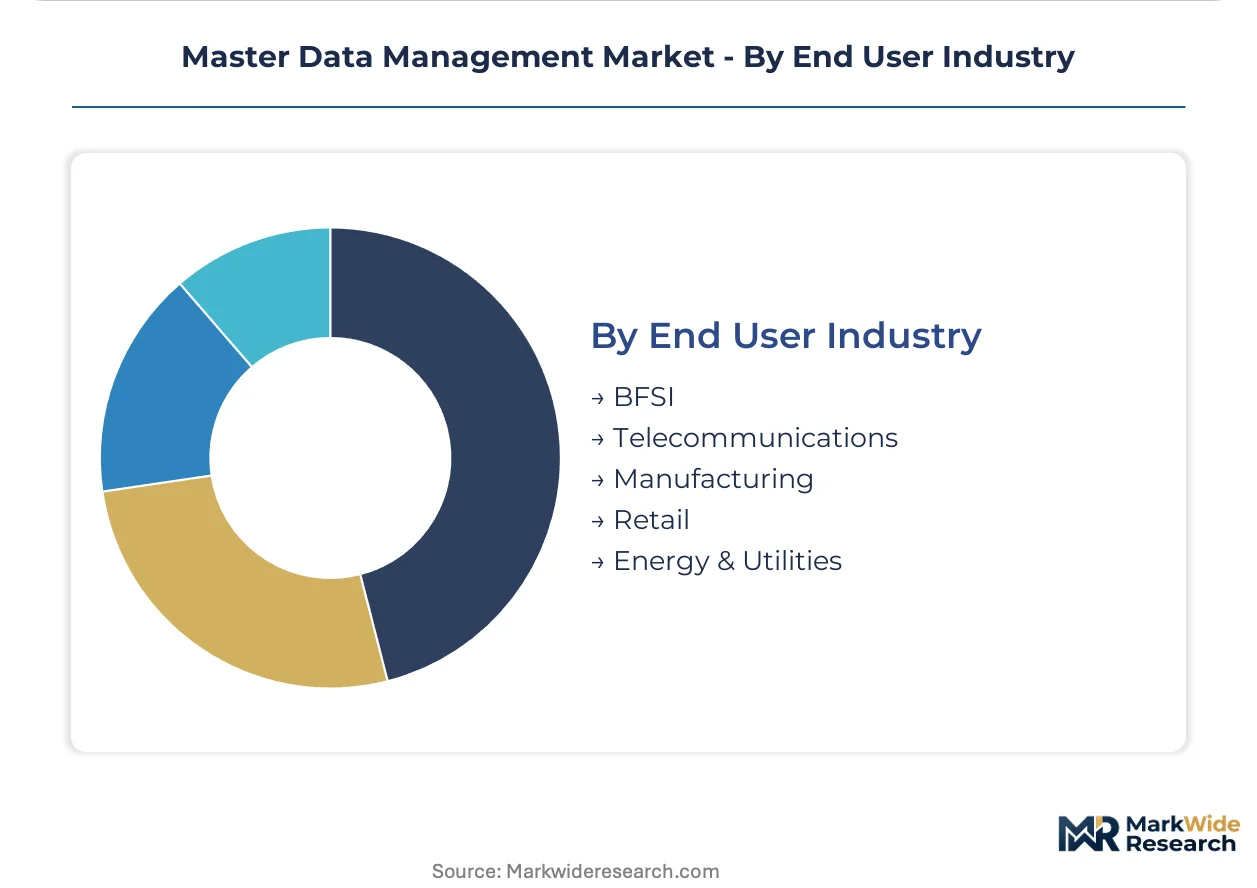
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Hosted Solution Type: Data Governance, Data Integration, Data Quality, Data Stewardship, Metadata Management Application: Customer Data Management, Product Data Management, Supplier Data Management, Employee Data Management, Financial Data Management End User Industry: BFSI, Telecommunications, Manufacturing, Retail, Energy & Utilities |
| Companies Covered | Informatica, IBM, Semarchy, SAP, Oracle, Ataccama, Microsoft, Accenture, Profisee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Master Data Management Market Strategic Shifts & Innovations
The evolution of master data management is defined by a push towards greater intelligence and accessibility. Platforms are transforming from passive, IT-managed repositories into active, business-centric hubs that leverage automation to deliver tangible data insights and operational efficiencies.
AI-augmented data management incorporates machine learning algorithms to automate core tasks like data discovery, matching, and cleansing. Business functions like marketing and supply chain management are adopting these intelligent tools to gain direct control over their respective data domains. This technological shift is decomposing the traditional monolithic MDM platform into a more agile and modular set of intelligent data services.
California's Consumer Privacy Act (CCPA) and its successor, the CPRA, mandate that businesses provide consumers with a clear view of the data collected about them. This regulation compels organizations to establish a unified, authoritative profile for each customer to efficiently process data access and deletion requests. The retail and e-commerce sectors are most affected, driving their investment in customer master data hubs to ensure compliance.
A clear behavioral shift sees enterprises moving from large, single-vendor contracts toward a more flexible, domain-specific procurement model. This disrupts the bundled suite approach, as buyers now prefer to select best-of-breed solutions for distinct domains like customer, product, or supplier data. This pattern is particularly prominent in the fast-moving technology and financial services sectors, where data agility is a critical capability.
Master Data Management Market Segmentation

The Master Data Management market exhibits diverse solution requirements and deployment preferences across various enterprise environments. Understanding these segmented demands is crucial for providers to align their offerings with specific operational needs and regulatory pressures.
Deployment:
The choice of deployment model often faces substitution pressure from newer, more flexible alternatives that offer reduced infrastructure overhead.
- Cloud:This model delivers MDM solutions via the internet, offering superior scalability, operational flexibility, and lower upfront capital expenditure. Small and medium-sized enterprises increasingly adopt cloud-based MDM for its accessibility and subscription-based cost structure.
- On-Premises:Enterprises deploy on-premises MDM solutions within their own data centers, providing maximum control over data security, customization, and integration with existing legacy systems. Organizations with stringent data residency requirements often prefer this model.
- Hybrid:This deployment combines elements of both on-premises and cloud environments, allowing businesses to manage sensitive data locally while leveraging cloud scalability for other data domains. Hybrid deployments address complex integration challenges.
- Hosted:Third-party providers manage MDM infrastructure and software, offering a dedicated environment that balances control with reduced internal IT burden. This model appeals to organizations seeking managed services.
On-Premises retains volume leadership; Cloud holds the steepest expansion curve.
Solution Type:
Organizations prioritize solutions based on their immediate data challenges and the maturity of their data management frameworks.
- Data Quality:These solutions ensure the accuracy, completeness, consistency, and validity of master data across disparate systems. Data Quality tools are foundational for regulatory compliance and reliable business analytics.
- Data Governance:This solution type establishes policies, processes, and responsibilities for managing data assets, ensuring compliance with regulations like GDPR and the Sarbanes-Oxley Act. Data Governance provides an auditable framework for data usage.
- Data Integration:Data Integration tools connect various enterprise systems, enabling the seamless flow and synchronization of master data. These solutions are critical for creating a unified view across complex IT landscapes.
- Data Stewardship:These tools support human oversight and management of data assets, facilitating collaboration between business and IT teams to resolve data issues. Data Stewardship ensures ongoing data accuracy.
- Metadata Management:This solution focuses on managing information about data, such as its definition, source, and relationships, which enhances data discoverability and understanding. Metadata Management aids in data lineage tracking.
While Data Governance establishes foundational rules, Data Quality solutions directly enhance operational reliability.
Application:
The maturity of data management practices often dictates the initial application focus within enterprises, addressing the most pressing business needs.
- Customer Data Management:This application focuses on creating a single, authoritative view of customer information across all touchpoints, crucial for personalized marketing and regulatory compliance under CCPA. Retail and e-commerce sectors extensively utilize this for engagement.
- Financial Data Management:These solutions centralize and standardize financial data, ensuring accuracy for regulatory reporting, auditing, and financial analysis. The BFSI sector heavily relies on this for compliance with frameworks like SOX.
- Product Data Management:This application manages comprehensive information about products, including specifications, pricing, and marketing attributes, supporting efficient product launches and inventory management. Manufacturing and retail benefit significantly.
- Supplier Data Management:These solutions consolidate and maintain accurate information about suppliers, optimizing procurement processes, managing contracts, and mitigating supply chain risks. Supply chain-intensive industries prioritize this.
- Employee Data Management:This application centralizes human resources data, streamlining HR operations, ensuring compliance with labor laws, and supporting workforce analytics. Large organizations with complex HR structures leverage this.
Customer Data Management remains a strategic imperative for market engagement, while Financial Data Management underpins corporate accountability.
End User Industry:
Industry-specific regulatory burdens and data volumes dictate the scale and urgency of MDM adoption across different sectors.
- BFSI:The Banking, Financial Services, and Insurance sector implements MDM for stringent regulatory compliance, risk management, and accurate financial reporting. Regulations like GDPR and SOX drive significant investment.
- Retail:The retail sector adopts MDM to manage complex customer profiles, product catalogs, and supply chain data, supporting personalized marketing and efficient inventory management. E-commerce growth accelerates MDM adoption.
- Telecommunications:Telecommunication companies use MDM to consolidate customer data, service information, and network assets, enhancing customer experience and operational efficiency. Managing subscriber data is a primary driver.
- Manufacturing:This industry leverages MDM for product lifecycle management, supply chain optimization, and managing complex Bill of Materials (BOMs). Accurate product data ensures production quality and efficiency.
- Energy & Utilities:These organizations utilize MDM for managing asset data, customer information, and operational parameters, optimizing resource allocation and ensuring regulatory compliance. Infrastructure management is critical.
The BFSI sector continues to drive significant MDM demand, with Retail and E-commerce demonstrating rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a primary innovator in enterprise software, influences master data management adoption across global markets. Demand for robust data governance and compliance solutions drives market activity. This market expansion reflects evolving regulatory landscapes and digital transformation initiatives worldwide.
United States
United States organizations prioritize master data management for compliance with complex financial regulations and consumer privacy laws. The Sarbanes-Oxley Act (SOX) and the CCPA mandate precise data handling for financial and customer records. Technology and finance hubs in California and New York drive significant investment in advanced MDM platforms.
Germany
German enterprises adopt master data management to meet stringent data privacy mandates and enhance industrial operational efficiency. The EU's GDPR requires robust data governance for customer information across sectors. Manufacturing and automotive clusters in Bavaria and Baden-Württemberg centralize product and supplier data.
India
Rapid digitalization and e-commerce expansion in India fuel demand for scalable master data management solutions. The country's evolving data protection regulations compel organizations to ensure data accuracy and compliance. IT and financial services hubs in Bengaluru and Mumbai are adopting cloud-based MDM for customer and financial data.
Japan
Japanese enterprises focus on master data management to optimize operational efficiency and ensure high data quality across complex systems. Japan's Act on Protection of Personal Information (APPI) drives investment in customer data platforms. Manufacturing centers in the Kanto region and Kansai prioritize product and supplier data synchronization.
Brazil
Brazilian businesses are increasingly adopting master data management to support digital transformation initiatives and financial sector modernization. Brazil's Lei Geral de Proteção de Dados (LGPD) necessitates robust customer data governance across industries. Financial and industrial hubs in São Paulo and Rio de Janeiro are centralizing their customer and product information.
Master Data Management Market Key Industry Players
Player mix skews toward large enterprise suite providers, alongside specialized agile solution vendors. The market exhibits a tiered structure, with established technology giants offering comprehensive platforms. Niche players focus on specific data domains or deployment models, catering to business-led adoption. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Within the enterprise-grade solution tier, Informatica and Oracle exemplify providers offering broad, integrated platforms for complex deployments. Informatica leverages its comprehensive suite for large-scale, IT-centric implementations across diverse industries, focusing on data quality and governance. Oracle competes by integrating MDM deeply within its extensive database and application ecosystem, serving its established customer base with bundled value propositions. Semarchy represents the agile, user-focused segment, specializing in solutions that empower business departments with self-service data management capabilities and faster time-to-value.
| Leading Market Players |
|---|
| Informatica |
| IBM |
| Semarchy |
| SAP |
| Oracle |
| Ataccama |
| Microsoft |
| Accenture |
| Profisee |
| Others |
Cost & Logistics Intelligence
Typical MDM implementation lead times, often extending to several months, directly influence both supply chain flexibility for service providers and the pricing power of integrated solution vendors. Complex integration with legacy systems often extends project durations, impacting resource allocation and client costs.
Pricing Analysis
The pricing gap between current-generation cloud-native MDM platforms and legacy on-premises solutions reflects differing value propositions. Dominant pricing structures are subscription-based SaaS tiers, varying by data volume, user count, and feature set. Price differentiation stems from the level of customization required and the extent of after-sales support provided. Pricing pressure intensifies due to the availability of modular point solutions like CDPs, which offer perceived faster time-to-value for single data domains. Small and medium-sized enterprises are generally the most price-sensitive segment, while large enterprises prioritize comprehensive functionality and integration.
Supply Chain Analysis
Just-in-time software delivery models dominate the MDM market, emphasizing rapid deployment and continuous updates rather than physical inventory. Geographic supply concentration for development and support talent centers in the United States, India, and Ireland. The market primarily depends on a consistent supply of skilled data architects and reliable cloud infrastructure services from hyperscalers. A key structural supply chain risk is the persistent talent scarcity for experienced data stewards capable of governing complex MDM programs. Distribution predominantly runs through direct sales channels and a network of specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Master Data Management market functions as a substitution defense, as incumbents must navigate the threat posed by specialized point solutions like Customer Data Platforms.
For Market Incumbents: Shield core platforms by deepening integration with emerging AI-powered data stewardship tools. Consolidate market share through strategic acquisitions of niche providers specializing in ESG data management or specific cloud environments. Invest heavily in R&D for automation features to counter the agility of point solutions. This mitigates the threat from faster-to-deploy alternatives.
For New Entrants and Emerging Players: Lead with agile, user-focused solutions targeting underpenetrated segments like small and medium-sized enterprises. Focus on white-space opportunities in ESG data management and AI-powered data quality automation. Expand into rapidly digitalizing geographies such as Southeast Asia, offering cloud-based, subscription models. A go-to-market angle emphasizing rapid deployment and business-user empowerment will be critical.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-driven efficiency play because stringent data privacy regulations and corporate reporting mandates will continue to compel MDM adoption. Target acquisition archetypes include agile, cloud-native MDM providers with strong AI capabilities or deep vertical expertise in financial services. The signal to watch is the widespread adoption of new regulatory frameworks like the EU's CSRD across diverse industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for Data Stewardship | Automates data quality and conflict resolution, reducing manual effort for enterprise users. |
| Acquire Niche Cloud MDM Specialist | Expands platform capabilities for specific data domains and enhances multi-cloud deployment expertise. |
| Develop ESG Data Management Modules | Addresses new corporate reporting requirements under directives like the EU's CSRD. |
| Expand in Southeast Asian Markets | Captures demand from rapidly digitalizing economies for centralized customer and product data. |
| Form Strategic Partnerships with Hyperscalers | Enhances cloud-native MDM offerings with superior scalability and operational flexibility. |
Research Approach
A spread of perspectives from CTOs, data governance officers, IT procurement leads, and system integrators converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders informed qualitative insights, validated against extensive secondary research. Secondary sources included SEC 10-K filings, industry association reports, and academic research. Bottom-up and top-down triangulation ensured data consistency and market sizing accuracy.
Segmentation dimensions modeled include deployment, solution type, application, end user industry, and organizational size. An analytical framework projected market trajectory across the analysis window. Compound annual growth rates were derived from historical trends and anticipated future demand drivers. Industry-specific forecast inputs included regulatory compliance spending and cloud adoption rates across various sectors.
The analysis sits within stated boundaries; outcomes outside significant shifts in data privacy laws or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions documented through extensive research. Revision becomes warranted when market dynamics or regulatory environments cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Turkey ICT Market
Digital Solutions
UK Route Optimization Software Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Data Governance Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Product As a Service Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Global Referral Management Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Kenya ICT Market