
 Electronic Data Interchange (EDI) Market | 2026-2036
Electronic Data Interchange (EDI) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Data Interchange (EDI) Market Foresight
Platform licensing revenue is rewriting profit dynamics across the EDI value chain. E2open, LLC leverages its network-centric architecture to anchor multi-enterprise supply chain visibility. SPS Commerce, Inc. dominates cloud-based retail onboarding with a fully managed service model. OpenText Corporation sustains broad integration capabilities spanning legacy on-premises systems and modern API endpoints.
Electronic Data Interchange constitutes a structured, standards-based transmission protocol—typically using ANSI X12, EDIFACT, or TRADACOMS formats—to exchange business documents between computer systems without human intervention. Its primary commercial purpose centers on automating procurement, invoicing, and logistics workflows to reduce transaction errors and accelerate order-to-cash cycles. Cloud-based deployment now leads new implementations as enterprises abandon server maintenance burdens, while API services represent the fastest-growing solution category as organizations demand real-time connectivity beyond batch-file exchange. Managed services retain the deepest margin pools by embedding compliance expertise and ongoing mapping support into recurring contracts.
FDA 21 CFR Part 11 requirements shape validation protocols for pharmaceutical EDI transactions, while HIPAA transaction and code set standards enforce format consistency across US healthcare exchanges. The EU AI Act and GDPR frameworks increasingly influence how European EDI platforms handle automated decision-making and cross-border data flows. Stakeholders must weigh interoperability investments against emerging regulatory fragmentation as jurisdictions diverge on data sovereignty and algorithmic transparency mandates.
Market Dynamics
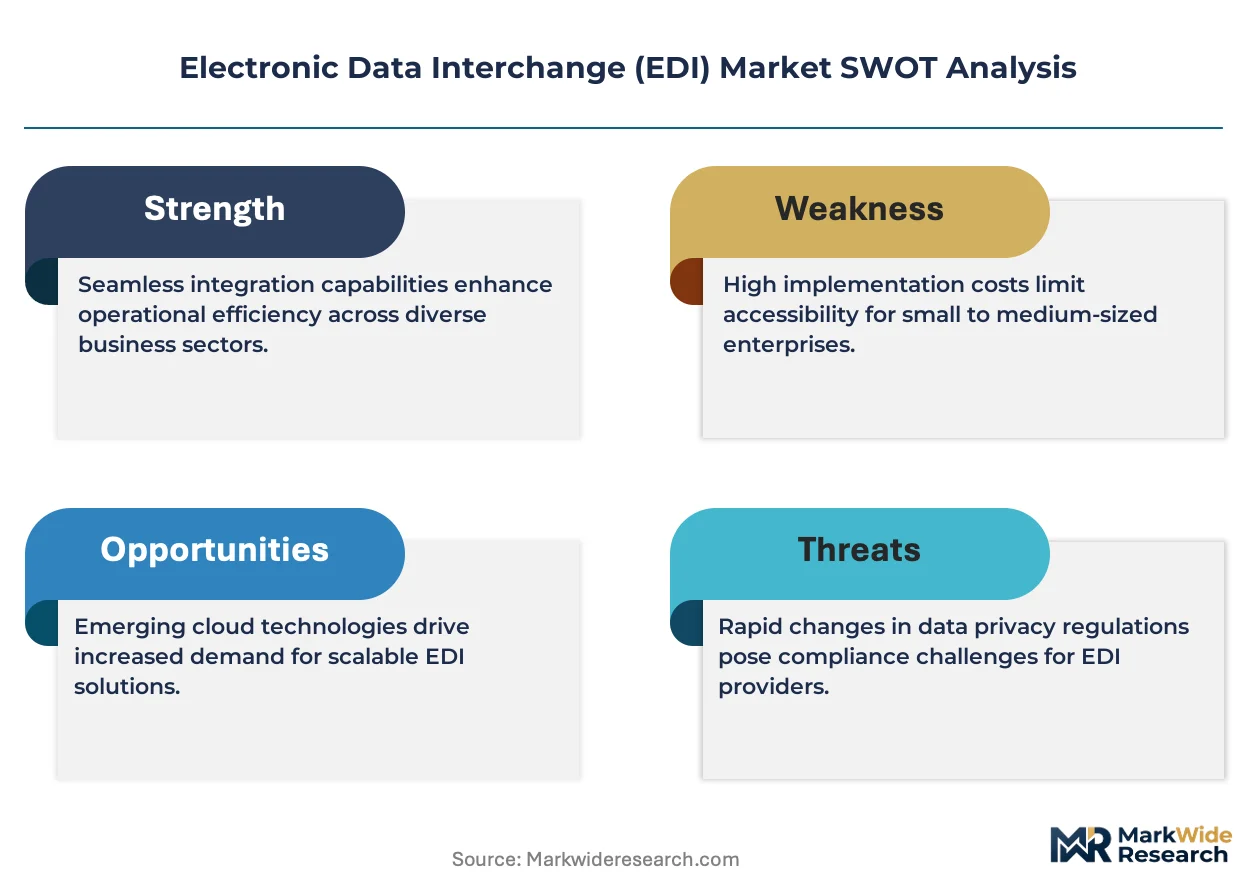
Cloud migration is compressing deployment timelines and forcing traditional on-premises EDI vendors to rearchitect their delivery models around subscription economics. This shift is redistributing margin pools toward managed service layers and API connectivity infrastructure.
Growth Catalysts
- HIPAA Transaction Mandates:US healthcare providers must maintain ANSI X12-compliant electronic formats for claims processing, creating baseline demand for certified EDI infrastructure across hospitals and insurers.
- API-First Architectures:Real-time inventory synchronization requirements from omnichannel retailers are displacing batch-file exchange protocols in procurement workflows.
- Mid-Market Cloud Adoption:Enterprises in Germany, Japan, and Brazil are abandoning server maintenance burdens for fully managed cloud EDI services.
Market Restraints
- Mapping Complexity Costs:Each trading partner requires custom data transformation rules, inflating implementation timelines and professional services dependencies.
- Legacy System Entrenchment:AS/400 and mainframe-based EDI installations in industrial manufacturing create switching friction that delays modernization cycles.
- Regulatory Fragmentation:Divergent data sovereignty requirements between GDPR, China's PIPL, and sector-specific mandates complicate cross-border platform architecture.
Strategic Opportunities
- Healthcare Interoperability Expansion:FDA 21 CFR Part 11 validation protocols for pharmaceutical supply chains create specialized service revenue pools.
- AI-Assisted Mapping:Machine learning tools are converging with traditional translation engines to automate partner onboarding and reduce manual configuration.
- SME Channel Development:Pre-configured industry templates and self-service portals open underpenetrated segments currently served by manual processes.
Industry Challenges
- EDI Specialist Talent Scarcity:Deep expertise in X12 and EDIFACT standards is concentrating among aging practitioner cohorts, constraining implementation capacity.
- Multi-Standard Integration Burden:Simultaneous support for ANSI X12, EDIFACT, TRADACOMS, and emerging JSON/XML APIs fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Data Interchange (EDI) Market |
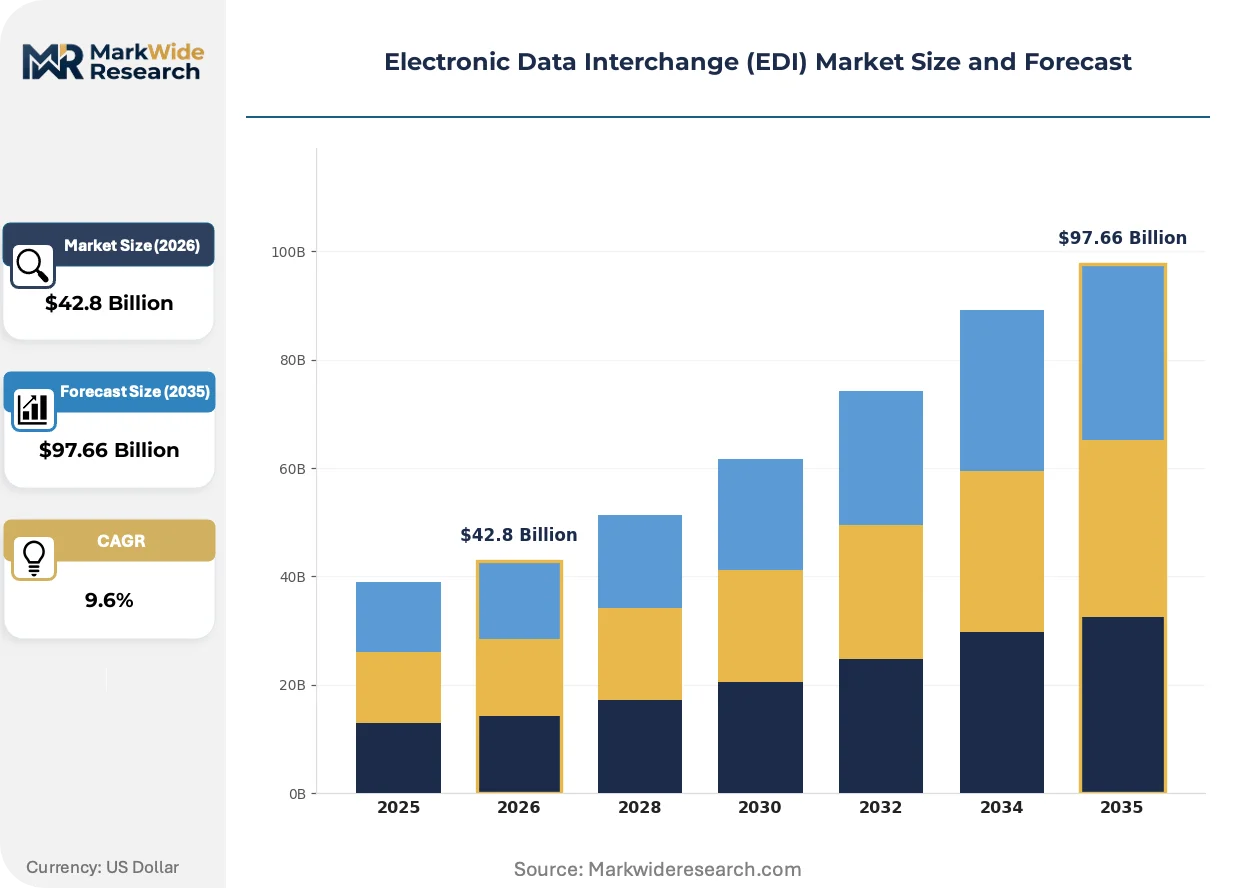
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $97.66 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Retail Transactions, Invoicing, Inventory Management Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Industry Vertical: Healthcare, Manufacturing, Retail, Transportation Solution: Integration Platforms, Managed Services, EDI Software, API Services |
| Companies Covered | E2open, LLC, Cleo Communications LLC, OpenText Corporation, DiCentral, LLC, Axway Software SA, International Business Machines Corporation, TrueCommerce Holdings, LLC, DataTrans Solutions Inc., SPS Commerce, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Data Interchange (EDI) Market Shifts & Advancements
Real-time connectivity requirements are dissolving the boundary between traditional batch EDI and synchronous API exchange, forcing platform vendors to unify disparate protocol stacks under single management layers.
Modern EDI platforms are hybridizing legacy translation engines with cloud-native microservices architectures. Automotive and aerospace manufacturers with complex supplier networks are adopting these blended stacks fastest. This convergence is compressing the distinction between on-premises and SaaS deployment models.
The EU AI Act's risk classification framework is reshaping how European EDI platforms handle automated decision-making in supply chain workflows. High-risk applications now require documented algorithmic transparency and human oversight protocols. German automotive suppliers and French pharmaceutical distributors are restructuring their validation documentation to meet these requirements.
Buyer procurement patterns are rotating toward consumption-based pricing for EDI services rather than fixed annual contracts. Mid-market retailers and third-party logistics providers are driving this shift, preferring per-transaction or per-document fees that align costs with actual trading volume. This preference is most visible in US and UK markets where CFO scrutiny of technology spend has intensified.
Electronic Data Interchange (EDI) Market Segmentation
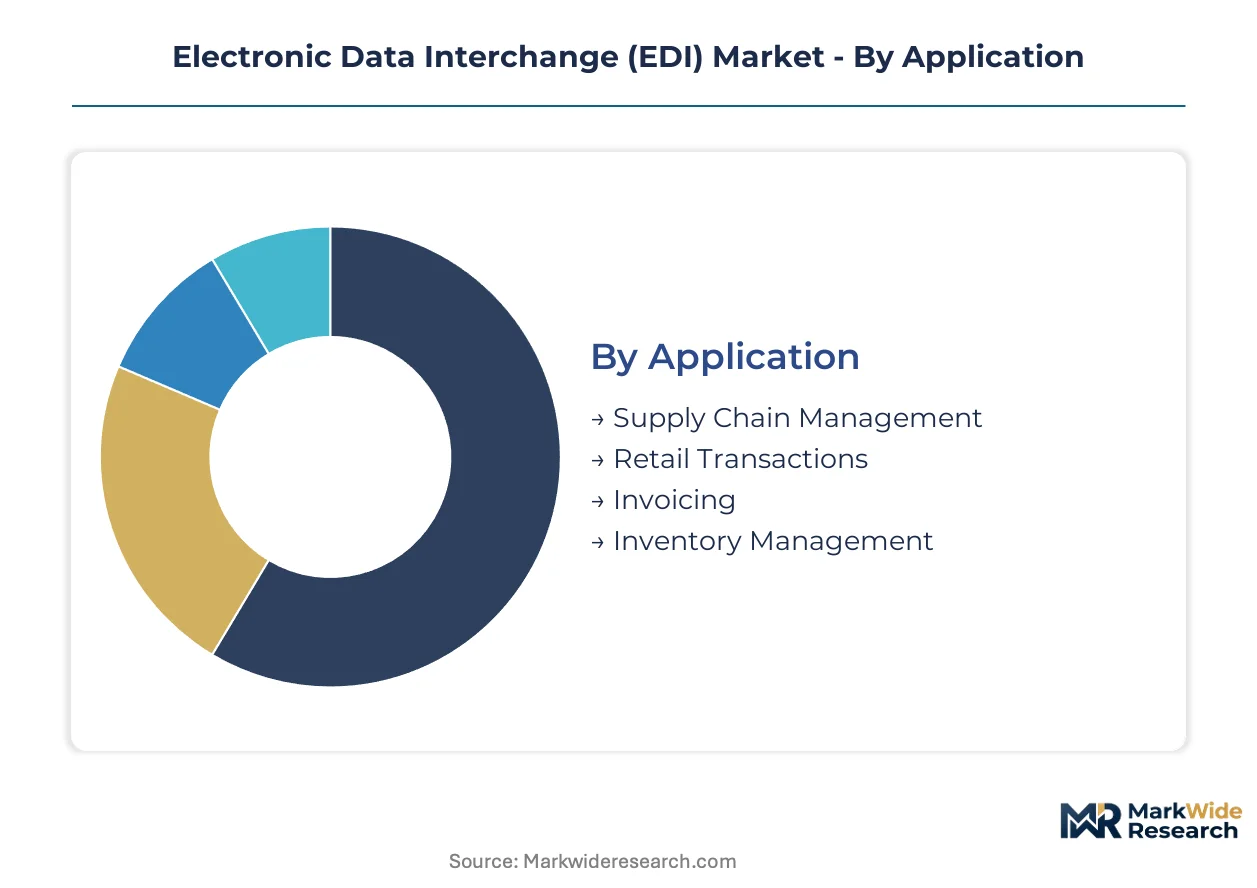
Segmentation in the EDI market reveals how procurement patterns diverge across technical architectures and compliance requirements. Each dimension carries distinct margin profiles and renewal dynamics that reshape vendor positioning.
Application:
After-sales service intensity varies sharply across application types, with supply chain deployments demanding continuous mapping support while invoicing solutions require less ongoing intervention.
- Supply Chain Management:Multi-enterprise visibility platforms coordinate purchase orders, shipping notices, and customs documentation across tiered supplier networks. Automotive manufacturers in Germany and aerospace contractors in France drive concentrated demand for real-time track-and-trace capabilities integrated with ERP systems.
- Retail Transactions:Omnichannel order orchestration synchronizes inventory positions across physical stores, warehouses, and marketplace endpoints. US and UK retailers are displacing batch-file protocols with synchronous API exchange to support same-day fulfillment commitments.
- Invoicing:Accounts payable automation reduces manual data entry errors through standardized remittance formats.
- Inventory Management:Stock-level synchronization prevents oversell scenarios across distributed fulfillment nodes.
By volume, Supply Chain Management leads. By growth pace, Retail Transactions is ahead.
Deployment:
Cost tier stratification separates enterprise buyers willing to absorb capital expenditure from mid-market adopters seeking operational expenditure alignment.
- Cloud-Based:Fully managed infrastructure eliminates server maintenance burdens while scaling compute resources elastically with transaction volumes. Mid-market enterprises in Brazil and Japan are abandoning on-premises installations fastest as CFO scrutiny intensifies on technology spend.
- SaaS:Subscription licensing bundles software, hosting, and basic support into per-user or per-transaction fees. Third-party logistics providers prefer this model for its alignment with variable shipping volumes.
- On-Premises:Licensed software running on customer-controlled hardware persists in defense and classified government workflows.
- Hybrid:Blended architectures connect legacy on-premises translation engines with cloud-native API gateways.
Cloud-Based deployments capture the deepest revenue pools. SaaS models are climbing the fastest as procurement patterns rotate toward consumption-based pricing.
Industry Vertical:
Margin concentration tracks regulatory complexity, with HIPAA-mandated healthcare workflows commanding premium pricing against standardized retail implementations.
- Healthcare:HIPAA transaction standards enforce ANSI X12-compliant electronic formats for claims processing and eligibility verification. US hospitals and insurers face baseline infrastructure requirements that create defensive revenue streams for certified platform vendors.
- Manufacturing:Industrial automation integrates EDI with MES and SCADA systems for supplier dock scheduling. German automotive suppliers are restructuring validation documentation to meet EU AI Act risk classification requirements.
- Retail:High-volume, low-margin transaction processing prioritizes cost efficiency over customization depth.
- Transportation:Freight visibility and customs brokerage documentation require specialized maritime and air cargo message formats.
Healthcare generates the highest per-transaction margins. Manufacturing is expanding most quickly as supplier network digitization accelerates.
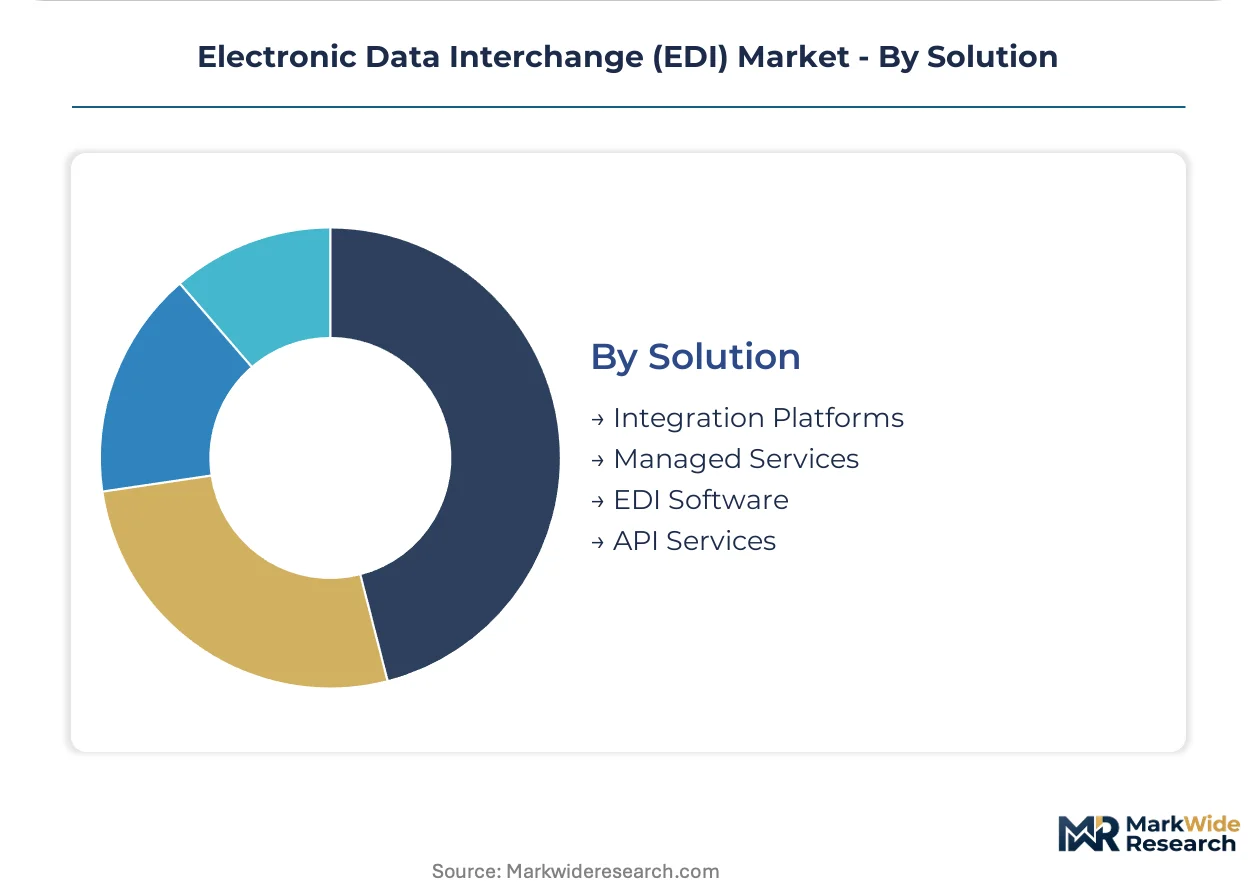
Solution:
Customer type segmentation separates enterprises seeking full outsourcing from those retaining internal integration competency.
- Managed Services:Outsourced partner onboarding, mapping maintenance, and compliance monitoring embed expertise into recurring contracts. This category retains the deepest margin pools by reducing customer switching through operational dependency.
- API Services:Real-time connectivity infrastructure supports synchronous JSON and XML exchange beyond traditional batch EDI. Omnichannel retailers and marketplace operators are the primary demand source.
- Integration Platforms:Unified middleware connecting legacy EDI engines with modern cloud applications.
- EDI Software:Licensed translation and mapping tools for enterprises maintaining internal IT capabilities.
Managed Services dominates current revenue. API Services holds the steepest expansion trajectory as real-time requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare providers in the United States process claims through HIPAA-mandated ANSI X12 formats, while German automotive suppliers synchronize multi-tier supplier networks through EDIFACT protocols. Brazilian mid-market enterprises and Japanese manufacturers are migrating fastest to cloud-based deployment models.
United States
HIPAA transaction standards compel hospitals and insurers to maintain certified EDI infrastructure for claims processing and eligibility verification. The FDA enforces 21 CFR Part 11 validation protocols for pharmaceutical supply chain documentation. Healthcare clusters in Boston and the Research Triangle Park are restructuring supplier onboarding around API-first architectures.
Germany
Automotive OEMs and tiered supplier networks drive concentrated demand for real-time track-and-trace capabilities integrated with ERP systems. The EU AI Act's risk classification framework requires documented algorithmic transparency for automated supply chain decision-making. Industrial manufacturers in Stuttgart and Wolfsburg are adopting hybrid architectures connecting legacy translation engines with cloud-native gateways.
Japan
Mid-market enterprises are abandoning on-premises installations for fully managed cloud EDI services as CFO scrutiny intensifies on technology spend. METI standards influence B2B document exchange protocols across manufacturing supply chains. Electronics manufacturers in Osaka and automotive suppliers in Nagoya are leading API services adoption for synchronous inventory synchronization.
Brazil
Third-party logistics providers prefer SaaS subscription models that align costs with variable shipping volumes. ANVISA requirements shape pharmaceutical distribution documentation standards. Retail and logistics clusters in São Paulo are displacing batch-file protocols with consumption-based pricing structures for EDI services.
United Kingdom
Omnichannel retailers are driving displacement of traditional batch EDI with synchronous API exchange to support same-day fulfillment commitments. GDPR frameworks influence how platforms handle cross-border data flows and automated decision-making. London-based financial services firms and Manchester-area distributors are restructuring procurement patterns toward per-transaction fee models.
Electronic Data Interchange (EDI) Market Competitive Landscape
Capability concentration sits with specialized managed service providers; scale advantage sits with network-centric platform operators. The vendor landscape organizes around three strategic archetypes: cloud-native SaaS providers, legacy integration platform vendors with hybrid offerings, and managed service specialists embedding compliance expertise into recurring contracts. Dominant competitive moves include portfolio diversification into API connectivity infrastructure and strategic partnerships to accelerate healthcare interoperability expansion.
Within the network-centric tier, E2open, LLC and SPS Commerce, Inc. exemplify platform operators leveraging multi-enterprise architectures. OpenText Corporation occupies a position bridging legacy on-premises systems and modern cloud endpoints. These three entities represent contrasting approaches to unifying disparate protocol stacks under single management layers while navigating divergent regulatory requirements across HIPAA-mandated healthcare and FDA-regulated pharmaceutical workflows.
| Leading Market Players |
|---|
| E2open, LLC |
| Cleo Communications LLC |
| OpenText Corporation |
| DiCentral, LLC |
| Axway Software SA |
| International Business Machines Corporation |
| TrueCommerce Holdings, LLC |
| DataTrans Solutions Inc. |
| SPS Commerce, Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud-native EDI infrastructure across US and German data centers is compressing margins for platform operators while simultaneously accelerating buyer migration from on-premises installations. This utilization imbalance rewards vendors with diversified managed service portfolios and pressures pure-play software providers into subscription model reinvention.
Pricing Analysis
Contract structures in the EDI market center on recurring subscription frameworks with consumption-based overlays rather than perpetual licensing or spot-market arrangements. Three-tier pricing separates HIPAA-certified healthcare deployments from standard retail integrations and economy-tier logistics connectivity, with certification grade and transaction volume scale as the primary differentiation levers. Pricing pressure stems from mid-market CFO scrutiny intensifying across Brazil and Japan, where enterprises demand per-document fee alignment with actual trading volumes. Third-party logistics providers exhibit the highest price sensitivity due to thin shipping margins, while pharmaceutical distributors under FDA 21 CFR Part 11 mandates accept premium pricing for validated compliance documentation.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Germany and retail consolidators in the United States are reshaping supplier financing dynamics for EDI platform vendors, forcing working capital reallocation toward cloud infrastructure provisioning. Component concentration rests on semiconductor supply from Taiwan and South Korea for translation engine hardware, software development labor pools in India and Poland, and data center capacity in the United States, Germany, and Japan. Single-source vulnerability in specialized X12 and EDIFACT standards expertise creates implementation bottlenecks as aging practitioner cohorts constrain capacity. Distribution runs through direct enterprise sales for large healthcare and manufacturing accounts, with channel partners and self-service portals penetrating mid-market retail and logistics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EDI market is approaching a platform-economics inflection where network effects from multi-enterprise connectivity are consolidating competitive advantage around API-first architectures and healthcare interoperability ecosystems.
For Market Incumbents: Build switching-cost moats through embedded compliance expertise and ongoing mapping maintenance that operationalizes customer dependency. Deepen API connectivity infrastructure investments to capture omnichannel retail demand displacing batch-file protocols. Defend against cloud-native entrants by accelerating hybrid architecture deployment for German automotive and US pharmaceutical accounts with legacy system entrenchment. For New Entrants and Emerging Players: Establish a beachhead in AI-assisted mapping automation for mid-market enterprises in Brazil and Japan where self-service onboarding gaps persist. Target underpenetrated SME segments with pre-configured industry templates for inventory management and invoicing workflows currently served by manual processes. Pursue strategic partnerships with ERP vendors and marketplace operators to bypass direct sales cost barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service specialists embedding HIPAA and FDA validation expertise into long-term contracts with healthcare and pharmaceutical accounts. Acquisition candidates with demonstrated API services growth and healthcare interoperability certifications offer the strongest five-to-ten year viability against protocol standardization and real-time connectivity trends. Monitor FDA guidance evolution on 21 CFR Part 11 digital validation and EU AI Act enforcement patterns as inflection signals for compliance-driven pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Synchronous inventory synchronization captures omnichannel retail demand from US and UK markets. |
| Healthcare Interoperability Partnership | HIPAA-certified onboarding opens defensive revenue streams across hospital and insurer networks. |
| AI-Assisted Mapping Development | Machine learning automation reduces professional services dependency for mid-market customer acquisition. |
| Hybrid Architecture Deployment | Legacy-to-cloud connectivity addresses German automotive and aerospace manufacturer modernization cycles. |
| Consumption-Based Pricing Launch | Per-transaction fee structures align with Brazilian logistics provider and Japanese manufacturer CFO priorities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EDI platform product managers, healthcare IT procurement directors, retail supply chain executives, logistics technology leads, and managed services operations heads. Secondary validation drew from SEC filings of publicly traded integration vendors, HIPAA enforcement action databases, FDA 21 CFR Part 11 guidance documents, and EU AI Act regulatory texts. Bottom-up transaction volume modeling and top-down market sizing triangulation were cross-referenced against cloud infrastructure capex disclosures and channel partner survey data.
Calibration against historical adoption curves and regulatory compliance deadline effects shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, industry vertical, and enterprise size tier alongside geographic regulatory cluster differentiation. CAGRs were derived from fitted growth curves adjusted for cloud migration velocity and API services expansion rates. Industry-specific inputs encompassed trading partner onboarding timelines, mapping complexity indices, and compliance certification renewal patterns.
Stress conditions across cloud infrastructure cost inflation, regulatory enforcement intensity, and legacy system replacement cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding HIPAA mandate continuity, EU AI Act implementation sequencing, and mid-market SaaS adoption thresholds. Macroeconomic contraction, regulatory fragmentation acceleration, or breakthrough protocol standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IT Operations Management Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Master Data Management Market
Digital Solutions
Container Orchestration Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Drone Mapping Software for Agriculture Market