
 Renewable Energy Certificate Market | 2026-2036
Renewable Energy Certificate Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Certificate Market Analysis
The EU Green Deal is repositioning certificate demand across European energy markets. NextEra Energy leverages its vertically integrated renewable fleet to supply bundled certificates directly to corporate offtakers. Invenergy anchors its competitive stance through direct origination relationships with Fortune 500 buyers seeking hourly matched clean energy claims. Brookfield Renewable Partners differentiates by controlling hydroelectric assets that deliver baseload-matched certificates to industrial consumers with 24/7 carbon-free requirements.
A renewable energy certificate represents one megawatt-hour of electricity generated from qualifying renewable sources, tracked through electronic registries that verify generation attributes and prevent double-counting across overlapping regulatory jurisdictions. Solar certificates command structural premiums in markets with high daytime peak demand and distributed generation mandates, while wind certificates dominate volume flows in regions with established production tax credit frameworks. Traders occupy critical intermediary roles in fragmented state-level markets where regulatory heterogeneity creates arbitrage opportunities across certificate vintages and eligibility standards.
EPA's Green Power Partnership and state-level renewable portfolio standards administered by public utility commissions shape compliance demand trajectories across US territories. EMA's evolving sustainability disclosure requirements under CSRD are extending certificate tracking obligations to European corporate supply chains. Stakeholders must monitor whether emerging hourly matching standards displace annual certificate aggregation as the dominant procurement paradigm.
Market Dynamics
Hourly matching standards are compressing annual certificate aggregation windows, forcing registry operators to rebuild tracking infrastructure around timestamped generation data rather than vintage-year bulk accounting.
Growth Catalysts
- Science Based Targets initiative:Corporate procurement teams at technology firms face binding emissions reduction timelines. Unbundled certificate purchases satisfy Scope 2 accounting requirements under GHG Protocol guidance.
- EU Green Deal renewable targets:Member states must accelerate clean electricity shares under tightening compliance schedules. Certificate demand concentrates in industrial sectors facing carbon border adjustment exposure.
- Distributed generation mandates:State-level solar carve-outs in US territories create structural premiums for geographically tagged certificates. Registries track locational attributes to prevent double-counting across overlapping jurisdictions.
Market Restraints
- Silicon supply concentration:Solar certificate issuance depends on polysilicon feedstock dominated by Chinese smelters. Trade restrictions disrupt project commissioning timelines in Western markets.
- Interconnection queue congestion:Grid operators in ERCOT and CAISO territories delay renewable project energization. Certificate supply lags behind offtake commitments by 18-36 months.
- Regulatory heterogeneity:State renewable portfolio standards impose incompatible eligibility rules. Traders face compliance risk arbitraging certificates across fragmented territorial boundaries.
Strategic Opportunities
- CSRD supply chain disclosure:European corporates must document electricity sourcing across tier-one suppliers. Certificate tracking obligations extend to mid-market manufacturers lacking established procurement functions.
- Green hydrogen offtake:Electrolyzer operators require 24/7 matched clean power claims. Baseload-matched hydroelectric certificates command structural premiums in industrial hydrogen hubs.
- Blockchain registry integration:Distributed ledger technology is expanding into certificate issuance and retirement tracking. Smart contracts automate settlement between generators and corporate buyers.
Industry Challenges
- Timestamp verification infrastructure:Registries lack standardized meter data integration for sub-hourly generation claims. IT system upgrades strain operator budgets and delay platform rollouts.
- Attribute tracking complexity:Multiple environmental claims attach to single megawatt-hours. Software developers must prevent double-counting across renewable energy certificates, carbon offsets, and green tariffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Certificate Market |
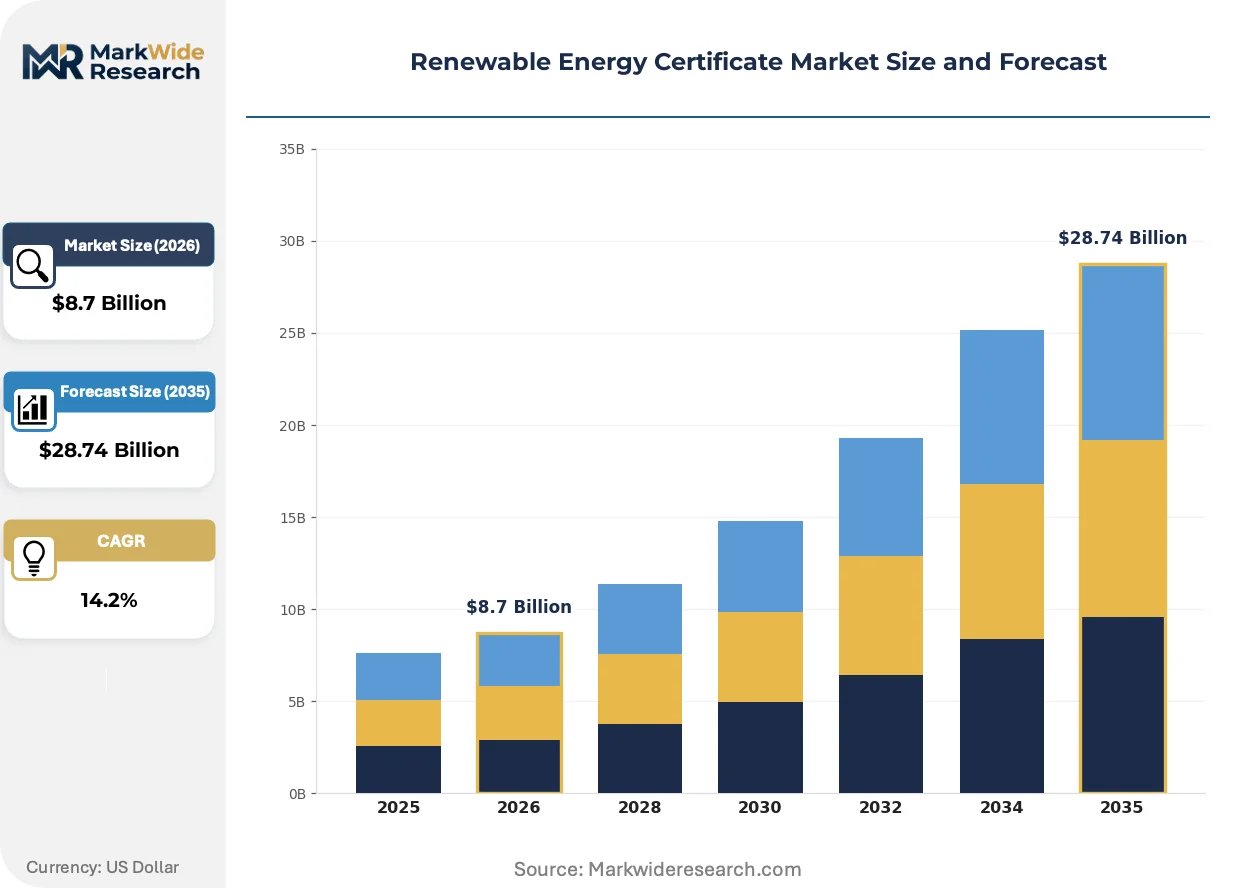
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Certification Type: Solar, Wind, Hydro, Biomass Utility Type: Investor-Owned, Municipal, Cooperative, Independent Market Participant: Developers, Aggregators, Corporations, Traders Transaction Model: Spot Market, Forward Market, Long-Term Contracts, Auctions |
| Companies Covered | Clearway Energy Group, Invenergy, NextEra Energy, Recurrent Energy, Apex Clean Energy, Brookfield Renewable Partners, Canadian Solar, LS Power, First Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Certificate Market Emerging Trajectories
Granular tracking technologies are fragmenting certificate products into time-differentiated instruments. Market participants must rebuild pricing frameworks around temporal value rather than annual vintage aggregation.
Automated meter infrastructure is expanding into sub-15-minute generation data collection. Grid operators in Germany and California deploy advanced metering to verify timestamped renewable output. Corporate buyers with 24/7 clean energy targets now procure certificates matched to specific consumption intervals rather than annual averages.
EMA's CSRD extends sustainability disclosure obligations to European corporate supply chains. Certificate tracking requirements now cover tier-one manufacturing partners previously exempt from Scope 2 reporting. Mid-market suppliers in Poland and Romania face immediate compliance deadlines without established procurement infrastructure.
Corporate buyers now specify delivery terms through direct origination contracts rather than secondary market purchases. Technology firms with Science Based Targets negotiate bundled power purchase agreements with hourly matching riders. This channel compression bypasses traditional trader intermediaries in fragmented state-level markets.
Renewable Energy Certificate Market Segmentation
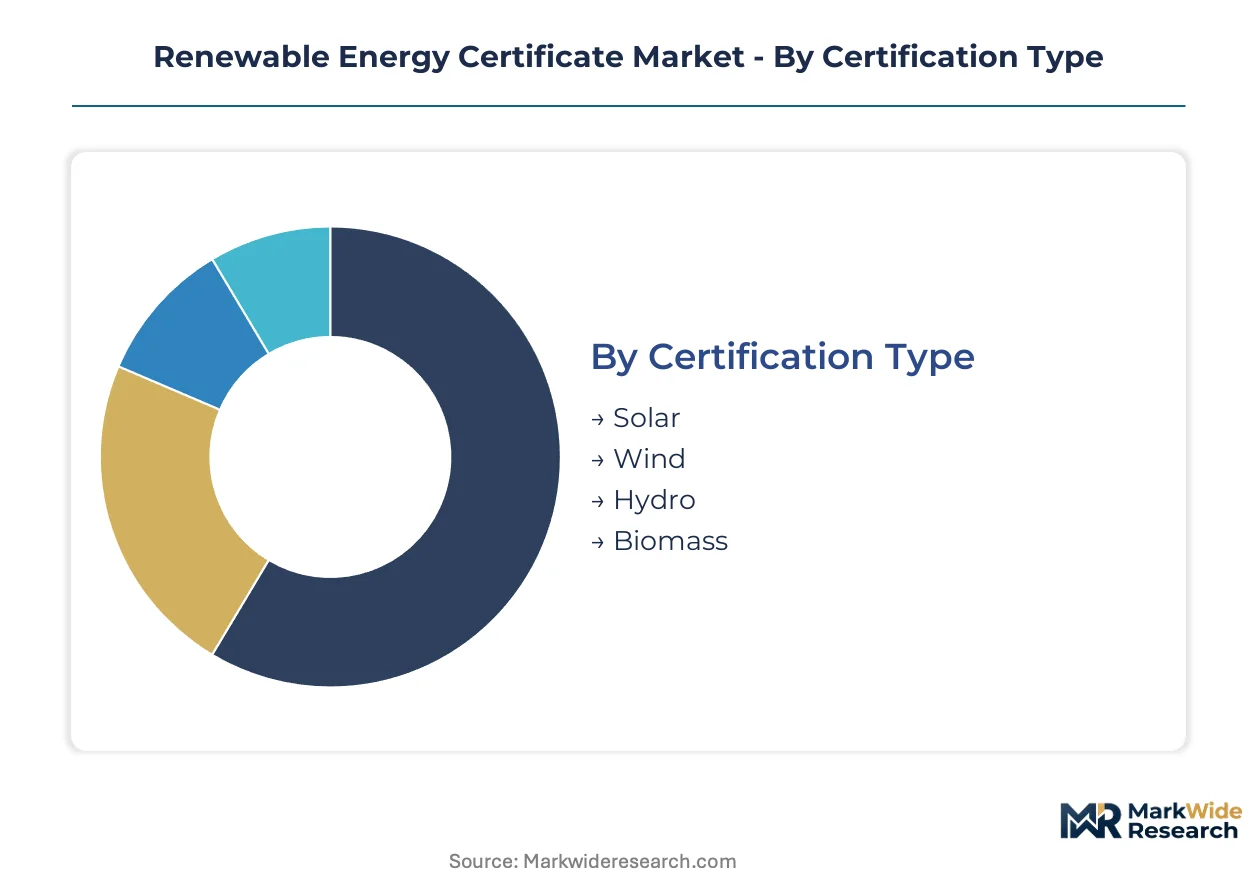
Certificate markets fragment across generation technologies, utility ownership structures, and transaction mechanisms. Each segmentation axis shapes liquidity conditions, pricing transparency, and counterparty risk profiles for corporate buyers.
Certification Type:
Solar, wind, hydro, and biomass certificates differ in temporal generation profiles and locational premiums.
- Solar:Photovoltaic generation produces certificates concentrated in daytime hours. Technology firms in California and Texas pay structural premiums for these instruments to match peak consumption periods.
- Wind:Variable output from onshore and offshore installations dominates certificate issuance volumes. ERCOT and CAISO territories see the heaviest concentration of wind-backed procurement.
- Hydro:Run-of-river and reservoir facilities deliver baseload-matched certificates. Industrial hydrogen producers in Germany seek these instruments for 24/7 clean power claims.
- Biomass:Organic waste-to-energy plants generate certificates with distinct sustainability attributes. Forestry sector integration in Nordic markets supports localized procurement.
Wind leads on scale; solar leads on momentum.
Utility Type:
Ownership structure determines regulatory obligations and certificate sourcing strategies.
- Investor-Owned:Shareholder-owned utilities operate under state renewable portfolio mandates. Public utility commissions in California and New York enforce compliance timelines that drive certificate demand.
- Municipal:City-owned utilities serve discrete service territories with localized clean energy targets. Community choice aggregations in Illinois and Ohio expand voluntary procurement programs.
- Cooperative:Member-owned rural electric cooperatives pool demand across agricultural load centers. NRECA affiliates in the Great Plains negotiate collective certificate purchases.
- Independent:Non-utility generators and retail suppliers operate outside traditional franchise territories. Texas retail electric providers bundle certificates with competitive supply offers.
Investor-owned utilities anchor compliance volume; municipal utilities are gaining share fastest in voluntary markets.
Market Participant:
Participant category defines risk tolerance and holding period preferences.
- Developers:Project sponsors originate certificates through owned renewable assets. Long-term offtake contracts with corporate buyers de-risk financing structures.
- Aggregators:Intermediaries pool distributed generation output into tradable certificate blocks. Small-scale solar installers in Florida and Arizona rely on these channels for monetization.
- Corporations:End-users procure certificates to satisfy Scope 2 emissions accounting under GHG Protocol guidance. Science Based Targets initiative commitments bind technology sector buyers to specific vintage requirements.
- Traders:Financial intermediaries arbitrage price differentials across state regulatory boundaries. Registry heterogeneity creates margin opportunities in fragmented territorial markets.
Corporations drive demand expansion; traders provide essential liquidity.
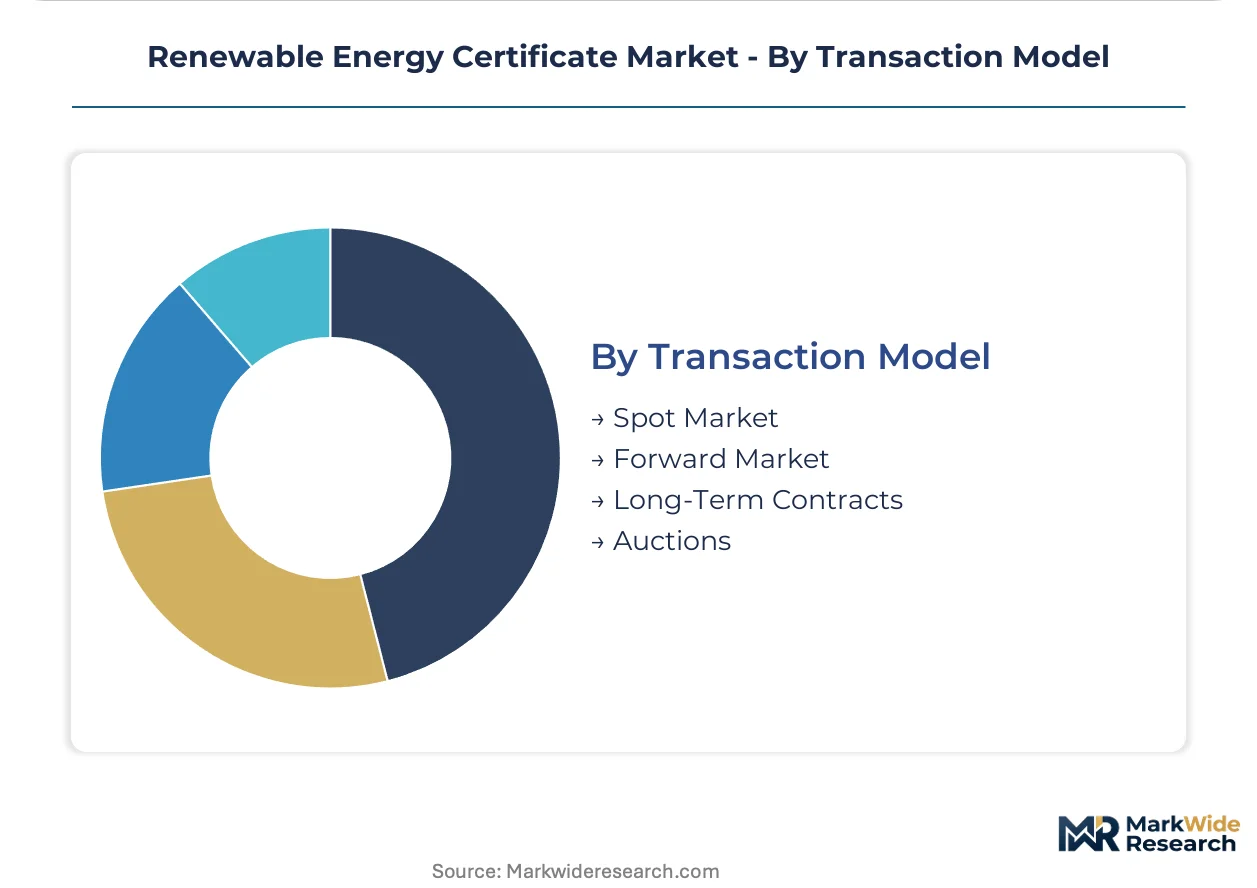
Transaction Model:
Contract structure shapes price discovery and delivery certainty.
- Spot Market:Immediate-delivery transactions clear through bilateral negotiations or electronic platforms. Price volatility in ERCOT territory reflects renewable generation intermittency.
- Forward Market:Future-delivery contracts lock in certificate availability for compliance deadlines. Municipal utilities in the Northeast hedge RPS obligations through seasonal forward positions.
- Long-Term Contracts:Multi-year bundled agreements pair certificates with physical power delivery. Corporate offtakers with 24/7 clean energy targets negotiate hourly matching riders.
- Auctions:Centralized procurement mechanisms administered by state regulators or utilities. New York NYSERDA and Massachusetts DOER conduct competitive solicitations for compliance-grade certificates.
Long-term contracts dominate corporate procurement; auctions set benchmark pricing for regulated utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certificate procurement specialists cluster in jurisdictions with binding clean electricity mandates and active corporate sustainability programs. Regulatory heterogeneity across territories shapes where traders, developers, and industrial buyers concentrate their operations.
United States
Technology firms in California and Texas drive voluntary certificate procurement under Science Based Targets initiative commitments. EPA's Green Power Partnership and state renewable portfolio standards administered by public utility commissions shape compliance trajectories. ERCOT and CAISO territories see concentrated wind certificate issuance, though interconnection queue congestion delays project energization by 18-36 months.
Germany
Industrial buyers face escalating carbon border adjustment pressures that concentrate certificate demand in manufacturing-heavy Länder. EU Green Deal renewable targets tighten compliance obligations through national implementation of RED III directives. The Ruhr industrial corridor and Bavarian manufacturing hubs anchor procurement of baseload-matched hydroelectric certificates for 24/7 clean power claims.
United Kingdom
Corporate offtakers leverage the Renewables Obligation and Contract for Difference frameworks to secure bundled certificate arrangements. Ofgem administers the Renewable Energy Guarantees of Origin registry that tracks generation attributes. London-based financial intermediaries arbitrage price differentials across continental European registries with incompatible eligibility standards.
India
State-level renewable purchase obligations administered by CEA drive compliance demand from discoms and captive consumers. PLI scheme incentives accelerate solar project commissioning in Gujarat and Rajasthan. Certificate issuance concentrates in Tamil Nadu and Karnataka where wind and solar installations serve industrial clusters in Bangalore and Chennai.
Australia
The Large-scale Generation Target and state-based schemes in Victoria and Queensland fragment certificate markets across territorial boundaries. AEMO tracks generation attributes through the REC Registry that prevents double-counting. Corporate buyers in Sydney and Melbourne procure unbundled certificates to satisfy voluntary sustainability commitments under Climate Active certification.
Renewable Energy Certificate Market Vendor Landscape
Capital-heavy producers compete with asset-light designers for corporate offtake relationships in certificate markets. The vendor base spans vertically integrated renewable developers, independent power producers, and financial intermediaries with registry access. Three archetypes dominate: fleet operators with captive generation assets, aggregators pooling distributed output, and trader-intermediaries arbitraging regulatory fragmentation. Competitive moves center on long-term origination contracts with hourly matching riders and strategic partnerships with electrolyzer operators in hydrogen hubs.
Within the integrated developer tier, NextEra Energy and Invenergy exemplify archetypes of scale-driven fleet operators. Brookfield Renewable Partners occupies a position among baseload specialists controlling hydroelectric assets. Clearway Energy Group sits within the independent power producer segment with diversified renewable portfolios. These entities represent competitive positioning around generation technology specialization, geographic footprint, and corporate offtake relationship depth rather than commodity trading capabilities.
| Leading Market Players |
|---|
| Clearway Energy Group |
| Invenergy |
| NextEra Energy |
| Recurrent Energy |
| Apex Clean Energy |
| Brookfield Renewable Partners |
| Canadian Solar |
| LS Power |
| First Solar |
| Others |
Supply Flow & Price Mechanics
Science Based Targets initiative commitments from technology sector procurement teams are forcing certificate suppliers toward hourly-matched products with granular timestamp verification, compressing margins on legacy annual vintage instruments and redirecting capital toward registry IT infrastructure upgrades.
Pricing Analysis
Bundled power purchase agreements with physical energy delivery command structural premiums over unbundled certificate-only transactions. Price differentiation stems from certification vintage specificity and geographic locational value tied to state renewable portfolio mandates. Cost compression in unbundled spot markets is intensifying because corporate buyers with 24/7 clean energy targets are bypassing secondary trader channels. Municipal utilities exhibit highest price sensitivity due to ratepayer-funded compliance obligations, while technology firms with binding emissions timelines show lowest sensitivity to hourly-matched premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon smelters that feed solar module manufacturing for certificate-eligible projects. Geographic supply concentration centers on China for photovoltaic components, Germany for wind turbine nacelles, and Norway for run-of-river hydroelectric equipment. Raw material dependencies draw from high-purity silicon metal, rare earth magnets for generators, and aluminum for tower structures. Supply chain risk hinges on tariff exposure from trade restrictions targeting Chinese solar inputs. Distribution runs through vertically integrated renewable developers with direct origination relationships to corporate offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hourly matching specifications are displacing annual aggregation as the dominant procurement paradigm, rewarding suppliers with timestamp-verification infrastructure.
For Market Incumbents: To counter channel compression from direct origination contracts, deepen captive generation fleets through hydroelectric asset acquisitions that deliver baseload-matched certificates. Prioritize backward integration into electrolyzer partnerships at industrial hydrogen hubs to lock in 24/7 clean power offtake. For New Entrants and Emerging Players: Blockchain-enabled registry platforms offer the most penetrable white-space for automated settlement between distributed generators and corporate buyers. Target mid-market European manufacturers facing CSRD supply chain disclosure deadlines without established procurement functions. Deploy smart contract architecture as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with baseload specialists controlling reservoir hydroelectric assets that command structural premiums in hourly-matched markets. Long-term viability favors developers with contracted offtake pipelines under Science Based Targets initiative timelines rather than merchant exposure. The inflection indicator to monitor is adoption velocity of sub-15-minute meter data standards across European registries.| Strategic Initiative | Industry Significance |
|---|---|
| Hourly Matching Infrastructure Buildout | Registry operators in Germany and California deploy timestamped generation tracking to verify 24/7 clean power claims. |
| Power Purchase Agreement with Bundled Certificates | Corporate offtakers negotiate direct origination contracts that bypass traditional trader intermediaries in fragmented markets. |
| Blockchain Registry Integration | Distributed ledger technology automates settlement between generators and buyers through smart contract architecture. |
| Backward Integration into Electrolyzer Partnerships | Renewable developers secure baseload-matched offtake from hydrogen hub operators requiring continuous clean power. |
| CSRD Compliance Service Expansion | Certificate tracking obligations extend to tier-one suppliers in Poland and Romania lacking procurement infrastructure. |
Methodological Framework
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and corporate sustainability directors grounded qualitative findings in operational realities across certificate issuance and retirement workflows. Secondary validation drew from EIA generation data, IEA renewable market reports, FERC interconnection queue filings, and project development databases tracking energization timelines. Bottom-up capacity buildout estimates triangulated against top-down regulatory mandate trajectories.
Bottom-up modeling aggregated project-level certificate issuance potential across fuel source, generation capacity tier, and regional grid type, while top-down analysis calibrated against national renewable portfolio standard obligations. CAGRs were derived from regression analysis of historical vintage pricing and forward contract curves. Key forecast inputs included interconnection queue clearance rates and corporate procurement commitment timelines under Science Based Targets initiative guidance.
The model assumes a particular technology adoption path; alternative pathways for distributed ledger registry systems would alter the outlook for intermediary disintermediation. Forecasts reflect assumptions around hourly matching standard adoption velocity and trade policy stability for solar supply chains. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
China Solar Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Solar Showers Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Green Power Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Canada Renewable Energy Market