
 IQF Fruits and Vegetables Market | 2026-2036
IQF Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
IQF Fruits and Vegetables Market Outlook
Single-serve pouch configurations are shifting buyer preference across retail and foodservice channels, replacing bulk formats in convenience-oriented segments. Uren Food Group leverages its European sourcing network to sustain year-round berry availability. Dole Food Co. anchors its IQF portfolio on tropical fruit specialization. Ardo NV competes through vegetable-centric capacity across Belgian and Polish processing plants.
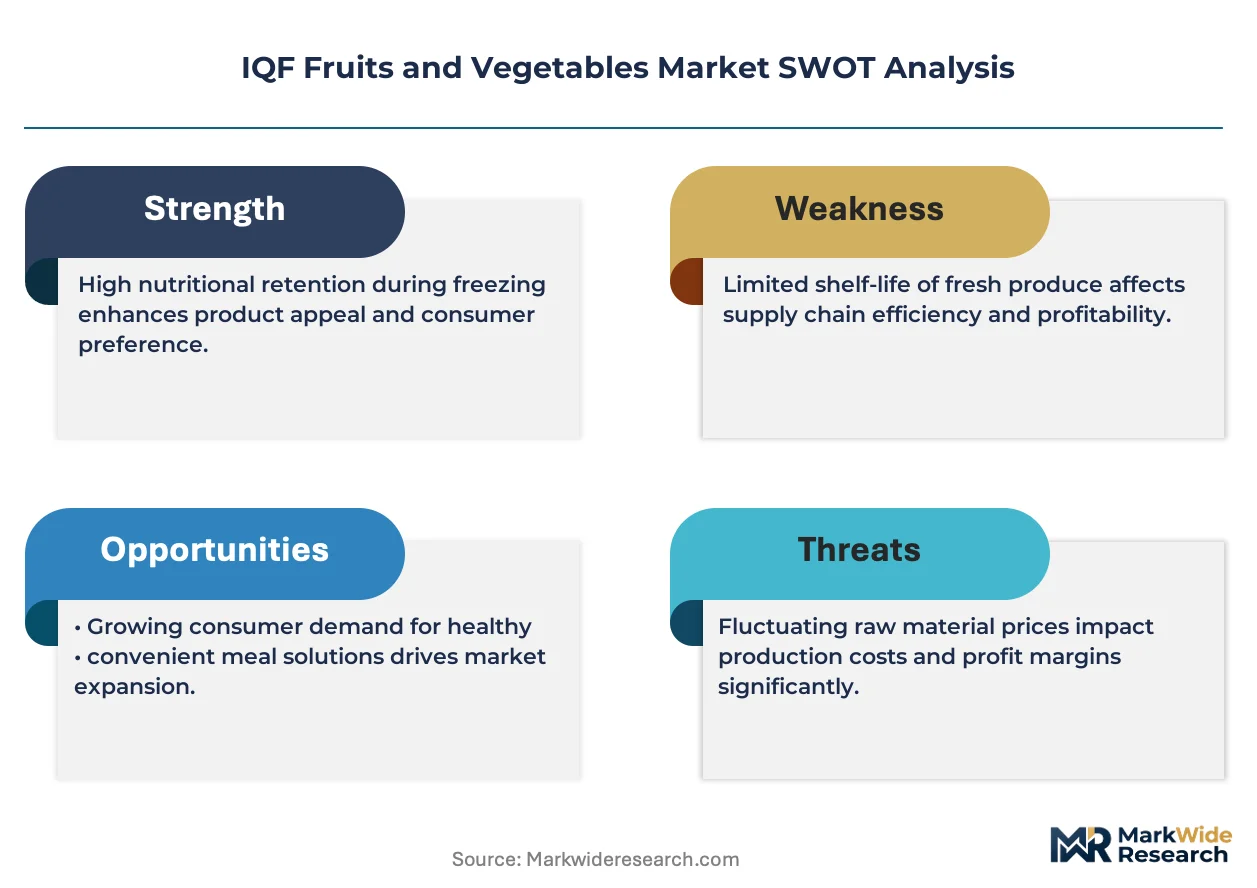
Individual Quick Freezing (IQF) denotes a blast-freezing process where each piece of fruit or vegetable is frozen separately at temperatures typically below minus 40 degrees Celsius, preserving cellular structure, color, and nutritional content for subsequent industrial or consumer use. The technique serves food manufacturers and foodservice operators requiring ingredient integrity without thawing degradation. IQF fruits command premium positioning in retail pouches, while mixed produce applications are accelerating fastest within contract catering channels. Food processing buyers absorb the largest volume flows, though margin pools concentrate in retail bag formats targeting household freezers.
FDA enforces Hazard Analysis Critical Control Point protocols across IQF processing facilities, while USDA grades frozen produce quality for institutional procurement eligibility. EFSA and national regulators within the EU apply Contaminants Regulation thresholds that shape import acceptance criteria for non-European suppliers. Stakeholders must monitor evolving cold-chain documentation requirements as traceability mandates tighten across multiple jurisdictions.
Market Dynamics
Quick-service restaurant chains are consolidating frozen produce procurement into fewer, larger contracts, squeezing mid-tier processors and forcing capacity consolidation across the IQF supply base.
Growth Catalysts
- FDA cold-chain traceability mandates:Tighter documentation requirements are accelerating processor investment in digital lot-tracking systems that command premium contract pricing from institutional buyers.
- Ready-meal manufacturing expansion:Food processing buyers are scaling IQF ingredient volumes to supply frozen entrée lines for North American and European retail channels.
- Blast-freezing technology diffusion:Cryogenic tunnel systems are penetrating mid-scale processing facilities, extending cellular-structure preservation capabilities previously limited to large-capacity plants.
Market Restraints
- Energy cost volatility:Cryogenic nitrogen and mechanical refrigeration inputs face pricing pressure from natural gas market fluctuations, compressing margins at continuous-run facilities.
- Seasonal supply concentration:Berry sourcing clusters in specific growing regions create harvest-window bottlenecks that constrain year-round volume guarantees.
- Fresh produce substitution:Controlled-atmosphere logistics improvements are extending raw vegetable shelf life, eroding IQF's cost advantage in certain foodservice applications.
Strategic Opportunities
- Contract catering channel expansion:Mixed vegetable and fruit blends are penetrating institutional meal programs in the United Kingdom and Germany, displacing canned alternatives.
- EU Green Deal agricultural incentives:Frozen produce qualifies for sustainability procurement credits in public-sector food contracts, creating preferential access for compliant processors.
- Single-serve pouch automation:Vertical form-fill-seal robotics are enabling retail-format flexibility at lower minimum order quantities, opening convenience-store distribution.
Industry Challenges
- Cryogenic equipment technician scarcity:Specialized maintenance skills for minus-40-degree systems command premium wages, constraining facility uptime at smaller processors.
- HACCP certification timelines:FDA facility approval processes for new freezing lines extend 12-18 months, delaying capacity expansion returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IQF Fruits and Vegetables Market |
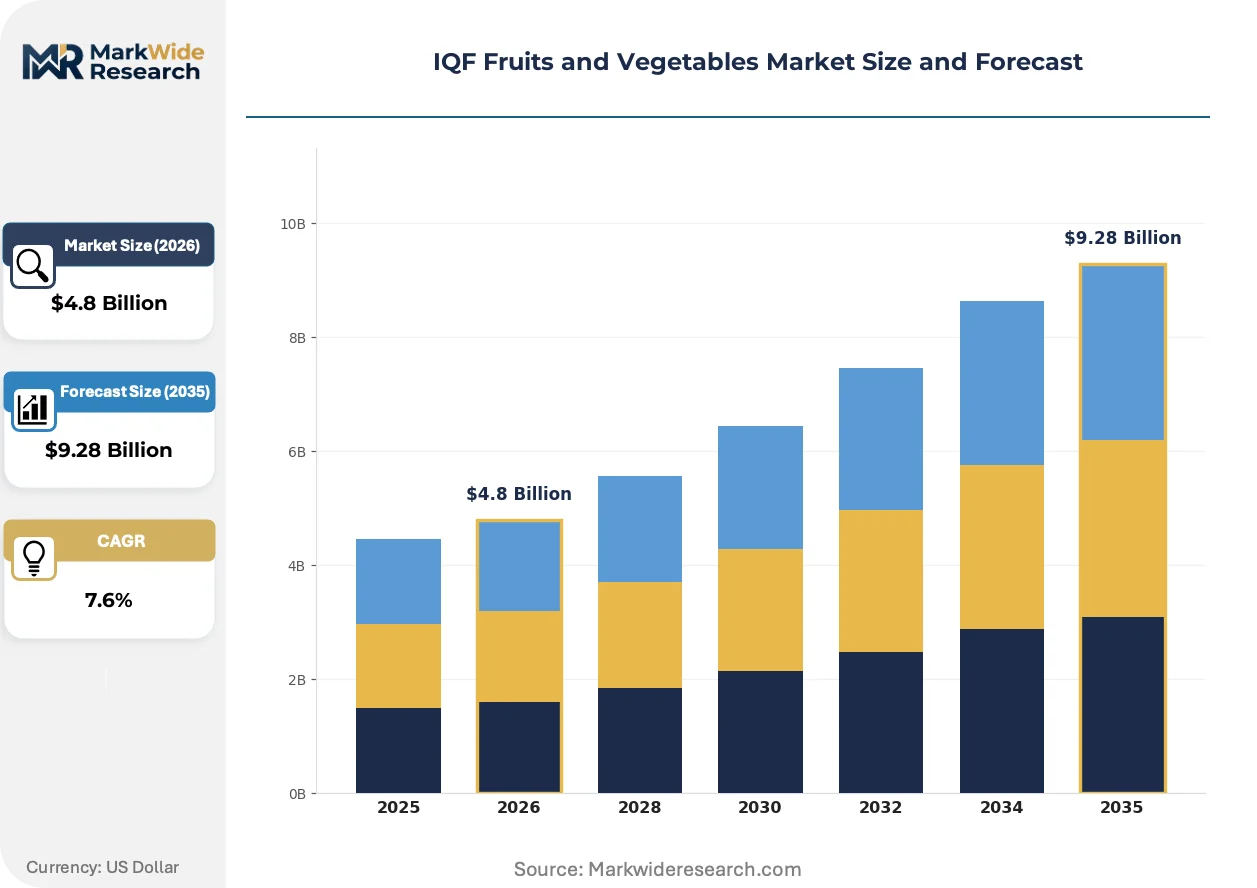
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
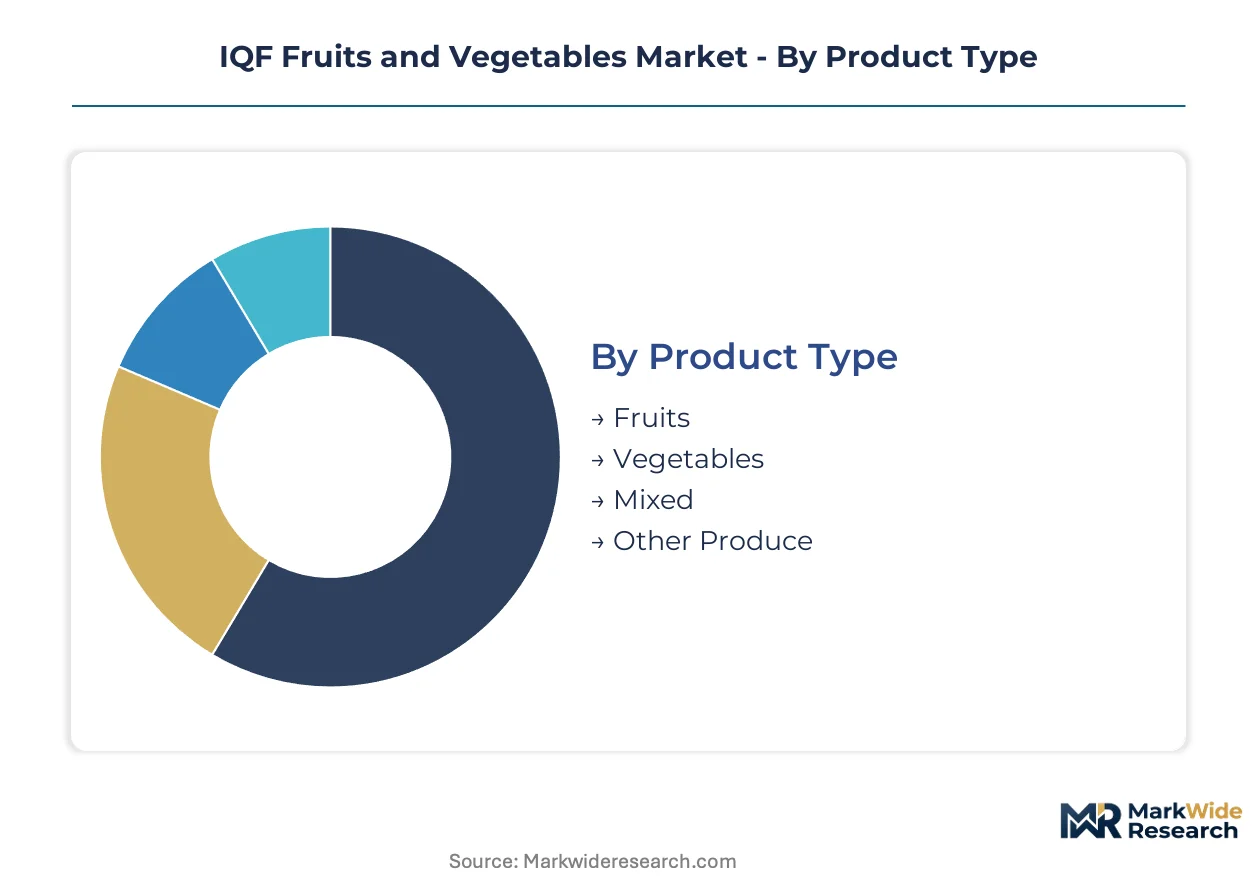
| Segmentation | Product Type: Fruits, Vegetables, Mixed, Other Produce Application: Food Service, Retail, Food Processing, Catering Packaging Type: Bags, Boxes, Bulk, Pouches End User: Households, Restaurants, Cafes, Institutional |
| Companies Covered | Uren Food Group, Dole Food Co. Inc., Ardo NV, Capricorn Food Products Ltd., J.R. Simplot Co., Greenyard NV, Bonduelle, B&G Foods, Conagra Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IQF Fruits and Vegetables Market Strategic Shifts
Automation and regulatory digitization are compressing batch sizes while expanding traceability depth, reshaping how processors compete on flexibility versus scale.
Individual Quick Freezing tunnel systems are modularizing across mid-capacity processing lines. Regional vegetable processors in Poland and Belgium are adopting containerized freezing units that scale output in 500-kilogram increments. This technology is modularizing capital deployment, allowing processors to match capacity to seasonal crop availability without committing to full-scale plant construction.
EFSA Contaminants Regulation thresholds are tightening maximum residue limits for imported frozen berries. Non-European suppliers face enhanced laboratory testing requirements at port of entry. Asian and South American exporters are responding by certifying integrated pest management protocols to maintain EU market access.
Foodservice distributors are consolidating frozen produce SKUs into vendor-managed inventory programs. Broadline operators are replacing spot purchasing with contracted volume commitments that transfer demand forecasting risk to processors. This pattern concentrates most visibly in United States institutional channels serving K-12 and healthcare segments.
IQF Fruits and Vegetables Market Segmentation
IQF procurement patterns diverge sharply between bulk industrial buyers seeking cost efficiency and retail channels demanding portion-controlled formats. Segmentation reveals how freezing technology, packaging automation, and regulatory compliance reshape competitive positioning across distinct customer workflows.
Product Type:
Fruits dominate premium pricing tiers while vegetables anchor volume procurement contracts across institutional channels.
- Fruits:Berries, tropical varieties, and stone fruits retain cellular integrity through cryogenic tunnel freezing, supporting clean-label positioning in retail pouches. United States quick-service restaurant chains drive bulk strawberry and blueberry procurement for smoothie and dessert applications, though FDA residue testing requirements constrain non-domestic sourcing windows.
- Vegetables:Broccoli florets, peas, and diced peppers serve ready-meal manufacturers requiring uniform cook times. Ardo NV's Belgian and Polish processing capacity supplies year-round broccoli and cauliflower to European contract catering channels, displacing canned alternatives in UK and German institutional meal programs.
- Mixed:Pre-combined stir-fry and soup blends reduce labor costs for foodservice operators.
- Other Produce:Herbs, garlic, and ginger segments serve ethnic cuisine manufacturers.
Mature deployment sits with Vegetables. Newer deployment is concentrated in Mixed blends.
Application:
Channel selection determines margin structure, with food processing buyers absorbing volume flows and retail commanding per-unit premiums.
- Food Processing:Ready-meal manufacturers integrate IQF ingredients into frozen entrée lines for North American and European retail distribution. Blast-freezing technology diffusion extends cellular-structure preservation to mid-scale facilities previously excluded from premium contract eligibility.
- Food Service:Quick-service restaurant chains consolidate procurement into fewer, larger contracts, squeezing mid-tier processors. Dole Food Co. anchors tropical fruit supply to this channel through specialized mango and pineapple IQF lines.
- Retail:Single-serve pouch configurations replace bulk formats in convenience-oriented segments.
- Catering:Institutional meal programs in UK and Germany adopt mixed produce blends.
Food Processing captures the steepest expansion trajectory as entrée manufacturing scales. Catering is gaining share fastest in sustainability-credit procurement.
Packaging Type:
Format selection reflects automation investment levels and minimum order quantity thresholds across customer tiers.
- Pouches:Vertical form-fill-seal robotics enable retail-format flexibility at reduced minimum order quantities, opening convenience-store distribution. Single-serve configurations shift buyer preference across retail and foodservice channels seeking portion control.
- Bulk:Food processing buyers absorb the largest volume flows through tote and drum configurations. Cryogenic nitrogen cost volatility compresses margins at continuous-run facilities serving this format.
- Bags:Household freezer formats concentrate margin pools in retail channels.
- Boxes:Institutional channels favor corrugated for palletized logistics efficiency.
Pouch automation investment clusters with mid-cap processors. Bulk format deployment dominates established freezing lines.
End User:
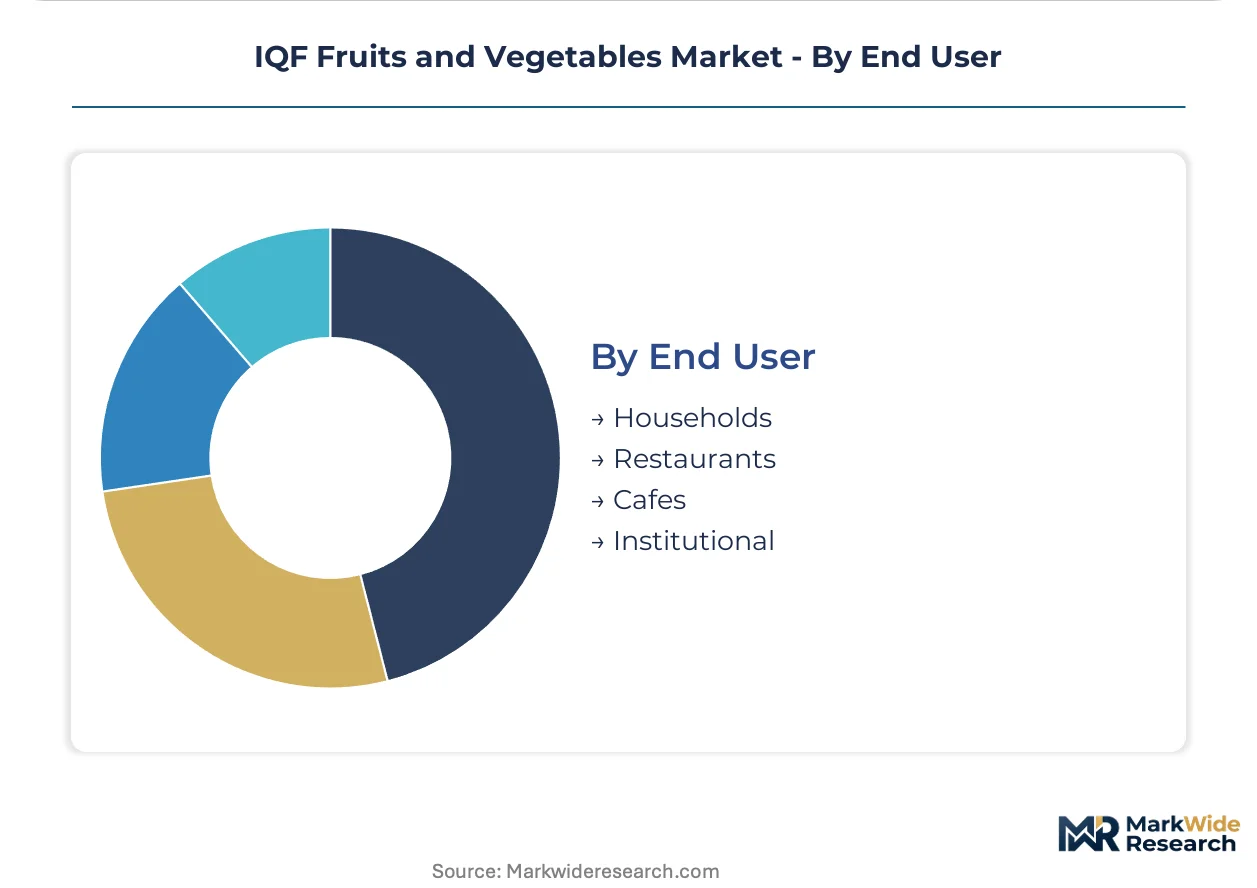
Customer type dictates specification stringency, from traceability documentation for institutional buyers to convenience prioritization for household segments.
- Restaurants:Quick-service chains drive bulk frozen produce purchasing with consolidated vendor-managed inventory programs. Broadline operators transfer demand forecasting risk to processors through contracted volume commitments.
- Institutional:K-12 and healthcare segments in the United States concentrate SKU consolidation under foodservice distributors. EU Green Deal agricultural incentives create preferential procurement access for sustainability-certified processors.
- Households:Retail bag formats target home freezer storage with premium positioning.
- Cafes:Smoothie and specialty beverage operators demand specific berry varieties.
Institutional procurement standardization sits with mature compliance frameworks. Restaurant chain consolidation represents the most dynamic contract restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Poland and Belgium supply frozen vegetables to European processors, while the United States absorbs the largest import volumes for quick-service restaurant chains. Consumption patterns diverge sharply between institutional bulk procurement in North America and retail pouch formats gaining traction across Western European households.
United States
Quick-service restaurant chains drive bulk frozen strawberry and blueberry procurement for smoothie applications. FDA enforces Hazard Analysis Critical Control Point protocols across processing facilities, extending facility approval timelines to 12-18 months for new freezing lines. Chicago and Minneapolis anchor foodservice distribution networks where broadline operators consolidate frozen produce SKUs into vendor-managed inventory programs.
Belgium
Ardo NV processes year-round broccoli and cauliflower for European contract catering channels. EFSA Contaminants Regulation thresholds tighten maximum residue limits for imported frozen berries, shaping import acceptance criteria. The Flanders region concentrates vegetable-centric freezing capacity that supplies UK and German institutional meal programs displacing canned alternatives.
Poland
Regional processors adopt containerized freezing units scaling output in 500-kilogram increments to match seasonal crop availability. National regulators apply EU Contaminants Regulation thresholds that non-European suppliers must meet for market access. Warsaw and Łódź processing clusters supply mixed vegetable blends penetrating contract catering channels across Central Europe.
Germany
Institutional meal programs in healthcare and K-12 segments adopt mixed produce blends under EU Green Deal agricultural incentives. Sustainability procurement credits in public-sector food contracts create preferential access for compliant processors. Bavaria and North Rhine-Westphalia concentrate demand from contract catering operators replacing canned vegetables with frozen alternatives.
United Kingdom
Contract catering channels absorb mixed vegetable and fruit blends for institutional meal programs. Uren Food Group leverages European sourcing networks to sustain year-round berry availability for British retail and foodservice buyers. London and the Southeast drive single-serve pouch preference shifts across convenience-oriented retail segments.
IQF Fruits and Vegetables Market Competitive Environment
The competitive structure tilts toward scale-driven processors with multi-plant networks and specialized regional players with crop-specific expertise. Large-capacity facilities command institutional contracts through volume guarantees, while mid-tier operators compete on flexibility and seasonal responsiveness. Three archetypes dominate: tropical fruit specialists, vegetable-centric processors with cross-border plant networks, and diversified food conglomerates with frozen produce divisions. Capacity consolidation and modular freezing technology adoption represent the primary competitive vectors reshaping processor positioning.
Within the vegetable-processing tier, Ardo NV exemplifies the multi-plant European operator archetype, while Dole Food Co. occupies a position as the tropical fruit specialist. Uren Food Group represents the sourcing-network-driven competitor leveraging continental European supply relationships. These three anchors illustrate how geographic specialization and crop focus differentiate competitive positioning across the IQF supply base.
| Leading Market Players |
|---|
| Uren Food Group |
| Dole Food Co. Inc. |
| Ardo NV |
| Capricorn Food Products Ltd. |
| J.R. Simplot Co. |
| Greenyard NV |
| Bonduelle |
| B&G Foods |
| Conagra Brands Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors across Poland and Belgium anchor supply discipline through harvest-window financing that locks in year-round volume guarantees against cryogenic nitrogen cost volatility. This ownership pattern concentrates pricing power with processors commanding backward integration into berry sourcing networks, while quick-service restaurant chains leverage consolidated procurement to compress contract margins.
Pricing Analysis
Cost-down pressure on bulk industrial formats accelerates because quick-service restaurant chains are consolidating frozen produce procurement into fewer, larger contracts. Pricing stratifies across retail pouch premiums, foodservice contract tiers, and bulk commodity baselines differentiated by FDA residue certification levels and volume scale. Institutional buyers exhibit highest price sensitivity due to EU Green Deal procurement credit requirements, while retail channels absorb premium positioning for single-serve convenience.
Supply Chain Analysis
Regional distribution centers in Chicago and Minneapolis anchor hub-and-spoke patterns serving United States quick-service restaurant chains. Supply concentrates in Poland, Belgium, and the United States, with raw material dependencies on seasonal berry harvests, cryogenic nitrogen, and corrugated packaging materials. Single-source vulnerability from concentrated berry growing regions creates harvest-window bottlenecks. Distribution runs through vendor-managed inventory programs transferring demand forecasting risk to processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic tunnel systems are displacing legacy mechanical freezing lines across mid-capacity processing facilities, compressing batch sizes while extending cellular-structure preservation capabilities previously limited to large plants.
For Market Incumbents: Extend modular freezing unit deployment across Polish and Belgian processing clusters to match seasonal crop availability without full-scale plant construction. Anchor defensive positioning through HACCP certification investment that accelerates FDA facility approval timelines. Consolidate capacity against mid-tier processor squeeze from quick-service restaurant chain contract consolidation. For New Entrants and Emerging Players: Launch via single-serve pouch automation targeting convenience-store distribution channels with reduced minimum order quantities. Penetrate contract catering channels in Germany and the United Kingdom where EU Green Deal sustainability credits displace canned alternatives. Exploit cryogenic equipment technician scarcity at smaller processors through specialized maintenance service offerings. For Investors and Strategic Acquirers: Distressed-cycle entries favor vegetable-centric processors with cross-border plant networks in Belgium and Poland. Long-term viability hinges on five-to-ten year positioning for ready-meal manufacturing expansion and traceability digitization mandates. Monitor FDA cold-chain documentation requirement tightening as inflection indicator for premium contract pricing eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Freezing Unit Deployment | Containerized cryogenic systems enable Polish processors to scale output in 500-kilogram seasonal increments. |
| Backward Integration into Berry Sourcing | Uren Food Group's European network sustains year-round availability against harvest-window bottlenecks. |
| Single-Serve Pouch Automation | Vertical form-fill-seal robotics open convenience-store distribution with reduced minimum order quantities. |
| HACCP Certification Investment | FDA facility approval processes extend 12-18 months, creating barrier against new freezing line entrants. |
| EU Green Deal Compliance Positioning | Sustainability procurement credits in German public-sector contracts create preferential processor access. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this IQF market assessment. Primary interviews with freezing line engineers, foodservice procurement directors, and contract catering operators combined with FDA enforcement records, USDA grading reports, EFSA contaminant thresholds, and EU import documentation. Bottom-up capacity modeling across Belgian and Polish processing plants triangulated against top-down demand estimates from quick-service restaurant chain procurement disclosures.
Segmentation-level granularity modeled product type at cryogenic tunnel versus mechanical freezing technology tiers, application channel at food processing versus foodservice versus retail workflows, and packaging format at bulk tote versus single-serve pouch configurations. CAGR derivation applied volume-weighted averaging across the projection horizon with industry-specific inputs including cryogenic nitrogen pricing volatility indices and seasonal berry harvest yield patterns.
Energy cost volatility, regulatory documentation requirement shifts, and fresh produce substitution through controlled-atmosphere logistics are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Global Pickle Market