
 Boysenberry Market | 2026-2036
Boysenberry Market Size, Share, and Industry Trends Forecast 2026-2036
Boysenberry Market Outlook
IQF (individually quick frozen) technology is expanding its share of boysenberry processing economics as fresh-to-frozen substitution cuts perishability losses and extends seasonal revenue windows. Van Drunen Farms leverages its Illinois-based drying infrastructure to dominate industrial ingredient supply for bakery and snack channels. Willamette Valley Fruit Co anchors Pacific Northwest production through cooperative partnerships with Oregon growers. Stark Brothers Nurseries and Orchards differentiates via proprietary cultivar development and rootstock propagation for home orchard and commercial planting stock.
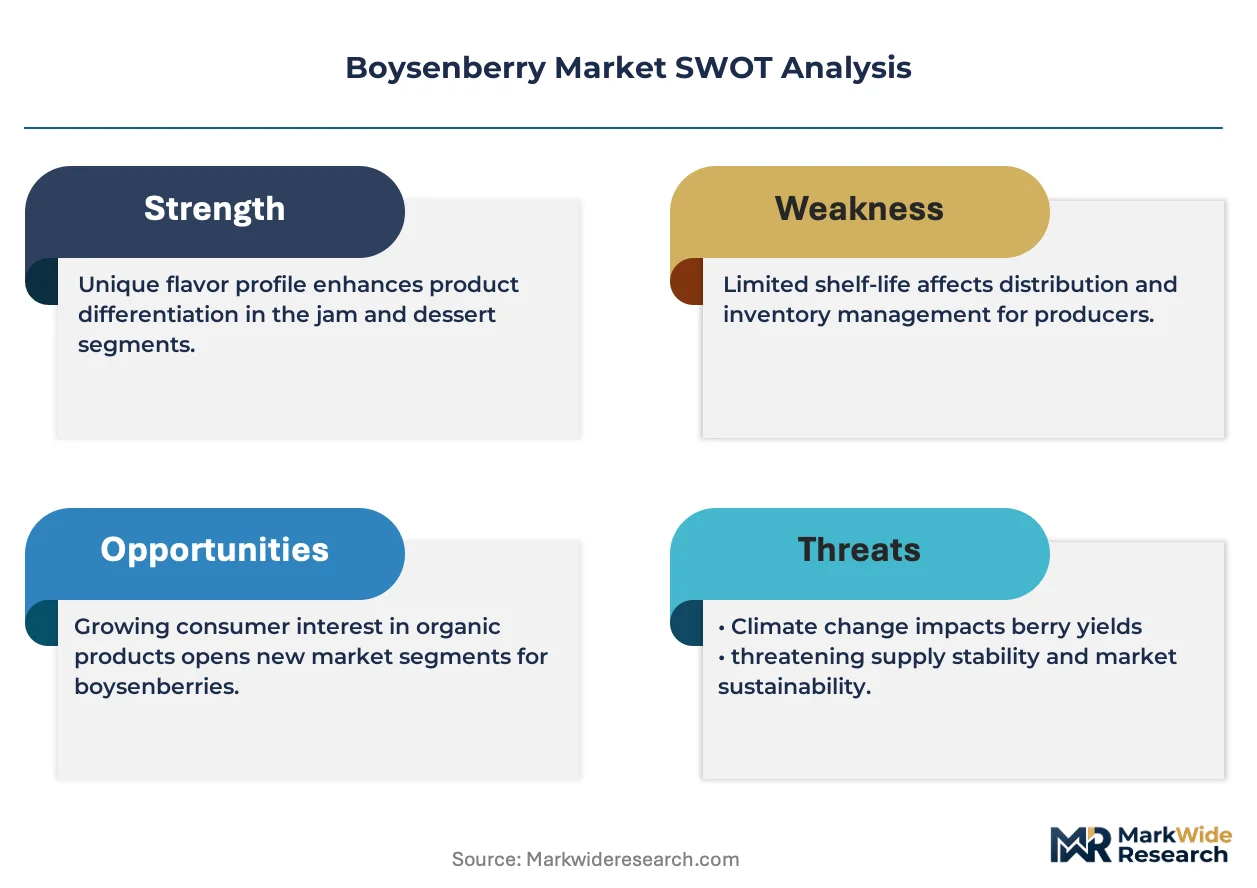
Boysenberry is a hybrid bramble fruit derived from raspberry, blackberry, and loganberry parentage, characterized by elongated drupelets, high anthocyanin content, and titratable acidity ranging from 1.5% to 2.5%, making it suitable for processing into heat-stable colorants and flavor concentrates. Its primary commercial purpose centers on food manufacturing applications where intense pigmentation and tart-sweet balance deliver functional and sensory value. Frozen boysenberry leads volume throughput due to year-round manufacturing demand and reduced cold-chain spoilage, while puree commands premium positioning among beverage manufacturers seeking clean-label fruit bases. Retail consumer demand through farmers' markets sustains price premiums for fresh product during narrow harvest windows.
USDA grading standards for processed berries and FDA food safety modernization rules govern domestic market access, while California's State Water Resources Control Board agricultural discharge requirements shape irrigation compliance costs for Central Valley growers. New Zealand's Ministry for Primary Industries export certification and MPI's food act standards regulate Wai-West Horticulture Ltd's international shipments. Stakeholders must monitor evolving water-right allocations and cold-storage energy tariffs as these operational cost drivers increasingly determine regional competitive advantage.
Market Dynamics
IQF technology adoption is compressing perishability losses across Pacific Northwest and Canterbury Plains supply chains while tightening processor margins through capital intensity requirements.
Growth Catalysts
- Functional Beverage Formulation:Craft soda manufacturers are accelerating puree procurement for clean-label product lines targeting antioxidant positioning.
- California State Water Resources Control Board Compliance:Agricultural discharge regulations are forcing efficiency investments that yield long-term yield stability for Central Valley growers.
- Anthocyanin Extraction:Heat-stable colorant demand from confectionery manufacturers is pulling premium berry grades into industrial ingredient channels.
Market Restraints
- Water Rights Scarcity:California's Central Valley irrigation allocation cuts are raising per-acre production costs for bramble fruit cultivation.
- Seasonal Labor Dependency:Hand-harvest requirements concentrate operational risk during narrow summer windows across Oregon and Washington.
- Blackberry Substitution:Conventional blackberry purees compete on price for beverage applications where color intensity specifications permit flexibility.
Strategic Opportunities
- Southeast Asian Export Expansion:Premium frozen boysenberry demand from Japan and South Korea food manufacturers remains underserved by current New Zealand capacity.
- USDA Organic Certification Premium Capture:Organic tier pricing spreads are widening as retail channel buyers consolidate procurement around certified supply.
- Controlled Environment Agriculture:Greenhouse bramble production is extending harvest windows for fresh market penetration in high-value urban corridors.
Industry Challenges
- Cold-Chain Energy Tariff Volatility:Frozen inventory carrying costs are compressing processor margins as electricity rates fluctuate across Illinois and Pacific Northwest storage hubs.
- Rootstock Propagation Lead Times:Multi-year cultivar development cycles constrain rapid response to shifting beverage manufacturer flavor preference profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boysenberry Market |
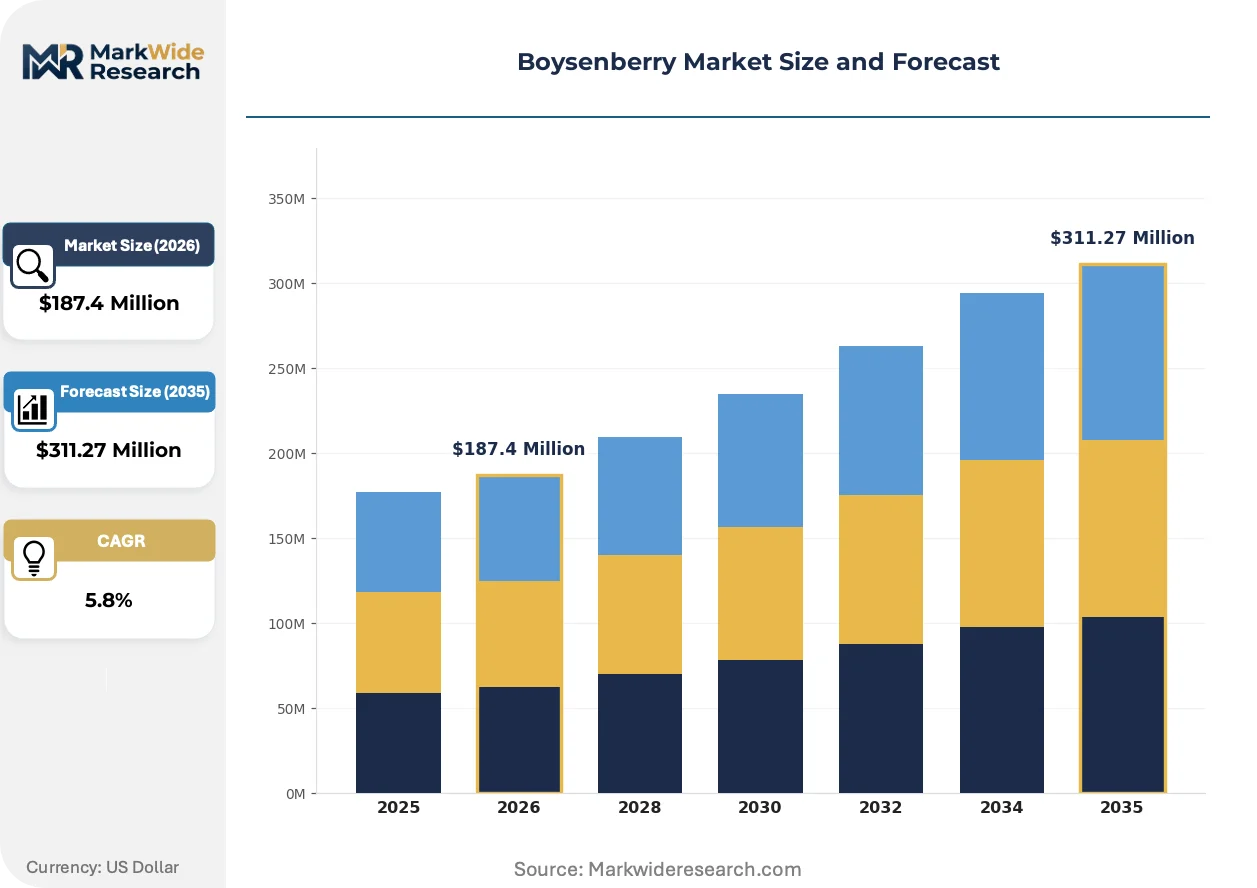
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Puree, Dried End User: Food Industry, Beverage Manufacturers, Retail Consumers, Confectionery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets Application: Desserts, Jams, Sauces, Beverages |
| Companies Covered | Van Drunen Farms, Willamette Valley Fruit Co, Stark Brothers Nurseries and Orchards, California Giant, VentureFruit, Bithell Farms, Wai-West Horticulture Ltd, Knott's Berry Farm, Kerr Concentrates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boysenberry Market Strategic Shifts
Processing technology convergence and regulatory compliance automation are restructuring competitive advantage around capital efficiency and certification speed rather than raw volume scale.
Flash-freezing tunnel systems paired with optical sorting is unifying quality grading and microbial reduction into single-pass operations. Mid-scale processors in Oregon and Canterbury are retrofitting legacy blast freezers to capture beverage manufacturer audit requirements. This unifying architecture is compressing the timeline from field harvest to export-ready frozen inventory from 72 hours to sub-24-hour cycles.
California's State Water Resources Control Board agricultural discharge permits are mandating real-time irrigation monitoring and runoff containment infrastructure. Berry growers in the Central Valley are deploying sensor networks and retention ponds to meet escalating compliance thresholds. Fresh market operators face the steepest capital burden as they lack the frozen channel's margin buffer to amortize infrastructure costs.
Beverage manufacturer procurement is consolidating around direct processor relationships that bypass traditional distributor markups. Craft soda and functional drink formulators in the Pacific Northwest are negotiating multi-year puree supply contracts with Illinois-based drying facilities. This channel compression is most visible in the premium organic tier where traceability documentation requirements favor vertically integrated suppliers.
Boysenberry Market Segmentation
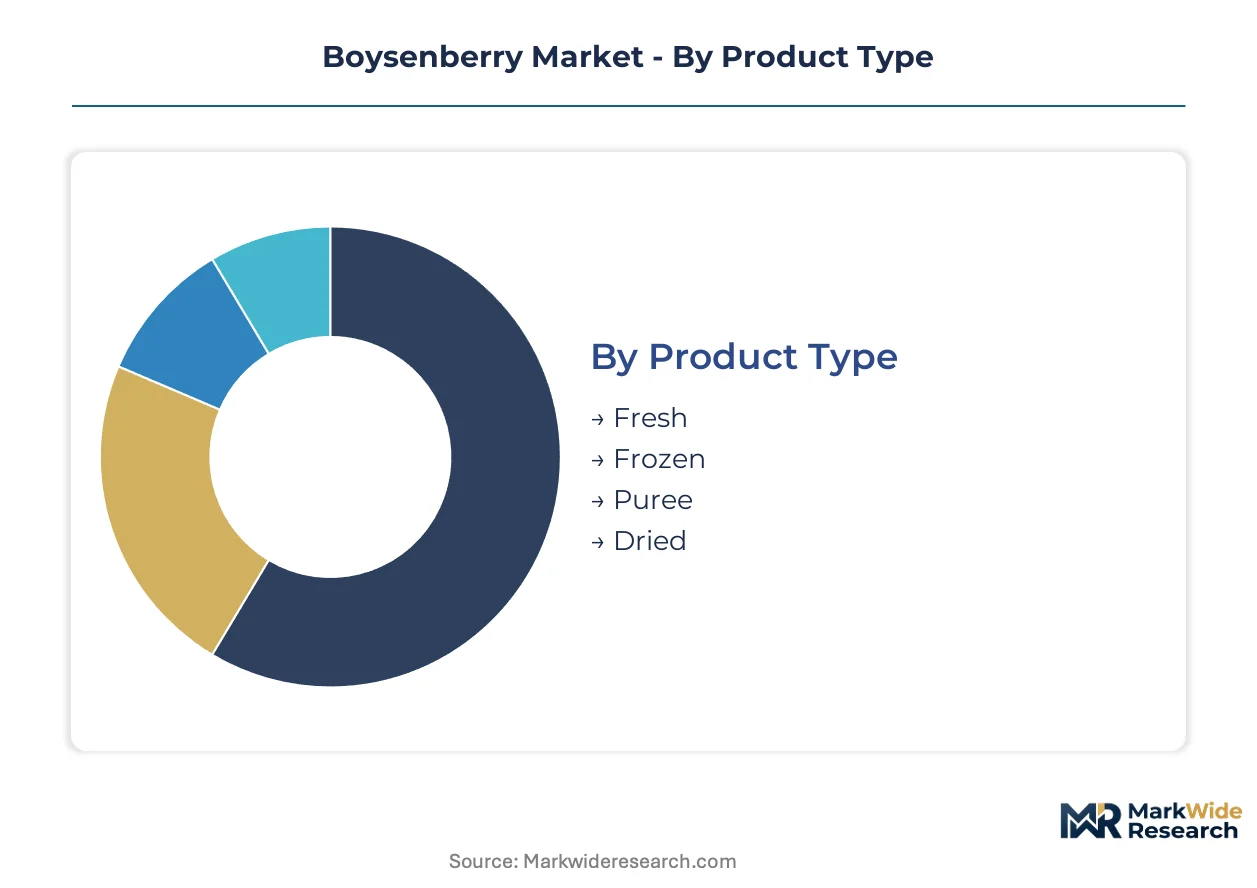
Boysenberry procurement decisions hinge on perishability tolerance, processing requirements, and end-use specifications. Manufacturers prioritize frozen and puree formats for year-round formulation flexibility, while fresh sales concentrate in narrow harvest windows with steep price premiums.
Product Type:
Buyers select formats based on cold-chain infrastructure and shelf-life requirements against application heat-stability needs.
- Frozen:IQF processing preserves drupelet integrity and anthocyanin concentration for industrial ingredient channels. Beverage manufacturers in the Pacific Northwest and Canterbury Plains anchor procurement contracts around frozen inventory for smoothie and functional drink bases. Volume sits with Frozen; growth tilts toward Puree.
- Puree:Heat-pasteurized liquid format delivers standardized brix levels and titratable acidity for clean-label beverage formulation. Craft soda producers accelerate direct-processor contracting to bypass distributor markups and secure traceability documentation.
- Fresh:Hand-harvested fruit with 3-5 day shelf life commands premium positioning at farmers' markets and specialty retail in Oregon's Willamette Valley.
- Dried:Low-moisture ingredient processed through Illinois-based drying infrastructure for bakery and snack manufacturing channels.
Frozen inventory dominates throughput; puree contracts expand fastest on beverage manufacturer demand.
End User:
Application-specific color intensity and acidity specifications drive procurement channel selection across manufacturing tiers.
- Beverage Manufacturers:Anthocyanin extraction for heat-stable colorants and tart-sweet flavor balance in craft sodas and functional drinks. Pacific Northwest formulators negotiate multi-year supply agreements with puree processors.
- Food Industry:Frozen boysenberry supplies bakery, dairy, and prepared dessert manufacturing with year-round formulation consistency.
- Confectionery:Premium berry grades enter industrial colorant channels where intense pigmentation justifies ingredient cost premiums.
- Retail Consumers:Fresh market demand concentrates in urban corridors with farmers' market access during narrow summer harvest windows.
Food Industry commands current volume; Beverage Manufacturers show steepest expansion trajectory on clean-label antioxidant positioning.
Distribution Channel:
Traceability requirements and margin compression reshape channel selection for organic-certified supply tiers.
- Supermarkets:Frozen retail packs and private-label puree lines reach mass-market consumers through conventional grocery distribution.
- Online Retail:Direct-to-consumer frozen shipments expand in urban corridors with reliable last-mile cold-chain infrastructure.
- Specialty Stores:Premium organic tiers and small-batch dried products target health-conscious shoppers in metropolitan markets.
- Farmers' Markets:Fresh boysenberry sales sustain price premiums through direct producer-consumer relationships in Oregon and Washington.
Supermarkets anchor frozen volume; Online Retail gains fastest on subscription-based puree replenishment models.
Application:
Heat-processing tolerance and color stability requirements differentiate formulation-grade from commodity-tier procurement.
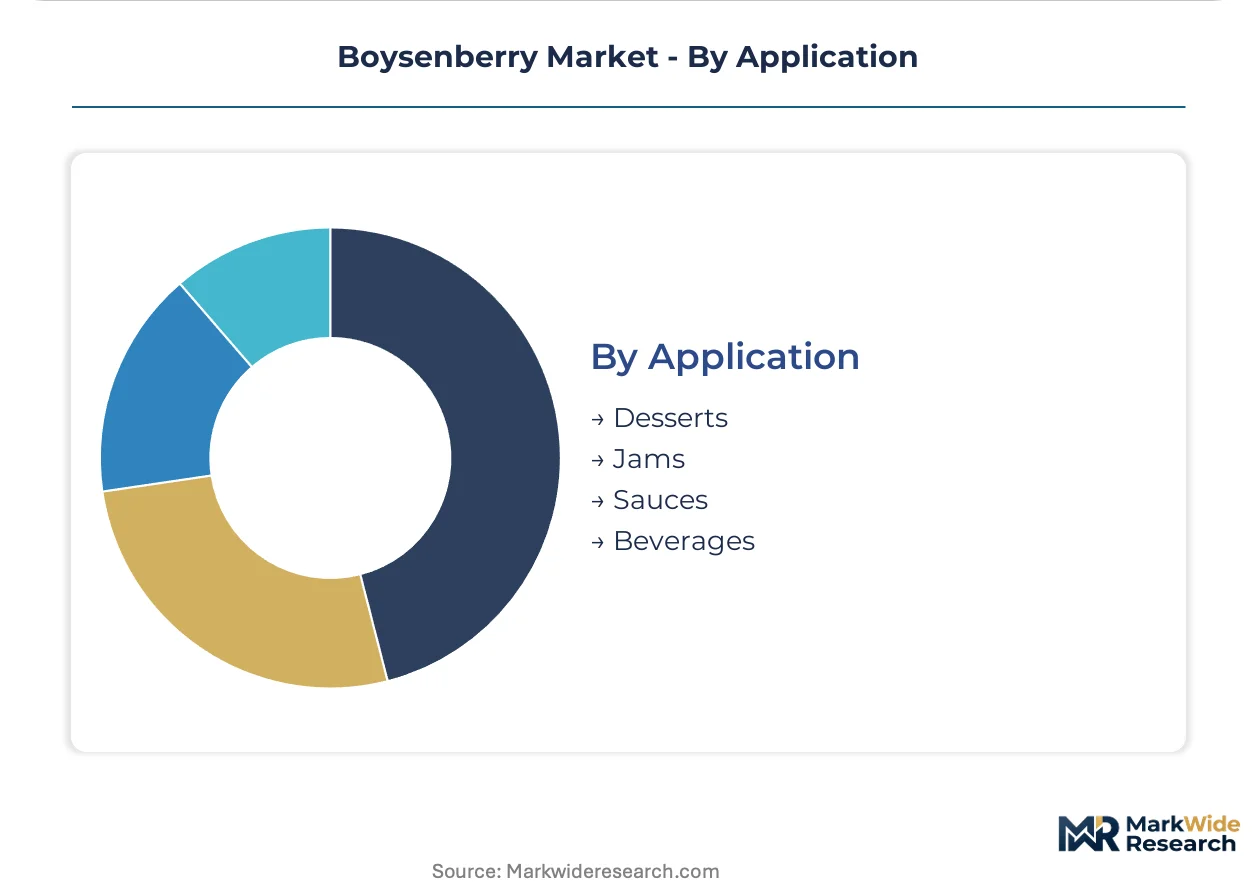
- Beverages:Puree and concentrate formats deliver consistent acidity and anthocyanin levels for functional drink and craft soda manufacturing.
- Jams:High-pectin fruit base with balanced sugar-acid ratios for preserved spread production in commercial and artisanal channels.
- Desserts:Frozen and fresh formats supply ice cream, pastry, and prepared dessert manufacturing with seasonal and year-round options.
- Sauces:Reduced puree applications in savory-sweet condiment formulations for foodservice and retail sauce categories.
Jams retain stable volume; Beverages climb the fastest on antioxidant-positioned product line expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturers in the Pacific Northwest and Canterbury Plains drive procurement concentration for premium puree and frozen formats. Regulatory water-use restrictions and export certification requirements reshape production economics across major supply zones. Processing infrastructure clusters around Illinois drying facilities and New Zealand's South Island cold-chain hubs.
United States
California's Central Valley growers face tightening irrigation allocations under State Water Resources Control Board agricultural discharge permits. USDA organic certification requirements and FDA food safety modernization rules govern domestic market access for processed berry exports. Van Drunen Farms anchors industrial ingredient supply through Illinois-based drying infrastructure serving bakery and snack channels.
New Zealand
Canterbury Plains horticulture clusters supply premium frozen boysenberry to Japan and South Korea food manufacturers. MPI's food act standards and export certification requirements regulate Wai-West Horticulture Ltd's international shipments. Cool-climate production advantages support year-round frozen inventory positioning for Asian export markets.
Australia
Tasmania's cool-climate berry regions expand cultivation for domestic puree demand and limited Asian export trials. State-level agricultural water licensing and biosecurity protocols govern interstate shipment compliance. Processing capacity remains concentrated in mainland Victoria with limited on-island freezing infrastructure.
United Kingdom
Specialty food importers source frozen boysenberry for artisanal jam and dessert manufacturing in London and Southeast England. FSA food safety standards and post-Brexit import documentation requirements reshape EU supply relationships. Direct procurement from Canterbury Plains processors bypasses traditional continental distribution channels.
Boysenberry Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with puree processors capturing premium pricing through direct beverage relationships while frozen commodity suppliers compete on volume scale. The vendor base concentrates around three strategic archetypes: vertically integrated orchard-processor hybrids, cooperative grower networks, and dedicated ingredient drying specialists. Capacity expansion through IQF tunnel retrofits and strategic partnerships with craft soda formulators represent the dominant competitive moves.
Among North American fabricators, Van Drunen Farms exemplifies the industrial drying specialist archetype through captive Illinois infrastructure. Willamette Valley Fruit Co occupies a cooperative network position anchoring Pacific Northwest production through Oregon grower partnerships. Stark Brothers Nurseries and Orchards represents the propagation-focused tier with proprietary cultivar development for planting stock supply.
| Leading Market Players |
|---|
| Van Drunen Farms |
| Willamette Valley Fruit Co |
| Stark Brothers Nurseries and Orchards |
| California Giant |
| VentureFruit |
| Bithell Farms |
| Wai-West Horticulture Ltd |
| Knott's Berry Farm |
| Kerr Concentrates |
| Others |
Value Chain & Pricing Dynamics
California agricultural water futures and irrigation allocation indices cascade through boysenberry production economics, compressing margins for Central Valley growers while elevating premiums for Canterbury Plains and Willamette Valley supply. This input cost volatility stratifies pricing tiers around certification grade and cold-chain reliability rather than raw volume scale.
Pricing Analysis
The volume-versus-margin split separates frozen commodity throughput from puree premium capture. Three-tier pricing structure across premium organic, standard IQF, and economy-grade frozen tiers reflects USDA certification status and anthocyanin concentration specifications. Pricing pressure stems from California water-right scarcity raising per-acre cultivation costs. Beverage manufacturers show least price sensitivity due to clean-label positioning requirements, while foodservice distributors face acute margin compression.
Supply Chain Analysis
USDA organic certification and MPI export qualification gating filter supplier access to premium-tier procurement contracts. Geographic concentration centers on New Zealand, Oregon, and California as primary production nodes. Raw material dependencies include irrigation water allocations, seasonal labor pools, and IQF processing capacity. Single-source vulnerability concentrates in Illinois drying infrastructure serving industrial ingredient channels. Distribution runs through direct processor-beverage manufacturer relationships bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained system where multi-year rootstock propagation cycles and limited cool-climate acreage prop pricing power toward established processors with captive cultivation partnerships.
For Market Incumbents: Acquire IQF tunnel freezing capacity in Canterbury Plains and Willamette Valley to lock in export-ready throughput. Blackberry substitution threats in beverage applications demand anthocyanin concentration differentiation through cultivar selection. Backward integration into proprietary rootstock propagation secures planting stock control against varietal preference shifts. For New Entrants and Emerging Players: Capture Southeast Asian premium frozen demand currently underserved by New Zealand capacity constraints. Controlled environment agriculture in high-value urban corridors offers the most penetrable fresh market entry point. Direct-to-craft-soda-processor puree supply contracts bypass established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors vertically integrated orchard-processor hybrids with established organic certification and Asian export relationships. Long-term viability rests on water-right security and cold-chain infrastructure ownership. Watch California State Water Resources Control Board allocation rulings as the inflection signal for regional competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| IQF Tunnel Retrofit Investment | Sub-24-hour harvest-to-freeze cycles meet beverage manufacturer audit requirements. |
| Direct Processor Partnership | Channel compression eliminates distributor markups in premium organic tier. |
| Proprietary Cultivar Development | Stark Brothers' rootstock propagation accelerates response to flavor preference shifts. |
| Controlled Environment Agriculture Expansion | Greenhouse production extends fresh market harvest windows in urban corridors. |
| USDA Organic Certification Investment | Widening organic tier pricing spreads reward certified supply consolidation. |
Study Parameters
Document review covered USDA agricultural discharge permits, MPI export certification standards, and FDA food safety modernization rules, complemented by interviews with boysenberry processors, beverage formulation executives, and Oregon cooperative growers. Secondary validation drew from customs trade data, state water resource board filings, and SEC disclosures by listed food ingredient suppliers. Bottom-up cultivation acreage estimates and top-down procurement demand curves were triangulated against processor capacity utilization rates.
Segment-level value outputs were derived across product type, end-user application, and distribution channel dimensions over the projection horizon. CAGRs were computed from historical price trajectory analysis and forward capacity expansion announcements. Key forecast inputs included California irrigation allocation scenarios and Asian import tariff schedules for frozen berry products.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to water-right adjudication and cold-chain energy tariff volatility. Projections reflect assumptions around sustained craft soda demand growth and stable New Zealand export certification pathways. A model refresh is warranted upon material change in California agricultural discharge permit enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Europe Shiitake Mushroom Market