
 Fruit Packaging Market | 2026-2036
Fruit Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Packaging Market Analysis
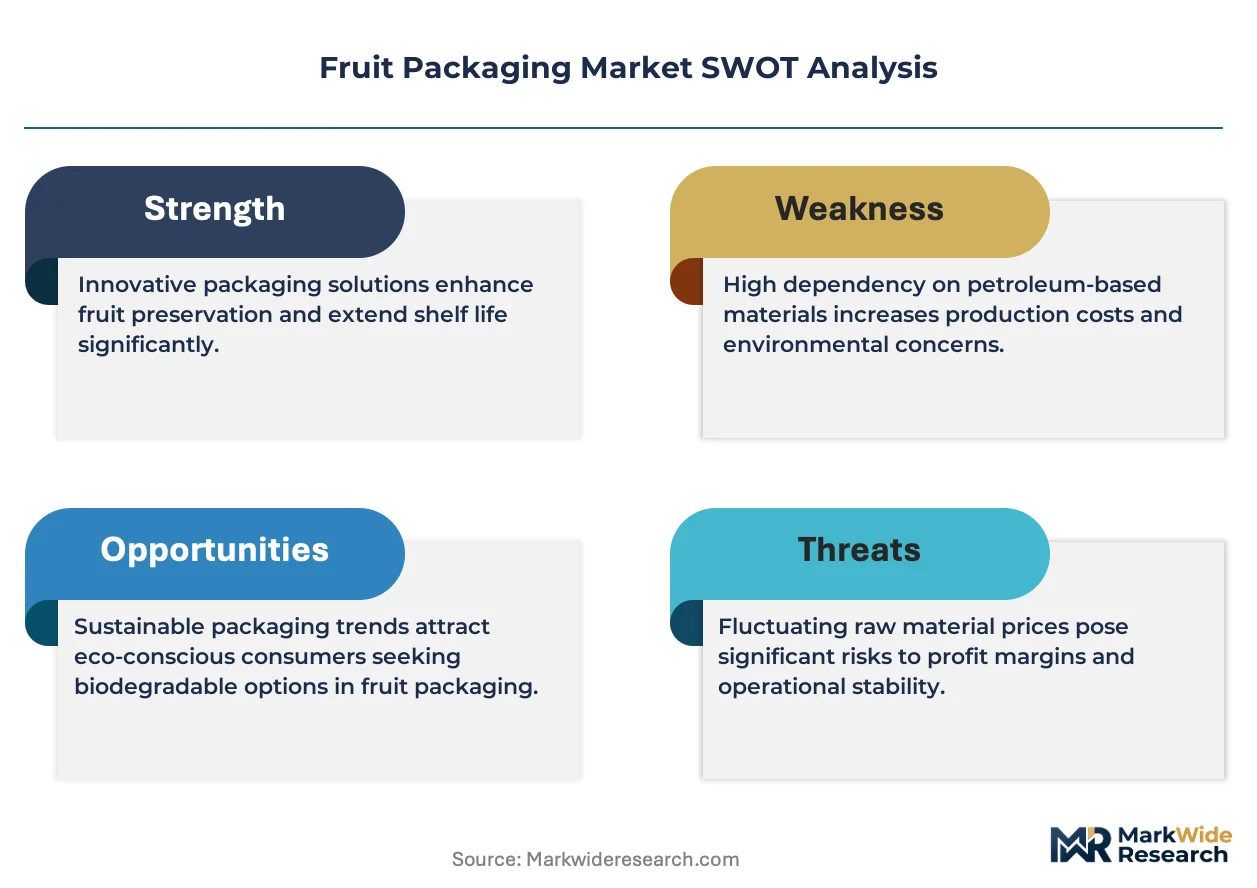
ISO 22000 certification is rotating as the primary gating standard for suppliers serving major fruit exporters. Huhtamaki Oyj leverages its molded fiber expertise to anchor European berry packaging demand. Mondi Group sustains competitive positioning through integrated kraft paper operations across Central European mills. Smurfit Kappa dominates corrugated tray supply to Iberian citrus exporters through regional manufacturing scale.
Fruit packaging encompasses protective enclosures engineered from corrugated board, molded pulp, flexible films, or rigid plastics, designed to maintain respiration rates, moisture equilibrium, and mechanical integrity during post-harvest handling and distribution. Wall thickness, venting aperture density, and ethylene permeability constitute critical functional parameters that determine shelf-life extension for climacteric produce. Carton formats command the largest volume share among packaging types due to structural efficiency in palletized ocean freight, while biodegradable materials represent the fastest-expanding material category as retail chains impose plastic reduction commitments. Pouch formats occupy niche premium positioning for cut-fruit convenience segments where modified atmosphere barriers justify unit cost premiums.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility frameworks that reshape material selection across European supply chains, while FDA food contact substance notifications govern barrier coatings for US-bound fruit exports. BIS certification requirements for food-grade paper imports into India add compliance layers for multinational suppliers. Stakeholders must monitor evolving state-level packaging EPR legislation and bioplastics labeling standards to preempt supply chain disruption.
Market Dynamics
Extended producer responsibility frameworks under the EU Packaging and Packaging Waste Regulation are forcing material substitution decisions across European supply chains, while fresh produce exporters in Spain and Peru scale protective formats to reduce ocean freight losses.
Growth Catalysts
- EU PPWR mandates:Material recovery targets are accelerating fiber-based tray adoption among Iberian citrus exporters seeking compliance certainty.
- Climacteric respiration control:Modified atmosphere films with tuned ethylene permeability are extending shelf life for avocado shipments from Peru's export corridor.
- Valencia cluster concentration:Spain's integrated citrus processing infrastructure is driving standardized corrugated format demand at scale.
Market Restraints
- Pulp fiber cost volatility:Kraft linerboard input prices fluctuate with Nordic softwood supply cycles, compressing molded fiber margin structures.
- Barrier coating technical limitation:Current bio-based moisture barriers lack the grease resistance required for stone fruit applications without synthetic additives.
- India BIS certification friction:Food-grade paper import requirements add compliance timelines that delay European supplier market entry.
Strategic Opportunities
- Peru avocado corridor expansion:Export volume growth is creating demand for vented corrugated formats with humidity control features.
- Cut-fruit convenience channel:Modified atmosphere pouches are penetrating retail ready-to-eat segments where unit premiums justify barrier costs.
- Biodegradable material convergence:Molded pulp with bio-based coatings is capturing share in berry clamshell applications previously served by PET.
Industry Challenges
- ISO 22000 certification timelines:Supplier qualification periods for major exporters extend 12-18 months, constraining new entrant velocity.
- Legacy equipment integration:Automated packing lines in established citrus facilities require retrofitting to handle fiber tray formats at speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Packaging Market |
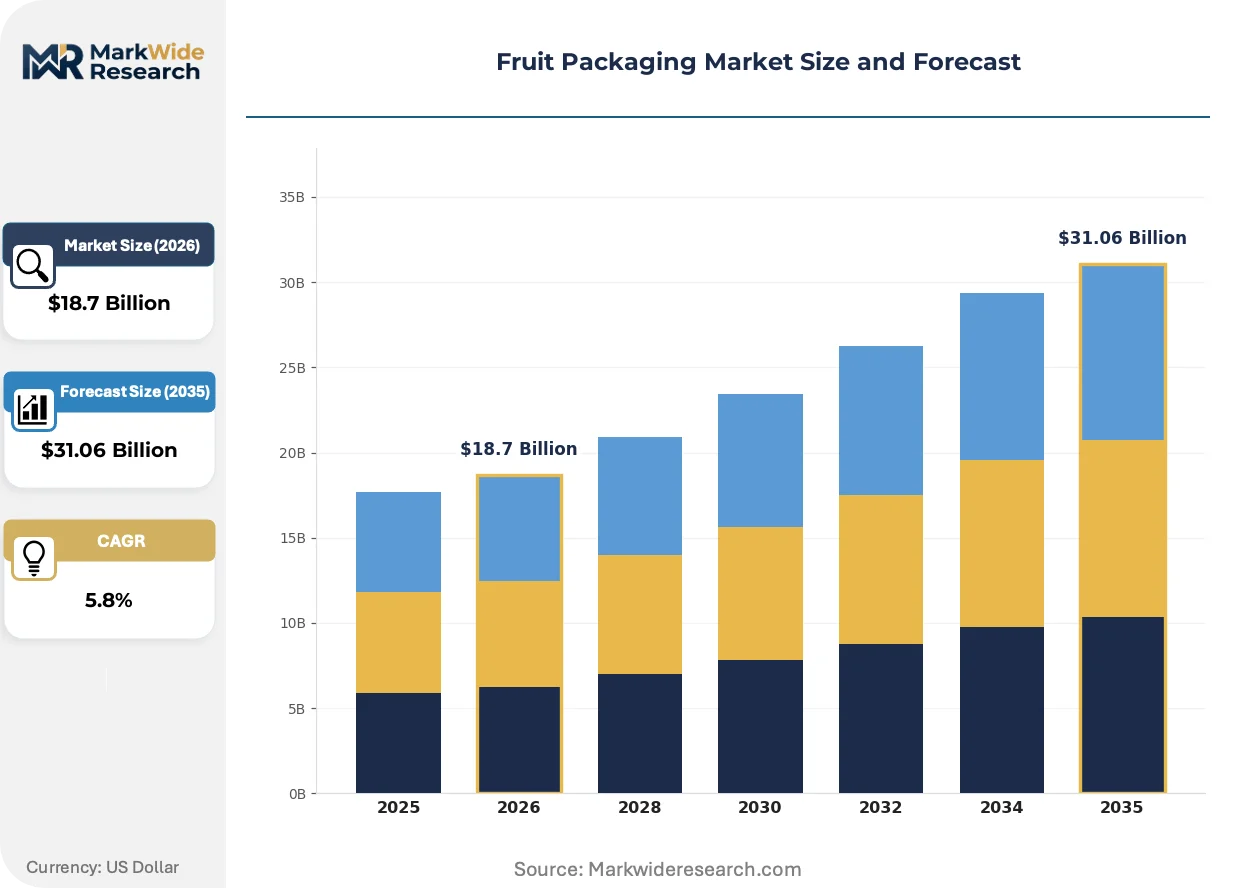
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Boxes, Pouches, Trays, Cartons Material: Plastic, Paper, Glass, Biodegradable End User: Retailers, Wholesalers, Exporters, Food Services Size: Small, Medium, Large, Extra Large |
| Companies Covered | Winpak Ltd., International Paper Company, ProAmpac, Huhtamaki Oyj, DS Smith Plc, Amcor plc, Mondi Group, Smurfit Kappa, Graphic Packaging Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Packaging Market Emerging Trajectories
Material science advances and regulatory compliance pressures are converging to reshape competitive positioning across protective produce formats, with fiber-based solutions capturing share from conventional plastics in high-volume applications.
Molded fiber trays with engineered venting aperture density are displacing expanded polystyrene in berry packaging applications. Major European retailers are mandating plastic-free produce sections by 2025, accelerating supplier qualification timelines for fiber alternatives. The shift is compressing demand for petroleum-based formats while expanding capacity requirements for thermoformed pulp operations.
The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility frameworks that reshape material selection decisions. Recycled content thresholds and material recovery targets are forcing corrugated producers to certify closed-loop fiber sourcing. Iberian citrus exporters are responding by consolidating supplier relationships around integrated paperboard mills with verified recycling streams.
Retail chain plastic reduction commitments are rotating procurement criteria toward certified biodegradable formats. Major supermarket groups in Northern Europe are unbundling packaging specifications from produce supply contracts, creating direct relationships with packaging specialists. This pattern is most visible in Germany and the Netherlands, where centralized distribution centers enable standardized format adoption across store networks.
Fruit Packaging Market Segmentation
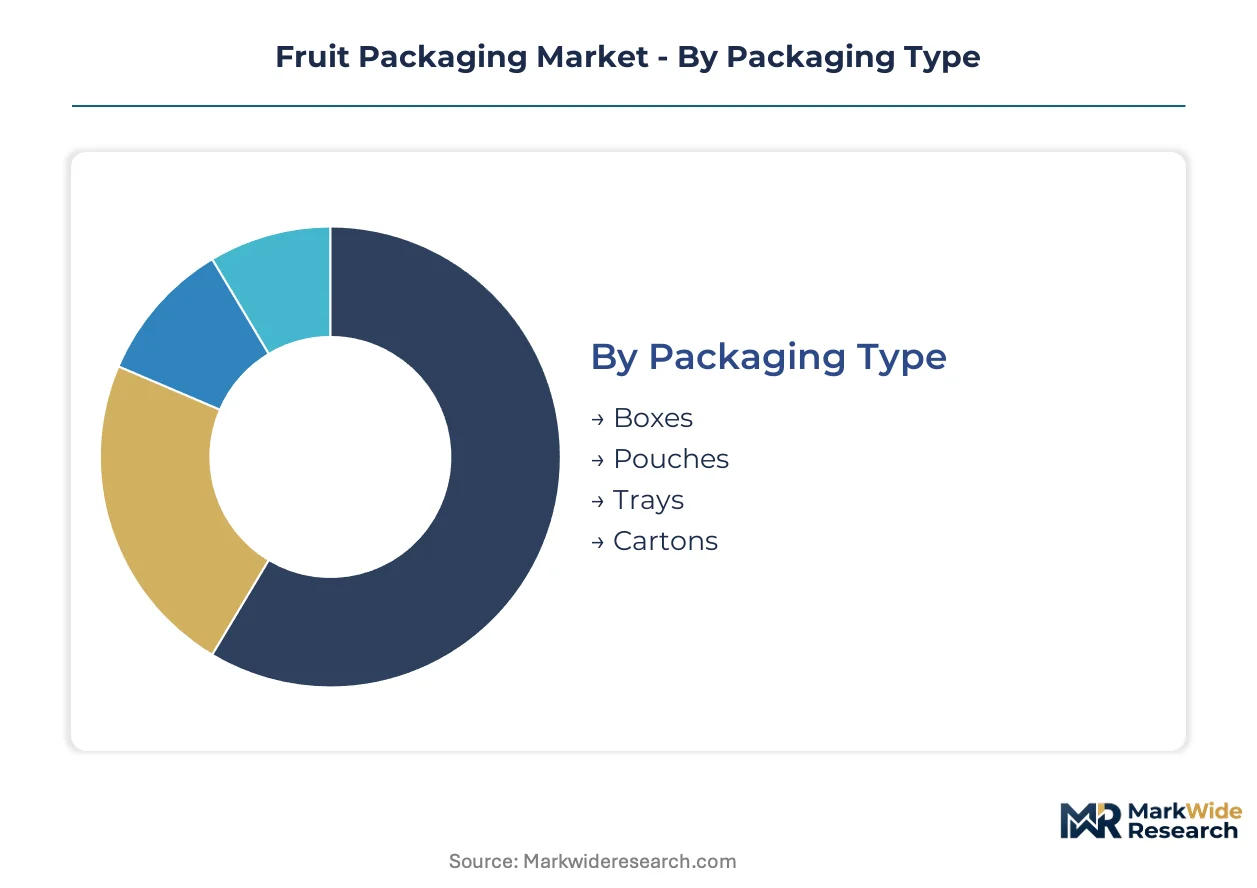
Segmentation in fruit packaging reflects divergent channel economics. Ocean freight consolidation favors rigid formats with pallet efficiency, while convenience retail drives premium barrier technologies. Material selection increasingly tracks regulatory geography rather than commodity pricing.
Packaging Type:
Channel mix determines format dominance: corrugated cartons flow through export logistics, pouches penetrate convenience retail, trays serve fresh-cut operations, and boxes handle bulk wholesale distribution.
- Cartons:Multi-wall corrugated construction with engineered flute profiles withstands stacking stress during containerized shipping. Spain's Valencia citrus cluster and Peru's avocado corridor standardize on this format for ocean freight efficiency. By volume, cartons lead. By growth pace, pouches are expanding most quickly.
- Trays:Molded pulp or PET thermoforming with compartmentalized cavities protects soft berries through automated packing lines. Huhtamaki Oyj and similar suppliers anchor European demand through ISO 22000-certified production.
- Pouches:Flexible laminates with modified atmosphere barriers serve cut-fruit convenience segments where shelf-life extension justifies unit cost premiums. German and Dutch retail chains drive specification unbundling from produce contracts.
- Boxes:Rigid board or reusable plastic containers handle wholesale volume transactions with minimal branding requirements.
Carton formats capture the highest shipment volumes. Pouch formats claim the steepest expansion trajectory through premium convenience channels.
Material:
Cost tiers separate commodity plastics from certified fiber alternatives, with biodegradables commanding margin premiums in regulated European markets.
- Paper:Kraft linerboard and molded pulp deliver structural integrity with EU Packaging and Packaging Waste Regulation compliance. Iberian citrus exporters consolidate around integrated mills with verified recycling streams.
- Plastic:PET, PP, and PE films retain cost advantage in moisture-critical applications, though retailer plastic-free mandates compress long-term demand.
- Biodegradable:Polylactic acid and molded pulp with bio-based coatings capture berry clamshell share from petroleum-based formats. Northern European supermarket groups mandate plastic-free produce sections.
- Glass:Premium preserves and specialty fruit products utilize inert barrier properties with limited fresh produce penetration.
Paper materials dominate shipment tonnage. Biodegradable alternatives gain share fastest under regulatory pressure.
End User:
Customer type dictates specification complexity: exporters prioritize transit survival, retailers demand shelf-ready presentation, food services optimize labor efficiency.
- Exporters:Spanish citrus and Peruvian avocado operations specify vented corrugated with humidity control features to reduce ocean freight losses. ISO 22000 certification gates supplier qualification.
- Retailers:Centralized distribution in Germany and Netherlands enables standardized format adoption across store networks, with direct packaging specialist relationships replacing bundled produce contracts.
- Wholesalers:Bulk handling requirements favor cost-minimized formats with minimal unit-level customization.
- Food Services:Pre-portioned and ready-to-serve formats reduce kitchen labor, driving pouch and tray demand in institutional channels.
Exporters generate the highest absolute volume. Retail procurement is shifting fastest toward certified sustainable formats.
Size:
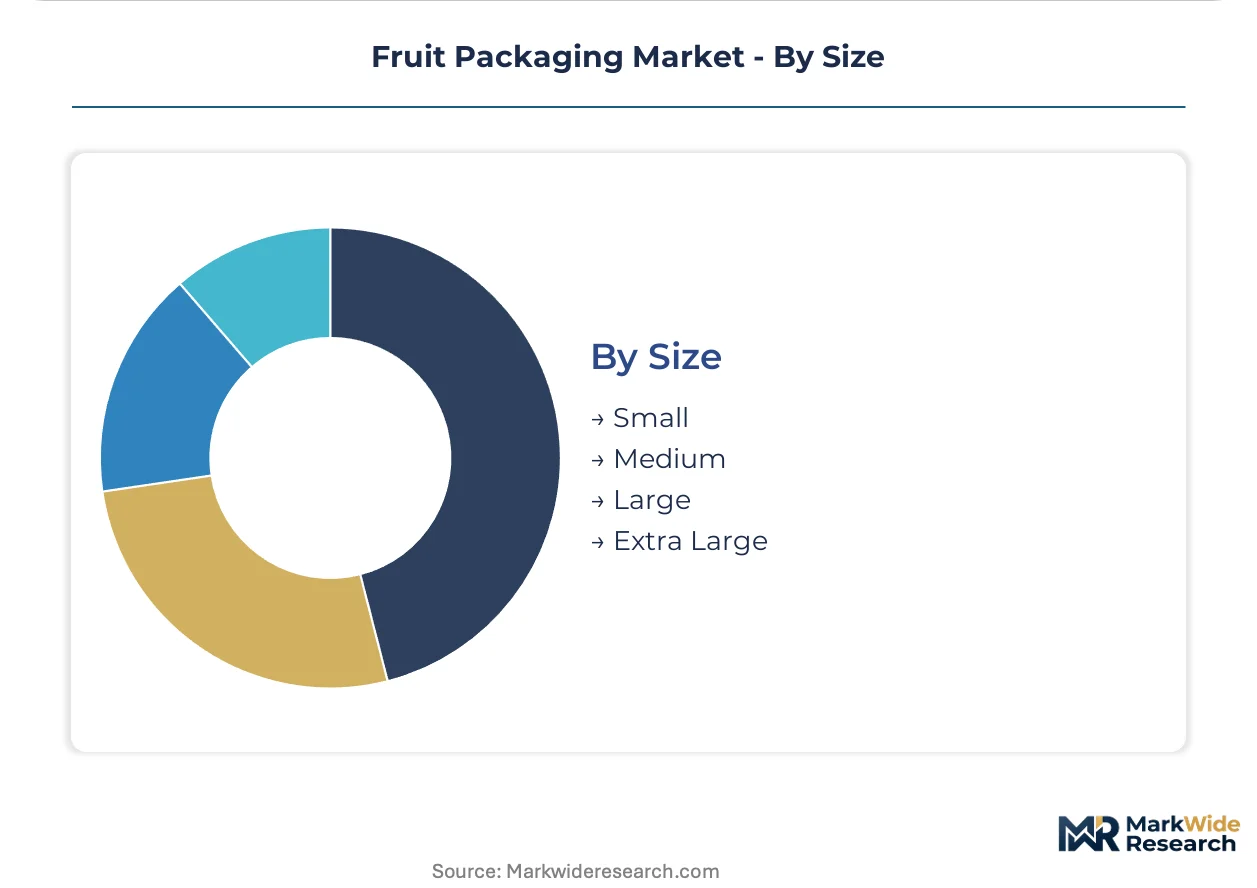
Volume scale correlates with distribution channel: retail-ready small formats versus bulk export large configurations.
- Large:Standard pallet configurations optimize container cube utilization for Valencia citrus and Peru avocado export corridors.
- Medium:Retail case packs balance shelf replenishment frequency with handling efficiency in European supermarket distribution centers.
- Small:Single-serve and snack portions capture convenience premium in Northern European retail ready-to-eat segments.
- Extra Large:Bulk institutional and food service formats minimize per-unit packaging cost for high-volume operators.
Large formats dominate export tonnage. Small formats climb fastest through convenience channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Valencia anchors Iberian citrus export capacity, handling over four million tons of fruit annually through specialized reefer terminals that demand standardized corrugated formats.
Spain
Valencia's integrated citrus processing infrastructure drives standardized carton demand at scale. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility frameworks that reshape material selection across Spanish supply chains. Andalusian berry growers are consolidating supplier relationships around ISO 22000-certified molded fiber producers to meet retailer plastic-free commitments.
Peru
Avocado export corridors through Callao port require vented corrugated formats with humidity control features to reduce ocean freight losses. Peru's national agricultural regulator enforces phytosanitary packaging standards for Hass avocado shipments to European and US markets. Ica Valley producers are scaling protective packaging investments as export volumes climb toward Asian destinations.
Germany
Centralized retail distribution centers enable standardized format adoption across supermarket networks. The country's national packaging regulator enforces strict recycling quotas under circular economy frameworks. Berlin and Hamburg logistics hubs are unbundling packaging specifications from produce contracts, creating direct relationships with fiber tray specialists.
Netherlands
Rotterdam's port infrastructure serves as the primary European entry point for Latin American fruit imports, driving demand for pallet-efficient carton designs. Dutch environmental authorities implement stringent extended producer responsibility schemes for plastic packaging alternatives. Venlo's food logistics cluster hosts major retail distribution centers mandating biodegradable berry clamshell formats.
United States
California's Central Valley citrus and berry production anchors domestic protective packaging demand, with FDA food contact substance notifications governing barrier coatings. The EPA oversees state-level packaging waste management frameworks that vary across jurisdictions. Salinas Valley leafy green processors are adopting modified atmosphere pouches for cut-fruit convenience segments.
Fruit Packaging Market Vendor Landscape
Listed leaders compete with private specialists across material technology and geographic coverage dimensions. The vendor base spans integrated paperboard mills, specialized molded fiber producers, and flexible film converters serving distinct channel requirements. Three archetypes dominate: integrated European paperboard groups with captive fiber sourcing, Nordic molded pulp specialists leveraging sustainability credentials, and North American flexible packaging converters with barrier coating expertise. Competitive moves concentrate on backward integration into recycled fiber supply and strategic partnerships with major retail chains.
Among integrated European paperboard groups, Huhtamaki Oyj and Mondi Group exemplify the fiber-based packaging archetype with established positions in produce protection formats. Smurfit Kappa occupies a position within the corrugated supply tier serving Iberian export corridors. These three entities represent distinct strategic approaches to material science and regional market development.
| Leading Market Players |
|---|
| Winpak Ltd. |
| International Paper Company |
| ProAmpac |
| Huhtamaki Oyj |
| DS Smith Plc |
| Amcor plc |
| Mondi Group |
| Smurfit Kappa |
| Graphic Packaging Holding Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Iberian citrus exporters and integrated paperboard mills lock in both kraft linerboard supply access and eighteen-month price visibility against Nordic softwood pulp volatility. These arrangements concentrate procurement power among Valencia cluster operators while insulating molded fiber margins from spot market fluctuations.
Pricing Analysis
Volume-discount tiering structures stratify across premium certified fiber, standard corrugated, and economy plastic formats. Price differentiation hinges on ISO 22000 certification grade and pallet cube efficiency in ocean freight. Cost compression in standard corrugated tiers is intensifying because kraft linerboard input prices track Nordic softwood supply cycles. Exporters demonstrate lowest price sensitivity due to compliance-driven procurement, while wholesale distributors face acute margin pressure.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Valencia ports fluctuate with container availability on Asia-Europe trade lanes, compressing delivery windows for Peruvian avocado exporters. Fiber supply draws from Sweden, Finland, and Portugal pulp mills, while barrier coatings rest on bio-based resin feedstocks. Single-source vulnerability concentrates in certified molded fiber capacity serving berry clamshell demand. Distribution runs through centralized retail distribution centers in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fruit packaging sits in early-cycle expansion as EU Packaging and Packaging Waste Regulation mandates force material substitution decisions across European supply chains before compliance deadlines tighten.
For Market Incumbents: Compound regional manufacturing scale through backward integration into recycled fiber supply chains near Valencia and Rotterdam logistics hubs. ISO 22000 certification investment gates supplier relationships with major exporters, while retrofitting legacy citrus packing lines for fiber tray formats at speed defends against molded pulp specialists capturing berry clamshell share.
For New Entrants and Emerging Players: Lead with bio-based barrier coating technology targeting stone fruit applications where current grease resistance limitations exclude fiber alternatives. Peru's avocado export corridor expansion offers the most penetrable geography, with direct relationships with Ica Valley producers bypassing incumbent distributor networks.
For Investors and Strategic Acquirers: Capital is best deployed toward Nordic molded pulp specialists with verified recycling streams and captive softwood fiber supply. Long-term viability over a five-to-ten year window rests on regulatory enforcement consistency across EU member states. The signal to watch is retailer plastic-free produce section mandate acceleration in Northern European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Supply | Captive kraft linerboard sourcing insulates Iberian citrus exporters from Nordic pulp volatility. |
| ISO 22000 Certification Investment | Twelve-month qualification timelines gate supplier relationships with Valencia cluster operators. |
| Bio-Based Barrier Coating Development | Grease-resistant formulations unlock stone fruit applications previously reserved for plastic formats. |
| Peru Avocado Corridor Partnership | Vented corrugated with humidity control features reduces ocean freight losses for Ica Valley producers. |
| Centralized Distribution Center Relationships | Direct procurement with German and Dutch retail chains unbundles packaging from produce contracts. |
Methodological Framework
Cross-validation between regulatory filing analysis and trade flow data anchors the qualitative findings on material substitution patterns. Primary interviews with packaging procurement managers at Spanish citrus exporters, molded fiber plant managers in Nordic markets, retail category buyers in Germany and the Netherlands, and barrier coating R&D directors informed demand drivers. Secondary sources include EU Packaging and Packaging Waste Regulation implementation documents, FDA food contact substance notification databases, and BIS certification requirement circulars. Bottom-up volume modeling triangulates against top-down market sizing across material categories.
Sensitivity analysis tested forecast robustness across pulp fiber cost volatility scenarios and regulatory enforcement intensity variations over the projection horizon. Segmentation dimensions span packaging type, material composition, end-user channel, and geographic production cluster. CAGRs derive from trend extrapolation of historical adoption curves adjusted for policy inflection points. Modeled inputs incorporate EU extended producer responsibility threshold implementation timelines and retailer plastic-free commitment acceleration patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or abrupt bio-based barrier technology breakthroughs would require recalibration. Forecasts reflect assumptions on kraft linerboard price stability and ISO 22000 certification timeline consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market