
 Romanesco Broccoli Market | 2026-2036
Romanesco Broccoli Market Size, Share, and Industry Trends Forecast 2026-2036
Romanesco Broccoli Market Analytics
Conventional cauliflower cultivation is consolidating around Romanesco broccoli as chefs and retailers prize its fractal structure and nuttier flavor profile. Church Brothers Farms leverages its Salinas Valley growing operations to anchor year-round supply for foodservice distributors. D'Arrigo Brothers Company sustains multi-generational expertise in cool-season brassica production across California's Central Coast. Frieda's Inc. differentiates through specialty produce merchandising and direct retail partnerships with premium grocers.
Romanesco broccoli (Brassica oleracea var. botrytis) is an edible flower bud distinguished by its logarithmic spiral phyllotaxy, chartreuse coloration, and vitamin C content exceeding conventional cauliflower by approximately twenty-five percent. Commercial growers harvest the compact inflorescence at six to eight inches diameter before florets separate, preserving the signature geometric form prized by high-end culinary establishments. Fresh Romanesco commands the dominant value share within product type segmentation, though frozen processing grows fastest as IQF technology preserves texture for institutional kitchens. Retail distribution channels capture margin concentration through branded clamshell packaging, while wholesale direct-to-restaurant routes handle volume leadership in urban foodservice corridors.
USDA organic certification and California's Leafy Greens Marketing Agreement shape growing protocols and traceability requirements for domestic producers. EU organic regulations and F-Gas standards for cold-chain refrigeration influence export competitiveness and post-harvest handling infrastructure. Stakeholders must monitor water allocation policies in drought-prone growing regions and evolving consumer willingness to pay premium prices for visual novelty versus nutritional parity with standard brassicas.
Market Dynamics
Specialty produce procurement by high-end culinary establishments is compressing traditional wholesale margins while elevating traceability requirements across the Romanesco broccoli supply chain. This demand-side concentration forces growers to consolidate cultivation expertise and invest in post-harvest handling infrastructure that preserves the vegetable's distinctive fractal geometry.
Growth Catalysts
- EU organic certification:Mandatory compliance with EFSA standards for pesticide residue limits and soil management protocols is opening premium channel access for certified growers. Retailers in Italy and France now require full traceability documentation.
- IQF technology:Individual quick freezing systems preserve cellular structure and color stability, enabling year-round foodservice distribution without seasonal supply gaps. Institutional kitchens increasingly specify IQF Romanesco for menu consistency.
- California's Salinas Valley:Concentrated cool-season brassica expertise and established cold-chain infrastructure anchor North American supply reliability. Church Brothers Farms and D'Arrigo Brothers leverage this cluster for continuous harvest scheduling.
Market Restraints
- Water allocation volatility:Drought-driven restrictions on Central Valley agricultural water access threaten yield predictability and force deficit irrigation practices that reduce head size uniformity.
- Input cost concentration:Nitrogen-based fertilizer pricing tied to natural gas markets creates margin compression for conventional growers unable to pass through cost spikes to fixed-price foodservice contracts.
- Perishability constraints:Romanesco's high respiration rate and sensitivity to ethylene exposure limit post-harvest shelf life to 7-10 days, constraining distribution radius from production centers.
Strategic Opportunities
- Controlled environment agriculture:Vertical farming installations in urban peripheries enable local production with reduced transportation spoilage and premium positioning for restaurant direct-to-kitchen programs.
- USDA organic transition incentives:The Environmental Quality Incentives Program subsidizes certification costs and cover crop establishment for conventional growers converting acreage.
- Direct-to-chef platforms:Specialty produce marketplaces bypass traditional distributor markups, capturing margin through subscription-based harvest forecasting and varietal pre-booking systems.
Industry Challenges
- Genetic consistency maintenance:Open-pollinated seed stock produces phenotypic variation in spiral tightness and color saturation, complicating brand standardization for premium retail clamshell programs.
- Harvest labor availability:Seasonal hand-harvesting requirements for intact head removal face competition from higher-wage permanent crop sectors, forcing mechanization investment or acreage abandonment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romanesco Broccoli Market |
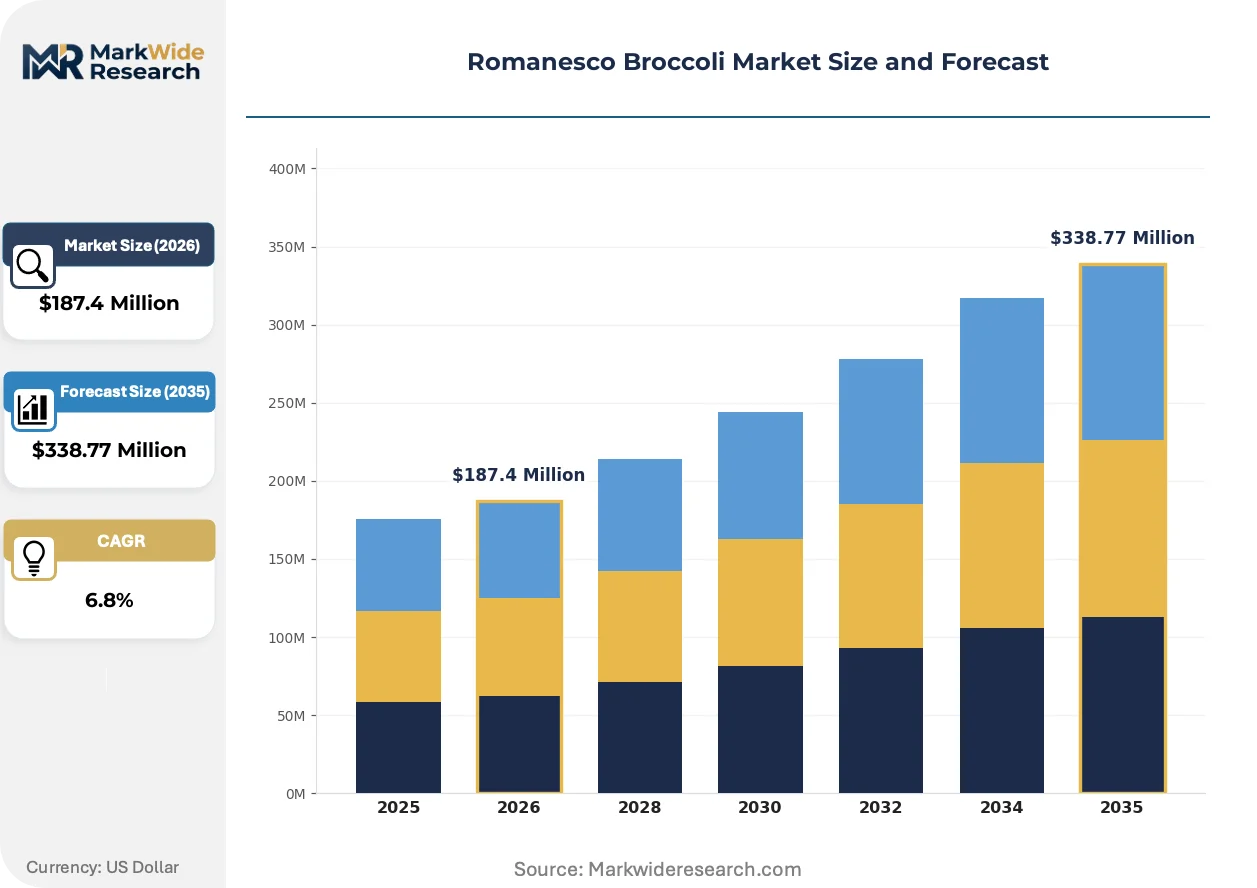
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Canned, Pickled Distribution Channel: Direct, Retail, Wholesale, Online End User: Restaurants, Households, Food Processors, Institutions Packing Type: Bulk, Carton, Bag, Tray |
| Companies Covered | Frieda's Inc., Holmes Seed Company, Victory Seed Company, Church Brothers Farms, D'Arrigo Brothers Company, Seattle Seed Company, Old World Seed Company, The Nunes Company, Rainbow Seeds and Supply, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romanesco Broccoli Market Evolving Landscape
Post-harvest technology and distribution channel restructuring are redefining competitive advantage in specialty brassica markets. Three developments merit particular attention for stakeholders positioning across the value chain.
Spectral sorting systems using near-infrared imaging is electrifying quality control at packhouse operations. These platforms detect internal browning and density variations non-destructively, enabling real-time grading that separates export-grade specimens from domestic retail lots. High-volume handlers in California's Monterey County have adopted this technology to defend contract renewals with national distributors.
California's Leafy Greens Marketing Agreement now mandates field-level environmental monitoring and rapid traceback protocols for all signatory growers. Compliance infrastructure investments have stratified the supplier base, with smaller operators exiting due to documentation burden while integrated farms capture expanded retail shelf space. The regulation's harvest crew hygiene requirements have accelerated automated washing line deployment.
Chef-driven varietal specification is fragmenting procurement patterns away from commodity cauliflower contracts. Fine-dining establishments now pre-book specific harvest windows and head diameter ranges, replacing spot-market purchasing with forward-commitment arrangements. This behavioral shift concentrates most visibly in San Francisco and New York metropolitan corridors, where ingredient provenance commands menu pricing power.
Romanesco Broccoli Market Segmentation
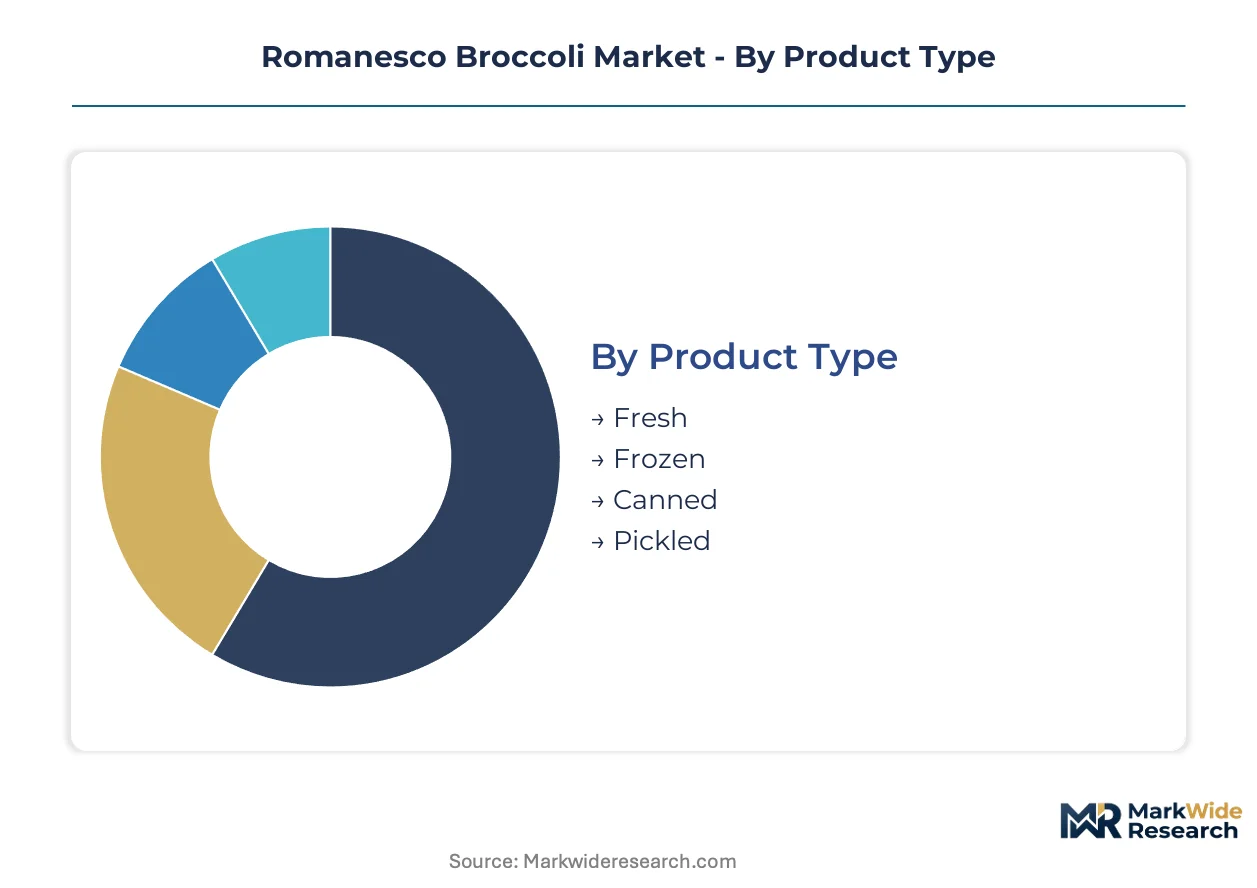
Romanesco broccoli's fractal geometry and perishability create distinct value capture patterns across product formats. Segmentation reveals where premium positioning commands margin versus where volume throughput drives profitability.
Product Type:
Volume concentration favors raw formats while processing investments reshape seasonality constraints.
- Fresh:Harvested at six to eight inches diameter before floret separation, fresh Romanesco commands premium positioning through visual novelty. High-end culinary establishments in Italy's Lazio region and California's Salinas Valley drive procurement, with chefs specifying logarithmic spiral tightness as a quality metric.
- Frozen:Individual quick freezing technology preserves cellular structure and chartreuse coloration, enabling institutional kitchen specification without seasonal supply gaps. IQF adoption is climbing fastest among foodservice distributors seeking year-round menu consistency.
- Canned:Thermal processing degrades the signature fractal structure, limiting application to ingredient formulations where geometry is irrelevant. Commercial buyers specify canned formats for soup and sauce manufacturing.
- Pickled:Brine preservation extends shelf life dramatically while acidification softens florets into condiment-appropriate texture. Artisan producers in Mediterranean markets drive niche demand.
Mature deployment sits with Fresh. Newer deployment is concentrated in Frozen.
Distribution Channel:
Channel selection determines margin retention versus volume throughput tradeoffs.
- Direct:Farm-to-chef platforms bypass distributor markups through subscription-based harvest forecasting. San Francisco and New York metropolitan corridors show highest penetration of direct procurement.
- Retail:Branded clamshell packaging captures margin concentration through visual differentiation at point of sale. Premium grocers specify head diameter ranges and organic certification status.
- Wholesale:Traditional foodservice distributors handle volume leadership in urban corridors, though compressing margins force consolidation among handler networks.
- Online:Specialty produce marketplaces enable varietal pre-booking and traceability documentation required by EU organic retailers.
Established infrastructure dominates Wholesale. Margin expansion is shifting toward Direct.
End User:
User type dictates specification stringency and price elasticity variation.
- Restaurants:Fine-dining establishments pre-book specific harvest windows and head diameter ranges, replacing spot-market purchasing with forward-commitment arrangements. Menu pricing power in provenance-focused concepts sustains premium tolerance.
- Households:Retail consumers demonstrate willingness to pay for visual novelty but exhibit high price sensitivity versus standard brassicas. Clamshell packaging and recipe cards drive trial conversion.
- Food Processors:IQF specification dominates procurement for frozen meal and ingredient manufacturing, with texture preservation technology determining supplier selection.
- Institutions:School and hospital foodservice programs prioritize cost containment and shelf stability over geometric perfection, favoring frozen formats.
Price inelasticity concentrates in Restaurants. Volume scaling is expanding fastest in Institutions.
Packing Type:
Packaging configuration aligns with distribution radius and handling intensity requirements.
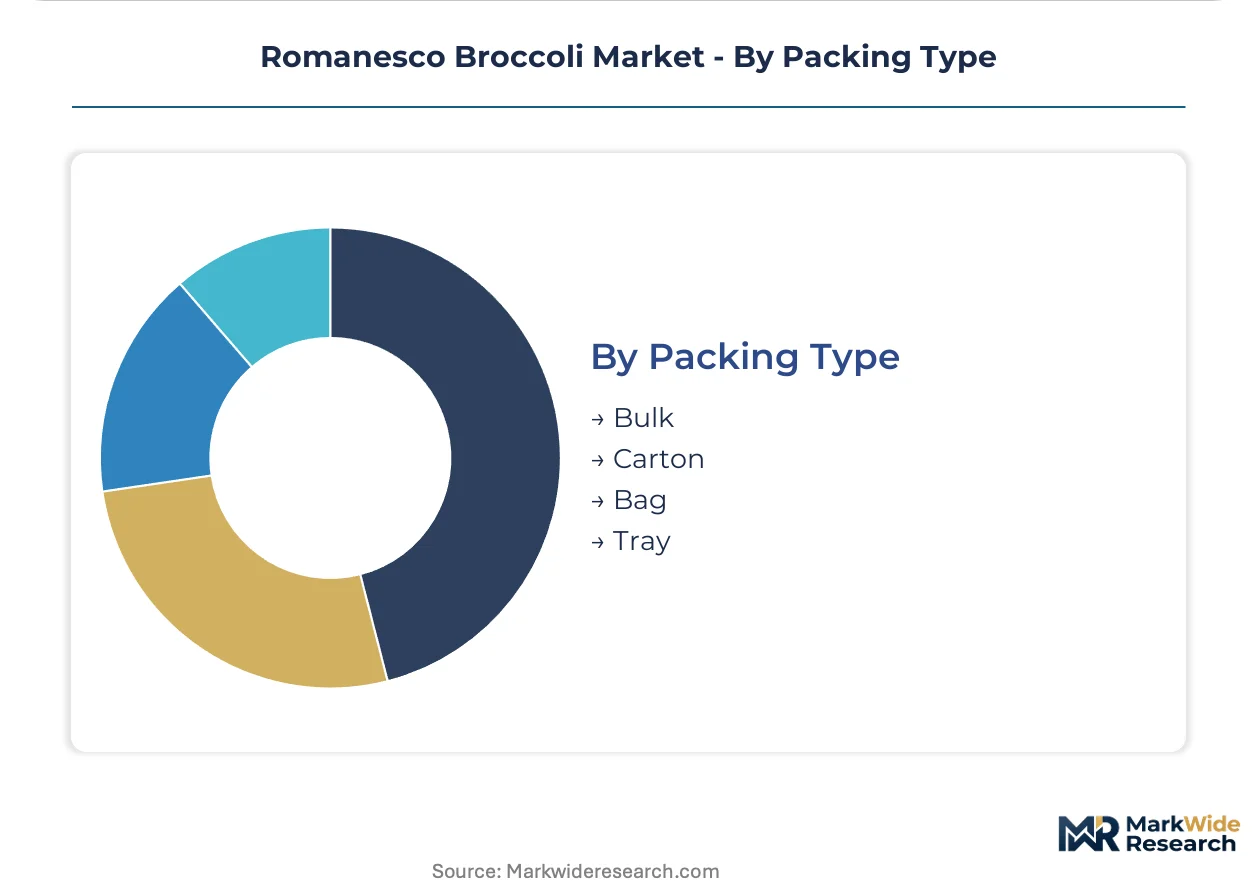
- Bulk:Loose-head shipment to processing facilities minimizes unit packaging cost for IQF and canning operations. Central Valley handlers dominate bulk consolidation.
- Carton:Corrugated containment protects fractal geometry through wholesale distribution channels, with wax coating extending cold-chain resilience.
- Bag:Modified atmosphere packaging extends retail shelf life to 7-10 days for conventional grocery placement.
- Tray:Molded pulp or plastic trays position individual heads for premium retail presentation, with clear film enabling visual quality assessment.
Cost-efficient formats dominate Bulk. Premium positioning is concentrating in Tray.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Salinas Valley Agricultural Enterprise Zone concentrates North American Romanesco broccoli cultivation through water-rights allocations and cool-season brassica infrastructure. Italy's Lazio region and the Netherlands' greenhouse clusters anchor European supply through distinct regulatory frameworks.
United States
California's Salinas Valley and Central Coast districts drive fresh produce procurement for specialty restaurants and premium retail chains. The state's Leafy Greens Marketing Agreement mandates field-level environmental monitoring and rapid traceback protocols for all signatory growers. Church Brothers Farms leverages Monterey County operations for year-round harvest scheduling and foodservice distributor anchoring.
Italy
Lazio region chefs and Rome metropolitan culinary establishments specify logarithmic spiral tightness as a quality metric for fresh Romanesco procurement. EU organic certification under EFSA standards requires full traceability documentation for pesticide residue limits and soil management protocols. D'Arrigo Brothers Company sustains multi-generational expertise through integrated cool-season brassica production networks.
Netherlands
Greenhouse horticulture clusters around Westland and Aalsmeer enable controlled-environment Romanesco production with reduced transportation spoilage. EU F-Gas standards for cold-chain refrigeration shape post-harvest handling infrastructure investments. Vertical farming installations in urban peripheries supply direct-to-kitchen programs for Amsterdam and Rotterdam fine-dining establishments.
France
Paris metropolitan and Lyon culinary corridors drive pre-booking arrangements for specific harvest windows and head diameter ranges. ANSM and national food safety protocols govern fresh produce traceability requirements for restaurant procurement. Provence-Alpes-Côte d'Azur specialty producers supply visual novelty positioning for premium grocery placement.
United Kingdom
London metropolitan specialty produce marketplaces bypass traditional distributor markups through subscription-based harvest forecasting. Food Standards Agency regulations align with EU organic equivalence agreements for import certification. Southeast England controlled-environment agriculture trials explore vertical farming viability for local production.
Romanesco Broccoli Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fresh produce handlers commanding premium positioning and seed suppliers anchoring genetic consistency. The supplier base stratifies between integrated farming operations with cold-chain infrastructure and specialized seed companies with varietal development programs. Three archetypes dominate: vertically integrated growers, specialty produce merchandisers, and open-pollinated seed stock developers. Competitive moves concentrate on direct-to-chef platform development and USDA organic certification transition.
Among California-based integrated growers, Church Brothers Farms and D'Arrigo Brothers Company exemplify the vertically consolidated archetype through Salinas Valley cultivation clustering and year-round supply reliability. Frieda's Inc. occupies the specialty merchandising tier, differentiating through branded clamshell packaging and direct retail partnerships with premium grocers. These three entities represent distinct positioning vectors within the value chain.
| Leading Market Players |
|---|
| Frieda's Inc. |
| Holmes Seed Company |
| Victory Seed Company |
| Church Brothers Farms |
| D'Arrigo Brothers Company |
| Seattle Seed Company |
| Old World Seed Company |
| The Nunes Company |
| Rainbow Seeds and Supply |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between USDA organic and conventional production tiers manifests in both pricing power and supply chain configuration, with compliant growers commanding premium positioning through California's Leafy Greens Marketing Agreement traceability infrastructure while conventional handlers face margin compression from nitrogen fertilizer cost volatility.
Pricing Analysis
Volume leadership versus margin capture splits sharply across distribution channels. Wholesale foodservice contracts operate on per-unit transactional pricing with compressed spreads, while direct-to-chef platforms and premium retail clamshells deploy value-based structures anchored to organic certification status and fractal geometry grading. Price differentiation rests on EU organic compliance and IQF technology adoption as dual drivers. Cost compression in conventional tiers intensifies because natural gas-linked fertilizer pricing outpaces contract pass-through mechanisms. Institutional buyers exhibit highest price sensitivity, whereas fine-dining establishments demonstrate lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with California's Salinas Valley water-rights allocations, where drought-driven restrictions threaten yield predictability across North American supply. Geographic supply concentration draws from the United States, Italy, and the Netherlands as primary production anchors. Raw material dependencies hinge on open-pollinated seed stock, nitrogen-based fertilizers, and cold-chain refrigeration equipment. Supply chain risk centers on single-source vulnerability from concentrated growing regions exposed to climate-driven water allocation volatility. Distribution runs through wholesale foodservice distributors for volume, with direct-to-chef platforms capturing margin expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, with California's Leafy Greens Marketing Agreement and EU organic certification standards erecting documentation barriers that favor incumbent players with established environmental monitoring infrastructure.
For Market Incumbents: Lock in supply reliability through controlled environment agriculture investments in urban peripheries, defending against water allocation volatility that threatens Salinas Valley yield consistency. Deepen backward integration into seed stock development to reduce phenotypic variation in spiral tightness, capturing brand standardization premiums. Prioritize IQF capacity expansion for institutional kitchen contracts that demand year-round menu consistency. For New Entrants and Emerging Players: Specialty produce marketplaces offer the most penetrable channel wedge, bypassing traditional distributor markups through subscription-based harvest forecasting and varietal pre-booking systems. Target vertical farming installations in drought-exposed regions where local production commands premium positioning. Exploit USDA organic transition incentives under the Environmental Quality Incentives Program to subsidize certification cost barriers. For Investors and Strategic Acquirers: Re-rating potential sits with integrated growers possessing cold-chain infrastructure and established EU organic certification, given traceability documentation requirements that stratify the supplier base. Long-term viability favors entities with captive water rights or controlled environment capabilities that de-risk climate exposure. Monitor chef-driven varietal specification trends as an inflection indicator for procurement pattern fragmentation away from commodity contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Environment Agriculture Expansion | Urban periphery installations reduce transportation spoilage and enable direct-to-kitchen premium positioning. |
| USDA Organic Certification Transition | Environmental Quality Incentives Program subsidies lower barrier-to-entry moats for compliant acreage conversion. |
| IQF Technology Deployment | Individual quick freezing preserves cellular structure for institutional kitchen year-round procurement. |
| Direct-to-Chef Platform Development | Subscription-based harvest forecasting captures margin through bypassing traditional foodservice distributor markups. |
| Spectral Sorting System Adoption | Near-infrared imaging enables real-time grading that separates export-grade specimens from domestic retail lots. |
Research Methodology
Independent corroboration across grower operations executives, foodservice procurement directors, and specialty produce merchandisers underwrites the qualitative findings. Primary interviews with cold-chain logistics specialists, seed company agronomists, and fine-dining executive chefs combined with secondary validation from USDA agricultural databases, EU organic certification registries, and California agricultural water rights filings. Bottom-up acreage and yield estimates triangulate against top-down consumption pattern analysis.
Rate-of-change decomposition across the projection horizon separates volume growth drivers from value capture mechanisms. Segmentation dimensions modeled include product format, distribution channel, end-user type, and certification status. CAGRs derive from weighted scenario analysis incorporating water allocation policy trajectories and chef procurement behavioral shifts. Industry-specific forecast inputs incorporate nitrogen fertilizer pricing correlation to natural gas markets and IQF technology adoption curves.
Caveats apply where drought severity, EU regulatory stringency revisions, or alternative protein substitution trends could materially shift the outlook. Forecasts reflect assumptions about sustained premium willingness-to-pay for visual novelty and continued water rights stability in Central Valley production zones. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Global Garcinia Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Middle East and Africa Shiitake Mushroom Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Apple Concentrate Market