
 Dragon Fruit Market | 2026-2036
Dragon Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Dragon Fruit Market Analysis
GlobalGAP certification for fresh produce exporters is collapsing the supplier base into operations capable of meeting traceability and residue-testing protocols. Nam Viet Foods & Beverage Co., Ltd. leverages integrated orchards and processing facilities to control supply consistency for beverage clients. Pitaya Plus differentiates through frozen puree specialization targeting North American smoothie chains. Great Sun Pitaya Farm Sdn. Bhd. anchors Malaysian supply with controlled-environment cultivation reducing seasonal volatility.
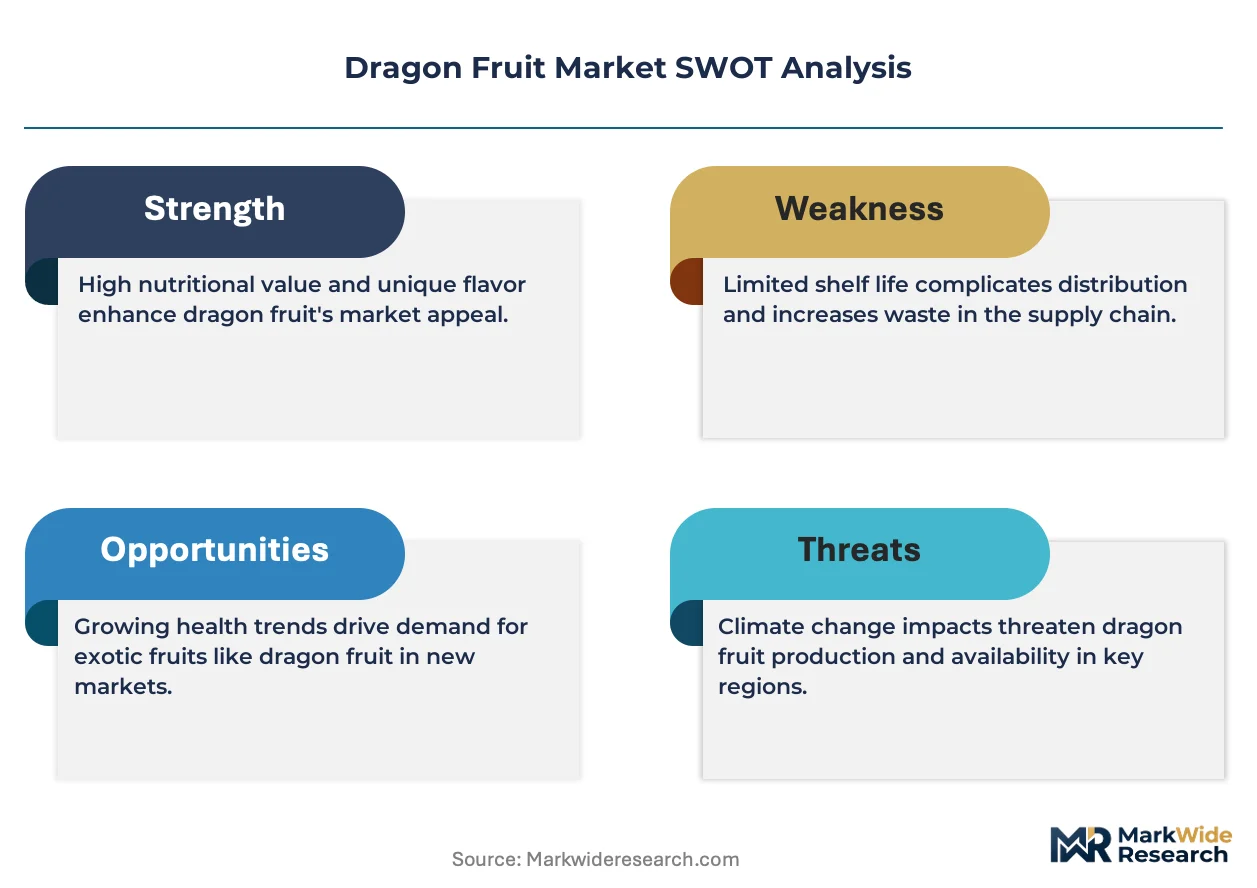
Dragon fruit, botanically Hylocereus species, delivers pulp with 8-10% soluble solids, notable betacyanin pigment concentration in red varieties, and pericarp-to-flesh ratios governing processing yield. The fruit serves commercial applications requiring natural colorants, fiber enrichment, and clean-label positioning in formulated foods. Red dragon fruit commands premium positioning in beverage and nutraceutical channels where pigment stability and antioxidant claims justify higher input costs. Modified atmosphere packaging extends cold-chain viability for fresh whole fruit, while bulk packaging dominates industrial ingredient flows to processors. White dragon fruit retains volume leadership in Asian fresh markets where milder flavor profiles align with traditional consumption patterns.
FDA enforcement of Foreign Supplier Verification Programs shapes import eligibility for US-bound processed dragon fruit ingredients. Vietnam's Plant Protection Department and the EU's EFSA residue monitoring protocols jointly determine which growers access premium export segments. Stakeholders must monitor evolving maximum residue limits and certification reciprocity agreements as regulatory divergence between destination markets intensifies compliance complexity.
Market Dynamics
Dragon fruit supply chains face acute compression as GlobalGAP certification requirements eliminate marginal growers, consolidating procurement power among vertically integrated orchard-processors capable of end-to-end traceability documentation.
Growth Catalysts
- Functional Beverage Formulation:Antioxidant-forward product lines from smoothie chains and wellness brands pull industrial puree volumes, with betacyanin pigment stability driving specification premiums in beverage manufacturing.
- EU EFSA Residue Protocols:Harmonized maximum residue limits across member states create predictable compliance pathways for Vietnamese and Malaysian exporters, reducing regulatory arbitrage friction in premium channel access.
- Controlled-Environment Cultivation:Malaysian greenhouse operations and Vietnamese net-house systems compress seasonal volatility, enabling year-round contract fulfillment for processor clients with fixed ingredient schedules.
Market Restraints
- Input Cost Volatility:Labor-intensive hand-pollination requirements and rising agricultural input costs squeeze margin structures for smallholder-dependent supply networks in Vietnam's Mekong Delta.
- Supply Concentration Risk:Vietnam controls approximately two-thirds of global export volume, creating single-origin vulnerability to climate events, phytosanitary disruptions, or bilateral trade friction.
- Pigment Instability:Betacyanin degradation during thermal processing limits application range, constraining high-heat food manufacturing adoption despite antioxidant marketing claims.
Strategic Opportunities
- Indian Market Penetration:FSSAI standardization of exotic fruit import protocols and urban smoothie chain expansion create first-mover positioning for certified Vietnamese exporters in an underdeveloped channel.
- Cosmeceutical Applications:Topical antioxidant and natural colorant formulations in skincare represent adjacent demand verticals with formulation flexibility that bypasses thermal stability constraints.
- USDA Organic Premium Tier:Tightened National Organic Program enforcement creates certified supply scarcity, rewarding growers with multi-year conversion investments through price premiums in North American natural retail.
Industry Challenges
- Phytosanitary Compliance Timelines:FDA Foreign Supplier Verification Program documentation requirements and Vietnam Plant Protection Department inspection backlogs create 90-120 day certification delays that disrupt just-in-time processor procurement.
- Cold-Chain Infrastructure Gaps:Modified atmosphere packaging efficacy degradates through multi-modal handoffs, requiring processor-side quality recertification that inflates working capital cycles.
- Skilled Pollination Labor Scarcity:Nocturnal flowering patterns demand specialized agricultural workforce availability that conflicts with competing crop harvest schedules in peak growing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dragon Fruit Market |
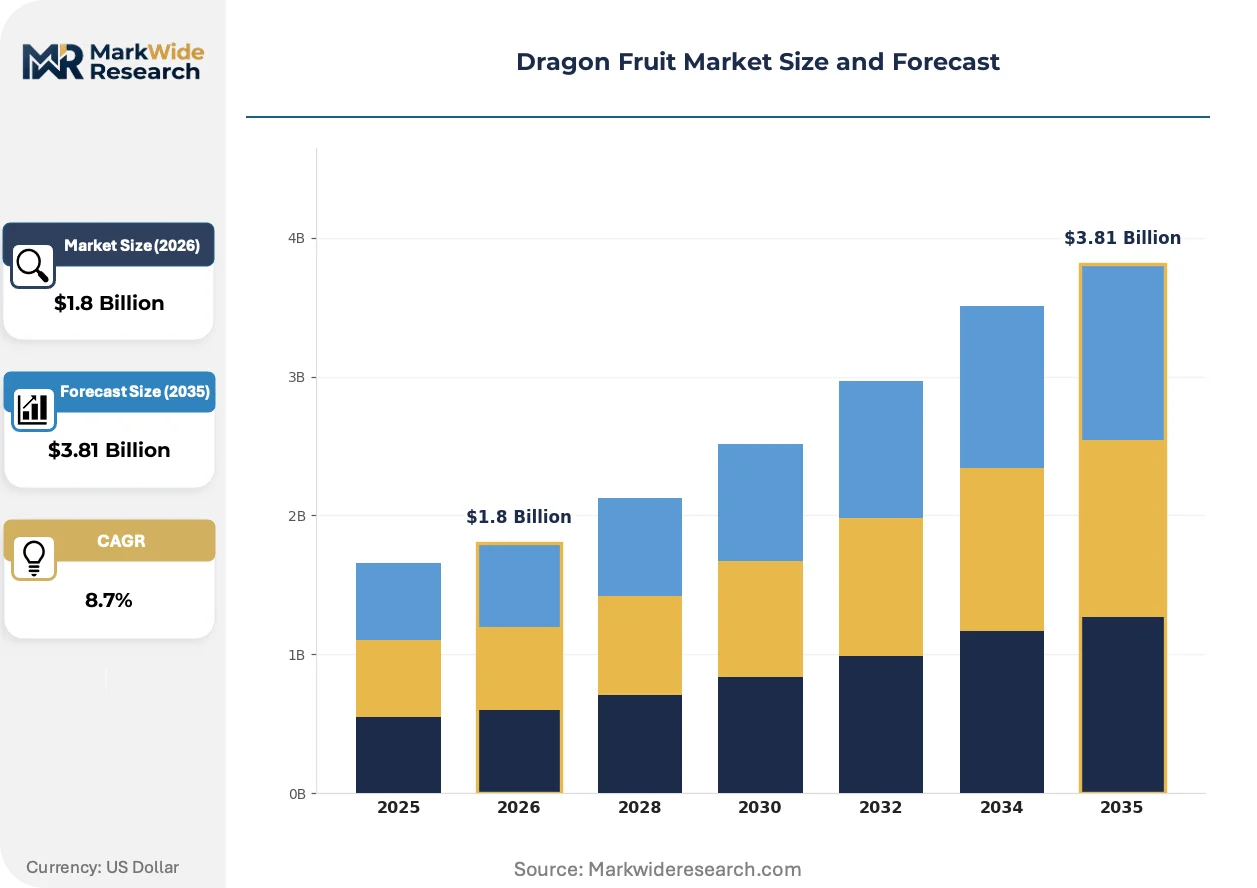
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Dragon Fruit, Red Dragon Fruit, Yellow Dragon Fruit, Black Dragon Fruit Distribution Channel: Supermarkets, Online Retail, Wholesale Markets, Exporters End User: Food Industry, Beverage Industry, Household Consumers, Health Stores Packaging Type: Bulk Packaging, Retail Packaging, Recyclable Packaging, Modified Atmosphere Packaging |
| Companies Covered | Bai Brands, Welch Foods Inc., Nam Viet Foods & Beverage Co., Ltd., Hybrid Herbs, Unicorn Superfoods, Biourah Herbal, Pitaya Plus, Wilderness Poets, Great Sun Pitaya Farm Sdn. Bhd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dragon Fruit Market Emerging Trajectories
Processing technology advances and regulatory harmonization pressures are compressing traditional supply chain tiers, while buyer procurement sophistication reshapes qualification criteria beyond commodity pricing toward integrated certification packages.
High-pressure processing (HPP) technology for fruit puree preservation is miniaturizing from industrial-scale batch systems to containerized modular units deployable at orchard-adjacent facilities. Mid-scale Vietnamese processors are adopting these 50-100 liter throughput systems to bypass centralized pasteurization bottlenecks. This distributed processing architecture is compressing cold-chain distances and enabling small-batch custom formulation for boutique beverage clients.
REACH regulation amendments on food contact material migration limits are forcing European-bound exporters to replace conventional wax coatings and modified atmosphere film substrates with compliant alternatives. Industrial consequence includes accelerated validation timelines for packaging suppliers serving dragon fruit cold-chain logistics. Fresh whole fruit exporters to Germany, Netherlands, and France are absorbing 8-12 month certification cycles for new barrier film formulations.
Direct contracting between smoothie chain procurement teams and certified orchard-processors is displacing traditional spot-market purchasing through consolidated import distributors. This disintermediation concentrates volume commitments among GlobalGAP-certified suppliers capable of lot-level traceability documentation. North American beverage chain procurement offices are mandating quarterly third-party audit reporting as a contractual condition, shifting supplier relationship management from trading margins to compliance infrastructure investment.
Dragon Fruit Market Segmentation
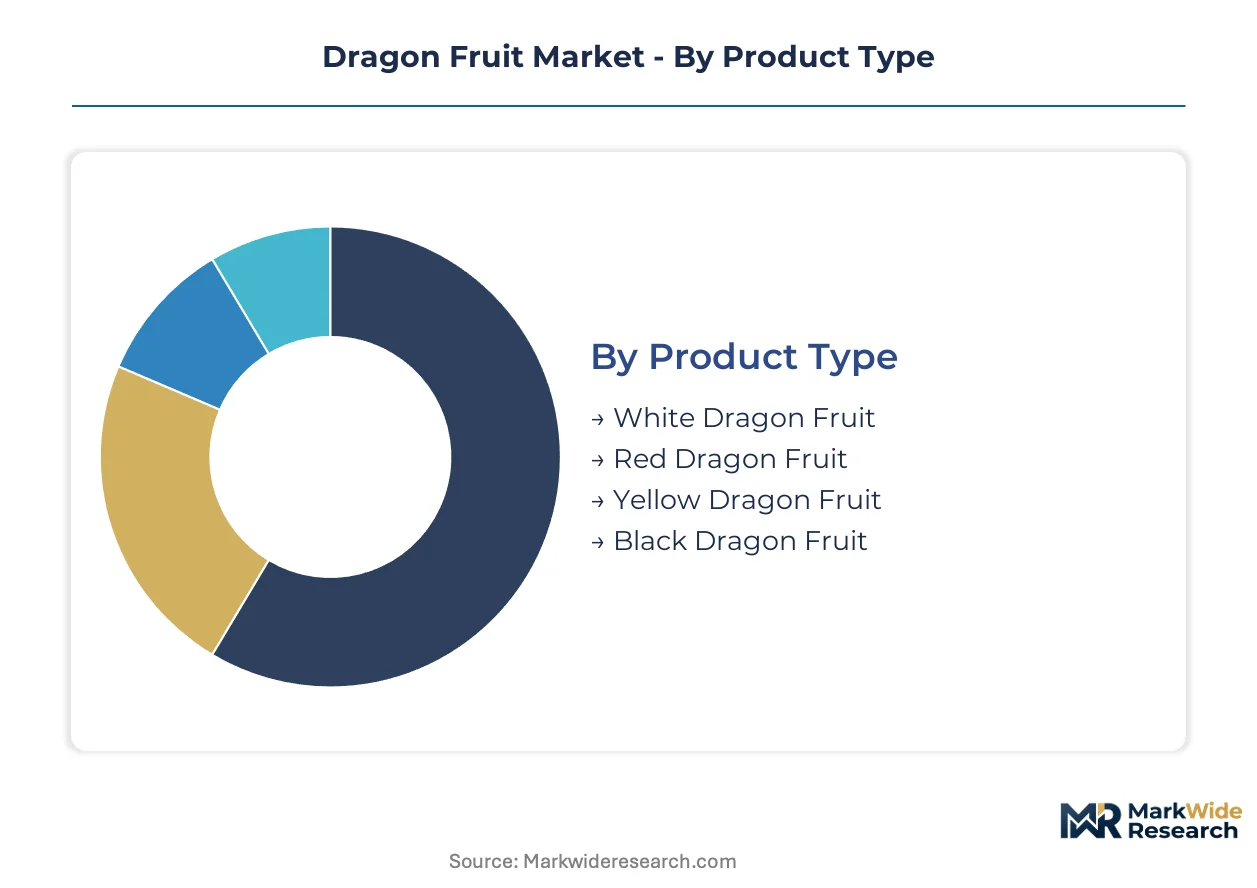
Dragon fruit segmentation reflects divergent supply chain architectures between fresh export channels and domestic processing markets. Category boundaries increasingly blur as beverage manufacturers source specific pigment grades while retailers demand shelf-life extensions through modified atmosphere technologies.
Product Type:
White varieties dominate Mekong Delta cultivation for Asian fresh consumption, while red varieties concentrate in Malaysian greenhouse operations targeting North American pigment extraction contracts.
- White Dragon Fruit:Mild flavor profile with lower betacyanin content suits traditional Asian fresh markets where pericarp appearance drives selection. Vietnam's Plant Protection Department certifies the majority of export volumes to China and Southeast Asian neighbors under bilateral phytosanitary protocols.
- Red Dragon Fruit:Concentrated betacyanin pigments deliver antioxidant specifications required by functional beverage formulators in the United States and Germany. Pigment stability limitations under thermal processing constrain application range despite premium pricing in nutraceutical channels.
- Yellow Dragon Fruit:Distinctive visual differentiation commands niche positioning in European specialty retail and Japanese gift fruit segments.
- Black Dragon Fruit:Emerging varietal with limited commercial scale, primarily cultivated in Ecuador and Colombia for experimental cosmetic ingredient applications.
White dragon fruit holds the largest share; momentum sits with red varieties as beverage manufacturers reformulate around natural colorant mandates.
Distribution Channel:
Channel selection determines certification burden intensity, with exporter and supermarket tiers demanding GlobalGAP documentation that eliminates two-thirds of Mekong Delta smallholders.
- Supermarkets:Modified atmosphere packaging requirements and cold-chain integrity specifications favor Vietnamese suppliers with integrated orchard-processing facilities capable of lot-level traceability documentation.
- Online Retail:Direct-to-consumer fulfillment compresses margin structures through last-mile refrigeration costs, limiting viable supply to domestic cultivation zones in Malaysia and Thailand.
- Wholesale Markets:Spot-price trading dominates Asian fresh consumption with minimal certification requirements, preserving smallholder access despite quality inconsistency.
- Exporters:FDA Foreign Supplier Verification Program and EFSA residue protocols create 90-120 day documentation timelines that consolidate procurement among vertically integrated orchard-processors.
Wholesale markets capture the highest volume throughput; steepest expansion trajectory belongs to exporter channels as direct contracting displaces distributor intermediation.
End User:
User segmentation tracks pigment stability requirements, with beverage applications demanding fresh-frozen puree while food manufacturing tolerates thermally processed ingredients.
- Food Industry:Bakery and confectionery applications utilize dragon fruit powder for natural colorant replacement of synthetic alternatives, with Malaysian processors supplying spray-dried formats to European manufacturers navigating REACH food contact compliance.
- Beverage Industry:High-pressure processing adoption enables cold-pressed smoothie formulations preserving betacyanin bioactivity, driving specification premiums from US wellness chains and German functional drink startups.
- Household Consumers:Fresh whole fruit purchase concentrates in Asian urban centers with established nocturnal market distribution infrastructure.
- Health Stores:Freeze-dried chip and powder formats align with clean-label positioning in North American natural retail channels requiring USDA Organic certification.
Food industry absorption leads by volume; beverage industry climbs the fastest as antioxidant marketing claims proliferate across premium product lines.
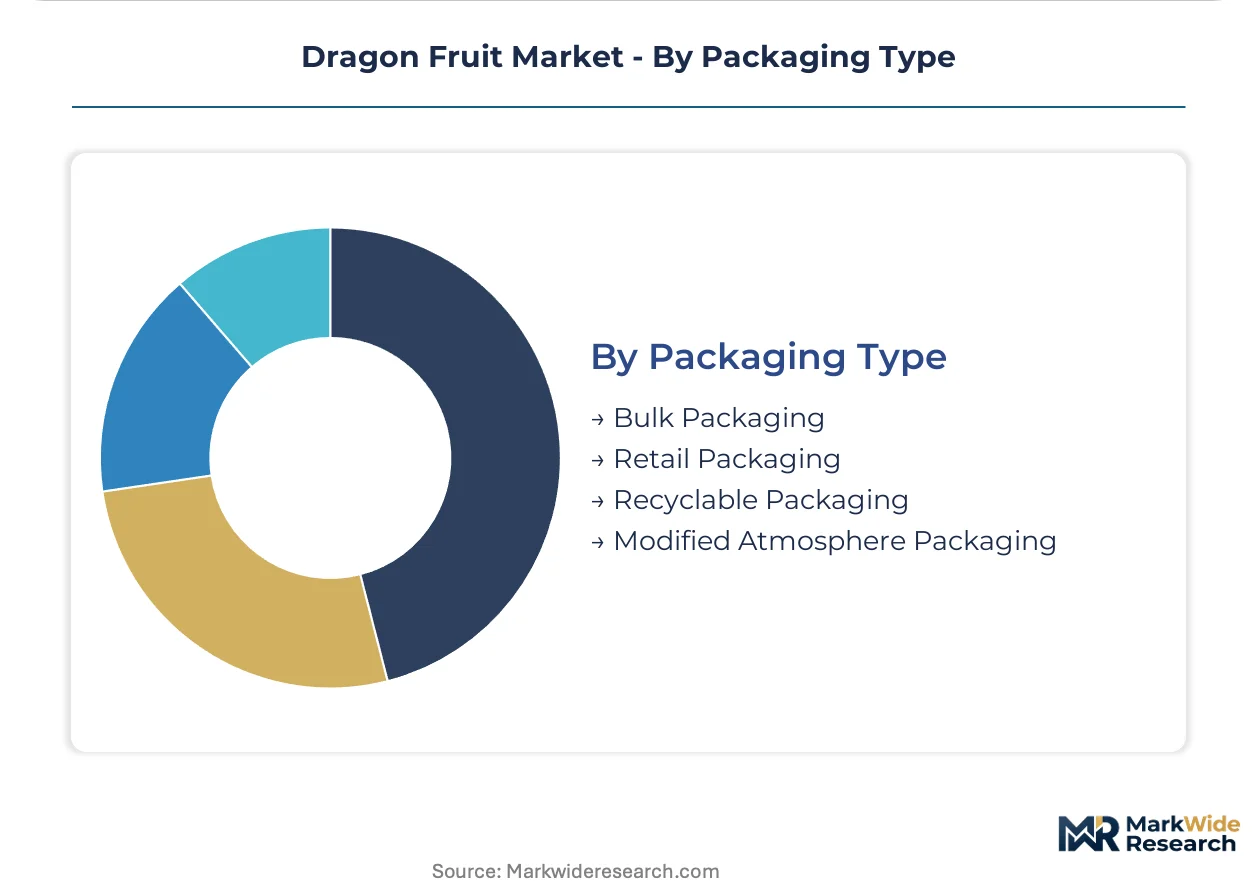
Packaging Type:
Packaging selection governs shelf-life extension capability and regulatory compliance burden across destination markets with divergent food contact material standards.
- Bulk Packaging:Industrial ingredient flows to processors utilize aseptic bag-in-drum configurations with 12-18 month frozen stability, dominating Vietnamese export volumes to US and German beverage manufacturers.
- Retail Packaging:Clamshell and net bag formats for fresh whole fruit require humidity control films validated under EFSA migration limits for European-bound shipments.
- Recyclable Packaging:Mono-material film development accelerates under EU Green Deal packaging waste directives, with 8-12 month validation cycles for new barrier substrates.
- Modified Atmosphere Packaging:Low-oxygen film systems extend cold-chain viability for premium supermarket segments, with efficacy degradation through multi-modal handoffs requiring processor-side quality recertification.
Bulk packaging commands the greatest tonnage; recyclable packaging gains share fastest as regulatory pressure intensifies on single-use plastics in European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU EFSA residue protocols and USDA National Organic Program standards are reshaping export eligibility criteria, concentrating supply access among certified orchard-processors in Vietnam, Malaysia, and emerging cultivation zones.
Vietnam
Functional beverage procurement from US wellness chains and German smoothie manufacturers pulls industrial puree volumes from Mekong Delta processing clusters. Vietnam's Plant Protection Department enforces phytosanitary documentation aligned with FDA Foreign Supplier Verification Program timelines. Long An and Tien Giang provinces host vertically integrated orchard-processors capable of GlobalGAP-certified lot-level traceability for direct contracting with North American buyers.
Malaysia
Controlled-environment greenhouse operations supply red dragon fruit pigment extraction contracts to European natural colorant manufacturers. Malaysian Department of Agriculture certification under ASEAN Good Agricultural Practice protocols enables preferential channel access within regional trade frameworks. Johor and Pahang cultivation zones leverage net-house systems to compress seasonal volatility for year-round contract fulfillment.
United States
Smoothie chain procurement offices mandate quarterly third-party audit reporting as a contractual condition for puree suppliers. FDA enforcement of Foreign Supplier Verification Program documentation creates 90-120 day certification delays that favor established Vietnamese exporters with compliance infrastructure. California and Florida domestic cultivation remains limited to specialty retail and farmers market channels.
Germany
REACH regulation amendments on food contact material migration limits force validation of modified atmosphere packaging substrates for fresh whole fruit imports. EFSA residue monitoring protocols determine Vietnamese grower eligibility for premium supermarket segments. Hamburg and Rotterdam logistics clusters handle bulk refrigerated container flows for redistribution across German retail networks.
India
FSSAI standardization of exotic fruit import protocols and urban smoothie chain expansion create first-mover positioning for certified Vietnamese exporters. DGFT licensing requirements for horticultural imports concentrate procurement through Mumbai and Chennai port-based cold-chain distributors. Bangalore and Delhi-NCR retail networks represent the primary demand concentration for premium fresh fruit positioning.
Dragon Fruit Market Vendor Landscape
Listed beverage conglomerates compete with private orchard-processors across certification infrastructure investment, creating a tiered structure where GlobalGAP documentation capability separates contract-eligible suppliers from spot-market participants. Three archetypes dominate: vertically integrated Vietnamese orchard-processors controlling end-to-end traceability, Malaysian greenhouse operators specializing in pigment-grade red varieties, and North American puree specialists serving smoothie chain direct procurement. Competitive moves concentrate on backward integration into captive cultivation and strategic partnerships with packaging technology providers to address REACH-compliant barrier film requirements.
Within the integrated processor tier, Nam Viet Foods & Beverage Co., Ltd. exemplifies the Vietnamese archetype of orchard-adjacent processing facilities controlling supply consistency. Pitaya Plus occupies a position among North American specialists targeting frozen puree formats for beverage manufacturing clients. Great Sun Pitaya Farm Sdn. Bhd. represents the Malaysian controlled-environment cultivation model reducing seasonal supply volatility for contract-based procurement relationships.
| Leading Market Players |
|---|
| Bai Brands |
| Welch Foods Inc. |
| Nam Viet Foods & Beverage Co., Ltd. |
| Hybrid Herbs |
| Unicorn Superfoods |
| Biourah Herbal |
| Pitaya Plus |
| Wilderness Poets |
| Great Sun Pitaya Farm Sdn. Bhd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Vietnamese orchard-processors and North American beverage chains lock in supply access while providing price visibility across volatile growing seasons. These agreements tie volume commitments to GlobalGAP certification status, creating tiered procurement relationships that insulate certified suppliers from spot-market price swings.
Pricing Analysis
Certification level creates the primary spread between GlobalGAP-certified puree and uncertified spot-market fruit. Three-tier pricing structure across premium, standard, and economy levels reflects pigment concentration grades and organic program compliance. Pricing pressure stems from rising agricultural input costs and hand-pollination labor scarcity squeezing Mekong Delta smallholders. Food manufacturers exhibit highest price sensitivity due to formulation flexibility, while beverage chains absorb premiums for antioxidant-forward positioning.
Supply Chain Analysis
Container availability constraints on the Ho Chi Minh City to Los Angeles trade lane inflate working capital cycles for Vietnamese exporters. Supply concentrates in Vietnam, Malaysia, and emerging Ecuadorian cultivation zones. The chain draws from specialized pollination labor, modified atmosphere packaging films, and cold-chain refrigeration equipment. Single-origin vulnerability to Vietnamese climate events and phytosanitary disruptions constitutes the dominant structural risk. Distribution runs through vertically integrated orchard-processors capable of lot-level traceability documentation for direct contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates white-space opportunities as direct procurement displaces traditional distributor intermediation. Smoothie chain procurement sophistication splits demand between compliant and non-compliant supply tiers.
For Market Incumbents: Shield market position through captive cultivation expansion in Vietnam's Long An province and accelerated USDA Organic program conversion. Rising input cost volatility and emerging Malaysian greenhouse competitors threaten margin structures. Certification infrastructure investment and backward integration into controlled-environment pollination facilities provide defensive leverage. For New Entrants and Emerging Players: Anchor in Indian FSSAI-compliant import channels where certified Vietnamese supply remains underdeveloped relative to urban smoothie chain expansion. Bangalore and Delhi-NCR retail networks offer penetrable demand concentration. Direct contracting with port-based cold-chain distributors bypasses established exporter relationships. For Investors and Strategic Acquirers: Orchard-adjacent processors with integrated HPP capabilities represent the most defensible acquisition archetype for long-term positioning. Five-to-ten year viability hinges on pigment stability technology breakthroughs expanding application range. Monitor EFSA-REACH packaging compliance timelines as inflection indicator for European channel access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Vietnamese processors secure pollination labor control and compress cold-chain distances to HPP facilities. |
| USDA Organic Program Conversion | Certified supply scarcity under tightened National Organic Program enforcement commands North American price premiums. |
| REACH-Compliant Packaging Validation | European-bound exporters absorb 8-12 month barrier film certification cycles to maintain German supermarket access. |
| Direct Procurement Relationship Development | Smoothie chain procurement offices mandate quarterly third-party audit reporting as contractual condition. |
| Cosmeceutical Application Expansion | Topical antioxidant formulations bypass thermal stability constraints limiting food manufacturing adoption. |
Methodological Framework
The analysis maps dragon fruit cultivation zones, processing technology tiers, and certification compliance pathways, each validated through procurement officers at beverage manufacturers, agricultural extension specialists, and cold-chain logistics providers. Primary interviews with smoothie chain sourcing executives, Vietnamese Plant Protection Department officials, and Malaysian Department of Agriculture certifiers combined with secondary validation against FDA Foreign Supplier Verification Program documentation requirements, EU EFSA residue monitoring protocols, and USDA National Organic Program standards. Bottom-up volume modeling from orchard-level cultivation data and top-down demand estimation from end-use industry consumption patterns underwent cross-triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated product type, distribution channel, end-user industry, and packaging format dimensions. CAGRs derived from historical growth trajectory analysis and forward-looking demand elasticity assessment for functional beverage and natural colorant applications.
Material uncertainties — regulatory divergence between FDA and EFSA protocols, climate volatility in Mekong Delta production zones, and pigment stability technology advancement timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification reciprocity agreements and cold-chain infrastructure development trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Mango Puree Market
Fruits and Vegetables
Fresh Peaches Market