
 Canned Vegetables Market | 2026-2036
Canned Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Vegetables Market Analysis
Asset-light contract manufacturing and third-party co-packing arrangements are reshaping competitive entry in canned vegetables, allowing regional brands to scale without capital-intensive retort facilities. Conagra Brands leverages its captive canning infrastructure across multiple US states to sustain cost advantages in private-label and branded production. Seneca Foods Corporation anchors its position through backward integration into agricultural sourcing, controlling acreage contracts for sweet corn and green beans. Del Monte Foods Inc. differentiates via retail channel dominance in Latin American and Asia-Pacific markets where its brand recognition commands shelf placement premiums.
Canned vegetables comprise thermally processed plant products sealed in hermetic containers, typically undergoing steam or water-bath retort sterilization at temperatures exceeding 121 degrees Celsius to achieve commercial sterility and shelf stability exceeding two years. The category serves retail households, institutional foodservice, and downstream food manufacturing requiring consistent year-round ingredient supply irrespective of harvest seasonality. Beans and peas occupy the core volume positions within product type segmentation, reflecting their structural role in prepared meals and side dishes across multiple cuisines. Aluminum can packaging maintains cost leadership for high-velocity SKUs, while glass jar formats command premium positioning in European and North American organic and specialty lines where visual product inspection influences purchase decisions.
USDA grading standards and FDA low-acid canned food regulations govern thermal processing parameters and container integrity testing, creating compliance barriers that favor established operators with validated process authorities. EU F-Gas Regulation and national packaging waste directives in Germany and France are accelerating transitions toward recyclable and reduced-metal packaging formats, influencing R&D allocation across major producers. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme expansions, as these mechanisms will determine cost structures and format viability across European and North American markets.
Market Dynamics
Cold-chain infrastructure gaps across tropical and subtropical zones are preserving ambient-stable formats as the dominant vegetable preservation method, while BPA-free lining mandates in North America and Europe force simultaneous retooling of can manufacturing specifications.
Growth Catalysts
- India cold-chain deficit:Perishable vegetable spoilage rates exceeding 30% drive food processing buyers toward shelf-stable inputs that eliminate refrigeration dependency throughout distribution.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants raises operating costs for frozen vegetable storage, tilting procurement economics toward canned alternatives in institutional foodservice.
- Retort pouch technology:Flexible packaging sterilization advances enable lighter-weight formats that reduce freight costs for export-oriented processors in Southeast Asia.
Market Restraints
- Steel and aluminum input volatility:Tinplate and aluminum coil prices tied to energy-intensive smelting expose can manufacturers to electricity cost swings in China and Russia.
- Single-source agricultural concentration:Sweet corn processing contracts cluster in the US Midwest and China's Heilongjiang corridor, creating harvest failure exposure.
- Glass jar premium ceiling:Visual inspection demand in organic segments hits price elasticity limits where private-label glass SKUs undercut branded equivalents.
Strategic Opportunities
- Indonesia archipelago logistics:Island-to-island shipping costs and intermittent power favor ambient-stable formats in retail and humanitarian procurement channels.
- USDA organic certification expansion:Premium positioning through certified organic lines captures price multiples in European and North American natural food channels.
- E-commerce direct-to-pantry models:Subscription-based canned vegetable bundles bypass traditional retail slotting fees and build recurring revenue streams.
Industry Challenges
- Retort process authority scarcity:FDA low-acid canned food regulations require validated thermal processing specialists, constraining new facility commissioning timelines.
- Legacy can line reconfiguration:BPA-free epoxy and polyester lining conversions demand capital-intensive welding and coating equipment upgrades at existing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Vegetables Market |
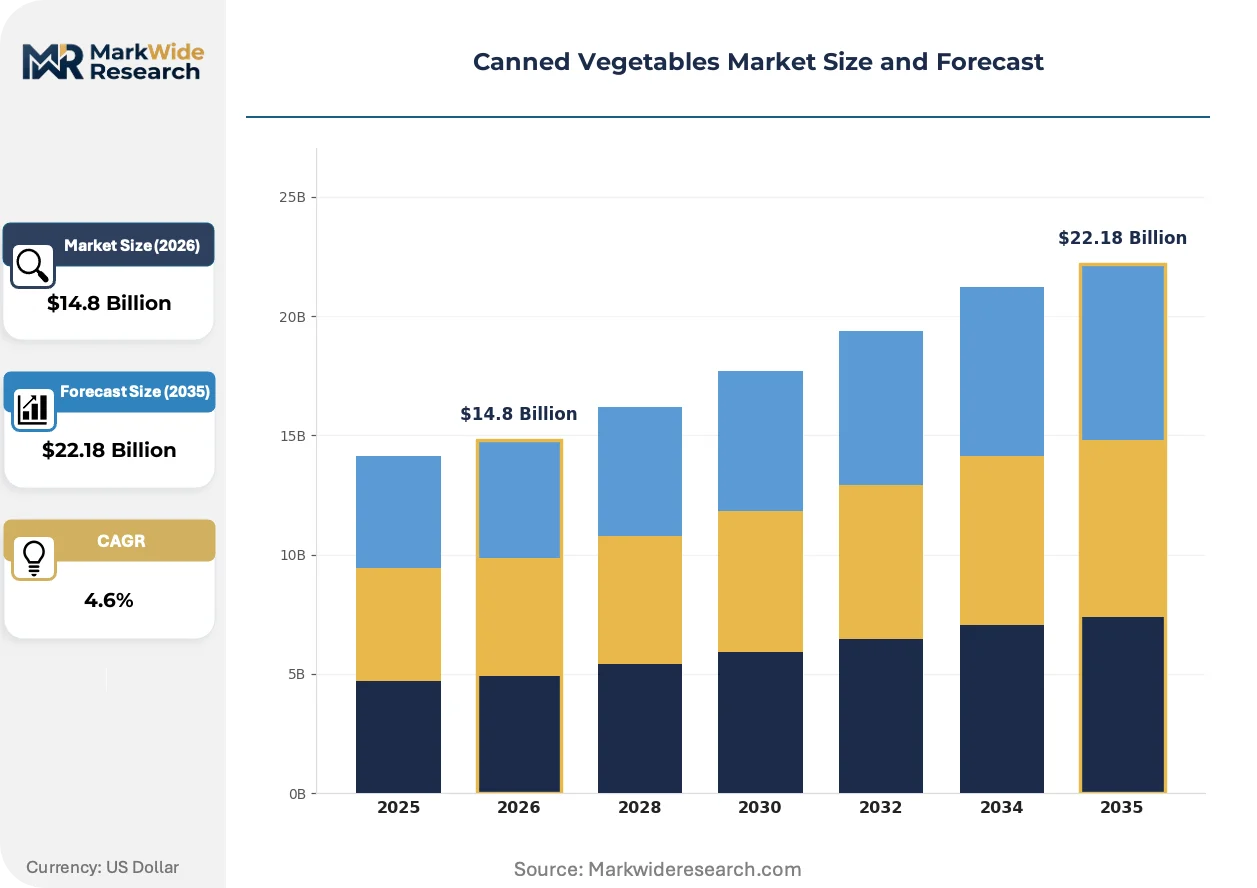
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beans, Corn, Peas, Carrots Packaging Type: Aluminum Can, Glass Jar, Tetra Pak, Plastic Container End User: Households, Restaurants, Food Processing Industry, Cafeterias Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Conagra Brands, Seneca Foods Corporation, Del Monte Foods Inc., Campbell Soup Company, Bonduelle SA, Nestlé S.A., Dole plc, TreeHouse Foods Inc., The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Vegetables Market Emerging Trajectories
Processing technology and packaging material science are converging to reduce thermal degradation of vegetable nutrients while meeting compressed shelf-life and sustainability requirements from retail and institutional buyers.
High-pressure processing (HPP) sterilization for vegetable purees and ready-to-eat components is rendering obsolete conventional water-bath retort methods for premium chilled and ambient product lines. European organic brands and North American meal-kit suppliers are adopting HPP at pilot scale. The technology is rendering obsolete the trade-off between extended shelf stability and vitamin retention that has constrained canned vegetable nutrition claims.
EU packaging waste directives in Germany and France are mandating minimum recycled content thresholds and extended producer responsibility fees based on material recyclability. Metal can producers face competitive pressure against glass and fiber-based alternatives in private-label negotiations. German retailers are responding by consolidating shelf placement behind mono-material aluminum formats with established post-consumer collection infrastructure.
Foodservice procurement consolidation through group purchasing organizations is compressing supplier qualification cycles and unbundling technical support from core product pricing. Institutional buyers in US K-12 and healthcare channels now demand annual cost-down commitments with volume guarantees. This concentration is most visible in the US Southeast, where regional healthcare systems have merged purchasing functions and reduced approved vendor lists by half.
Canned Vegetables Market Segmentation
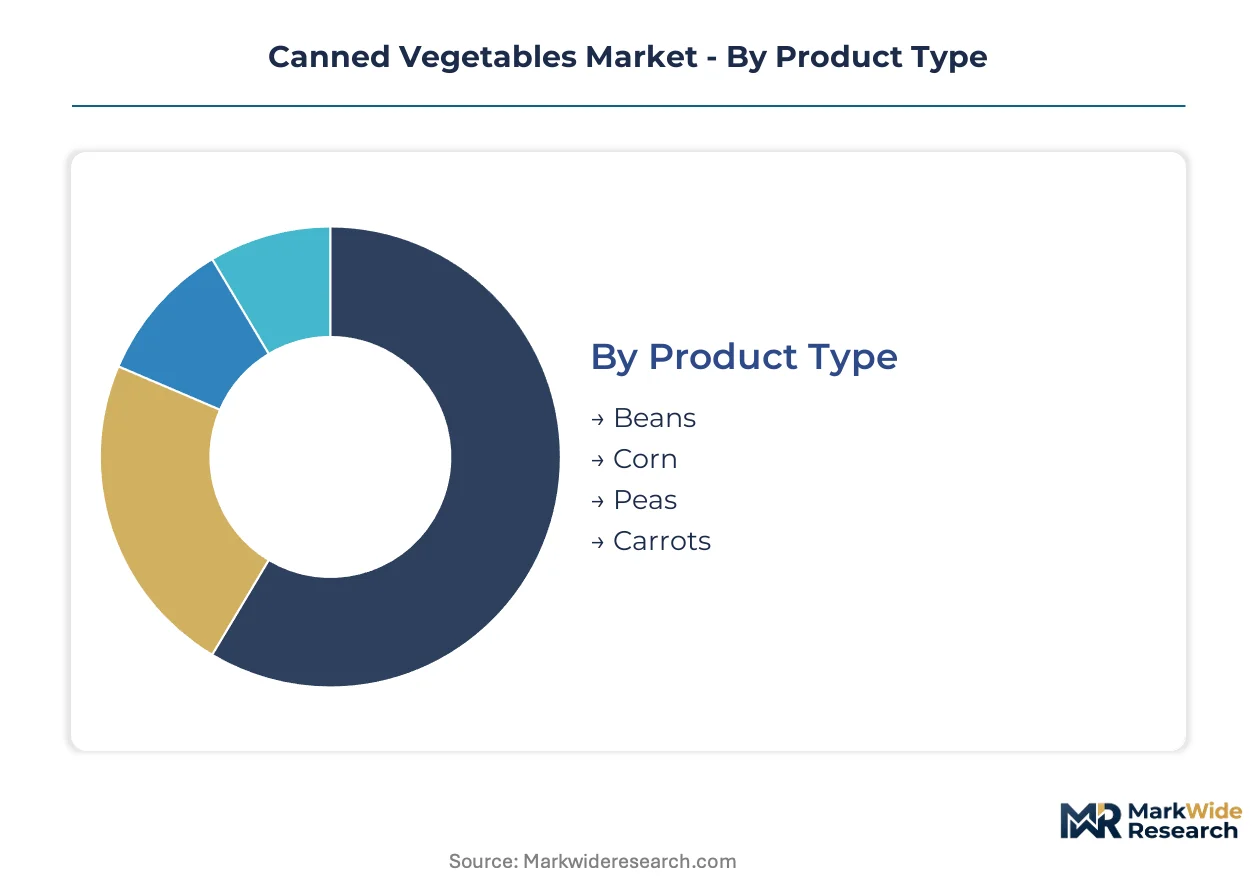
Canned vegetable procurement patterns diverge sharply across product categories, packaging formats, and institutional versus retail channels. Understanding these fault lines clarifies where formulation investments and shelf placement negotiations concentrate competitive advantage.
Product Type:
Volume concentration and harvest seasonality determine which vegetable categories anchor processor capacity planning and retail promotional calendars.
- Beans:Dried and fresh legumes undergo pressure-canning at 121°C to achieve commercial sterility for chili, soup, and side-dish applications. Demand clusters in US Southwest and Mexican food manufacturing where refried and black bean formulations require consistent year-round supply.
- Corn:Sweet corn kernels and creamed varieties dominate Midwest processing infrastructure, with Seneca Foods and Conagra operating captive acreage contracts across Illinois and Minnesota. Harvest windows concentrate procurement risk in a six-week period, forcing forward contracting.
- Peas:Garden and split pea formats serve prepared meal manufacturers requiring standardized moisture content and color grading.
- Carrots:Sliced and diced carrot products target institutional foodservice channels with uniform cook-time specifications.
Beans holds installed capacity. Corn is rotating up the share rankings.
Packaging Type:
Material science investments and freight economics are redistributing share across rigid and flexible formats, with sustainability mandates accelerating format transitions.
- Aluminum Can:Two-piece drawn aluminum dominates high-velocity retail SKUs with established post-consumer collection infrastructure. German retailers now mandate mono-material aluminum to satisfy EU packaging waste directives, tilting procurement specifications.
- Glass Jar:Visual inspection capability commands premium positioning in European organic segments where product transparency influences purchase decisions. Weight and breakage costs constrain distribution radius to 300 miles for most processors.
- Tetra Pak:Aseptic carton formats reduce freight weight for export-oriented Southeast Asian processors serving island archipelago logistics.
- Plastic Container:Polypropylene tubs with oxygen barrier layers target refrigerated premium lines with shorter shelf-life positioning.
Aluminum can maintains cost leadership. Glass jar is gaining share fastest in certified organic channels.
End User:
Customer type dictates thermal processing specifications, with institutional buyers demanding bulk formats and food manufacturers requiring ingredient-grade consistency.
- Households:Retail households purchase standard can sizes for pantry stocking, with subscription e-commerce models bypassing traditional slotting fees.
- Restaurants:Foodservice operators prioritize number-10 institutional cans with drainage specifications for kitchen efficiency.
- Food Processing Industry:Downstream manufacturers require drum-packed vegetables with documented thermal processing logs for FDA low-acid canned food compliance.
- Cafeterias:US K-12 and healthcare group purchasing organizations compress supplier lists and demand annual cost-down commitments.
Food processing industry holds installed capacity. Households is climbing the fastest as direct-to-pantry models expand.
Distribution Channel:
Channel configuration determines pack size, promotional intensity, and working capital requirements across the value chain.
- Supermarkets:Traditional retail commands slotting fee investments and seasonal promotional calendars, with private-label penetration highest in European markets.
- Online Retail:E-commerce platforms enable subscription bundling and bypass shelf placement premiums, building recurring revenue streams for regional brands.
- Convenience Stores:Small-format retail demands single-serve and ready-to-eat vegetable cups for immediate consumption.
- Wholesalers:Broadline distributors serve institutional accounts with palletized bulk shipments and consolidated invoicing.
Supermarkets holds installed capacity. Online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phasedowns and BPA-free lining mandates are redirecting capital toward ambient-stable formats in temperate and tropical zones alike. Cold-chain infrastructure gaps in emerging economies preserve canned vegetables as the dominant preservation method.
United States
Midwest sweet corn processing clusters anchor North American capacity, with Illinois and Minnesota hosting captive acreage contracts for institutional foodservice supply. FDA low-acid canned food regulations govern thermal processing parameters, creating compliance barriers for new entrants. Pacific Northwest operations are retooling can lines for BPA-free epoxy alternatives ahead of state-level mandates.
Germany
EU packaging waste directives and national deposit-return schemes favor mono-material aluminum formats in retail negotiations. German retailers now mandate minimum recycled content thresholds, tilting procurement specifications toward established post-consumer collection infrastructure. Bavarian food manufacturers are consolidating behind aluminum can formats to satisfy extended producer responsibility frameworks.
India
Perishable vegetable spoilage rates exceeding 30% drive food processing buyers toward shelf-stable inputs that eliminate refrigeration dependency. FSSAI regulations govern thermal processing standards for low-acid canned foods, with compliance costs favoring scaled operators. Maharashtra and Gujarat processing hubs are expanding retort capacity to serve domestic retail and export markets.
Indonesia
Island-to-island shipping costs and intermittent power favor ambient-stable formats across retail and humanitarian procurement channels. The country's national food safety authority enforces canning standards aligned with Codex Alimentarius protocols. Java-based processors are adopting retort pouch technology to reduce freight weight for archipelago distribution.
Brazil
São Paulo-state food manufacturers source shelf-stable vegetable inputs for prepared meal production serving Latin American markets. ANVISA regulates thermal processing parameters for low-acid canned foods, with validation requirements constraining new facility timelines. Minas Gerais agricultural corridors supply raw material to captive canning operations.
Canned Vegetables Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation characterizes North American and European markets where established operators wield validated process authorities and captive agricultural contracts. Three archetypes dominate: vertically integrated processors with backward control over raw material supply, brand-anchored multinationals with retail shelf placement premiums, and asset-light contract manufacturers enabling regional brand scaling. Competitive moves concentrate on BPA-free lining conversions and e-commerce direct-to-pantry subscription models.
Among North American-based operators, Conagra Brands and Seneca Foods Corporation exemplify divergent strategic positions within the integrated processor archetype, while Del Monte Foods Inc. occupies a position representing brand-anchored multinational reach. These three companies illustrate how channel control, agricultural integration, and geographic brand equity create distinct competitive footing without requiring identical resource configurations.
| Leading Market Players |
|---|
| Conagra Brands |
| Seneca Foods Corporation |
| Del Monte Foods Inc. |
| Campbell Soup Company |
| Bonduelle SA |
| Nestlé S.A. |
| Dole plc |
| TreeHouse Foods Inc. |
| The Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Midwest sweet corn processing clusters in Illinois and Minnesota concentrate raw material procurement, anchoring margin pools downstream with institutional foodservice buyers and private-label retailers who compete on volume scale rather than brand premium. This geographic concentration of captive acreage contracts forces processors to absorb harvest volatility while competing processors in Southeast Asia exploit flexible retort pouch formats to arbitrage freight cost advantages.
Pricing Analysis
Certification level creates the primary spread between premium organic lines and conventional economy tiers, with USDA organic and EU organic seals commanding shelf placement premiums in natural food channels. Three-tier pricing structure across premium, standard, and economy levels reflects BPA-free lining compliance costs, aluminum coil input volatility, and brand equity differentiation. Cost compression in private-label aluminum can segments is intensifying because German retailers now mandate mono-material formats with minimum recycled content thresholds. Institutional foodservice buyers through US K-12 and healthcare group purchasing organizations exhibit highest price sensitivity, while European organic specialty retailers show lowest sensitivity due to visual inspection preferences for glass jar formats.
Supply Chain Analysis
Extended payment terms from German retailers and supply-chain finance facilities from Southeast Asian processors are restructuring working capital requirements across tiered supplier networks. Raw material supply concentrates in the US Midwest for sweet corn, China's Heilongjiang corridor for select legumes, and India's Maharashtra-Gujarat belt for domestic retail and export processing. Tinplate and aluminum coil feedstock draws from energy-intensive smelting operations in China and Russia, exposing can manufacturers to electricity cost swings. Single-source agricultural concentration around six-week harvest windows creates harvest failure exposure. Distribution runs through broadline wholesalers serving institutional accounts, with e-commerce direct-to-pantry subscription models bypassing traditional retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated thermal processing specialists and FDA process authorities represent the critical capability gap constraining new facility commissioning, with retort process authority scarcity extending timelines for entrants lacking established compliance infrastructure.
For Market Incumbents: Harden BPA-free lining conversion timelines ahead of state-level mandates in the US Pacific Northwest, securing welding and coating equipment upgrades before capacity bottlenecks emerge. Deepen backward integration into agricultural sourcing through captive acreage contracts in Illinois and Minnesota to defend against harvest failure exposure and stabilize input costs against commodity volatility. For New Entrants and Emerging Players: Build out asset-light contract manufacturing partnerships with established retort facilities to bypass capital-intensive plant construction, targeting Indonesia's archipelago logistics where island-to-island shipping costs and intermittent power favor ambient-stable formats. E-commerce direct-to-pantry subscription models offer the most penetrable channel, enabling recurring revenue streams without slotting fee investments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers and regional co-packers possessing validated process authorities but lacking brand equity or agricultural integration. Five-to-ten year viability hinges on BPA-free lining conversion completion and e-commerce channel capture. The signal to watch is consolidation velocity among German retailers mandating mono-material aluminum formats, which will determine which packaging configurations retain shelf access.| Strategic Initiative | Industry Significance |
|---|---|
| BPA-Free Lining Conversion | Retooling can lines ahead of FDA and state-level mandates preserves shelf access in North American retail. |
| Backward Integration into Agricultural Sourcing | Captive acreage contracts in Illinois and Minnesota stabilize input costs against six-week harvest concentration. |
| Retort Pouch Technology Adoption | Flexible packaging sterilization reduces freight weight for Southeast Asian processors serving island archipelago logistics. |
| E-Commerce Direct-to-Pantry Launch | Subscription bundling bypasses supermarket slotting fees and builds recurring revenue for regional brands. |
| USDA Organic Certification Expansion | Premium positioning through certified organic lines captures price multiples in European and North American natural food channels. |
Methodological Framework
Initial hypotheses were tested against primary input from food processing procurement managers, retail category buyers, can manufacturing operations directors, and regulatory compliance officers, then refined against secondary validation from FDA low-acid canned food filings, USDA grading standards documentation, EU F-Gas Regulation impact assessments, and customs trade data on tinplate and aluminum coil movements. Bottom-up volume modeling across product types, packaging formats, and end-user segments was triangulated with top-down macroeconomic anchoring.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product type, packaging format, end-user category, and distribution channel, with CAGRs derived from historical trajectory analysis and forward-looking input cost assumptions. Forecast inputs incorporated BPA-free lining conversion capital expenditure schedules, cold-chain infrastructure development timelines in India and Southeast Asia, and extended producer responsibility framework implementations in Germany and France.
Stress conditions across aluminum and tinplate input price volatility, harvest yield variance, and regulatory compliance timeline slippage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticity between canned and frozen formats, infrastructure investment pacing, and trade flow stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Frozen Soup Market