
 Fava Beans Market | 2026-2036
Fava Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Fava Beans Market Intelligence
Ingredient processing revenue is reconfiguring margin pools away from raw commodity trading toward value-added protein extraction and fractionation. AGT Food and Ingredients Inc. leverages its pulse processing infrastructure across North American facilities to capture this shift. Roquette Freres sustains its position through specialized protein isolation technology for plant-based meat applications. BENEO Corporation anchors European supply with integrated fava starch and protein operations.
Fava beans (Vicia faba) are large-seeded annual legumes containing approximately 25-30% protein by dry weight, with distinct nutritional profiles varying by cultivar and processing method. The beans undergo dehulling, splitting, or air-classification milling to produce ingredients ranging from whole cotyledons to fine protein isolates for food manufacturing. Whole beans and powder categories dominate current volume, though processed products command superior margins through functional protein concentrates. The Food & Beverage end-use industry leads absolute consumption, while nutraceutical applications represent the fastest-expanding segment as supplement formulators seek allergen-free alternatives to soy and pea protein.
FDA food labeling requirements and USDA organic certification standards shape ingredient transparency and clean-label positioning in the United States. The EU Green Deal and EFSA novel food authorization pathways determine market access for innovative fava-derived ingredients within Europe. Stakeholders must monitor protein functionality benchmarking against established alternatives and regulatory clarity on sustainability claims to secure formulation partnerships.
Market Dynamics
Protein fractionation technology is compressing ingredient economics and forcing commodity traders to rebuild around functional isolate capabilities or exit fava bean value chains entirely.
Growth Catalysts
- EU Green Deal protein diversification:Agricultural subsidy redirection toward legume cultivation expands domestic fava bean acreage across France, Germany, and Poland. Food processors secure localized supply chains for meat alternative formulations.
- Food & Beverage reformulation:Plant-based meat manufacturers substitute fava protein isolates for soy and pea to achieve cleaner allergen profiles and improved texture in finished products.
- Air-classification milling:Dry fractionation advances reduce water intensity in protein concentrate production, lowering capital barriers for regional processing facilities.
Market Restraints
- Vicine-convicine antinutrient removal:Low-tannin cultivar breeding and enzymatic debittering add processing cost layers that commodity whole-bean traders cannot absorb.
- Black Sea supply concentration:Ukraine and Russia-origin fava bean exports dominate global raw volume, exposing buyers to geopolitical disruption and port access volatility.
- Pea protein substitution:Established pea isolate supply chains and familiar functionality profiles slow fava protein adoption in risk-averse formulation environments.
Strategic Opportunities
- India pulse processing infrastructure:Underutilized dal milling capacity in Madhya Pradesh and Maharashtra regions offers low-cost entry points for fava protein isolate production targeting Asian nutraceutical demand.
- EFSA novel food authorization:Regulatory clarity on fava-derived ingredients unlocks formulation partnerships with European dairy alternative and sports nutrition brands.
- Precision fermentation hybridization:Combining fava protein hydrolysates with microbial biomass production creates next-generation functional ingredients for cellular agriculture applications.
Industry Challenges
- Protein functionality benchmarking:Formulators lack standardized protocols comparing fava isolate gelling, emulsification, and solubility against incumbent soy and pea benchmarks, delaying specification approvals.
- Organic certification timelines:USDA organic and EU organic transition periods for newly converted legume acreage create supply gaps that conflict with food manufacturer clean-label commitments.
- Fractionation engineering talent:Shortage of process engineers experienced in pulse air-classification and wet-extraction systems constrains capacity expansion at regional processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fava Beans Market |
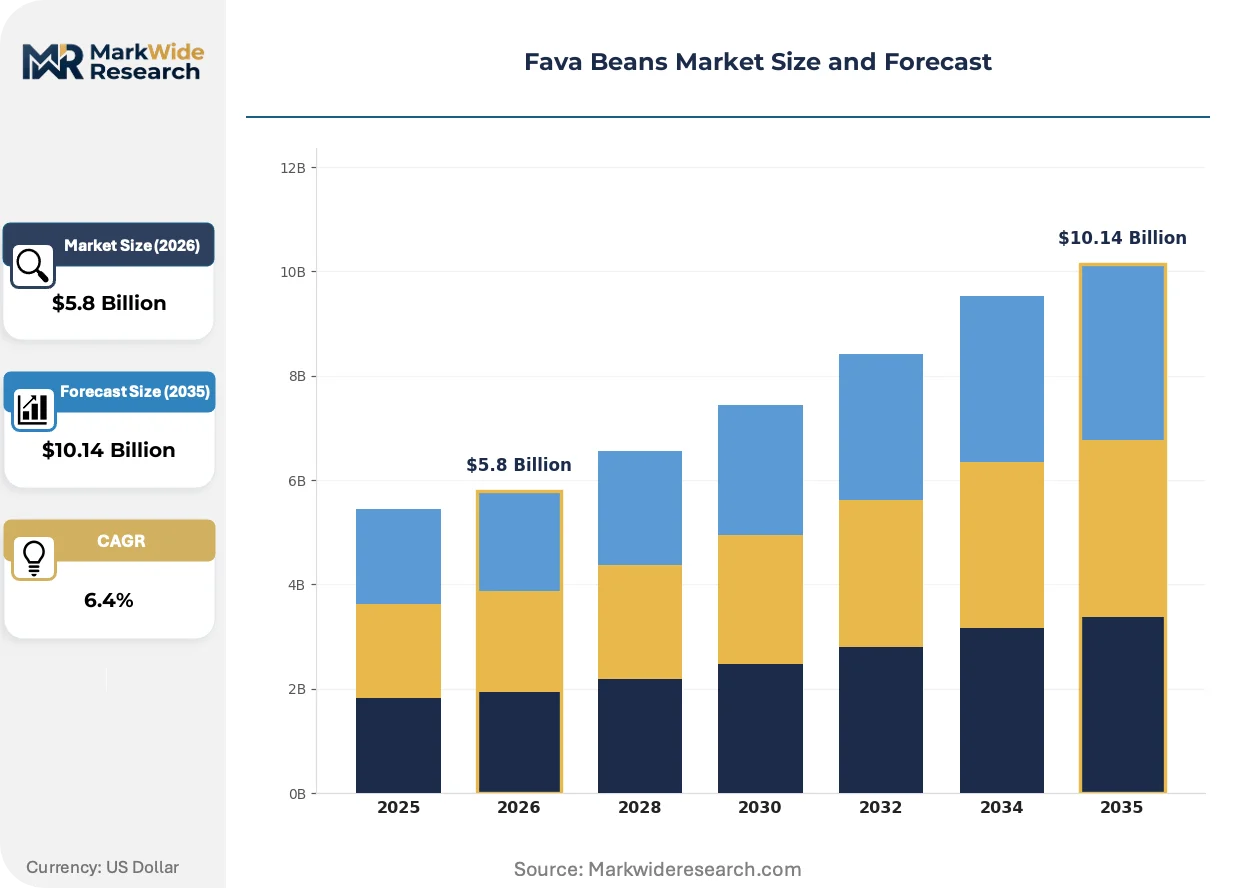
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Split Beans, Powder, Processed Products End Use Industry: Food & Beverage, Feed Industry, Nutraceuticals, Cosmetics Packaging Type: Bulk Packaging, Retail Packs, Vacuum Sealed, Tetra Packs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | AGT Food and Ingredients Inc., Nuttee Bean Co., Roquette Freres, Unigrain Pty Ltd, GrainCorp Limited, BENEO Corporation, Burcon NutraScience Corporation, Prairie Fava Ltd., Bunge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fava Beans Market Strategic Shifts & Innovations
Digital twin modeling of protein extraction yield curves is compressing pilot-to-scale timelines and enabling real-time process optimization across distributed processing networks.
Dry fractionation equipment is virtualizing traditional wet-extraction infrastructure by enabling protein-starch separation without water-intensive steps. Mid-cap processors in Germany and the Netherlands adopt these systems to reduce effluent treatment burdens. The technology is virtualizing capital deployment patterns, allowing smaller facilities to achieve isolate-grade outputs previously requiring industrial-scale aqueous processing plants.
EFSA novel food authorization pathways are restructuring ingredient market access timelines for innovative fava-derived products. Food manufacturers delay formulation commitments pending regulatory certainty on protein isolate safety dossiers. European plant-based dairy and meat alternative segments are responding by pre-submitting proprietary fractionation processes to accelerate competitive positioning.
Clean-label procurement mandates are displacing commodity spot purchasing with long-term offtake agreements tied to sustainability certification. German and French food processors now contract directly with farmer cooperatives for identity-preserved fava bean supply. This pattern concentrates most visibly in Bavaria and Brittany regions where processor-producer vertical coordination secures traceability for organic and regenerative agriculture claims.
Fava Beans Market Segmentation
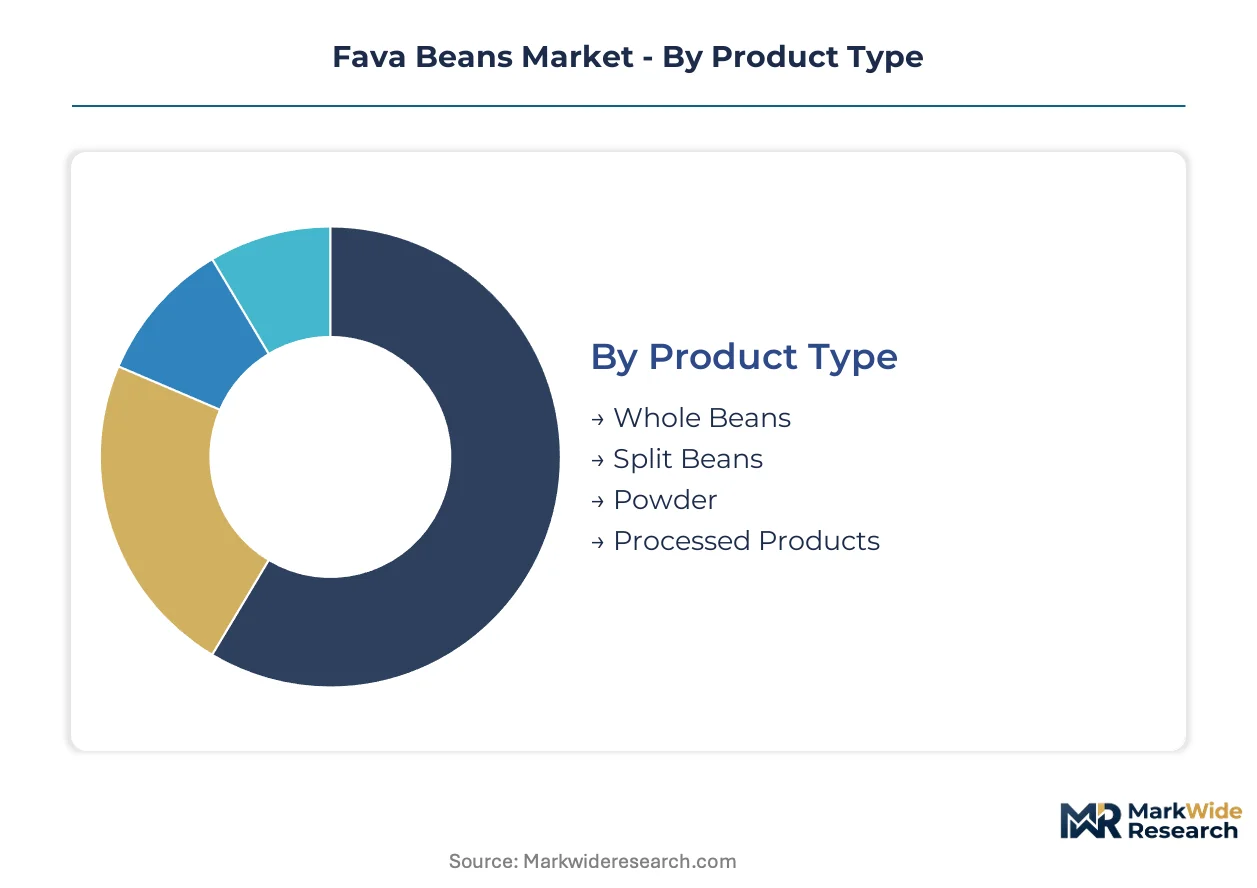
Fava bean market segmentation reveals how value migrates from commodity whole beans toward functional ingredients. Processing depth, end-use application, and distribution channel each reshape margin capture and competitive positioning across the value chain.
Product Type:
The use-case spectrum spans from agricultural commodities to specialized protein isolates, with processing intensity determining pricing power and customer stickiness.
- Whole Beans:Raw fava beans retain hulls and require dehulling before food manufacturing. German meat alternative processors source identity-preserved whole beans from Bavarian farmer cooperatives to secure organic certification and traceability for clean-label claims.
- Processed Products:Protein isolates and concentrates command premium positioning through functional gelling and emulsification properties. Air-classification milling advances enable mid-cap processors to achieve isolate-grade outputs without water-intensive wet extraction, lowering capital barriers for regional facilities.
- Split Beans:Dehulled and split cotyledons accelerate cooking time for traditional Mediterranean and Middle Eastern food applications.
- Powder:Ground whole or split beans serve as flour extenders in gluten-free bakery formulations and as base material for further fractionation.
The dominant share belongs to Whole Beans, while Processed Products is closing the gap fastest.
End Use Industry:
Customer type determines specification rigor, with food manufacturers demanding functional benchmarking against soy and pea benchmarks while feed buyers prioritize volume and price stability.
- Food & Beverage:Plant-based meat manufacturers substitute fava protein isolates for soy and pea to achieve cleaner allergen profiles and improved texture. EFSA novel food authorization pathways determine market access for innovative fava-derived ingredients in European dairy alternative formulations.
- Nutraceuticals:Supplement formulators seek allergen-free alternatives to soy and pea protein for sports nutrition and senior nutrition applications. Fava protein hydrolysates combine with microbial biomass production in precision fermentation hybridization for next-generation functional ingredients.
- Feed Industry:Compound feed manufacturers utilize fava beans as protein-rich alternatives to soybean meal in poultry and aquaculture rations.
- Cosmetics:Fava starch and protein derivatives enter natural skincare formulations as texturizing and film-forming agents.
Food & Beverage maintains the largest consumption base, with Nutraceuticals expanding most quickly as clean-label protein demand intensifies.
Packaging Type:
Volume scale and shelf-life requirements split procurement patterns between industrial buyers and consumer-facing channels.
- Bulk Packaging:25-50kg sacks and tote bags serve food processors and feed compounders with high-throughput ingredient handling systems. Black Sea-origin exports dominate this segment, exposing buyers to geopolitical disruption and port access volatility.
- Vacuum Sealed:Oxygen barrier packaging extends shelf life for premium organic and specialty grade beans targeting discerning retail channels.
- Retail Packs:500g to 2kg consumer formats stock supermarket shelves and specialty grocers in urban centers.
- Tetra Packs:Aseptic cartons for ready-to-use fava bean purees and cooking bases serve convenience-oriented foodservice operators.
Bulk Packaging handles the greatest tonnage, though Vacuum Sealed formats are gaining share fastest as organic certification premiums justify protective packaging investment.
Distribution Channel:
Supply chain configuration directly shapes price discovery and relationship economics across fragmented buyer bases.
- Wholesale:Trader-mediated spot and contract sales connect Ukrainian and Russian-origin supply with European and Asian processors. This channel concentrates price risk and quality variability for buyers lacking direct farm relationships.
- Supermarkets:Mass retail chains in Germany and France stock packaged whole and split beans for home cooking segments, with private label penetration rising.
- Specialty Stores:Ethnic grocers and health food retailers curate organic and heritage cultivar selections for Mediterranean and Middle Eastern diaspora communities.
- Online Retail:Direct-to-consumer platforms and B2B marketplaces reduce intermediary layers for small-batch nutraceutical formulators seeking traceable supply.
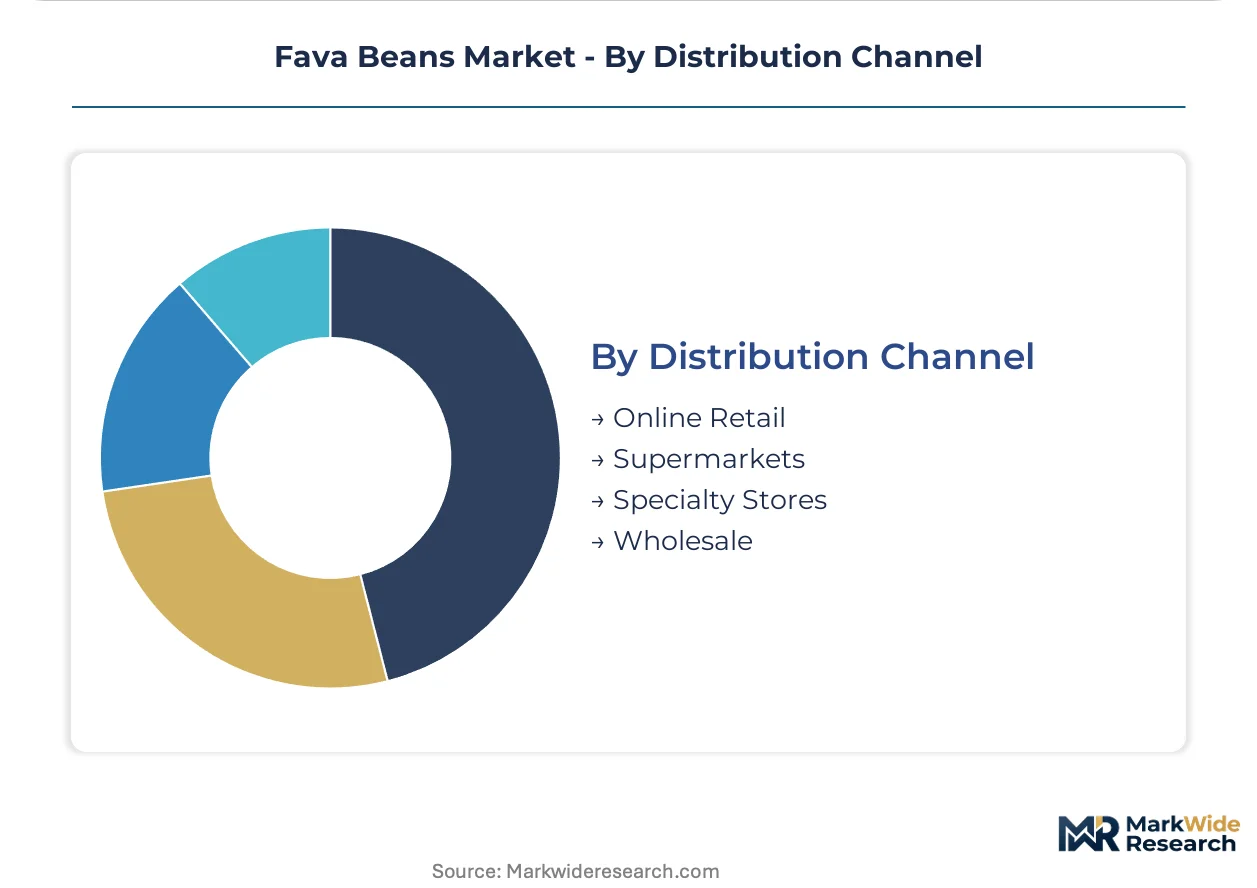
Wholesale channels move the highest volume, while Online Retail is climbing the fastest as procurement digitization penetrates ingredient sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes fava beans primarily into meat alternative isolates, while India channels them through underutilized dal mills for nutraceutical powder exports. This consumption-mix differential shapes divergent infrastructure investments and regulatory priorities across key producing and processing geographies.
Germany
Plant-based meat manufacturers in Bavaria reformulate with domestically sourced fava protein to achieve cleaner allergen profiles than soy alternatives. The EU Green Deal's protein diversification targets redirect agricultural subsidies toward legume cultivation in Bavarian and Brandenburg farming cooperatives. Food processors in Munich and Hamburg secure identity-preserved supply chains through direct contracting with regional farmer cooperatives.
France
Roquette Freres anchors European fava starch and protein operations through specialized isolation technology for dairy alternative formulations. EFSA novel food authorization pathways determine market access timelines for innovative fractionated ingredients. Processing clusters in the Hauts-de-France and Brittany regions concentrate air-classification milling capacity to serve reformulating food manufacturers.
India
Supplement formulators seek allergen-free protein alternatives to soy and pea for sports nutrition applications, driving demand for fava-derived ingredients. FSSAI food safety standards and PLI scheme incentives for food processing infrastructure shape investment decisions. Underutilized dal milling capacity in Madhya Pradesh and Maharashtra offers low-cost entry points for protein isolate production targeting Asian nutraceutical markets.
United States
FDA food labeling requirements and USDA organic certification standards drive clean-label positioning among plant-based meat manufacturers. Compound feed manufacturers in the Midwest utilize fava beans as protein-rich alternatives to soybean meal in poultry rations. Pulse processing infrastructure across North American facilities captures margin migration toward value-added protein extraction.
Australia
GrainCorp Limited leverages bulk handling networks to connect Black Sea-origin supply volatility with Asian processor demand. The country's national agricultural regulator maintains biosecurity protocols for imported legume shipments. Export-oriented trading operations in Melbourne and Sydney concentrate spot and contract sales to European and Asian buyers.
Fava Beans Market Key Industry Players
Capability concentration sits with specialized protein fractionation technology holders; scale advantage sits with diversified agribusiness traders with existing pulse infrastructure. The competitive structure tiers between commodity whole-bean merchants and functional isolate processors. Three archetypes dominate: integrated pulse processors with air-classification assets, specialized protein isolation technology licensors, and diversified grain traders pivoting toward ingredient value chains. Dominant competitive moves include backward integration into farmer cooperative contracting and technology licensing partnerships for dry fractionation systems.
Within the integrated processing tier, AGT Food and Ingredients Inc. and BENEO Corporation exemplify divergent geographic anchoring strategies for margin capture. Roquette Freres occupies a position representing specialized protein isolation capabilities for plant-based meat applications. Among North American specialists, Burcon NutraScience Corporation and Prairie Fava Ltd. sit within the technology-focused archetype targeting functional ingredient positioning.
| Leading Market Players |
|---|
| AGT Food and Ingredients Inc. |
| Nuttee Bean Co. |
| Roquette Freres |
| Unigrain Pty Ltd |
| GrainCorp Limited |
| BENEO Corporation |
| Burcon NutraScience Corporation |
| Prairie Fava Ltd. |
| Bunge |
| Others |
Cost & Logistics Intelligence
Black Sea export concentration exposes buyers to port access volatility that widens spreads between contract and spot pricing tiers while forcing European processors toward identity-preserved farmer contracting. This structural vulnerability compresses margins for commodity traders unable to secure long-term offtake agreements while rewarding integrated processors with captive supply chains.
Pricing Analysis
Long-term offtake agreements dominate procurement for German and French food processors seeking organic certification traceability, while spot markets absorb Black Sea-origin volume volatility. Price differentiation hinges on functional protein grade and EU organic certification tier, with isolate-grade concentrates commanding substantial premiums over whole-bean commodity benchmarks. Cost compression in standard-grade powder runs through enzymatic debittering add-ons required for vicine-convicine removal. Feed compounders exhibit highest price sensitivity due to substitution elasticity with soybean meal, whereas nutraceutical formulators prioritize allergen-free profile consistency over unit cost.
Supply Chain Analysis
Roquette Freres and AGT Food and Ingredients Inc. anchor contract-manufacturing concentration for protein isolate capacity across European and North American facilities. Raw material flows draw from Ukraine, Russia, and emerging French cultivation regions expanding under EU Green Deal subsidy redirection. The supply chain hinges on low-tannin cultivar seedstock availability and air-classification milling equipment lead times. Single-source vulnerability concentrates in Black Sea port access for raw bean intake. Distribution runs through processor-direct contracting with Bavarian and Brittany farmer cooperatives, displacing traditional trader-mediated spot channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fractionation technology licensing and protein functionality certification services expand faster than raw commodity throughput, creating recurring-revenue attach opportunities for equipment suppliers and analytical laboratories.
For Market Incumbents: Insulate margin pools by deepening backward integration into identity-preserved seedstock programs and farmer cooperative contracting in Bavaria and Brittany. Roquette Freres and BENEO Corporation demonstrate how captive supply chains neutralize Black Sea price volatility while securing EFSA novel food authorization timelines. Air-classification equipment partnerships with regional processors extend technology licensing revenue beyond captive capacity utilization. For New Entrants and Emerging Players: Pursue underutilized dal milling conversion opportunities in Madhya Pradesh and Maharashtra for low-cost isolate production targeting Asian nutraceutical demand. The fastest-penetrable white space sits in sports nutrition hydrolysates where allergen-free positioning commands formulation premium. Go-to-market leverage rests on FSSAI compliance bundling with PLI scheme infrastructure incentives for food processing investment. For Investors and Strategic Acquirers: EFSA novel food authorization reshapes the acquisition landscape by concentrating value in dossier-ready fractionation technology holders rather than commodity trading assets. Long-term viability centers on processors capable of isolate-grade output with water-efficient dry fractionation economics. The signal to watch is German meat alternative manufacturer specification approvals for fava protein gelling benchmarks against incumbent pea isolates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seedstock Programs | Bavarian farmer cooperative contracting secures organic traceability for EFSA-compliant isolate production. |
| Air-Classification Technology Licensing | Roquette Freres extends proprietary milling systems to mid-cap regional processors seeking effluent reduction. |
| EFSA Novel Food Pre-Submission | Accelerated regulatory pathways unlock formulation partnerships with European dairy alternative manufacturers. |
| India Dal Mill Conversion Partnerships | Madhya Pradesh infrastructure repurposing targets Asian nutraceutical demand with PLI scheme support. |
| Protein Functionality Certification Services | Standardized gelling and emulsification benchmarking protocols reduce formulator specification approval delays. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU Green Deal subsidy disbursement records, EFSA novel food authorization databases, and FSSAI food processing infrastructure filings. Interviews with pulse processing plant managers, German meat alternative procurement leads, French farmer cooperative agronomists, and Indian dal mill operators inform capacity utilization and technology adoption patterns. Secondary validation draws from customs trade data for Black Sea-origin legume shipments, USDA organic certification registries, and SEC filings from listed agribusiness processors. Bottom-up facility capacity modeling triangulates against top-down protein demand projections from food manufacturer reformulation announcements.
Forecast inputs span processing depth tier, end-use application rigor, and distribution channel configuration across the projection horizon. Segmentation dimensions include product type spectrum from whole bean to isolate, end-use industry differentiation between food manufacturing and nutraceutical formulation, and regional regulatory cluster alignment with EU Green Deal, FDA labeling requirements, and FSSAI standards. CAGRs derive from protein substitution elasticity modeling against soy and pea benchmarks, coupled with air-classification technology diffusion curves for regional processing capacity expansion.
Sensitivities concentrate around EFSA authorization timeline delays, Black Sea port access disruption, and low-tannin cultivar breeding program yields. Forecasts reflect assumptions on farmer subsidy redirection persistence and meat alternative manufacturer specification approval velocity. Quarterly review of German processor-producer contracting announcements and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Fresh Cherries Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Pineapple Market