
 Fresh Lemons Market | 2026-2036
Fresh Lemons Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Lemons Market Insights
Multi-source procurement from Mediterranean and Latin American growers is decoupling from the historical single-origin dependency that dominated fresh lemon supply chains. Sunkist leverages its century-old cooperative structure to sustain year-round availability across North American retail channels. Laoyishengxian anchors e-commerce distribution within China's domestic citrus trade, competing on speed-to-shelf rather than origin branding. Organic Mountain differentiates through certified organic acreage in California's Central Valley, where it controls direct farm-to-retail relationships with specialty grocers.
Fresh lemons denote the unprocessed fruit of Citrus limon, harvested at color-break to full-yellow maturity with titratable acidity typically ranging from five to eight percent and essential oil concentration in the flavedo layer determining aromatic intensity; the fruit serves as a raw input for juice extraction, culinary acidification, essential oil distillation, and natural preservative applications across food and beverage manufacturing. Conventional product types still occupy the largest volume share, though organic and specialty grades command disproportionate margin pools as retailers segment shelf space by certification tier. Juice producers represent the fastest-growing end-user category, driven by contract demand from cold-pressed beverage bottlers and flavor houses seeking consistent acid profiles.
USDA grading standards and the FDA's Food Safety Modernization Act shape domestic market access by mandating traceability systems and microbial testing protocols for imported fresh citrus. The EU's CE marking requirements for processing equipment and REACH compliance for post-harvest treatments filter which suppliers can serve European juice producers and packers. Stakeholders must monitor how climate volatility in key growing basins reshapes harvest timing and whether emerging phytosanitary barriers in Asian import markets reroute trade flows from traditional export corridors.
Market Dynamics
Juice producers' cold-pressed beverage expansion is compressing harvest-to-processing windows across Mediterranean and Latin American supply basins, forcing packers to synchronize color-break maturity with acid-profile specifications demanded by flavor houses.
Growth Catalysts
- EU F-Gas Regulation:Tightened cold-chain emissions standards for perishable citrus transport are accelerating fleet retrofits and triggering demand for low-GWP refrigeration systems in Spanish export corridors.
- Cold-pressed juice extraction:Premium beverage bottlers are contracting directly with Murcia and Valencia growers for consistent titratable acidity, bypassing traditional wholesale auction structures.
- Essential oil distillation:Flavor houses are expanding flavedo-layer procurement for aromatic intensity specifications, creating parallel revenue streams for processors previously focused on juice yield alone.
Market Restraints
- Input cost volatility:Natural gas price swings directly compress margins for heated post-harvest washing and waxing operations in California's Central Valley packing sheds.
- Supply concentration risk:Spain's Mediterranean export dominance creates single-point vulnerability to citrus greening vector pressure and irrigation allocation disputes in the Segura River basin.
- REACH compliance friction:Post-harvest treatment registration delays are blocking non-EU suppliers from European juice producer qualification programs, lengthening market entry timelines.
Strategic Opportunities
- Underpenetrated organic acreage:Certified organic lemon production in Argentina's Tucumán province offers counter-seasonal supply for North American retailers seeking year-round organic SKUs.
- E-commerce speed-to-shelf:Direct-to-consumer platforms in China's domestic citrus trade are compressing distribution layers, enabling origin-labeled lemons to reach urban consumers within 48 hours of harvest.
- Technology convergence:Near-infrared spectroscopy paired with blockchain traceability is enabling real-time acid-profile verification at packing house intake, reducing rejection rates for contract juice deliveries.
Industry Challenges
- Phytosanitary certification timelines:Emerging Asian import markets are extending quarantine protocols for Mediterranean fruit fly mitigation, forcing exporters to hold inventory in bonded cold storage.
- Cold-chain capex intensity:Compliance with EU F-Gas phase-down schedules requires fleet replacement investments that strain mid-size Spanish logistics operators serving Valencia export terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Lemons Market |
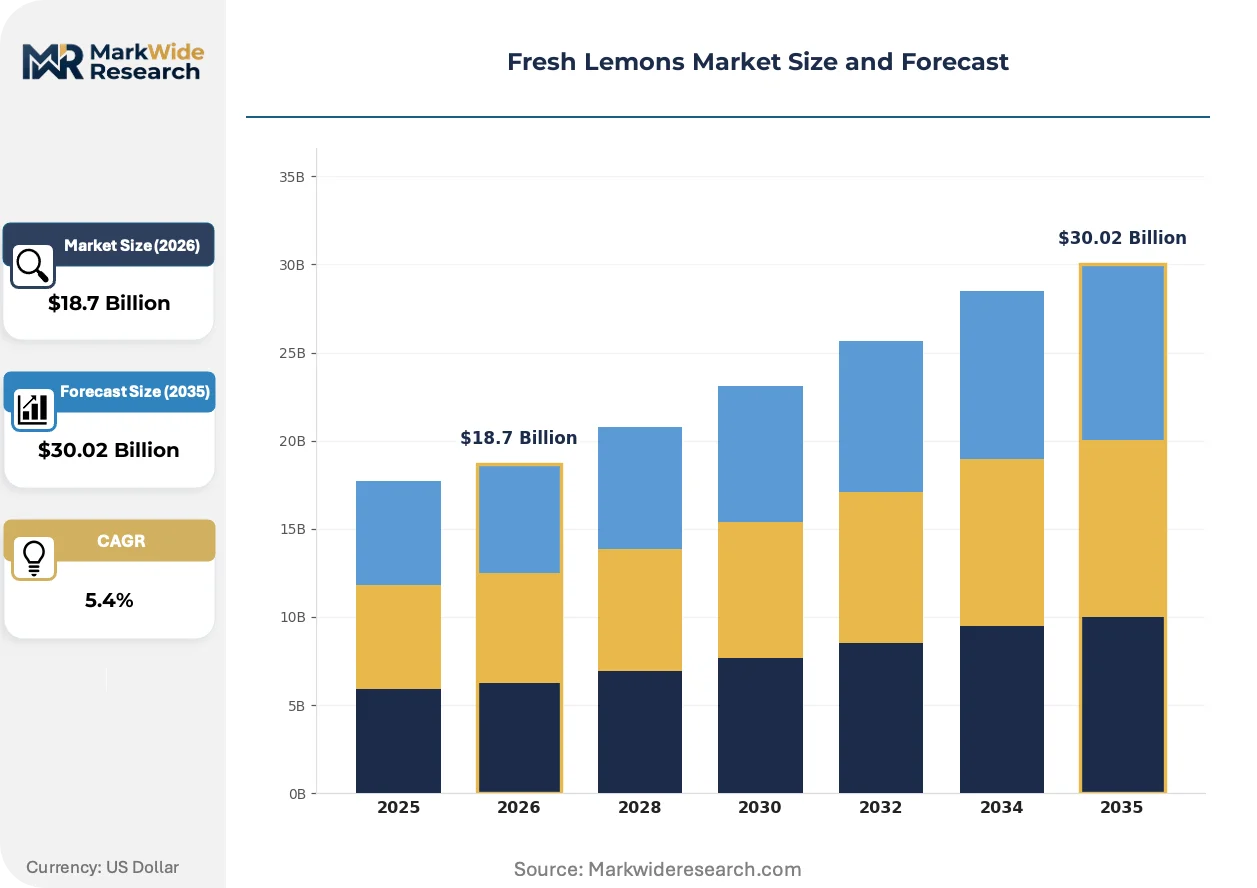
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Value-added, Specialty End User: Retail, Food Service, Juice Producers, Exporters Distribution Channel: Direct Sales, Wholesalers, Online Retail, Supermarkets Packaging Type: Bags, Boxes, Bulk, Clamshell |
| Companies Covered | Fairview Orchards, Organic Mountain, Sunkist, Laoyishengxian, Sanniti, Melissa's Produce, TastePadThai, Kaiying Trading, Fruit World, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Lemons Market Trends and Innovations
Spectral sorting technology is compressing quality-assurance cycles at packing houses while regulatory pressure on refrigerant chemistry reshapes logistics procurement. Consumer-facing traceability demands are forcing transparency investments back to orchard level.
Near-infrared spectroscopy systems deployed at color-break staging facilities measure titratable acidity and essential oil concentration without destructive sampling. Juice producers adopting this inline verification are reducing lot rejection rates and compressing contract negotiation cycles. Conventional wet-chemistry laboratory testing is overtaking manual Brix refractometry as the baseline quality protocol across Mediterranean export cooperatives.
The EU F-Gas Regulation's hydrofluorocarbon phase-down mandates are triggering cold-chain equipment replacement cycles across Spanish and Italian transport fleets. Refrigerated trailer operators serving Murcia-Valencia export corridors face compressed compliance timelines as 2024-2030 reduction targets escalate. Mid-size logistics providers are responding by leasing rather than owning compliant assets, shifting capital structure across the perishable citrus distribution tier.
Retail buyers in North American and European channels are unbundling origin claims from traditional wholesale markups, demanding direct orchard-to-shelf documentation. Specialty grocers are displacing conventional distributors by contracting directly with California Central Valley and Argentine Tucumán growers for certified organic lines. This channel compression is most visible in German and Dutch retail markets where discounter competition has eroded traditional wholesale margins.
Fresh Lemons Market Segmentation
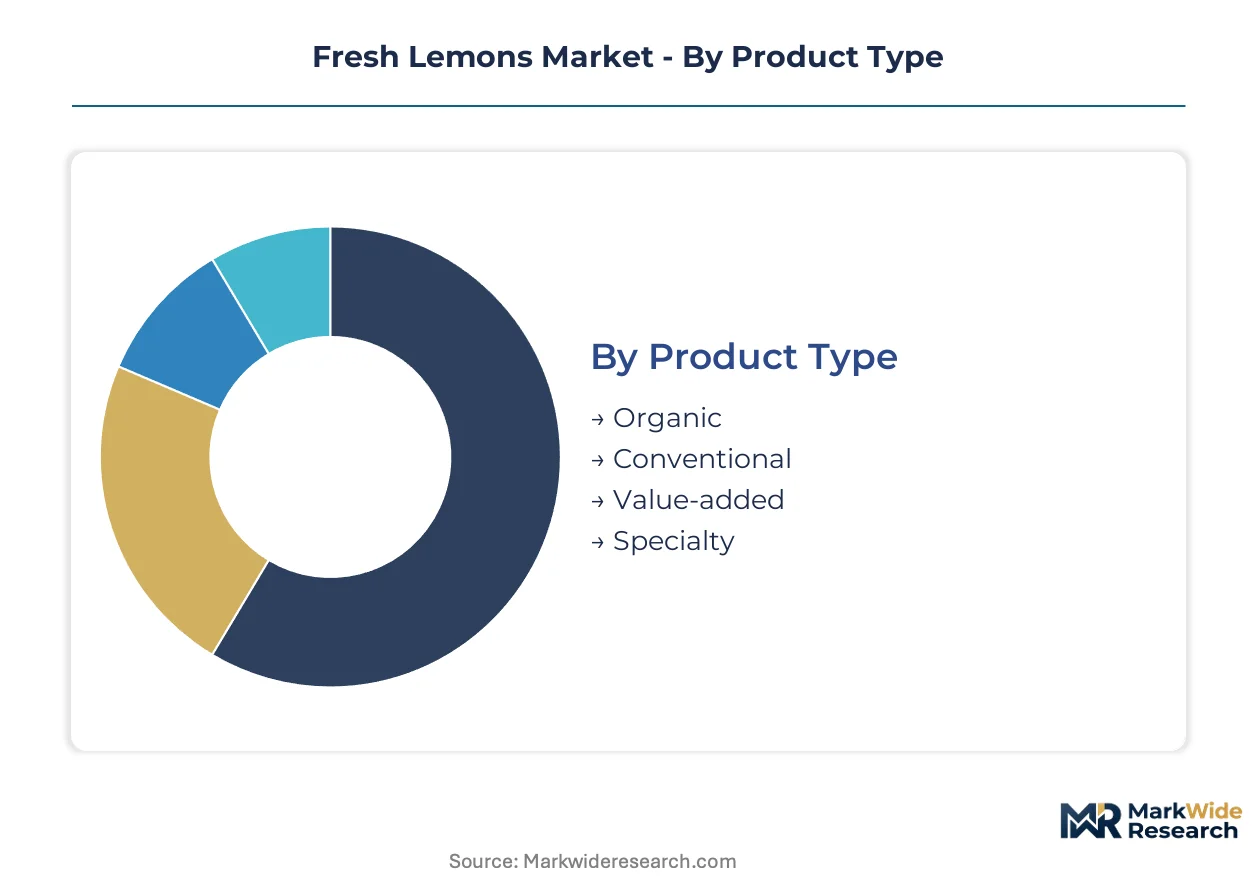
Fresh lemon segmentation tracks how certification tiers, channel structures, and packaging formats split procurement budgets across distinct quality and logistics requirements. Buyers segment supply by acid-profile specifications for juice extraction against visual-grade standards for retail display.
Product Type:
Upgrade cycles in product type selection track retailer certification requirements and juice-processor acid-profile demands rather than pure price sensitivity.
- Organic:Certified acreage adheres to USDA National Organic Program or EU organic standards, prohibiting synthetic pesticides and mandating soil-building practices. German and Dutch retailers contract directly with Argentine Tucumán growers for counter-seasonal organic supply, bypassing traditional wholesale markups to capture margin.
- Conventional:Standard agricultural protocols permit synthetic crop protection and controlled post-harvest fungicide applications. Spanish Murcia and Valencia cooperatives move the largest conventional volumes through Mediterranean export terminals to juice producers seeking consistent titratable acidity.
- Value-added:Pre-washed, waxed, or laser-etched fruit commands shelf-ready positioning.
- Specialty:Heritage varieties and limited-harvest lines target premium culinary channels.
Volume placements concentrate in Conventional; the faster expansion belongs to Organic.
End User:
End-user cost tiers separate commodity-scale juice extraction from premium retail and food-service positioning.
- Juice Producers:Cold-pressed beverage bottlers contract for color-break maturity synchronized to five-to-eight-percent titratable acidity. Flavor houses in California and Spain now specify flavedo-layer essential oil concentration alongside juice yield, creating dual-revenue contracts for processors.
- Retail:Supermarket chains and specialty grocers grade on visual uniformity, size consistency, and origin documentation. North American retailers source year-round through Sunkist's cooperative structure, blending California summer fruit with imported winter supply.
- Food Service:Restaurant and hospitality procurement prioritizes shelf-life stability and case-price efficiency over origin branding.
- Exporters:Re-export traders arbitrage seasonal windows between Southern and Northern Hemisphere supply.
Procurement volume clusters with Retail; Juice Producers are climbing the fastest.
Distribution Channel:
Channel application determines cold-chain intensity and documentation requirements from packing house to final delivery.
- Supermarkets:Corporate produce buyers mandate blockchain traceability and real-time temperature logging compliant with EU F-Gas Regulation. Spanish logistics operators serving Valencia terminals retrofit refrigerated fleets to hydrofluorocarbon-phase-down schedules.
- Direct Sales:Grower-to-processor contracts eliminate intermediary margins for juice producers with dedicated acid-profile requirements. California Central Valley packing houses deploy near-infrared spectroscopy at intake to verify contract specifications inline.
- Wholesalers:Traditional auction structures in Mediterranean growing regions aggregate smallholder supply for export consolidation.
- Online Retail:E-commerce platforms in China's domestic citrus trade compress distribution layers to 48-hour harvest-to-door delivery.
Supermarkets dominate current volume; Online Retail shows the steepest expansion trajectory.
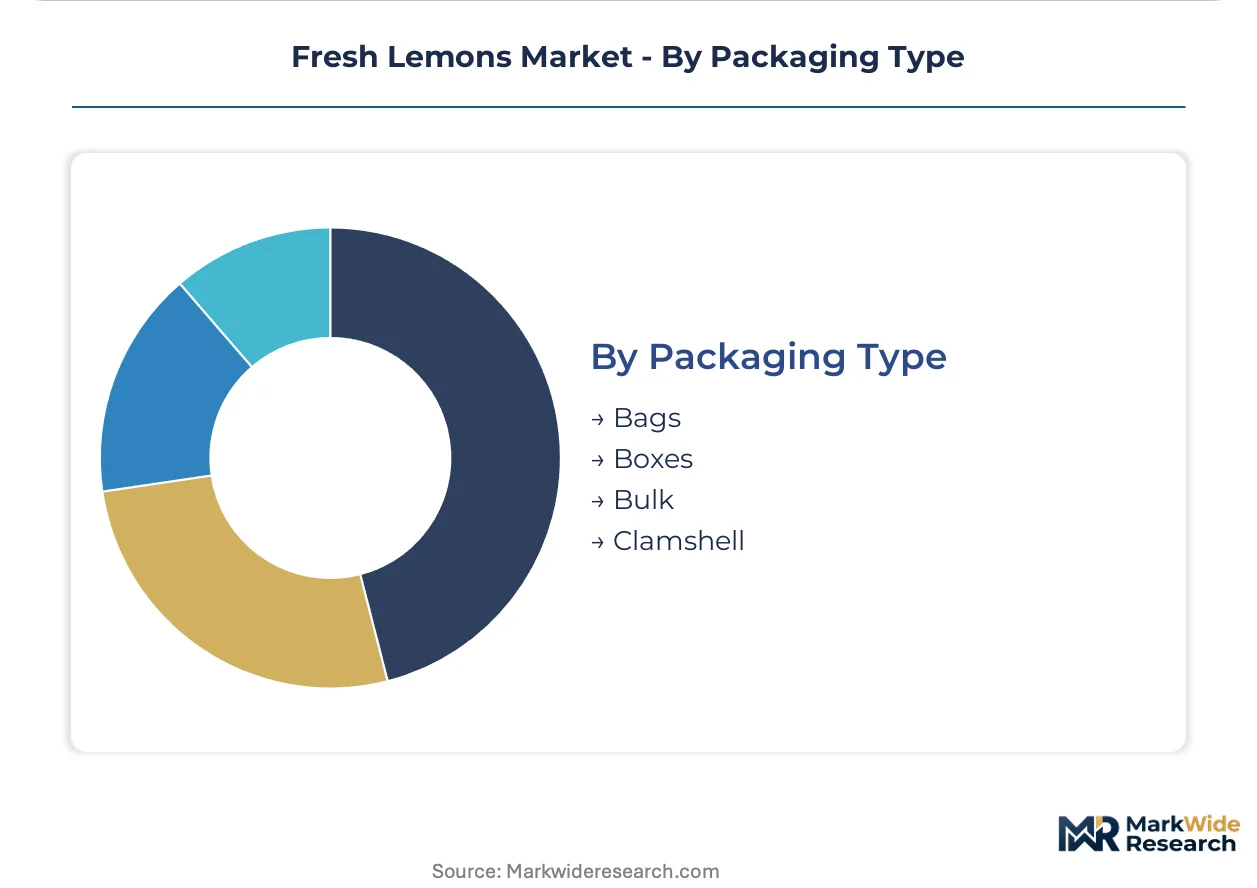
Packaging Type:
Packaging customer type separates bulk commodity movements from consumer-facing unit configurations.
- Bulk:Loose fruit in ventilated bins serves juice processors and re-exporters with minimal handling stages. Mediterranean cooperatives load bulk shipments at Valencia and Murcia terminals for transatlantic cold-chain transport.
- Boxes:Standardized corrugated containers balance protection with stackability for wholesale distribution.
- Clamshell:Rigid transparent packaging protects individual fruit for premium retail display.
- Bags:Mesh or perforated plastic sacks target value-oriented retail and food-service segments.
Bulk placements anchor processor supply; Clamshell configurations gain share fastest in specialty retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Murcia and Valencia in Spain anchor Mediterranean fresh lemon production, with the Segura River basin irrigation infrastructure supporting export-grade fruit for European juice processors and North American retail channels.
Spain
Valencia packing houses contract directly with cold-pressed beverage bottlers for acid-profile specifications. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs across refrigerated export fleets serving Mediterranean terminals. Murcia cooperatives deploy near-infrared spectroscopy at intake to verify titratable acidity for flavor house contracts.
United States
California's Central Valley supplies year-round organic and conventional grades through Sunkist's cooperative structure. The FDA's Food Safety Modernization Act mandates traceability systems for microbial testing of imported citrus. Kern County packing sheds face natural gas price volatility affecting heated post-harvest washing operations.
Argentina
Tucumán province offers counter-seasonal organic supply for North American retailers seeking winter availability. The country's national agricultural regulator oversees phytosanitary certification for Mediterranean fruit fly mitigation. San Miguel de Tucumán processors are expanding flavedo-layer procurement for essential oil distillation alongside juice extraction.
China
Domestic e-commerce platforms compress harvest-to-door delivery to 48 hours for urban consumers. The country's national food safety authority enforces standards for citrus trade through wholesale and direct channels. Sichuan and Yunnan growing regions supply Laoyishengxian with speed-to-shelf distribution competing on logistics rather than origin branding.
Italy
Sicily and Calabria heritage varieties target premium culinary channels with limited-harvest positioning. REACH compliance requirements filter post-harvest treatment registrations for European juice producer qualification. Catania processors balance essential oil distillation with conventional juice yield contracts.
Fresh Lemons Market Competitive Landscape
Direct contracting dominates the current landscape as juice producers bypass traditional wholesale auctions. The vendor base splits between century-old agricultural cooperatives, vertically integrated organic specialists, and e-commerce-native distributors. Three archetypes define positioning: origin-branded cooperatives with year-round availability, certified organic operators controlling farm-to-retail relationships, and platform-based traders competing on logistics velocity. Competitive intensity centers on acid-profile consistency and cold-chain compliance rather than price alone.
Within the cooperative archetype, Sunkist anchors North American retail sourcing through seasonal blending of domestic and imported supply. Organic Mountain exemplifies the certified-tier specialist with direct relationships in California's Central Valley. Laoyishengxian occupies the platform-native position in China's domestic trade, compressing distribution layers for urban delivery speed.
| Leading Market Players |
|---|
| Fairview Orchards |
| Organic Mountain |
| Sunkist |
| Laoyishengxian |
| Sanniti |
| Melissa's Produce |
| TastePadThai |
| Kaiying Trading |
| Fruit World |
| Others |
Pricing and Supply Chain Analysis
Natural gas price benchmarks in California's Central Valley cascade through post-harvest washing and waxing operations, compressing margins for conventional grades while organic premiums absorb cost volatility through direct retailer contracts.
Pricing Analysis
Certified organic status bundled with blockchain traceability commands premium positioning against unbundled conventional supply. Three-tier pricing structure across organic, conventional, and value-added grades separates procurement budgets by certification investment and acid-profile verification. Price differentiation hinges on titratable acidity consistency and flavedo-layer essential oil concentration for flavor house contracts. Juice producers demonstrate lowest price sensitivity due to acid-profile specificity, while food-service buyers prioritize case-price efficiency over origin documentation.
Supply Chain Analysis
Single-source vulnerability sits with Spain's Murcia and Valencia export corridors, where Segura River basin irrigation disputes and citrus greening vector pressure threaten Mediterranean supply continuity. Raw material flows draw from Argentine Tucumán organic acreage, California Central Valley cooperative structures, and Italian Sicily heritage varieties. Tariff exposure through emerging Asian phytosanitary barriers creates bonded cold-storage bottlenecks. Distribution runs through direct grower-to-processor contracts for juice specification compliance, bypassing traditional wholesale auction structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
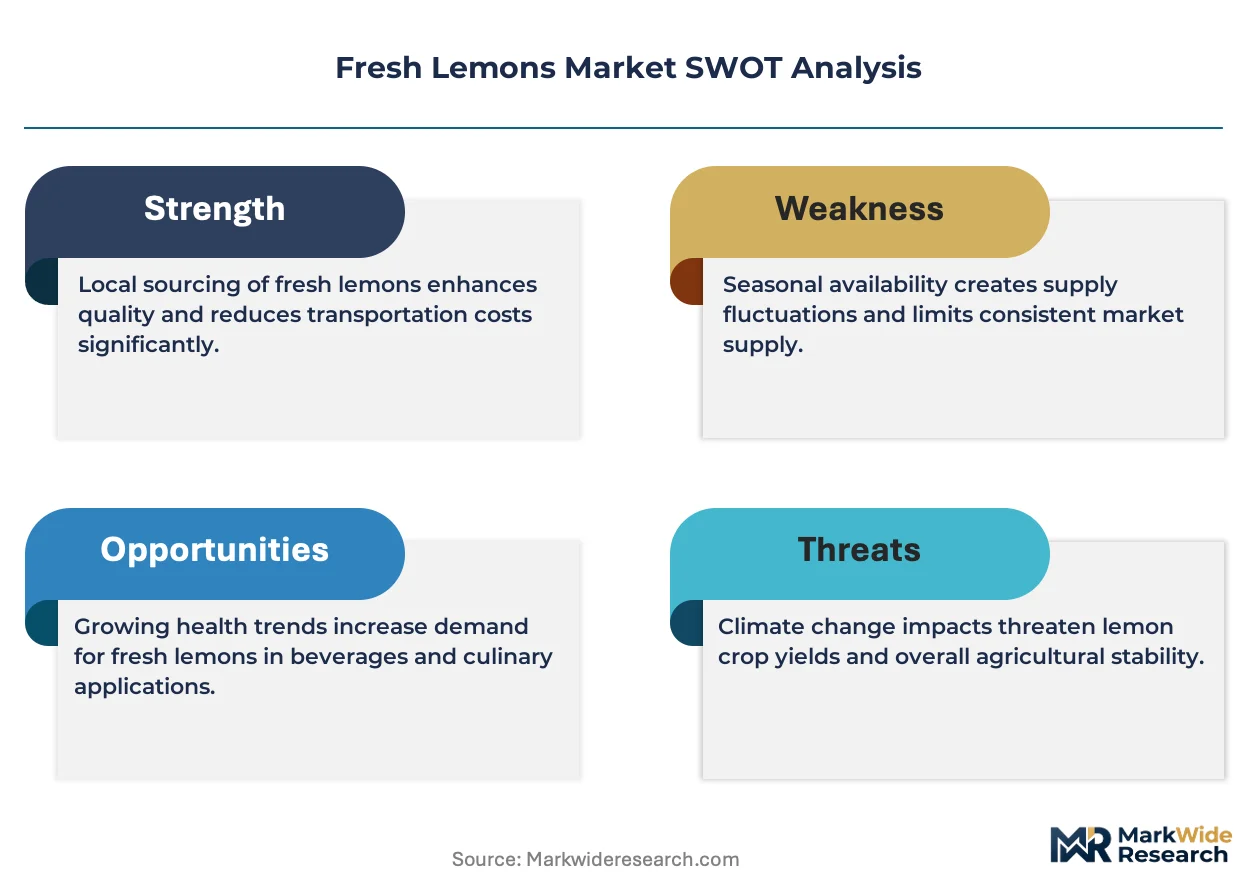
Fresh lemon supply operates under hard capacity constraints, with certified organic acreage expansion lagging contract demand from North American retailers and cold-pressed beverage bottlers.
For Market Incumbents: Hedge against Segura River basin irrigation volatility by securing counter-seasonal supply agreements with Argentine Tucumán processors. Deepen backward integration into California Central Valley packing infrastructure to control post-harvest acid-profile verification through near-infrared spectroscopy deployment. For New Entrants and Emerging Players: Enter via China's domestic e-commerce citrus trade, where Laoyishengxian's logistics velocity model remains replicable for origin-labeled speed-to-shelf positioning. Target underpenetrated organic certification in Italian Calabria heritage varieties for premium culinary channel penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size Spanish logistics operators facing EU F-Gas Regulation compliance capex burdens in Valencia export corridors. Long-term viability centers on cold-chain asset ownership with refrigerated fleet retrofit capabilities. Watch Mediterranean fruit fly quarantine protocol extensions as inventory-holding cost inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Packing Infrastructure | California Central Valley spectroscopy deployment reduces contract rejection rates for juice producers. |
| Counter-Seasonal Supply Agreement | Argentine Tucumán organic acreage anchors North American winter SKU availability. |
| Blockchain Traceability Implementation | German and Dutch retailers mandate orchard-to-shelf documentation for organic tier positioning. |
| Refrigerated Fleet Retrofit Program | EU F-Gas Regulation hydrofluorocarbon phase-down compliance enables continued Valencia terminal access. |
| Direct E-Commerce Platform Launch | China's 48-hour harvest-to-door logistics compression displaces traditional wholesale layers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fresh lemon market assessment. Primary interviews with juice procurement directors, citrus cooperative managers, refrigerated logistics operators, and specialty grocery category buyers validated supply chain cost structures. USDA grading standards documentation, EU F-Gas Regulation compliance databases, and FDA Food Safety Modernization Act traceability filings supplemented trade flow analysis. Bottom-up acreage and yield estimates triangulated against top-down consumption projections across certification tiers.
Data-stream reconciliation merged production surveys from Murcia and Valencia cooperatives with import manifests at North American retail distribution centers. Segmentation modeling tracked product type, end-user category, distribution channel, and packaging format across the projection horizon. CAGRs derived from volume-weighted growth rates in organic certification expansion and cold-pressed juice extraction demand. Climate volatility indices and phytosanitary certification timelines fed scenario-based forecast adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended Mediterranean fruit fly quarantine protocols and natural gas price spikes in California packing operations. Deviation in EU F-Gas Regulation enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Apple Concentrate Market