
 APAC Frozen Fruits and Vegetables Market | 2026-2036
APAC Frozen Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Frozen Fruits and Vegetables Market Outlook
Food service buyers is bifurcating from retail and household segments as the dominant demand archetype across APAC. Nichirei Corporation leverages its integrated cold-chain network to dominate Japanese institutional supply. Olam International anchors procurement volumes through direct farm partnerships in Thailand and Vietnam. Ajinomoto Co., Inc. differentiates via specialized frozen vegetable blends tailored to quick-service restaurant specifications.
Frozen fruits and vegetables comprise produce subjected to rapid temperature reduction, typically to minus eighteen degrees Celsius or below, followed by controlled storage to arrest enzymatic degradation and preserve nutritional content for extended distribution. The category serves industrial food manufacturing, food service preparation, and retail consumer channels requiring year-round ingredient consistency regardless of harvest seasonality. The berries segment within product type captures premium margin pools due to concentrated antioxidant demand and limited fresh-season availability in tropical APAC climates. Food service within end user represents the fastest-expanding consumption channel, driven by quick-service restaurant chain proliferation across Indonesia, Philippines, and Vietnam. Pouches within packaging type are gaining share against rigid formats, reflecting e-commerce fulfillment requirements and reduced logistics cube.
FSSAI in India enforces frozen food safety labeling and contaminant thresholds that determine import eligibility for foreign suppliers. China's SAMR and GB standards mandate specific microbiological limits and origin documentation that shape product formulation and sourcing decisions for market entrants. Australia's FSANZ maintains parallel standards that influence cross-Tasman trade flows with New Zealand. Stakeholders must monitor divergence between national frozen food codes as regulatory fragmentation becomes a decisive factor in regional expansion planning.
Market Dynamics
Cold-chain infrastructure maturation across Southeast Asia is consolidating procurement authority into fewer food service operators with direct supplier relationships, compressing traditional distributor margins while expanding contract farming arrangements.
Growth Catalysts
- Quick-service restaurant expansion:Chains across Indonesia, Philippines, and Vietnam are standardizing frozen vegetable specifications to ensure year-round menu consistency regardless of local harvest cycles.
- FSSAI compliance harmonization:India's frozen food safety labeling and contaminant threshold enforcement is creating import eligibility clarity that accelerates foreign supplier market entry.
- Blast freezing technology:Advanced rapid temperature reduction systems are preserving cellular structure in tropical fruits, enabling premium export positioning for Thai and Vietnamese processors.
Market Restraints
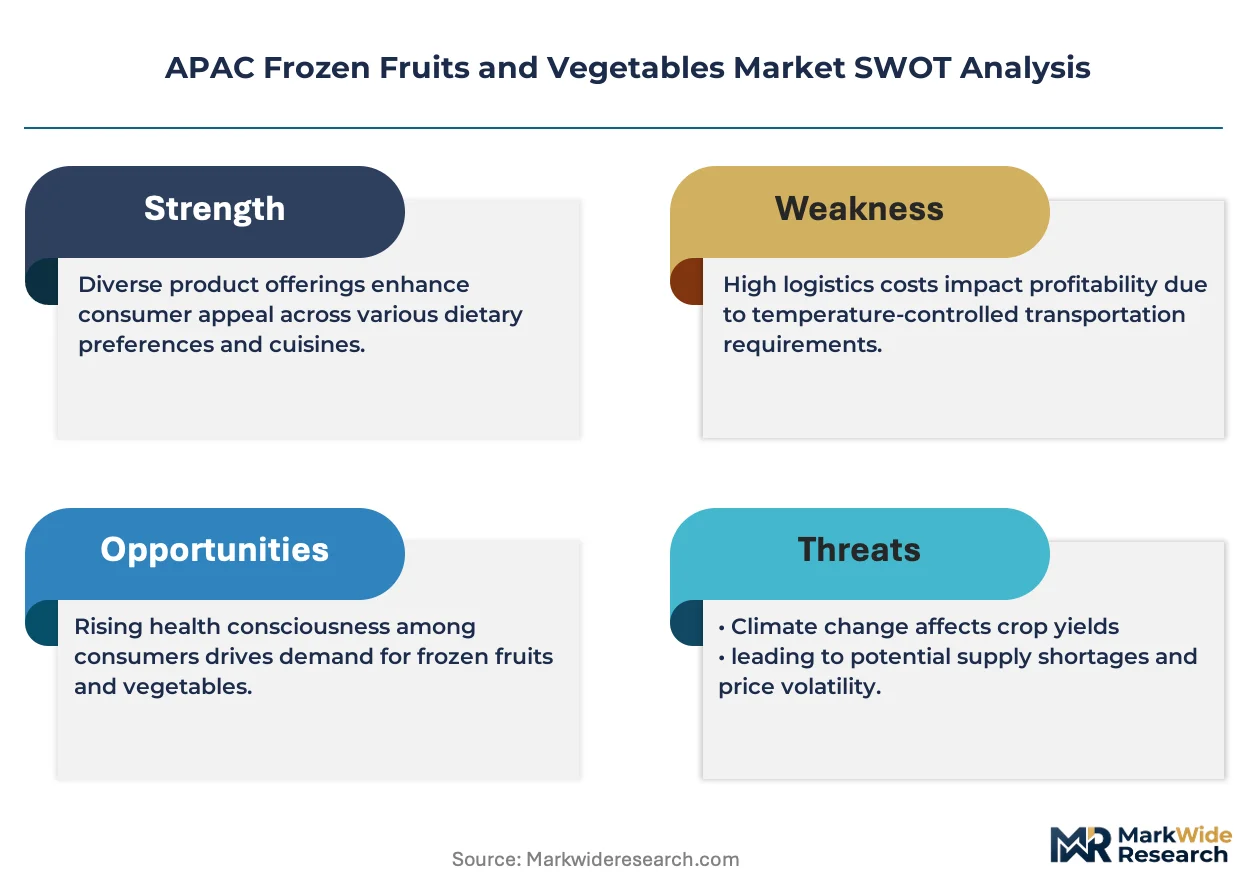
- Energy cost volatility:Diesel-powered refrigerated transport and electricity-intensive cold storage operations expose margins to fossil fuel price swings across archipelagic Southeast Asian markets.
- Import documentation fragmentation:Divergent microbiological limits and origin certification requirements between China's SAMR, India's FSSAI, and Australia's FSANZ create compliance redundancy costs.
- Fresh produce substitution:Wet-market vegetable availability in price-sensitive Indian tier-2 cities limits frozen adoption among household segments despite modern trade expansion.
Strategic Opportunities
- E-commerce fulfillment formats:Pouch packaging configurations optimized for last-mile delivery are capturing share from rigid formats in Vietnam's urban corridor online grocery channels.
- Antioxidant-positioned berries:Limited fresh-season blueberry and raspberry availability in tropical climates creates year-round premium positioning for frozen imports in Malaysian and Singaporean retail.
- Direct farm partnerships:Bypassing aggregator layers through captive sourcing in Thailand's Central Plains and Vietnam's Mekong Delta secures volume commitments and traceability documentation.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration system maintenance and temperature monitoring expertise remains concentrated in metro hubs, constraining rural distribution network reliability.
- Multi-jurisdiction label compliance:Simultaneous adherence to China's updated GB standards, India's FSSAI rules, and Japan's JIS requirements demands specialized regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Frozen Fruits and Vegetables Market |
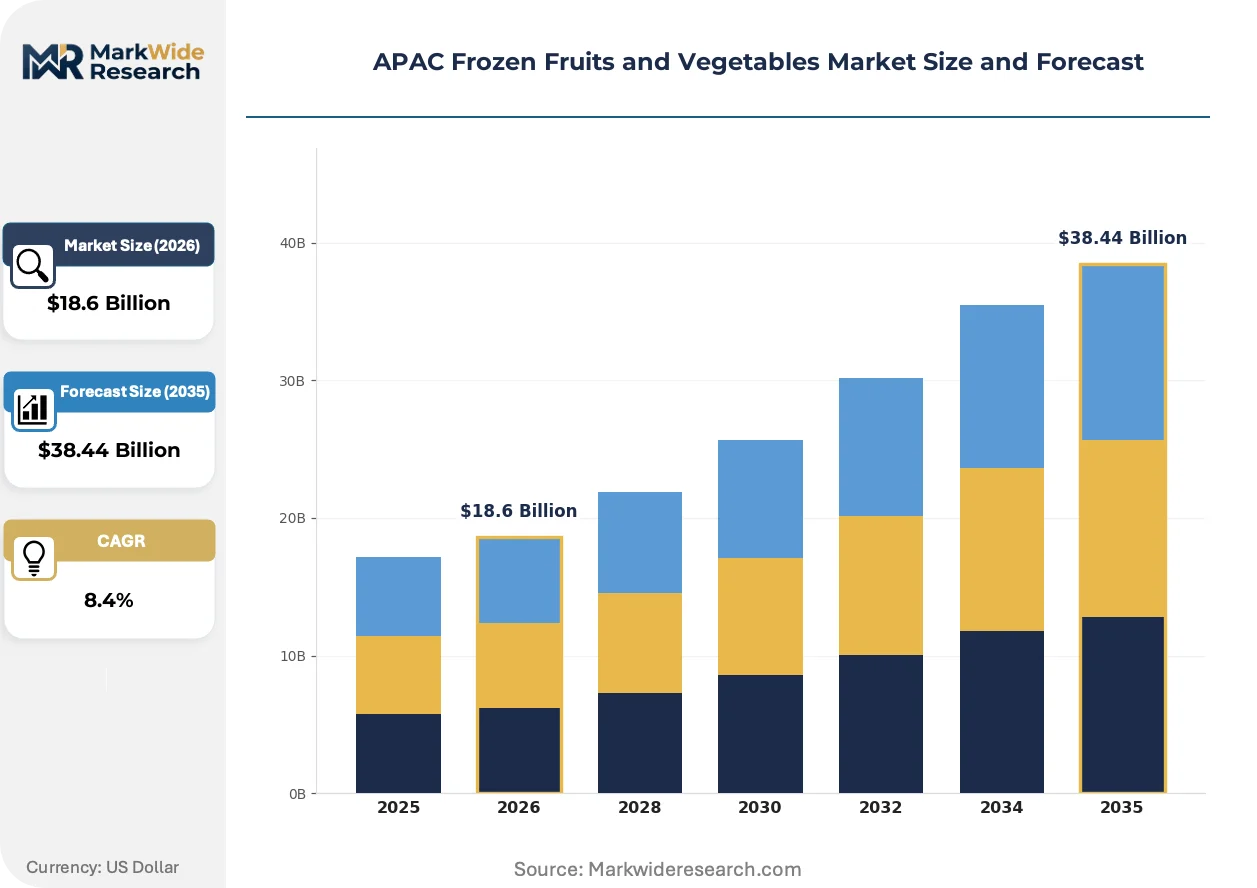
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berries, Peas, Carrots, Spinach End User: Food Service, Retail, Households, Processing Packaging Type: Bags, Boxes, Cartons, Pouches Distribution Channel: Supermarkets, Online, Wholesale, Convenience Stores |
| Companies Covered | Nichirei Corporation, Olam International, Dole Food Company, Ardo NV, General Mills Inc., Nestlé S.A., Conagra Brands Inc., Ajinomoto Co., Inc., Simplot Australia Pty Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Frozen Fruits and Vegetables Market Strategic Shifts
Processing technology and packaging formats are converging to address shelf-life extension and logistics efficiency simultaneously, while regulatory divergence is forcing suppliers toward modular compliance architectures rather than single-standard formulations.
Individual quick freezing technology with fluidized bed configurations is supplanting traditional block freezing in Southeast Asian processing facilities. Food manufacturers in Thailand and Vietnam are adopting IQF systems to preserve discrete piece identity for industrial ingredient applications. This shift is compressing commodity pricing power while enabling specification-grade premium tiers based on clump-free flowability and moisture retention metrics.
China's SAMR has tightened microbiological limits and mandated enhanced origin documentation for frozen vegetable imports under revised GB standards. Foreign suppliers are reformulating blanching protocols and intensifying laboratory testing to meet the new thresholds. Japanese and South Korean exporters with established testing infrastructure are capturing share from newer entrants facing certification timeline delays.
Quick-service restaurant chains are consolidating procurement through direct supplier contracts rather than distributor intermediaries. This pattern is most visible in Indonesia's Java corridor and the Philippines' Luzon region, where centralized commissary operations are displacing fragmented local purchasing. Suppliers with integrated cold-chain networks and national distribution licenses are securing multi-year volume commitments at the expense of regional brokers.
APAC Frozen Fruits and Vegetables Market Segmentation
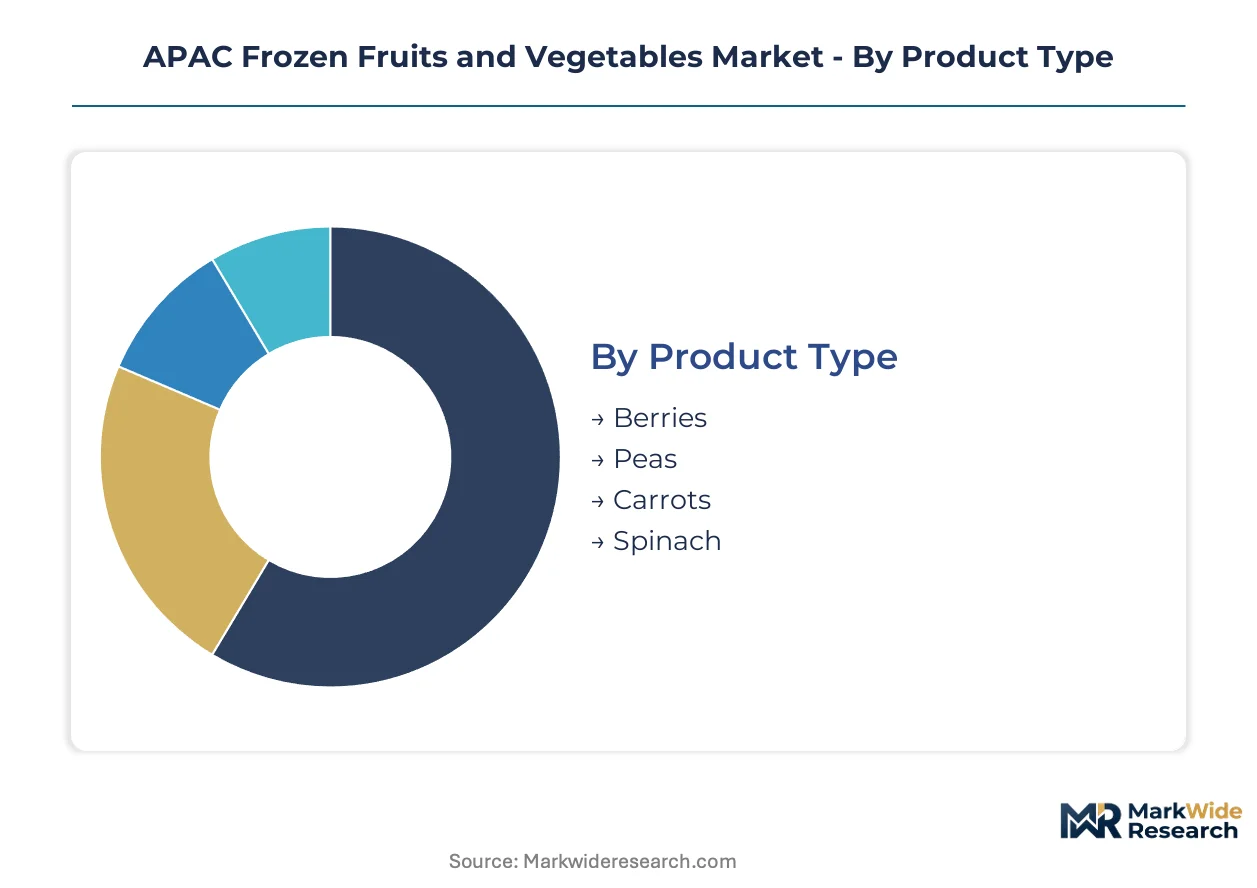
Segmentation in frozen produce determines channel access and margin capture. Product type dictates cold-chain intensity. Packaging format shapes e-commerce viability. End-user concentration drives contract structure and volume commitment terms.
Product Type:
Berries command premium positioning through food service and retail channels. Peas and carrots flow predominantly into institutional procurement. Spinach serves niche health-positioned retail segments with specialized packaging requirements.
- Berries:Rapid individual quick freezing preserves cellular integrity for antioxidant-rich applications. Quick-service restaurant chains in Indonesia and Vietnam standardize frozen blueberry and raspberry specifications for year-round smoothie menu consistency.
- Peas:Blanching and blast freezing arrest enzymatic activity while maintaining bright coloration for visual appeal. Institutional commissaries across Thailand's Central Plains and Vietnam's Mekong Delta concentrate procurement volumes for standardized ingredient applications.
- Carrots:Diced and sliced configurations serve industrial food manufacturing with uniform cooking properties.
- Spinach:Leaf integrity preservation through controlled freezing supports premium retail positioning in urban Indian modern trade formats.
Peas dominate installed base through commodity scale. Berries is where expansion concentrates.
End User:
Cost tier separation distinguishes contract-volume institutional buyers from price-sensitive household segments. Food service operators leverage direct supplier relationships. Retail channels intermediate between processors and consumers. Household penetration remains constrained by wet-market substitution in tier-2 Indian cities.
- Food Service:Centralized commissary operations in Indonesia's Java corridor and the Philippines' Luzon region consolidate procurement authority. Quick-service restaurant chains mandate specification-grade frozen vegetable blends with documented cold-chain custody from farm to fryer.
- Retail:Modern trade formats in India's urban corridors displace traditional wet-market purchasing through convenience positioning and safety assurance labeling.
- Households:Price sensitivity and fresh produce availability limit adoption outside metro India and developed Southeast Asian markets.
- Processing:Industrial food manufacturers in Thailand and Vietnam source commodity-grade frozen vegetables for ingredient applications requiring thermal stability and moisture retention.
Food Service commands volume concentration. Retail channels represent the steepest expansion trajectory.
Packaging Type:
Margin structure separates rigid formats from flexible configurations optimized for logistics cube reduction. E-commerce fulfillment requirements accelerate pouch adoption. Wholesale channels maintain box and carton preference for palletized handling efficiency.
- Pouches:Stand-up and flat configurations reduce shipping cube while enabling portion-controlled dispensing. Vietnam's urban online grocery channels capture share fastest from rigid formats through last-mile delivery optimization.
- Bags:Polyethylene configurations serve commodity retail with cost-efficient barrier properties against freezer burn.
- Boxes:Corrugated containment supports wholesale distribution with stacking strength for palletized logistics.
- Cartons:Retail-ready presentation formats with graphic panels serve premium positioning in Malaysian and Singaporean supermarket frozen sections.
Boxes dominate wholesale infrastructure. Pouches is where e-commerce positioning concentrates.
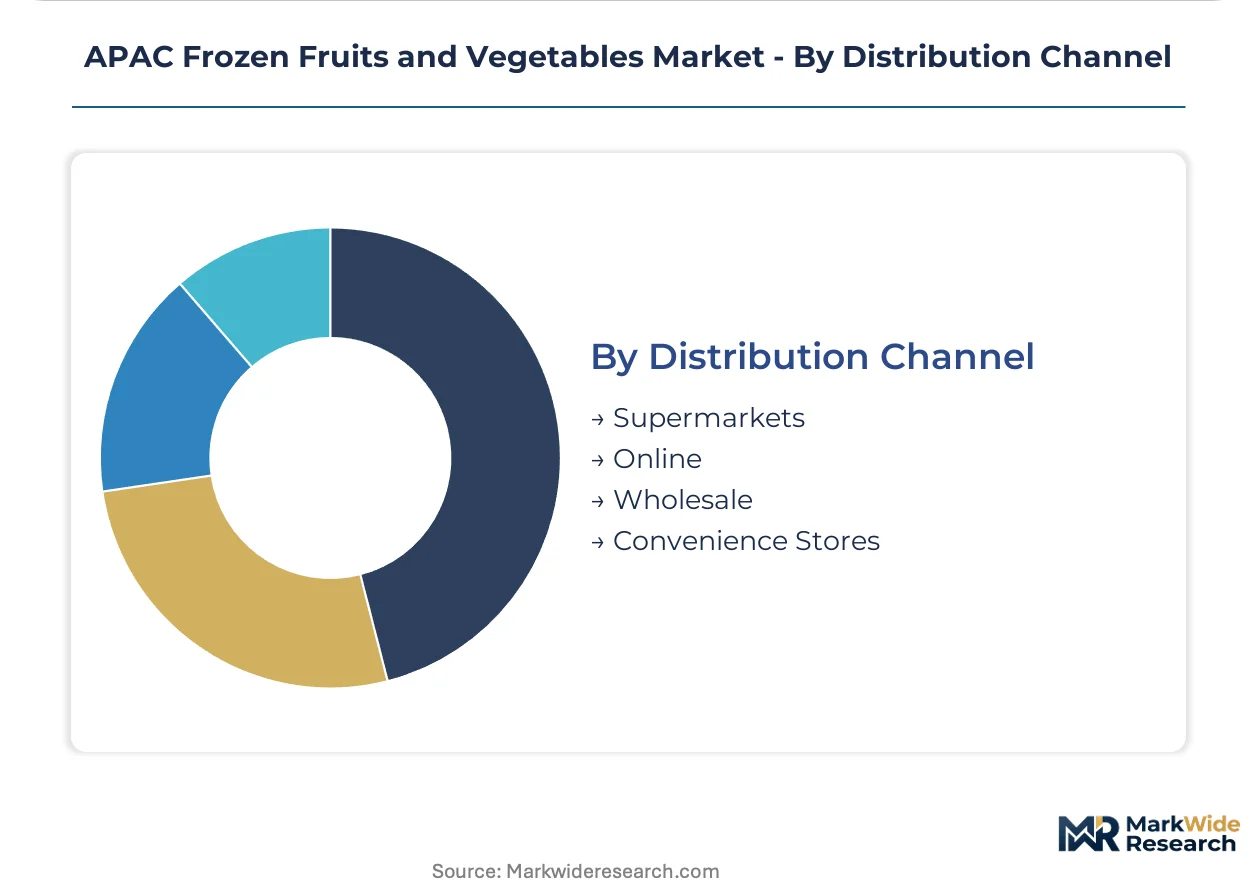
Distribution Channel:
Geographic reach determines channel viability across archipelagic Southeast Asian markets with fragmented cold-chain coverage. Supermarkets anchor urban penetration. Online channels exploit mobile commerce adoption. Wholesale serves institutional volume with direct delivery contracts.
- Supermarkets:Frozen section expansion in India's modern trade formats and Southeast Asian urban retail corridors provides temperature-controlled display infrastructure for branded frozen produce.
- Online:Mobile commerce platforms in Vietnam and Indonesia leverage third-party cold-chain logistics for frozen grocery fulfillment with delivery-time guarantees.
- Wholesale:Cash-and-carry operators and dedicated frozen food distributors serve food service and processing accounts with pallet-scale transactions.
- Convenience Stores:Limited frozen section footprint restricts assortment depth to high-velocity SKUs in urban Japanese and South Korean markets.
Wholesale channels dominate volume throughput. Online distribution is where channel experimentation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang Deep Sea Port's cold-chain connectivity underwrites Thailand's role as a regional frozen produce export hub, linking Mekong Delta processing clusters to East Asian consumer markets.
China
Quick-service restaurant chains in Shanghai and Guangzhou are standardizing frozen vegetable procurement specifications. SAMR's revised GB standards mandate enhanced microbiological testing and origin documentation for import eligibility. Yangtze River Delta processing zones near Suzhou are retrofitting blast freezing capacity to meet export compliance thresholds.
India
Modern trade formats in Mumbai and Delhi-NCR are displacing wet-market purchasing through branded frozen produce availability. FSSAI labeling and contaminant threshold enforcement creates import eligibility clarity for foreign suppliers. Maharashtra's Nashik-Satara corridor is consolidating contract farming arrangements for frozen pea and carrot processing.
Japan
Institutional food service operators in Tokyo and Osaka are consolidating procurement through direct supplier relationships. JIS standards and METI cold-chain guidelines shape domestic distribution infrastructure requirements. Chubu region processing facilities near Nagoya are upgrading IQF technology for premium berry exports.
Vietnam
E-commerce grocery platforms in Ho Chi Minh City are accelerating pouch packaging adoption for last-mile frozen fulfillment. The country's national food safety authority enforces HACCP-aligned protocols for export-oriented processing facilities. Mekong Delta freezing plants near Cần Thơ are expanding blast capacity for tropical fruit value-added processing.
Indonesia
Centralized commissary operations in Jakarta and Surabaya are displacing fragmented local purchasing for quick-service restaurant chains. The national food and drug regulator mandates cold-chain custody documentation for frozen import shipments. Java corridor distribution hubs are consolidating procurement authority into fewer operator-direct supplier relationships.
APAC Frozen Fruits and Vegetables Market Competitive Environment
Concentration sits with integrated cold-chain operators and direct farm partnership networks rather than fragmented distributor layers. The market structure favors players with captive sourcing infrastructure and multi-jurisdiction compliance capacity. Three archetypes dominate: Japanese institutional suppliers with integrated logistics, Southeast Asian farm-direct processors, and multinational food manufacturers with brand equity. Competitive moves center on backward integration into contract farming and modular compliance architectures for regulatory divergence.
Within the integrated logistics tier, Nichirei Corporation and Ajinomoto Co., Inc. exemplify cold-chain dominance and specification-grade product positioning respectively. Olam International anchors the farm-direct procurement archetype through Southeast Asian sourcing relationships. These three occupy positions that reflect the market's bifurcation between infrastructure-heavy institutional supply and traceability-driven export processing.
| Leading Market Players |
|---|
| Nichirei Corporation |
| Olam International |
| Dole Food Company |
| Ardo NV |
| General Mills Inc. |
| Nestlé S.A. |
| Conagra Brands Inc. |
| Ajinomoto Co., Inc. |
| Simplot Australia Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
Blast freezing capacity utilization across Thailand's Central Plains and Vietnam's Mekong Delta shapes both supply concentration and price floors, as processors with captive cold-chain infrastructure extract margin premiums while smaller operators face volume-driven price compression from food service procurement consolidation.
Pricing Analysis
Volume-discount tiering structures separate food service contract pricing from spot retail transactions, with specification-grade IQF berries commanding premium positioning against commodity block-frozen vegetables. Price differentiation rests on certification tier (FSSAI compliance for India entry, SAMR GB standards for China) and cold-chain custody documentation completeness. Cost compression in economy-tier peas and carrots is intensifying because diesel-powered refrigerated transport exposes margins to fossil fuel volatility. Household segments in India's tier-2 cities exhibit highest price sensitivity, while quick-service restaurant chains in Indonesia and Vietnam prioritize specification consistency over unit cost.
Supply Chain Analysis
Laem Chabang Deep Sea Port cold-chain connectivity underwrites Thailand's regional export hub status, linking Mekong Delta processing clusters to East Asian consumer markets. Geographic supply concentrates in Thailand, Vietnam, and China's Yangtze River Delta processing zones. Raw material dependencies include diesel fuel for refrigerated transport, electricity for blast freezing operations, and polyethylene for flexible pouch packaging. Single-source vulnerability runs through archipelagic Southeast Asian markets where cold-chain technician scarcity constrains rural distribution reliability. Distribution runs through centralized commissary operations in Indonesia's Java corridor and the Philippines' Luzon region, displacing fragmented local purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quick-service restaurant procurement platformization is creating ecosystem interoperability requirements around specification documentation and cold-chain custody verification, favoring suppliers with integrated data architectures over fragmented distributor networks.
For Market Incumbents: Shield contract farming arrangements in Thailand's Central Plains and Vietnam's Mekong Delta through multi-year volume commitments with traceability documentation that satisfies divergent FSSAI, SAMR, and FSANZ requirements. Prioritize backward integration into captive blast freezing capacity to defend margin position against energy cost volatility and food service buyer consolidation. For New Entrants and Emerging Players: Lead with antioxidant-positioned berry segments in Malaysian and Singaporean retail channels where limited fresh-season availability creates year-round premium positioning whitespace. Target e-commerce fulfillment partnerships in Vietnam's urban corridor with pouch-optimized packaging configurations. Anchor go-to-market strategy through direct farm partnerships that bypass aggregator layers and secure HACCP-aligned export certification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated cold-chain operators with modular compliance architectures for regulatory divergence between China's SAMR, India's FSSAI, and Australia's FSANZ. Long-term viability over the projection horizon rests on acquisition targets with captive sourcing infrastructure in Southeast Asian processing clusters and established laboratory testing capacity for microbiological threshold compliance. The signal to monitor is FSSAI enforcement intensity in India's urban retail corridors as modern trade format expansion accelerates import eligibility clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Blast freezing capacity additions in Thailand and Vietnam secure volume commitments from quick-service restaurant chains requiring documented custody from farm to fryer. |
| Direct Farm Partnership Consolidation | Bypassing aggregator layers through captive sourcing in the Mekong Delta and Central Plains intensifies traceability documentation for multi-jurisdiction compliance. |
| Modular Compliance Architecture Investment | Simultaneous adherence to SAMR GB standards, FSSAI labeling rules, and FSANZ requirements demands specialized regulatory affairs capacity for market entry. |
| E-Commerce Fulfillment Format Adaptation | Pouch packaging configurations optimized for last-mile delivery capture share from rigid formats in Vietnam's urban online grocery channels. |
| IQF Technology Upgrade | Individual quick freezing with fluidized bed configurations preserves discrete piece identity for industrial ingredient applications in Thai and Vietnamese processing facilities. |
Study Parameters
A spread of perspectives from food service procurement directors, cold-chain logistics operators, frozen food processing plant managers, regulatory affairs specialists at import-dependent suppliers, and modern trade category buyers converged on the working assumptions. Primary interviews across these stakeholder roles combined with secondary validation through FSSAI compliance bulletins, SAMR GB standard updates, customs and trade data from ASEAN member states, and cold-chain infrastructure investment disclosures. Bottom-up volume modeling from processing facility capacities and top-down demand estimation from quick-service restaurant expansion trajectories were triangulated to establish forecast ranges.
Segmentation dimensions modeled include product type (berries, peas, carrots, spinach), end user (food service, retail, households, processing), packaging format (pouches, bags, boxes, cartons), and distribution channel (supermarkets, online, wholesale, convenience stores) across the analysis window. CAGRs were derived from trend extrapolation of cold-chain infrastructure investment cycles and quick-service restaurant procurement consolidation patterns. Forecast inputs incorporated diesel price volatility assumptions for refrigerated transport and electricity cost trajectories for blast freezing operations.
Forecasts assume regulatory continuity in India's FSSAI enforcement regime, China's SAMR import documentation requirements, and Australia's FSANZ standards; material policy shifts in microbiological limits or labeling mandates would require re-modeling. Practitioners should keep alternative scenarios live as cold-chain technician scarcity constraints and energy cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Canada Fruits and Vegetables Market
Fruits and Vegetables
Fruit Punnet Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Global Garcinia Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market