
 Global Fresh Fruits and Vegetables Market | 2026-2036
Global Fresh Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
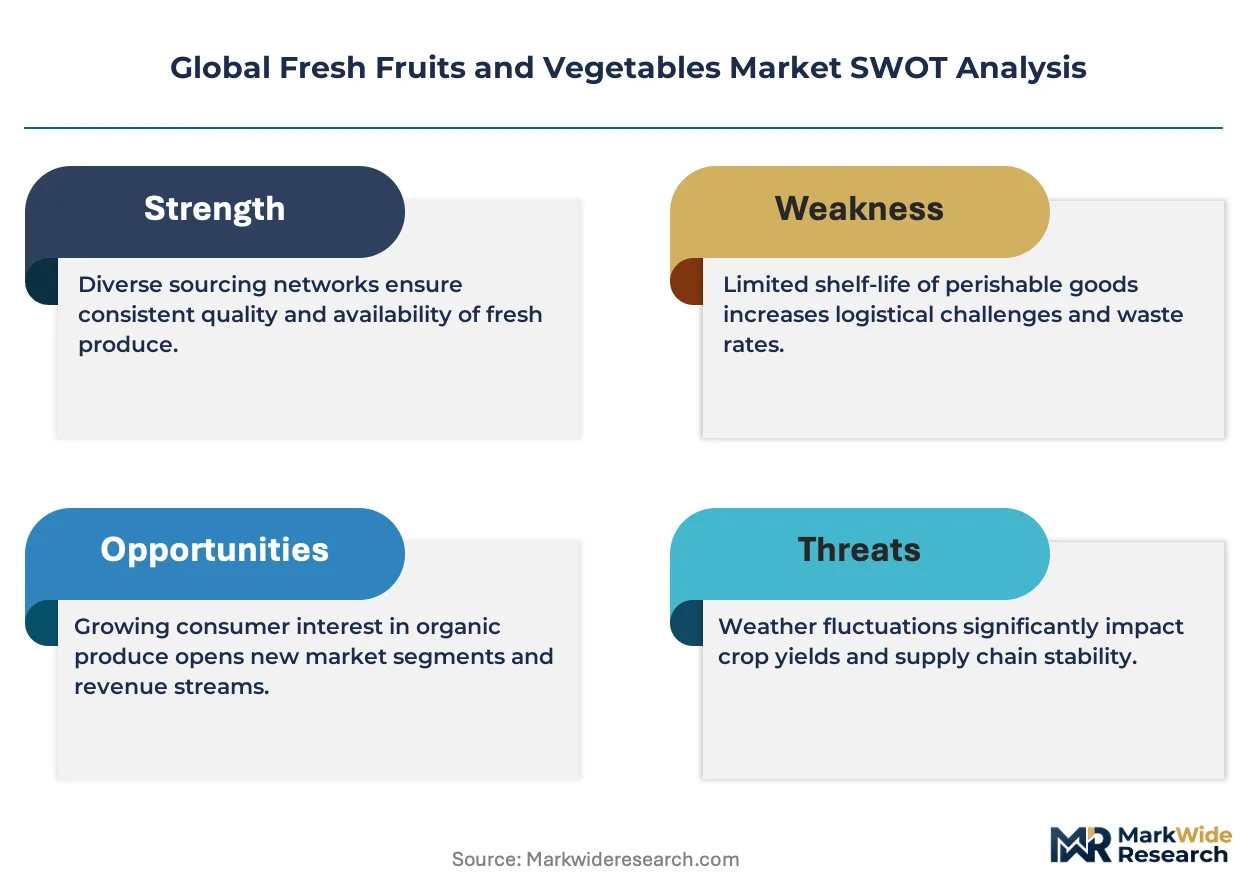
Global Fresh Fruits and Vegetables Market Analysis
Fresh-cut processing revenue is fragmenting across regional packers and specialty operators as retailers build direct farm relationships. Dole Food Company leverages its integrated plantation network to sustain year-round supply consistency across tropical and temperate zones. Taylor Farms competes through precision-controlled wash-and-pack automation that anchors its position in the North American bagged salad category. Driscoll's differentiates via proprietary berry genetics that command premium shelf placement in conventional and organic channels.
Fresh fruits and vegetables comprise unprocessed or minimally processed plant tissues harvested at physiological maturity, with respiration rates, ethylene sensitivity, and moisture content determining cold-chain requirements from field to consumer. The primary commercial purpose centers on delivering safe, nutritious, and sensorially acceptable produce to households and food service operations while minimizing post-harvest loss. Fruits occupy the dominant value pool within product type segmentation, though microgreens generate the highest margin per kilogram through restaurant and direct-to-consumer channels. Online retailers represent the fastest-expanding distribution channel, while supermarkets retain volume leadership through private-label fresh programs and localized sourcing partnerships.
EU Green Deal farm-to-fork standards, FDA Food Safety Modernization Act traceability mandates, and India's FSSAI packaging regulations collectively reshape compliance burdens and market access conditions for cross-border produce trade. These frameworks accelerate investment in digital chain-of-custody systems and pressure smaller growers toward cooperative aggregation models. Stakeholders must monitor evolving pesticide maximum residue limits and carbon border adjustment mechanisms to preserve export eligibility and retail authorization.
Market Dynamics
EU Green Deal farm-to-fork standards are compressing supply chain transparency timelines while India's organized retail expansion pulls procurement away from traditional wet markets. These dual pressures force growers toward digital traceability investments and direct retailer relationships.
Growth Catalysts
- EU Green Deal farm-to-fork standards:Mandatory digital chain-of-custody documentation accelerates investment in blockchain-enabled traceability systems across Mediterranean and Northern European supply bases.
- Urban household channel migration in India:Organized retail penetration in Mumbai, Delhi, and Bangalore creates demand for standardized grading, pre-packaging, and cold-chain logistics previously absent in wet market procurement.
- Precision-controlled wash-and-pack automation:North American bagged salad processors deploy sensor-driven sorting and modified atmosphere packaging to extend shelf life and reduce retail shrink.
Market Restraints
- Input cost volatility in fertilizer and agricultural chemicals:Phosphate and nitrogen price swings compress margin predictability for open-field vegetable growers in Spain and Italy.
- Supply concentration risk in proprietary berry genetics:Controlled varietal licensing limits grower switching and concentrates premium shelf access with genetics holders.
- Regulatory friction from FDA Food Safety Modernization Act traceability mandates:Compliance documentation burdens disproportionately impact small-scale Mexican and Central American exporters serving US food service channels.
Strategic Opportunities
- Underpenetrated direct-to-consumer microgreens channels in Germany:Restaurant and home-delivery subscription models command highest margin per kilogram with minimal cold-chain infrastructure versus leafy greens.
- Carbon border adjustment mechanism alignment:Early certification against EU carbon intensity benchmarks secures preferential retail authorization as 2026 implementation approaches.
- Controlled environment agriculture convergence with renewable energy:Vertical farms in the Netherlands integrate surplus wind power to stabilize year-round tomato and cucumber supply independent of seasonal field production.
Industry Challenges
- Post-harvest physiology skill scarcity:Respiration rate management and ethylene sensitivity protocols require specialized training unavailable in emerging supply bases across Southeast Asia and North Africa.
- Cold-chain capex intensity for smallholder aggregation:Pre-cooling and refrigerated transport investments exceed cooperative balance sheet capacity in Indian and Kenyan export corridors.
- FSSAI packaging compliance timeline compression:India's rapid regulatory evolution forces simultaneous reformulation of film specifications and label declarations across multiple product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fresh Fruits and Vegetables Market |
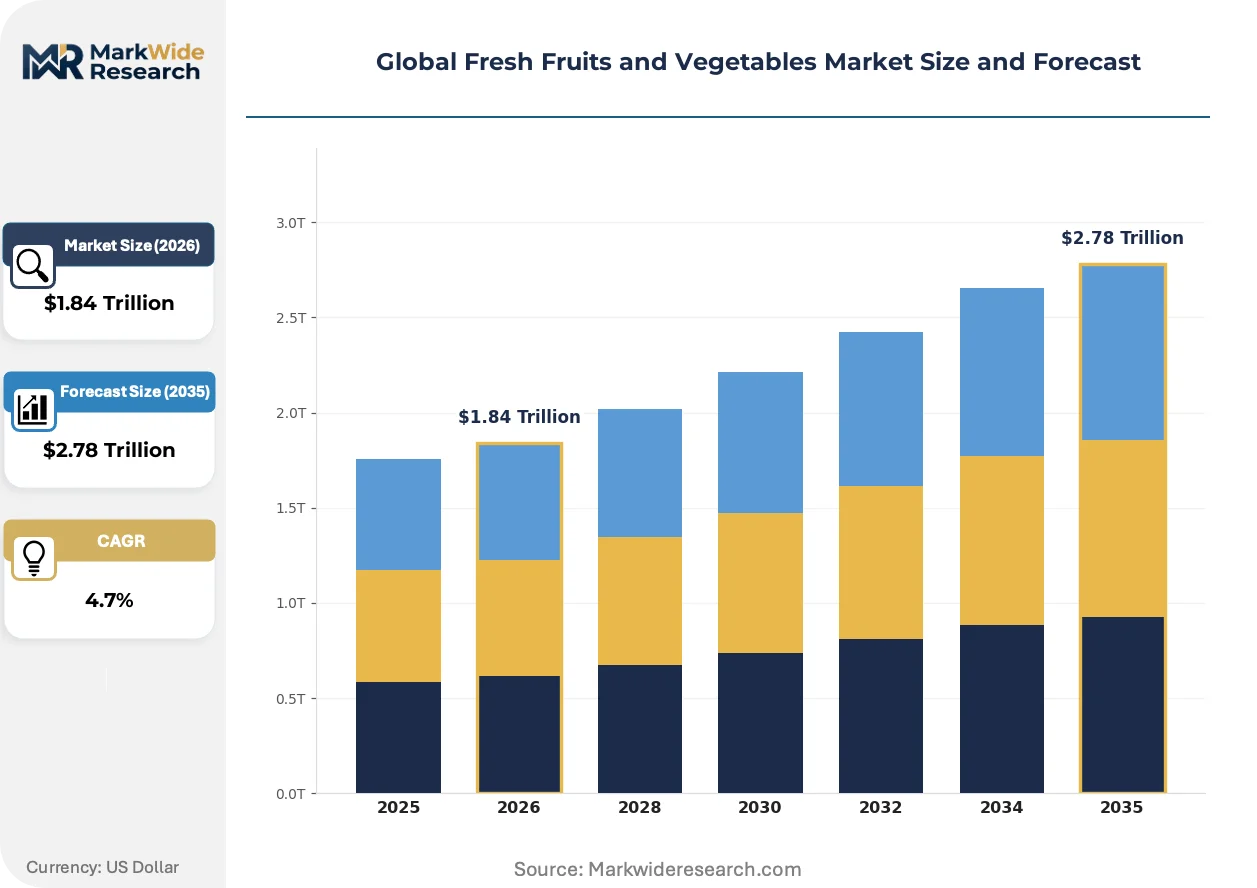
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $2.78 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Herbs, Microgreens Distribution Channel: Supermarkets, Farmers' Markets, Online Retailers, Convenience Stores End User: Households, Food Service, Retailers, Wholesalers Packaging Type: Bulk, Pre-Packaged, Net Bags, Baskets |
| Companies Covered | Total Produce, Taylor Farms, Dole Food Company, Driscoll's, Ocean Mist Farms, Chiquita Brands International, Bonduelle, Calavo Growers, Fresh Del Monte Produce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fresh Fruits and Vegetables Market Emerging Trajectories
Digital traceability infrastructure and controlled environment production methods are compressing traditional field-to-shelf timelines while reshaping buyer-seller contracting structures. These shifts favor capital-intensive operators with captive data systems.
Hyperspectral imaging and AI-driven defect detection is migrating from high-value berry sorting into mainstream apple and citrus packing operations. North American and European fresh-cut processors deploy these systems to reduce manual inspection labor and standardize defect thresholds. The technology is migrating from premium tier applications toward mid-market private-label programs as hardware costs decline and cloud-based model training accelerates deployment cycles.
EU F-Gas Regulation phase-down schedules are accelerating adoption of transcritical CO2 refrigeration in Dutch and Spanish cold storage and distribution centers. Industrial consequence includes retrofit cost concentration among mid-scale operators lacking balance sheet capacity for system replacement. Berry and avocado exporters serving Northern European retailers face compressed compliance timelines as contractor availability tightens ahead of 2030 phase-out milestones.
Food service procurement consolidation around menu transparency requirements is displacing spot market purchasing with multi-year direct farm contracts. Large contract caterers and quick-service chains in the United Kingdom and France now require documented variety provenance and pesticide application records as standard tender conditions. This pattern is most visible in tomato and leafy green categories where traceability failures trigger immediate supplier disqualification.
Global Fresh Fruits and Vegetables Market Segmentation
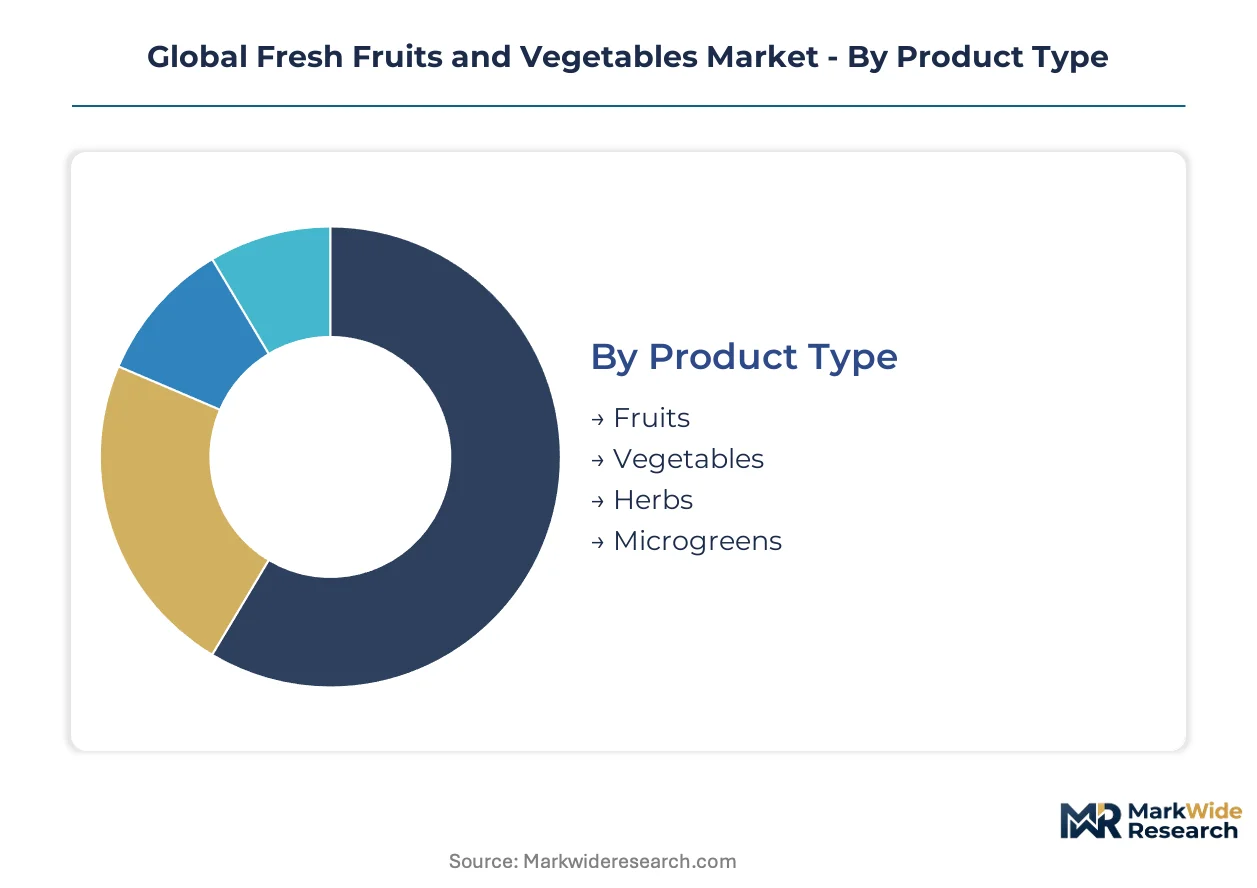
Segmentation in fresh produce markets tracks how cold-chain requirements, shelf-life sensitivity, and buyer procurement power reshape margin distribution across channel and packaging configurations. Understanding these divides exposes where capital investment concentrates and where cooperative aggregation models compete.
Product Type:
Mature categories dominate revenue tonnage while emerging segments command premium positioning through controlled environment production and direct-to-consumer channels.
- Fruits:Respiration rates and ethylene sensitivity vary dramatically across climacteric categories, mandating differentiated cold-chain protocols from harvest through retail. Demand concentrates in India, where urban households shifting from wet markets toward organized retail create volume pull for standardized grading and pre-packaging.
- Vegetables:Leafy greens and brassicas require precision-controlled humidity management to prevent moisture loss and tissue degradation during extended distribution. EU Green Deal farm-to-fork standards are compressing transparency timelines for field vegetables sourced from Mediterranean supply bases.
- Herbs:Highly perishable foliage with accelerated respiration drives demand for rapid-turn inventory management in food service procurement.
- Microgreens:Restaurant and home-delivery subscription models in Germany deliver the highest margin per kilogram with minimal infrastructure versus conventional leafy greens.
Fruits retain volume leadership; microgreens hold the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain operators from asset-light spot market intermediaries.
- Supermarkets:Private-label fresh programs and localized sourcing partnerships anchor volume throughput, with shrink reduction driving investment in sensor-driven inventory management. Retail authorization increasingly depends on documented chain-of-custody compliance under EU and FDA traceability mandates.
- Online Retailers:Last-mile cold-chain configuration and dynamic slotting algorithms enable rapid assortment expansion beyond traditional store-based distribution economics. Urban household penetration in Mumbai, Delhi, and Bangalore accelerates demand for pre-packaged formats and standardized quality grades.
- Farmers' Markets:Direct producer-consumer relationships minimize intermediation costs but limit scale and seasonality coverage.
- Convenience Stores:Grab-and-go fresh snack formats drive localized procurement of pre-cut fruits and ready-to-eat vegetable portions.
Supermarkets retain volume leadership; online retailers gain share fastest.
End User:
Application-specific requirements separate food service traceability mandates from household convenience preferences.
- Households:Sensorially driven purchasing prioritizes visual quality indicators and convenience-oriented pre-packaging over bulk procurement. Channel migration in Indian urban centers shifts volume toward organized retail with standardized grading.
- Food Service:Menu transparency requirements under EU Green Deal standards and FDA Food Safety Modernization Act traceability mandates displace spot market purchasing with multi-year direct farm contracts. Large contract caterers in the United Kingdom and France now require documented variety provenance as standard tender conditions.
- Retailers:Category management and private-label development drive backward integration into direct farm relationships and captive packing operations.
- Wholesalers:Consolidation and aggregation functions face margin compression as retailers build direct sourcing capabilities and digital platforms disintermediate traditional intermediaries.
Households retain volume leadership; food service holds the steepest expansion curve.
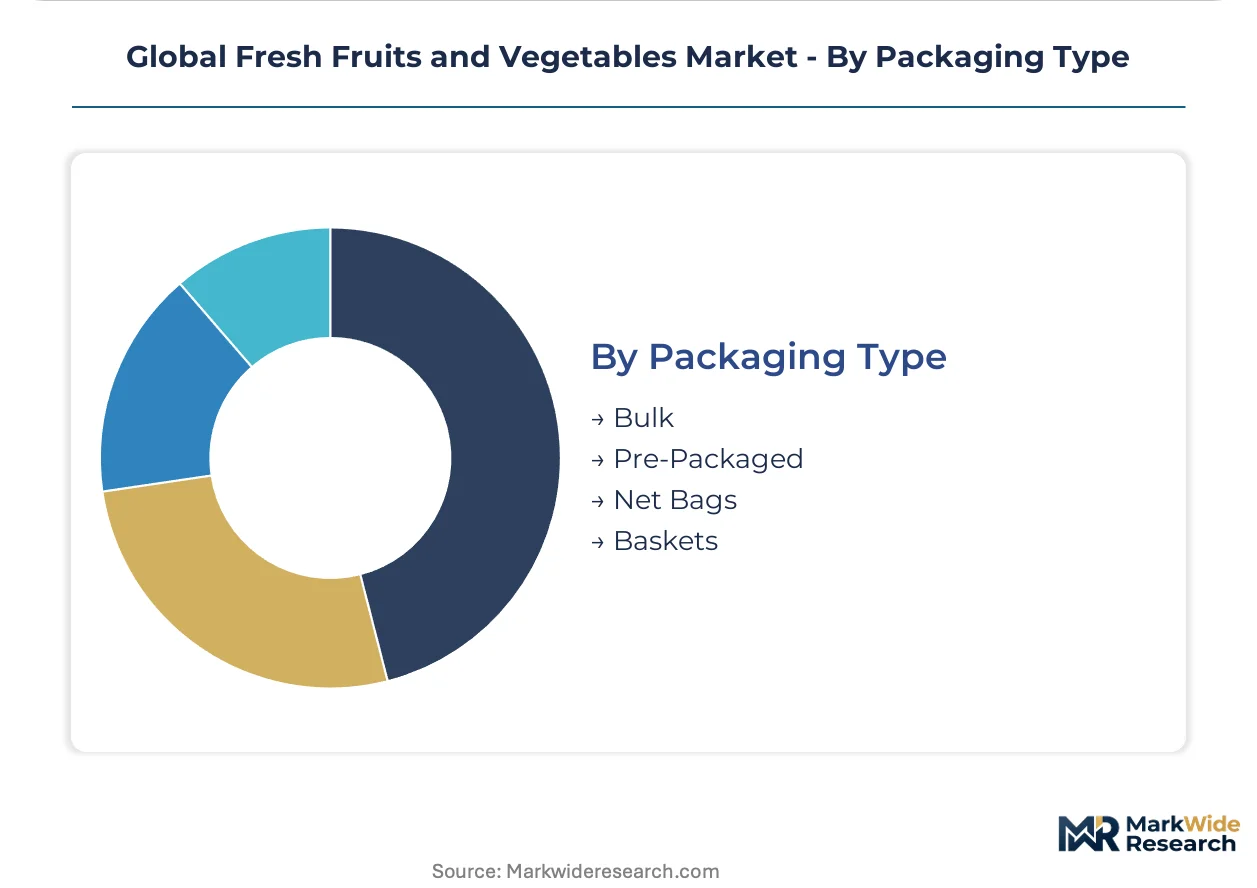
Packaging Type:
Customer type and margin structure separate institutional bulk procurement from premium pre-packaged retail formats.
- Pre-Packaged:Modified atmosphere packaging and breathable films extend shelf life while enabling standardized portion control for retail and food service channels. India's FSSAI packaging regulations force simultaneous reformulation of film specifications and label declarations across multiple product lines.
- Bulk:Minimal processing and reduced packaging cost serve institutional buyers and traditional wet market channels with price-sensitive procurement criteria. Cold-chain capex intensity for smallholder aggregation exceeds cooperative balance sheet capacity in Indian and Kenyan export corridors.
- Net Bags:Breathable mesh configurations balance ventilation with containment for root vegetables and citrus categories.
- Baskets:Reusable and biodegradable container formats serve farmers' market and direct-to-consumer channels with sustainability positioning.
Bulk retains volume leadership; pre-packaged climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresh produce consumption patterns diverge sharply between mature economies prioritizing convenience formats and emerging markets where channel migration from traditional wet markets drives structural transformation.
United States
Food service procurement consolidation and FDA Food Safety Modernization Act traceability mandates reshape supplier-retailer contracting. Large contract caterers now require documented variety provenance as standard tender conditions. California's Central Valley anchors domestic vegetable supply through direct farm relationships with national retail chains.
Germany
Restaurant and home-delivery subscription models for microgreens command premium positioning with minimal cold-chain infrastructure versus conventional leafy greens. EU F-Gas Regulation phase-down schedules accelerate transcritical CO2 refrigeration adoption in Dutch and Spanish cold storage serving German distribution. Berlin-Brandenburg clusters direct-to-consumer vertical farm operations integrating surplus renewable energy.
India
Urban households in Mumbai, Delhi, and Bangalore shift volume from wet markets toward organized retail with standardized grading and pre-packaging requirements. FSSAI packaging regulations force simultaneous reformulation of film specifications and label declarations across multiple product lines. Maharashtra and Karnataka anchor export corridor development through cooperative aggregation models.
Netherlands
Controlled environment agriculture convergence with renewable energy stabilizes year-round tomato and cucumber supply independent of seasonal field production. EU Green Deal farm-to-fork standards compress transparency timelines for vegetables sourced from Mediterranean supply bases. Westland region concentrates glasshouse operations with surplus wind power integration.
Spain
Phosphate and nitrogen price swings compress margin predictability for open-field vegetable growers serving Northern European retailers. EU carbon border adjustment mechanism alignment pressures early certification against intensity benchmarks ahead of 2026 implementation. Almería and Murcia anchor Mediterranean production with concentrated cold-chain investments for berry and avocado export.
Global Fresh Fruits and Vegetables Market Vendor Landscape
Capability concentration sits with genetics holders and integrated plantation operators; scale advantage sits with diversified fresh-cut processors and regional packers. The vendor base stratifies across three tiers: proprietary variety licensors commanding premium shelf access, vertically integrated plantation networks sustaining year-round supply consistency, and precision-automation packers anchoring private-label programs. Dominant competitive moves include direct farm relationship building to displace spot market intermediation, and backward integration into captive packing operations to secure retail authorization.
Within the integrated plantation tier, Dole Food Company and Fresh Del Monte Produce exemplify scale-driven supply consistency across tropical and temperate zones. Among precision-automation specialists, Taylor Farms occupies a position in North American bagged salad processing through sensor-driven operations. Driscoll's sits within the proprietary genetics tier, representing controlled varietal licensing that concentrates premium shelf access. These three anchors illustrate how capital intensity and captive data systems reshape buyer-seller contracting structures.
| Leading Market Players |
|---|
| Total Produce |
| Taylor Farms |
| Dole Food Company |
| Driscoll's |
| Ocean Mist Farms |
| Chiquita Brands International |
| Bonduelle |
| Calavo Growers |
| Fresh Del Monte Produce |
| Others |
Supply Flow & Price Mechanics
Mediterranean-to-Northern European reefer corridors anchor cost dynamics across the fresh produce value chain, concentrating pricing power with integrated plantation networks while fragmenting margin capture among spot-market intermediaries serving price-sensitive wet market channels in emerging economies.
Pricing Analysis
Long-term offtake contracts between Dutch glasshouse operators and German retail chains displace volatile spot procurement, stabilizing year-round tomato and cucumber supply pricing. Three-tier pricing structure across premium organic, standard conventional, and economy-grade categories differentiates by certification level and cold-chain integrity. Cost compression in open-field vegetable tiers intensifies because phosphate and nitrogen input volatility erodes margin predictability for Spanish and Italian growers. Food service buyers exhibit lowest price sensitivity due to menu transparency mandate compliance requirements, while traditional wet market households in India remain most price-responsive.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates risk calculus for avocado and berry exporters serving North American food service channels. Supply concentrates in Spain, the Netherlands, and India, with the Almería-Murcia corridor and Westland glasshouse region anchoring European vegetable throughput. Production draws from phosphate fertilizers, nitrogen-based crop inputs, and proprietary berry genetics licensing. Single-source vulnerability in controlled varietal access concentrates premium shelf placement with genetics holders like Driscoll's. Distribution runs through supermarket private-label programs, direct farm-retailer contracts, and emerging online retail platforms with last-mile cold-chain configuration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital traceability infrastructure and blockchain-enabled chain-of-custody systems are transforming fresh produce markets toward platform-economics dynamics, with interoperability between farm management software and retailer inventory systems becoming the critical ecosystem battleground.
For Market Incumbents: Harden defensibility by accelerating backward integration into captive packing operations and precision-controlled wash-and-pack automation. Taylor Farms' sensor-driven sorting investments illustrate how capital-intensive automation anchors private-label authorization against emerging regional packers. Secure retail shelf access through early EU carbon border adjustment mechanism certification ahead of implementation timelines.
For New Entrants and Emerging Players: Build out direct-to-consumer microgreens subscription models in underpenetrated German urban corridors, where restaurant and home-delivery channels command highest margin per kilogram with minimal cold-chain infrastructure versus conventional leafy greens. Target precision-automation packer partnerships as the most penetrable entry vector, leveraging cloud-based AI-driven defect detection hardware cost declines to standardize quality thresholds for mid-market private-label programs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-automation packers with sensor-driven operations and integrated plantation networks with renewable energy convergence. Long-term viability across the projection horizon rests on digital traceability infrastructure deployment and controlled environment agriculture scale. Acquisition target archetype: regional packers with direct farm relationships and blockchain-enabled chain-of-custody capabilities. Monitor EU F-Gas Regulation contractor availability tightening as inflection indicator for cold-storage retrofit capex concentration among mid-scale operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Packing | Secures retail authorization under EU Green Deal farm-to-fork traceability mandates. |
| Blockchain-Enabled Chain-of-Custody Deployment | Compresses transparency timelines for FDA Food Safety Modernization Act compliance. |
| Controlled Environment Agriculture Scale-Up | Stabilizes year-round supply independent of seasonal field production volatility. |
| Direct Farm-Retailer Contract Consolidation | Displaces spot market intermediation with multi-year provenance-documented offtake. |
| Carbon Border Adjustment Mechanism Certification | Secures preferential retail authorization as EU intensity benchmarks take effect. |
Methodological Framework
Desk research of customs and trade flow databases, EU regulatory filing repositories, and SEC 10-K disclosures preceded structured interviews with fresh-cut processing executives, supermarket category buyers, cold-chain logistics operators, and cooperative aggregation managers across Indian export corridors. Primary fieldwork combined with secondary validation from FSSAI regulatory circulars, FDA Food Safety Modernization Act guidance documents, and controlled environment agriculture operator disclosures. Bottom-up volume modeling triangulated against top-down value estimates across product type, distribution channel, and regional segmentation dimensions.
Assumptions held fixed include EU Green Deal implementation timelines, F-Gas Regulation phase-down schedules, and India's organized retail penetration curves, while fertilizer input cost volatility and carbon border adjustment mechanism enforcement intensity were varied across sensitivity scenarios. Segmentation modeling tracked product type, packaging configuration, distribution channel, and end-user application across the analysis window. CAGRs derived from historical volume trajectories adjusted for channel migration patterns and regulatory compliance investment cycles. Forecast inputs incorporated cold-chain capex intensity, proprietary genetics licensing concentration, and precision-automation hardware cost decline curves.
Practitioners should monitor EU carbon border adjustment mechanism enforcement intensity, F-Gas Regulation contractor availability, and India's FSSAI packaging compliance evolution for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Packaged Fresh Fruits Market