
 Water Chestnut Market | 2026-2036
Water Chestnut Market Size, Share, and Industry Trends Forecast 2026-2036
Water Chestnut Market Analytics
Asian grocery wholesale networks in North America and Europe are reshaping how water chestnut processors reach food manufacturers and restaurants. Guangxi Hualong Food Co., Ltd. leverages its southern China processing base to supply bulk frozen grades to export channels. Qingdao Dongsheng Foodstuffs Co., Ltd. anchors its position through integrated farming contracts across Shandong's freshwater aquaculture zones. Fujian Lixing Foods Co., Ltd. differentiates via vacuum-sealed retail formats targeting premium Asian supermarket chains.
Water chestnut (Eleocharis dulcis) is an aquatic corm crop harvested from shallow freshwater marshes, containing 2-3% protein and 16-20% starch by dry weight, valued for its crisp texture retention after thermal processing. The crop serves commercial food manufacturing as a texturizer in dim sum fillings, stir-fry blends, and canned vegetable mixes where structural integrity under high-heat cooking is essential. Canned water chestnuts dominate volume throughput due to shelf-stable logistics and institutional catering procurement patterns, while frozen formats capture expanding demand from quick-service Asian restaurant chains requiring consistent year-round supply. Direct sales channels to food manufacturers command margin premiums through customized sizing and brining specifications, whereas online retail remains nascent outside diaspora consumer segments.
China's SAMR enforces GB standards for aquatic vegetable heavy metal limits and geographic origin labeling, compelling processors to upgrade testing infrastructure or exit export eligibility. The USDA and FDA regulate U.S. import thresholds for canned and frozen water chestnuts, with phytosanitary certificates required from Chinese provincial agricultural authorities. Stakeholders must monitor tightening EU pesticide maximum residue limits under EFSA guidance, as these rules increasingly determine which Asian suppliers retain access to European food manufacturing contracts.
Market Dynamics
China's SAMR tightening of GB standards for heavy metal limits and geographic origin labeling is forcing aquatic crop processors to upgrade testing infrastructure or surrender export eligibility, compressing the supplier base toward integrated operations with captive farming contracts.
Growth Catalysts
- Quick-service Asian restaurant chains:North American operators are expanding year-round procurement of frozen formats for stir-fry and dim sum applications, creating consistent demand pull.
- GB standards compliance:Processors achieving SAMR certification gain preferential access to institutional catering contracts requiring documented traceability.
- Vacuum-sealed retail formats:Premium Asian supermarket chains in Europe and North America are differentiating shelf space with extended-shelf-life packaging for diaspora consumers.
Market Restraints
- Freshwater aquaculture zone concentration:Processing gravity centers on Guangdong province and the Pearl River Delta, creating geographic supply vulnerability to regional climate events.
- EFSA pesticide residue thresholds:Tightening EU maximum residue limits under EFSA guidance are disqualifying smaller Chinese processors from European food manufacturing contracts.
- Canned format substitution:Frozen water chestnuts are capturing quick-service demand at the expense of institutional canned procurement, pressuring legacy cannery capacity utilization.
Strategic Opportunities
- Direct-to-manufacturer channels:Customized sizing and brining specifications for food manufacturers command margin premiums over commodity wholesale.
- Shandong freshwater aquaculture expansion:Integrated farming contracts across northern China's aquaculture zones offer geographic diversification beyond the Pearl River Delta.
- Online retail diaspora penetration:E-commerce platforms serving Asian diaspora communities in Europe remain underdeveloped relative to established wholesale networks.
Industry Challenges
- Heavy metal testing infrastructure:SAMR compliance requires capital investment in laboratory equipment that smaller processors cannot finance.
- Phytosanitary certificate procurement:Chinese provincial agricultural authorities face administrative bottlenecks issuing USDA and FDA-required documentation for U.S. import clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Chestnut Market |
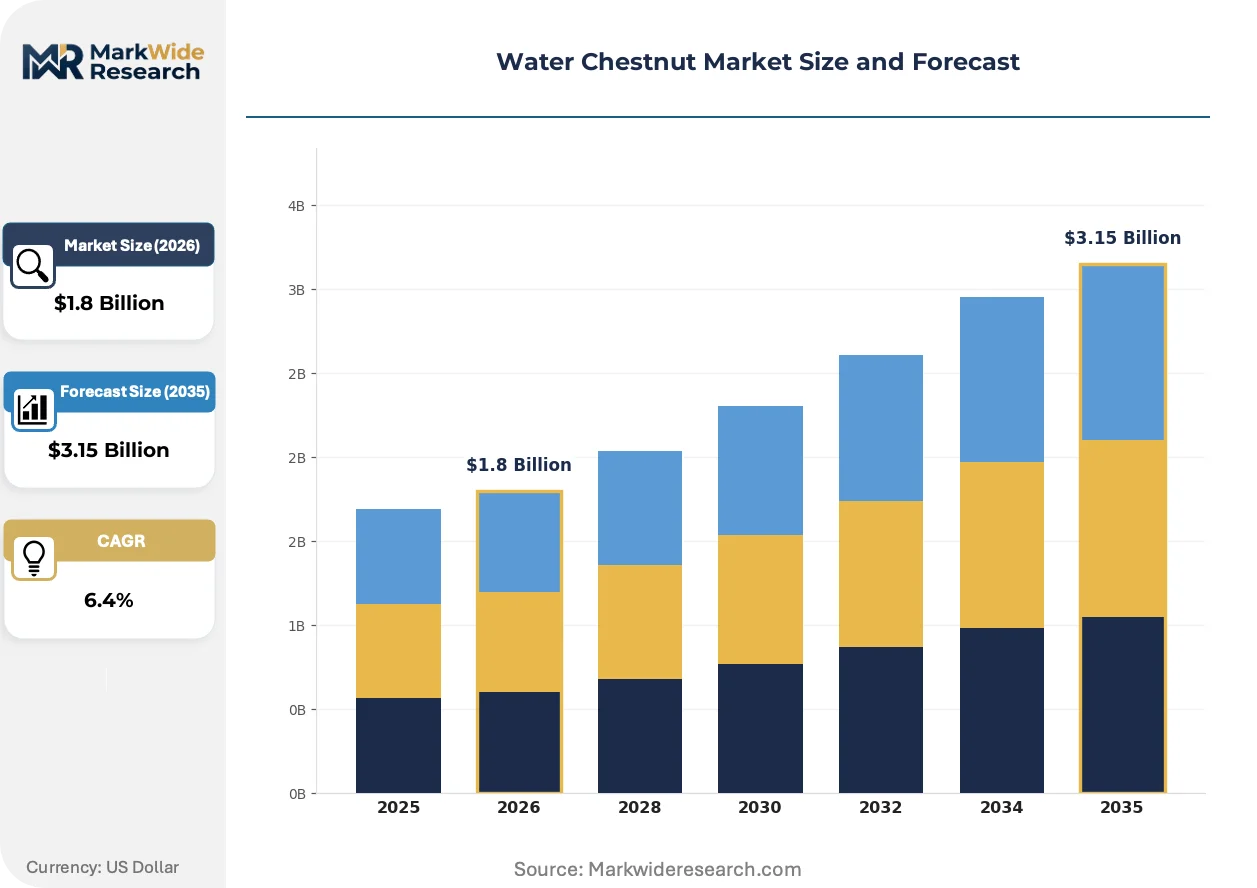
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Canned, Dried Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales End User: Restaurants, Households, Food Manufacturers, Caterers Packaging Type: Bags, Jars, Vacuum Sealed, Bulk |
| Companies Covered | Guangxi Hualong Food Co., Ltd., Qingdao Dongsheng Foodstuffs Co., Ltd., Qingdao Alliance Trading Co., Ltd., Dragon Enterprise Co., Ltd., Shandong Weifang Sansho Food Co., Ltd., Fujian Lixing Foods Co., Ltd., Baijia Food Group Co., Ltd., Cofco Tunhe Co., Ltd., Amoytop Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Chestnut Market Evolving Landscape
Processing technology and packaging formats are reshaping how water chestnut corms move from freshwater marshes to food manufacturing lines, with implications for texture retention, shelf stability, and regulatory compliance.
High-pressure processing systems for frozen water chestnut segments are rendering obsolete conventional blanching methods that compromised cellular structure. Quick-service Asian restaurant chains in North America are adopting these formats for consistent year-round supply. The technology is compressing demand toward processors with capital-intensive equipment, marginalizing small-batch operators.
EFSA guidance on pesticide maximum residue limits is tightening enforcement across European food manufacturing contracts. Processors must now maintain dual testing protocols—one for domestic Chinese distribution under SAMR GB standards, another for EU export eligibility. The frozen format segment faces the steepest compliance burden as European buyers demand batch-level documentation.
Asian grocery wholesale networks are consolidating procurement authority previously dispersed among independent restaurant suppliers. North American distributors now specify customized brining concentrations and corm sizing grades that bypass traditional commodity specifications. This concentration is most visible in Vancouver and Toronto, where diaspora population density supports dedicated cold-chain distribution infrastructure.
Water Chestnut Market Segmentation
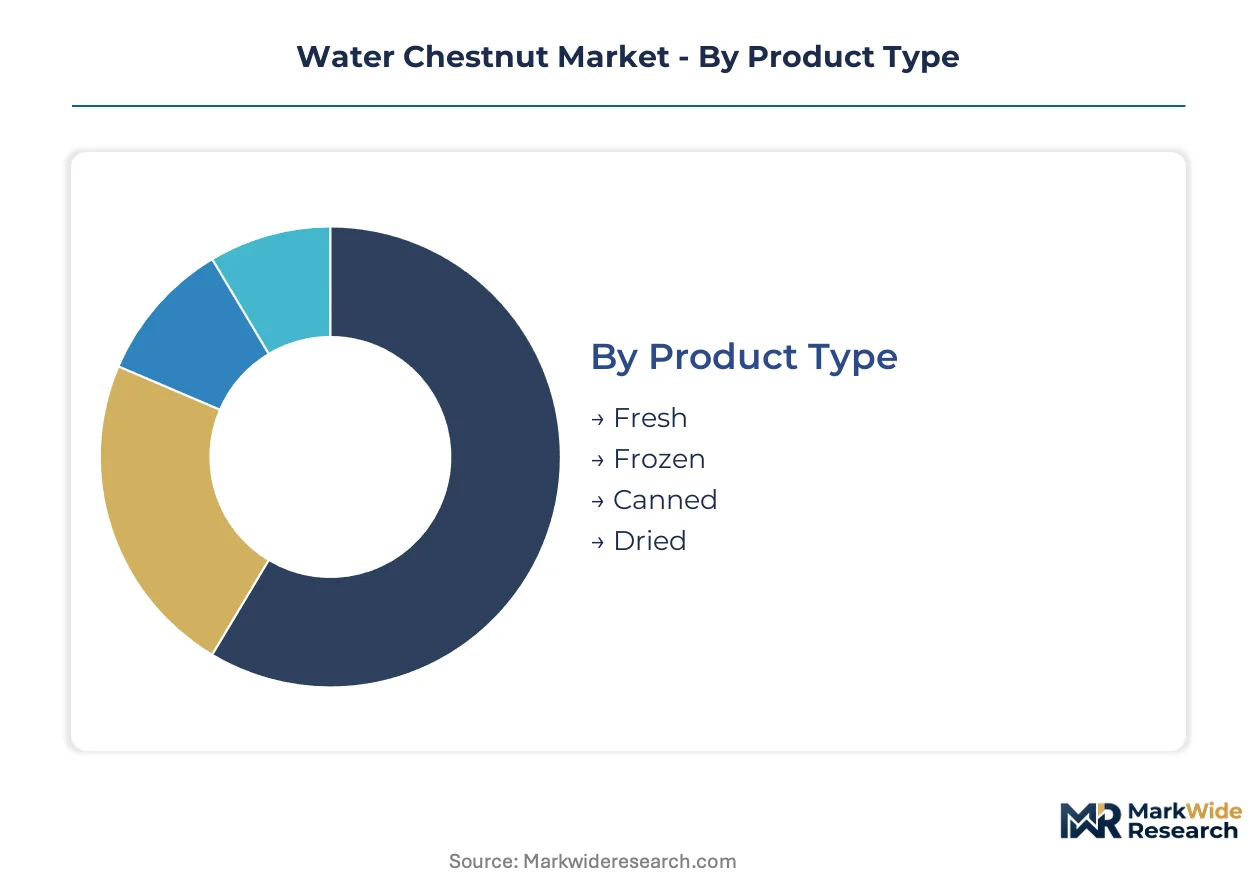
Water chestnut processors face divergent service requirements across product formats—frozen demands cold-chain reliability, canned requires shelf-stable logistics, while fresh needs rapid turnover. Segmentation reveals how procurement patterns split between institutional volume buyers and diaspora retail channels with distinct specification tolerances.
Product Type:
After-sales service intensity varies sharply: frozen formats demand temperature-monitoring partnerships, canned requires traceability documentation, while fresh hinges on spoilage arbitration.
- Canned:Heat-sterilized corms in brine solution deliver 24-36 month shelf stability through retort processing. Institutional catering contracts in the United States and Canada specify this format for inventory predictability, though quick-service chains are migrating toward frozen alternatives.
- Frozen:Individual quick-freezing preserves cellular structure for crisp texture retention in high-heat cooking. North American quick-service Asian restaurant chains are expanding year-round procurement of this format for stir-fry and dim sum applications.
- Fresh:Raw corms with 7-14 day shelf life serve specialty Asian supermarkets and restaurant prep kitchens in Vancouver and Toronto.
- Dried:Dehydrated slices target traditional medicine applications and diaspora households seeking extended pantry storage.
Canned holds the largest share; momentum sits with frozen.
Distribution Channel:
Channel selection maps to buyer scale and specification complexity—direct relationships reward customization, wholesale aggregates fragmented demand.
- Direct Sales:Processors negotiate customized brining concentrations and corm sizing grades with food manufacturers. These contracts command margin premiums through specification control unavailable in commodity wholesale.
- Wholesale:Asian grocery distribution networks in North America consolidate procurement authority previously dispersed among independent restaurant suppliers. Vancouver and Toronto's diaspora population density supports dedicated cold-chain infrastructure for frozen format aggregation.
- Supermarkets:Premium Asian supermarket chains in Europe and North America differentiate shelf space with vacuum-sealed retail formats for diaspora consumers.
- Online Retail:E-commerce platforms serving Asian diaspora communities remain underdeveloped relative to established wholesale networks, presenting whitespace for specialized entrants.
Wholesale captures the highest volume; direct sales deliver the steepest margin expansion.
End User:
User type dictates packaging format, order frequency, and compliance documentation burden—restaurants prioritize consistency, manufacturers demand traceability.
- Restaurants:Quick-service Asian chains in North America require frozen formats with batch-level documentation for year-round supply security. Independent operators mix fresh and canned based on menu complexity and storage constraints.
- Food Manufacturers:Dim sum and stir-fry blend producers specify frozen segments for structural integrity under thermal processing. SAMR certification and phytosanitary documentation are non-negotiable entry requirements.
- Households:Diaspora consumers in Europe and North America purchase vacuum-sealed retail formats through Asian supermarkets and emerging e-commerce channels.
- Caterers:Institutional catering procurement favors canned formats for shelf-stable logistics and inventory predictability in high-volume feeding operations.
Restaurants drive the steepest volume expansion; food manufacturers extract the highest specification premiums.
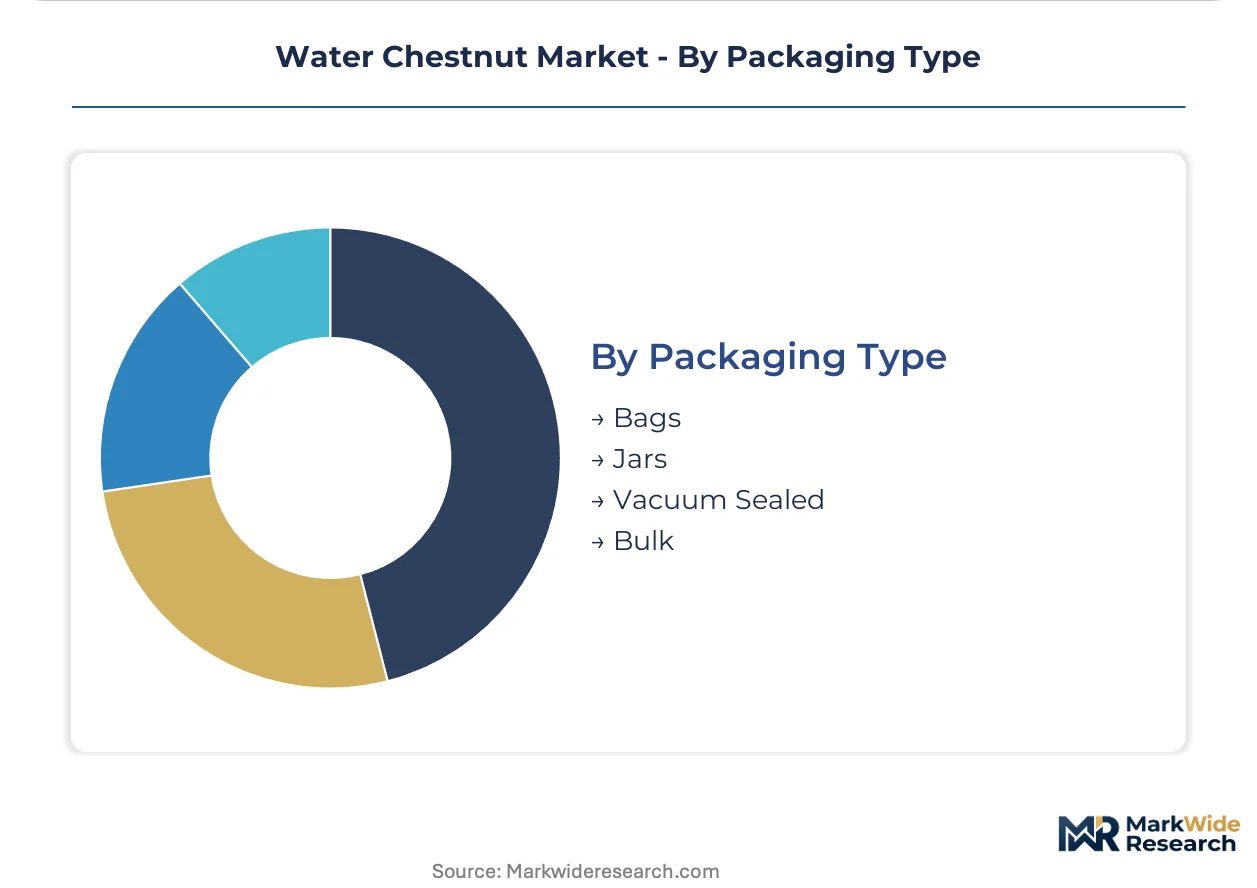
Packaging Type:
Packaging engineering balances shelf-life extension against cost—vacuum technology commands premiums, bulk minimizes unit economics for processors.
- Vacuum Sealed:Modified atmosphere packaging extends retail shelf life while preserving crisp texture. Fujian Lixing Foods and similar processors target premium Asian supermarket chains in Europe with this differentiated format.
- Bulk:Food-service-grade frozen segments in 10-20kg containers serve quick-service restaurant chains and food manufacturers with high-throughput processing lines.
- Jars:Glass packaging for brined canned formats serves retail segments where packaging aesthetics influence purchase decisions in Asian supermarkets.
- Bags:Polyethylene retail pouches for dried and frozen formats balance cost containment with basic moisture protection.
Bulk dominates institutional procurement; vacuum sealed is climbing the fastest in retail premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Guangzhou's container throughput underwrites China's dominance in water chestnut export logistics, connecting Pearl River Delta processing clusters to North American and European food manufacturing corridors.
China
Quick-service Asian restaurant chains in North America are pulling frozen format volumes from Guangdong province processors. SAMR's GB standards for heavy metal limits and geographic origin labeling are compressing the supplier base toward integrated operations with captive farming contracts. The Pearl River Delta processing cluster concentrates canning and IQF capacity, with Shandong's freshwater aquaculture zones emerging as a geographic diversification play.
United States
Asian grocery wholesale networks in Vancouver and Toronto are consolidating procurement authority for diaspora retail channels. USDA and FDA phytosanitary requirements for Chinese imports are creating administrative bottlenecks at provincial agricultural authorities. The Pacific Northwest cold-chain infrastructure supports frozen format distribution to quick-service chains across California and Washington State.
Canada
Institutional catering contracts in Ontario and British Columbia specify canned formats for inventory predictability in high-volume feeding operations. Health Canada's food safety regulations align with FDA thresholds, simplifying import documentation for Chinese processors. Toronto's diaspora population density supports dedicated Asian supermarket distribution for vacuum-sealed retail formats.
Germany
Premium Asian supermarket chains in Berlin and Frankfurt are differentiating shelf space with extended-shelf-life packaging for diaspora consumers. EFSA guidance on pesticide maximum residue limits is tightening enforcement across food manufacturing contracts. The Netherlands' Rotterdam port serves as the entry hub for German distribution, with batch-level documentation requirements favoring larger Chinese processors.
United Kingdom
London's restaurant sector is expanding year-round procurement of frozen water chestnut segments for dim sum and stir-fry applications. The UK's post-Brexit food safety regime maintains alignment with EFSA pesticide thresholds while adding UK-specific import documentation. Birmingham and Manchester's Asian wholesale networks are replicating the Vancouver-Toronto consolidation pattern.
Water Chestnut Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The water chestnut processing sector exhibits a bifurcated structure where large-scale operators with integrated farming contracts capture institutional volume, while smaller processors serve fragmented retail channels. Three archetypes dominate: Pearl River Delta canneries with legacy retort infrastructure, Shandong-based frozen format specialists with IQF capacity, and Fujian-area packagers focused on vacuum-sealed premium retail. Competitive moves center on geographic diversification beyond Guangdong and backward integration into captive aquaculture zones.
Among southern China-based processors, Guangxi Hualong Food Co., Ltd. and Fujian Lixing Foods Co., Ltd. occupy positions within the export-oriented frozen and premium retail tiers respectively. Qingdao Dongsheng Foodstuffs Co., Ltd. represents the northern China diversification archetype, anchoring Shandong's freshwater aquaculture processing corridor. These three exemplify the geographic and format-based segmentation that structures competitive positioning across the sector.
| Leading Market Players |
|---|
| Guangxi Hualong Food Co., Ltd. |
| Qingdao Dongsheng Foodstuffs Co., Ltd. |
| Qingdao Alliance Trading Co., Ltd. |
| Dragon Enterprise Co., Ltd. |
| Shandong Weifang Sansho Food Co., Ltd. |
| Fujian Lixing Foods Co., Ltd. |
| Baijia Food Group Co., Ltd. |
| Cofco Tunhe Co., Ltd. |
| Amoytop Foods |
| Others |
Value Network & Pricing Analysis
The Port of Guangzhou's container freight corridors anchor cost dynamics across frozen and canned format exports, compressing margin structures for processors lacking integrated farming contracts while enabling price differentiation through cold-chain reliability premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with SAMR-certified processors commanding premiums from European food manufacturers while commodity-grade canned volumes face cost compression from frozen format substitution. Price differentiation rests on certification tier and volume scale, with institutional buyers negotiating long-term offtake terms. Margins are tightening for legacy canneries as quick-service chains migrate toward IQF segments. Food manufacturers exhibit lowest price sensitivity due to specification rigidity, whereas independent restaurants arbitrage aggressively between fresh and canned alternatives.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for Pearl River Delta processors dependent on North American quick-service restaurant demand. Production gravity centers on Guangdong province and Shandong's freshwater aquaculture zones, with raw material inputs drawing from captive marshland leases, seasonal labor pools, and brining chemical supplies. Single-source vulnerability concentrates in Guangdong's processing cluster, where regional climate events disrupt harvest logistics. Distribution runs through Asian grocery wholesale networks in Vancouver and Toronto, consolidating previously fragmented restaurant procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
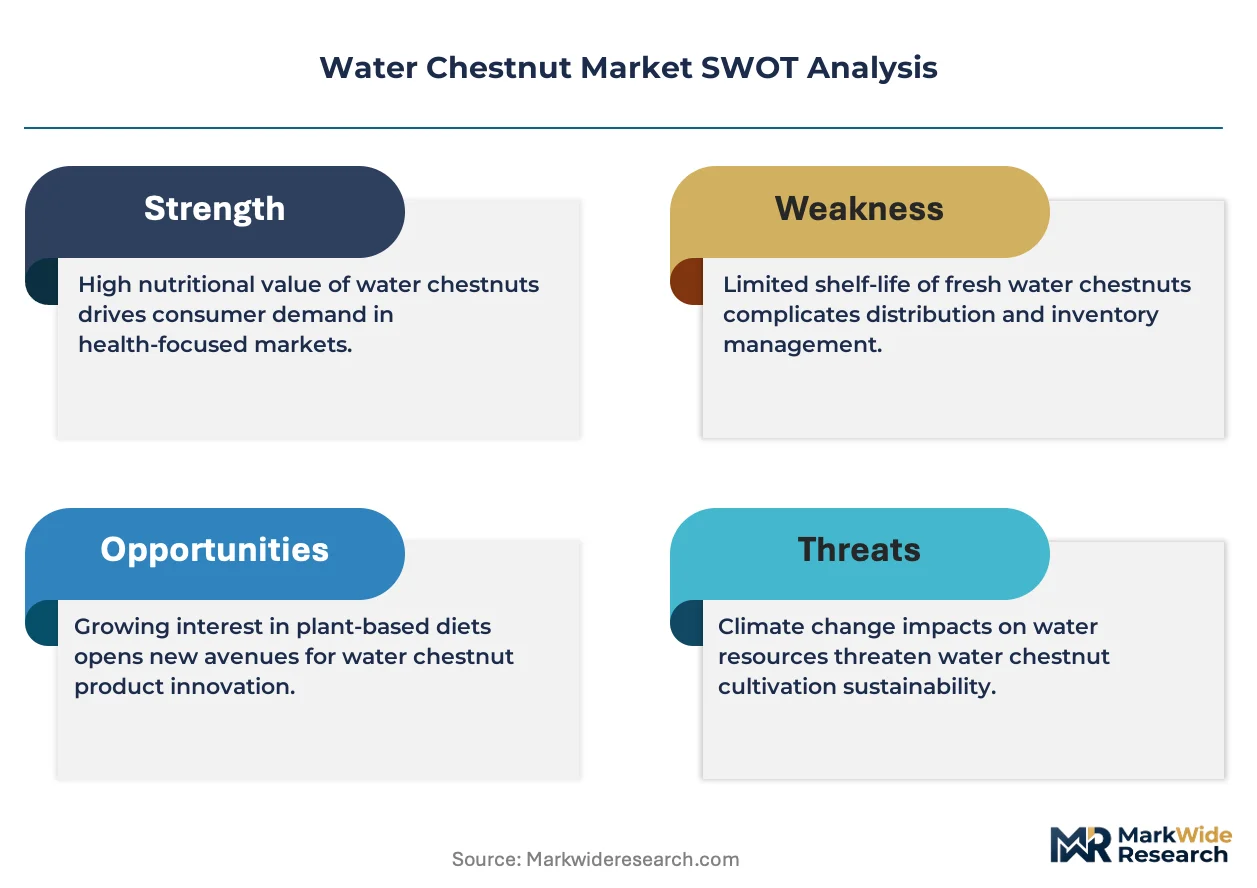
Water chestnut processors face sustained substitution pressure from alternative texturizers—jicama, bamboo shoots, and reformulated starches—requiring incumbents to defend through supply security and specification lock-in.
For Market Incumbents: Insulate market position through backward integration into Shandong freshwater aquaculture zones, reducing Pearl River Delta concentration risk. Secure SAMR certification and dual GB-EFSA testing protocols to disqualify smaller competitors from European contracts. Prioritize direct-to-manufacturer channel control with customized brining specifications that commodity wholesalers cannot replicate.
For New Entrants and Emerging Players: Build out e-commerce infrastructure targeting diaspora households in Germany and the United Kingdom, where Asian supermarket penetration lags North American benchmarks. Exploit vacuum-sealed retail whitespace with modified atmosphere packaging formats. Lead with premium positioning through extended-shelf-life claims rather than competing on canned commodity volume.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming aquatic vegetable divisions lacking export certification infrastructure. Long-term viability favors processors with captive farming contracts and IQF capacity over legacy cannery assets. Monitor EFSA pesticide threshold enforcement as the decisive filter for European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Aquaculture | Shandong freshwater zone expansion reduces Guangdong concentration risk for export processors. |
| Dual Certification Investment | Parallel SAMR GB and EFSA compliance testing unlocks European food manufacturing contract eligibility. |
| IQF Capacity Expansion | Individual quick-freezing infrastructure captures quick-service restaurant migration from canned formats. |
| Direct-to-Manufacturer Channel Development | Customized brining specifications command margin premiums unavailable in commodity wholesale. |
| Vacuum-Sealed Retail Format Launch | Modified atmosphere packaging penetrates premium Asian supermarket chains in European diaspora corridors. |
Research Methodology
Cross-validation between processor export filings and Asian grocery distribution network data anchors the qualitative findings across this analysis. Primary interviews with aquatic crop processing executives, cold-chain logistics operators, Asian supermarket category buyers, and food manufacturing procurement leads were synthesized with secondary validation from customs trade records, SAMR regulatory filings, and EFSA guidance documents. Bottom-up volume aggregation from provincial processing clusters was triangulated against top-down demand estimates from North American quick-service restaurant procurement patterns.
Calibration against historical volume trajectories and regulatory enforcement phases shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, distribution channel structure, end-user type, and packaging technology tier. CAGRs were derived through growth driver weighting and constraint penalty functions. Forecast inputs incorporated SAMR compliance cost curves and EFSA maximum residue limit enforcement intensity.
Stress conditions across freshwater harvest volatility, trans-Pacific freight rate fluctuations, and EU pesticide threshold revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and diaspora population growth patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market