
 Argentina Lime Market | 2026-2036
Argentina Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Lime Market Outlook
Beverage industry demand is realigning the Argentina lime value chain as distilleries and flavor houses expand cold-pressed oil and clarified juice purchases. San Miguel S.A. leverages its integrated citrus estates in Tucumán to secure year-round varietal supply. Citromax Group anchors its position through controlled-atmosphere storage infrastructure that extends the commercial window for Persian lime exports. Ledesma S.A.A.I. competes by specializing in organic-certified orchards that command premium placement in European retail channels.
Lime denotes the tart citrus fruit of Citrus aurantiifolia and related cultivars, containing citric acid concentrations of five to six percent by weight and essential oil glands concentrated in the flavedo layer; processors extract these oils for flavoring, while the juice serves acidification and preservation functions across food systems. Seedless limes dominate fresh export volumes due to consumer preference for convenience and extended shelf stability. The beverage industry segment records the fastest structural expansion as Argentine distillers and multinational flavor houses increase concentrate offtake. Carton packaging for premium retail channels captures disproportionate margin pools compared with bulk bag shipments to industrial processors.
Argentina's Servicio Nacional de Sanidad y Calidad Agroalimentaria (SENASA) enforces phytosanitary certification for all citrus export lots, while the Administración Nacional de Medicamentos, Alimentos y Tecnología Médica (ANMAT) governs lime-derived ingredients entering processed food and beverage matrices. These frameworks elevate traceability requirements and restrict market access for non-compliant packers. Stakeholders must monitor evolving EU phytosanitary equivalence negotiations and domestic water-use regulations affecting Tucumán orchard productivity.
Market Dynamics
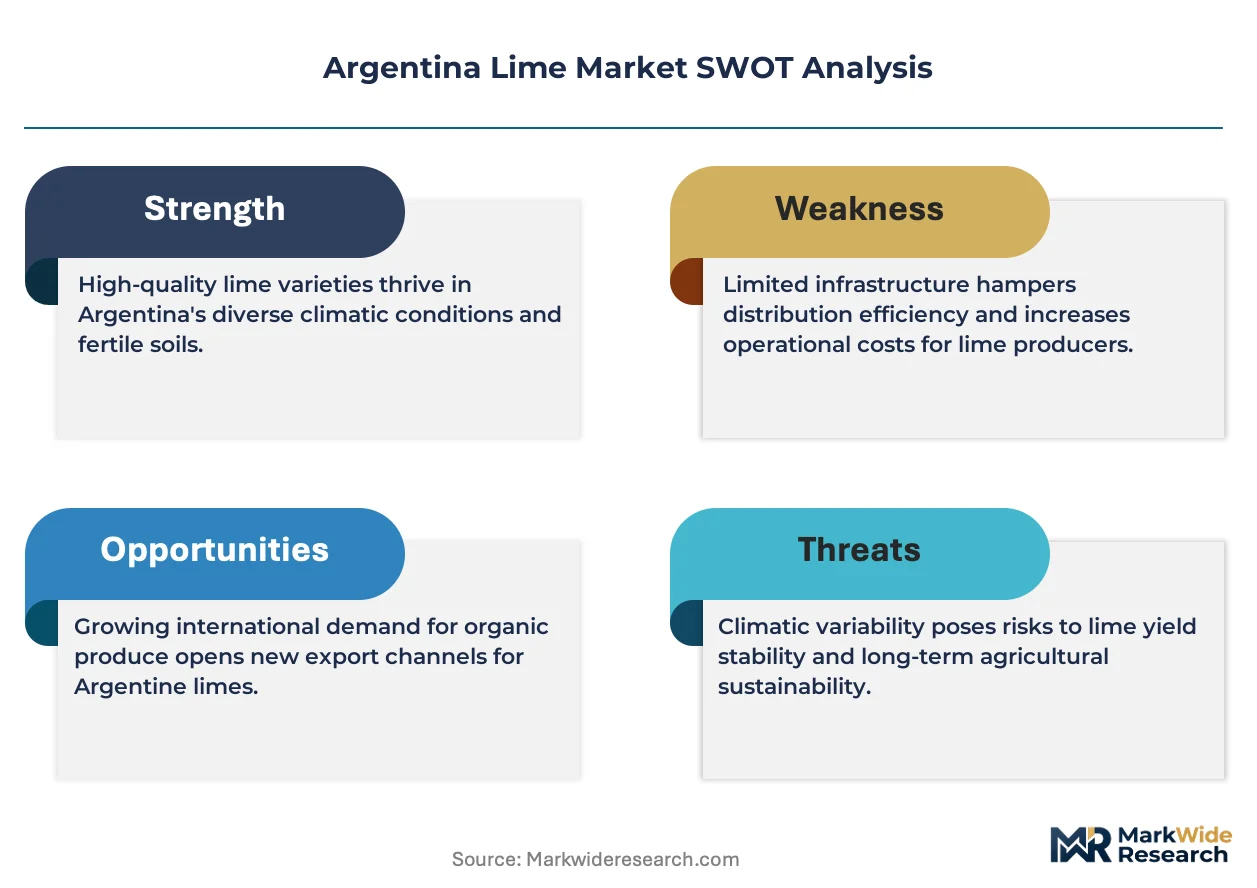
Argentina's lime sector is experiencing structural recalibration as beverage manufacturers intensify cold-pressed oil procurement, compressing traditional wholesale channels and rewarding processors with captive orchard control.
Growth Catalysts
- Craft Distillery Expansion:Argentine gin and vodka producers are scaling clarified lime juice purchases for natural flavoring, creating dedicated supply contracts with Tucumán processors.
- SENASA Export Certification:Stricter phytosanitary protocols are filtering out informal packers, consolidating volume among compliant operators with traceable orchard-to-port systems.
- Persian Lime Storage Infrastructure:Controlled-atmosphere facilities are extending the commercial export window, enabling year-round shipment scheduling to European retail buyers.
Market Restraints
- Water Access Volatility:Tucumán orchard irrigation depends on seasonal rainfall patterns and groundwater allocation disputes, constraining yield predictability for smallholder suppliers.
- Organic Certification Cost Burden:European retail channel entry requires multi-year conversion timelines and SENASA-accredited third-party audits, elevating fixed costs for non-integrated packers.
- Concentrate Substitution Risk:Synthetic citric acid and lemon-derived alternatives from Brazil and Mexico are displacing Argentine lime concentrate in industrial acidification applications.
Strategic Opportunities
- European Organic Premium Channel:Underpenetrated placement in German and Dutch natural food retailers offers margin expansion for certified Tucumán producers with direct import relationships.
- ANMAT-Compliant Ingredient Supply:Processed food manufacturers require lime-derived preservatives with full traceability documentation, creating white space for compliant oil and concentrate suppliers.
- E-Commerce Direct-to-Consumer:Buenos Aires-based specialty food platforms are enabling small-batch lime product sales, bypassing traditional wholesale markups for artisanal processors.
Industry Challenges
- Cold-Chain Infrastructure Investment:Maintaining oil quality from Tucumán processing facilities to Buenos Aires export terminals requires refrigerated transport capex that strains mid-scale operators.
- Phytosanitary Documentation Complexity:SENASA lot certification timelines create working capital pressure, as exporters cannot book vessel space until final clearance is issued.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Lime Market |
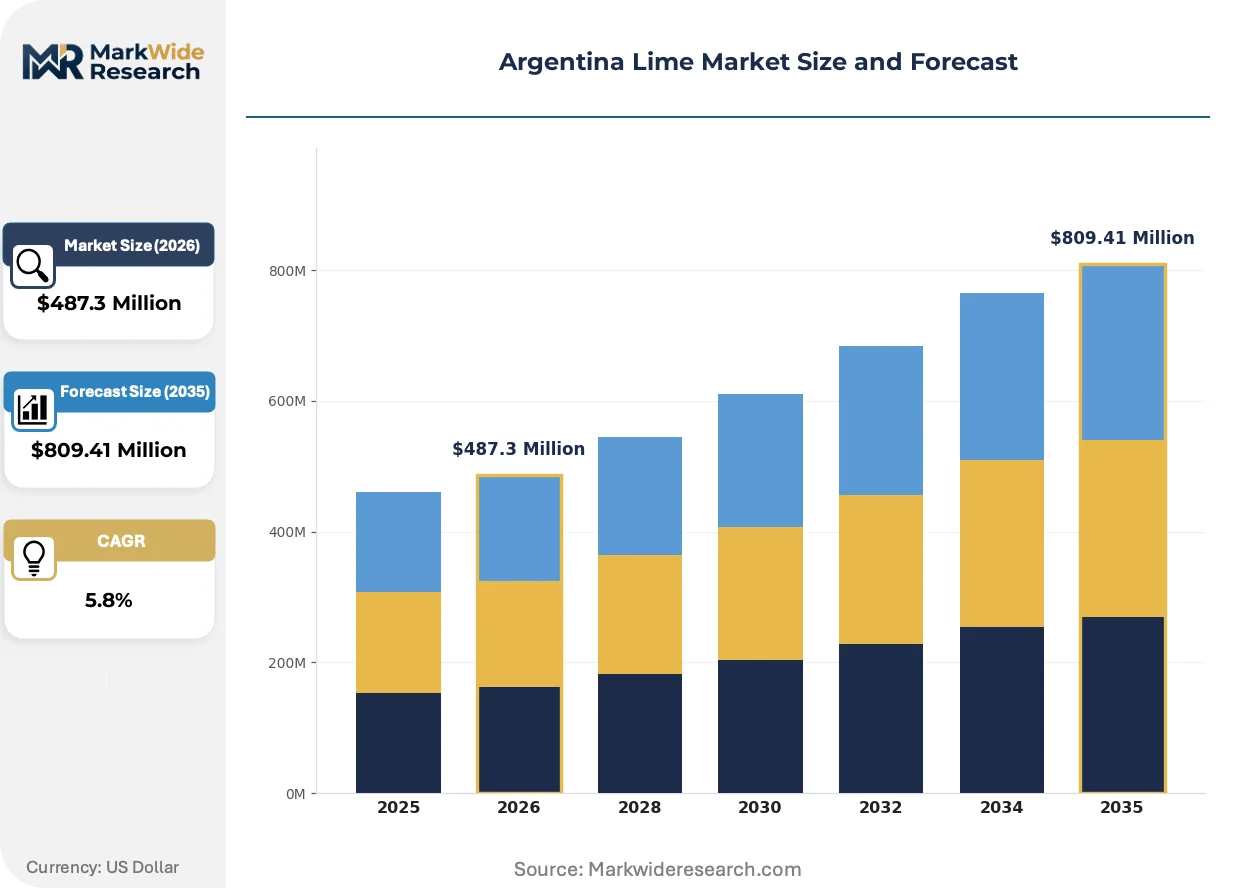
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seedless Limes, Persian Limes, Key Limes, Finger Limes End User: Food Processing, Beverage Industry, Retail, Hospitality Distribution Channel: Online Retail, Wholesale, Direct Sales, Export Packaging Type: Cartons, Baskets, Bulk Bags, Plastic Pouches |
| Companies Covered | San Miguel S.A., Citrusvil S.A., Citromax Group, Ledesma S.A.A.I., Pampa Store S.A., Calidra Group, Trapani, Argenti Lemon, Emelco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Lime Market Strategic Shifts
Processing technology and regulatory documentation requirements are compressing traditional supply hierarchies, rewarding operators with integrated quality control systems and direct buyer relationships.
Near-infrared spectroscopy is unifying quality assessment across Tucumán processing lines, replacing manual oil grading with real-time citral content measurement. Major distilleries and flavor houses are mandating this specification in procurement contracts. The technology is unifying supplier tiers by forcing smaller packers to invest in comparable analytical capability or exit premium contract pools.
SENASA has tightened phytosanitary equivalence documentation for EU-bound citrus shipments, requiring genetic cultivar verification and orchard GPS mapping. This elevates traceability infrastructure costs for exporters. Organic-certified operators are responding fastest, having already invested in lot-level documentation systems for European retail compliance.
Beverage manufacturers are consolidating supplier relationships around processors with captive orchard supply, displacing spot-market purchasing. Argentine distillers now favor three-to-five-year concentrate supply agreements with Tucumán estates. This concentration is most visible in the craft spirits segment, where formulation consistency requirements override short-term price optimization.
Argentina Lime Market Segmentation
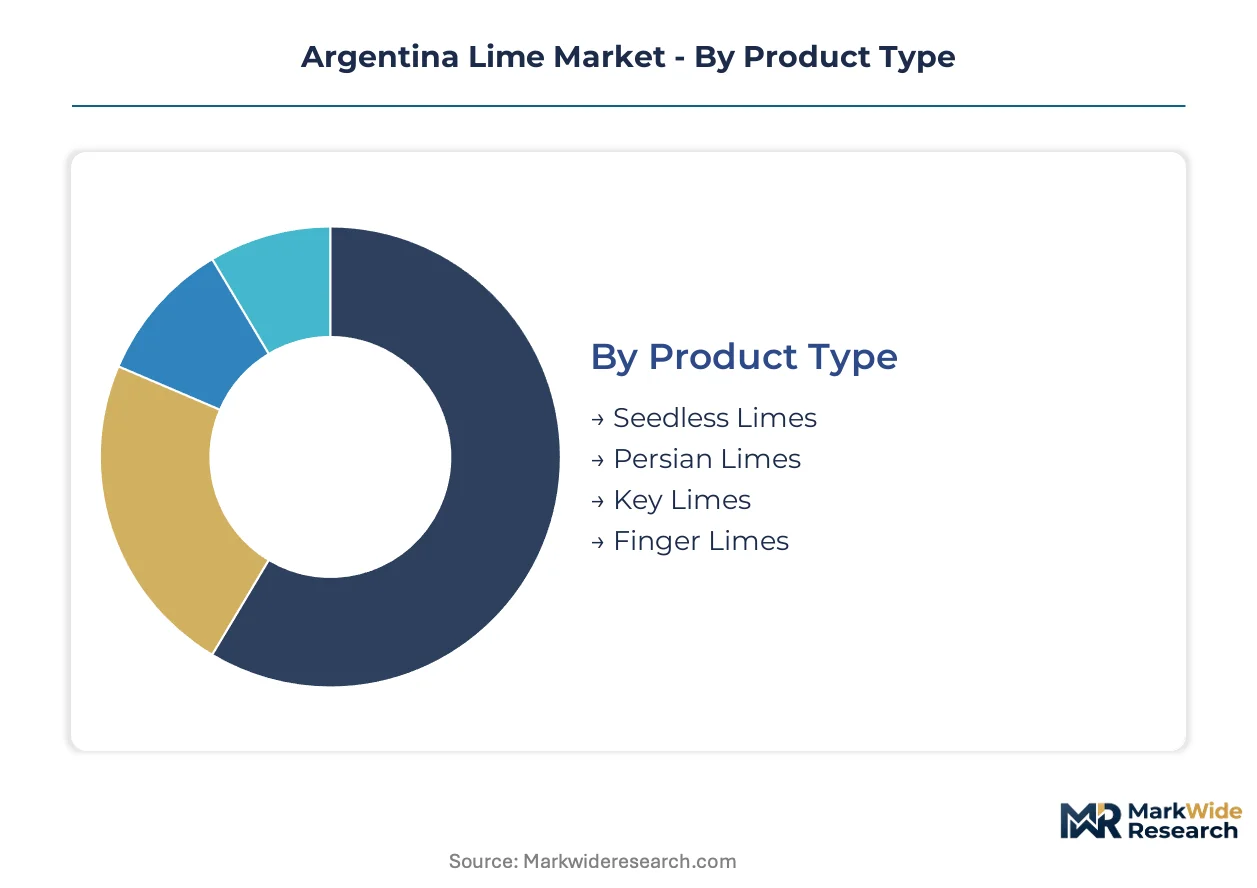
Segmentation in the Argentina lime market reveals how capital deployment and regulatory compliance concentrate returns among specific product tiers and channel configurations. Distinct investment requirements across seedless varieties, beverage-directed supply chains, and export-grade packaging create divergent margin structures for Tucumán-based operators.
Product Type:
Capital intensity varies sharply across varietal cultivation, with controlled-atmosphere storage infrastructure and grafting technology separating premium export tiers from commodity supply.
- Seedless Limes:These varieties command premium placement in European retail channels due to consumer preference for convenience and extended shelf stability. Tucumán processors with SENASA-certified traceability systems capture disproportionate margin pools from German and Dutch supermarket chains.
- Persian Limes:Thick-rinded and oil-rich, Persian limes dominate cold-pressed oil extraction for distilleries and flavor houses. Citromax Group's controlled-atmosphere facilities specifically target this varietal for year-round export scheduling.
- Key Limes:Higher acid concentration suits industrial concentrate production; smaller orchard footprint limits scale economies.
- Finger Limes:Caviar-like vesicles command niche premium in hospitality garnish applications; propagation costs constrain volume expansion.
Persian limes absorb the bulk of installed capacity; seedless limes are expanding most quickly.
End User:
Application-specific formulation requirements are restructuring procurement relationships around dedicated supply contracts versus spot-market purchasing.
- Beverage Industry:Craft distilleries and multinational flavor houses now mandate near-infrared spectroscopy verification for citral content. Argentine gin and vodka producers are locking three-to-five-year concentrate agreements with captive Tucumán estates to secure formulation consistency.
- Food Processing:ANMAT-compliant preservative applications require full traceability documentation from orchard to processing facility. Lime-derived acidification serves processed food manufacturers with strict phytosanitary protocols.
- Retail:Organic certification and carton packaging differentiate premium placement in Buenos Aires specialty channels.
- Hospitality:Fresh fruit procurement concentrates in high-volume hotel and restaurant chains with direct import relationships.
Beverage industry offtake dominates revenue concentration; food processing applications are climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity and documentation burden, with export certification timelines creating divergent liquidity pressures.
- Export:SENASA phytosanitary clearance requirements and vessel booking constraints demand integrated orchard-to-port traceability systems. Genetic cultivar verification and GPS mapping elevate fixed costs for compliant operators.
- Wholesale:Traditional spot-market channels are compressing as beverage manufacturers consolidate around processor-direct relationships.
- Direct Sales:Distillery-processor partnerships bypass wholesale markups through multi-year supply agreements.
- Online Retail:Buenos Aires-based specialty food platforms enable small-batch sales for artisanal processors with limited cold-chain infrastructure.
Export channels absorb the bulk of installed capacity; online retail is gaining share fastest.
Packaging Type:
Packaging configuration directly shapes margin capture, with premium retail formats requiring capital-intensive grading and presentation standards.
- Cartons:Premium retail presentation for European organic channels demands calibrated sizing and protective inserts. Ledesma S.A.A.I.'s organic-certified orchards specifically target this format for German and Dutch natural food retailers.
- Bulk Bags:Industrial concentrate and oil extraction supply chains prioritize volume efficiency over presentation. Beverage manufacturers accept bulk shipment for downstream processing.
- Baskets:Traditional wholesale formats serve domestic hospitality procurement with minimal value-add.
- Plastic Pouches:Single-serve and convenience-oriented formats target urban retail with shorter shelf-life requirements.
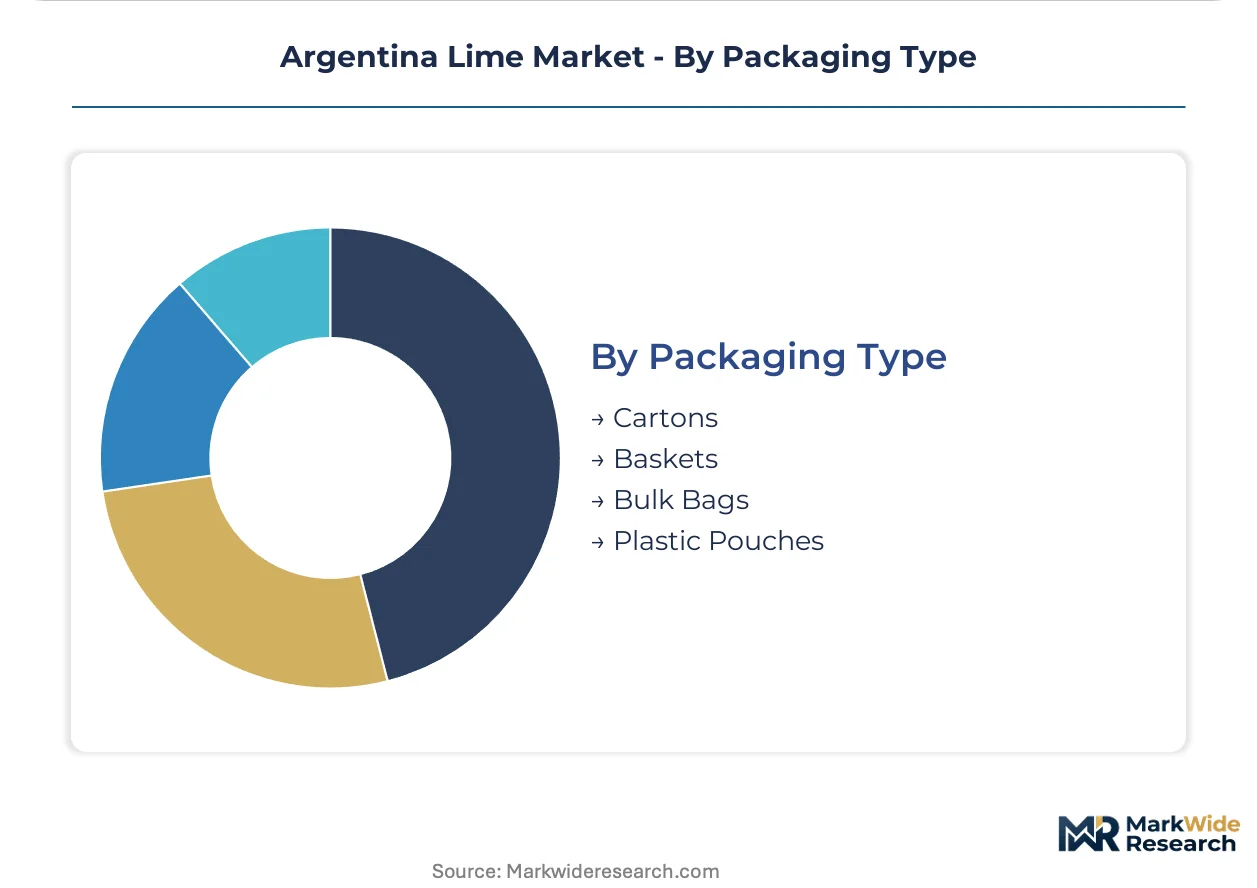
Bulk bags absorb the bulk of installed capacity; cartons are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's citrus processing incentives in Tucumán Province concentrate lime oil and concentrate production within federally designated agro-industrial zones that reduce export tariff burdens for qualifying packers.
Tucumán Province
Beverage manufacturers and cold-pressed oil extractors dominate procurement from this northwestern cluster. SENASA enforces genetic cultivar verification and GPS orchard mapping for all export-bound shipments. San Miguel S.A. leverages integrated estate holdings here to secure year-round Persian lime supply for distillery contracts.
Buenos Aires Province
Specialty food platforms and artisanal processors drive small-batch demand through direct-to-consumer channels. ANMAT governs lime-derived ingredient entry into processed food matrices manufactured in Greater Buenos Aires. Cold-chain logistics providers cluster in the capital region to bridge Tucumán processing with port terminals.
Mendoza Province
Wine industry acidification applications create secondary lime concentrate demand from vinegar and preservative manufacturers. Provincial water-use regulations constrain orchard expansion in this arid western zone. Limited Persian lime cultivation serves local food processors rather than export channels.
Entre Ríos Province
Citrus diversification programs subsidize Key lime propagation for industrial concentrate production. National agricultural credit lines from Banco Nación support smallholder conversion to certified export varieties. Processing infrastructure remains underdeveloped compared with Tucumán benchmarks.
Argentina Lime Market Competitive Environment
Top-tier vendors anchor integrated estate-to-processor operations, while mid-scale packers compete through organic certification or specialized cold-pressed oil capacity. The vendor base stratifies between captive orchard controllers and toll-processing specialists serving spot-market demand. Strategic archetypes include vertically integrated citrus conglomerates, organic-certified estate operators, and regional cooperative packers. Dominant competitive moves center on multi-year supply agreements with beverage manufacturers and controlled-atmosphere storage infrastructure deployment.
Within the integrated estate tier, San Miguel S.A. and Citromax Group exemplify operators with captive orchard supply and export-grade storage infrastructure. Ledesma S.A.A.I. occupies a distinct position as an organic-certified specialist targeting European retail premium channels. These three S.A.-structured entities represent the dominant competitive archetypes visible in the raw data: integrated conglomerate, infrastructure-anchored processor, and certification-driven premium operator.
| Leading Market Players |
|---|
| San Miguel S.A. |
| Citrusvil S.A. |
| Citromax Group |
| Ledesma S.A.A.I. |
| Pampa Store S.A. |
| Calidra Group |
| Trapani |
| Argenti Lemon |
| Emelco |
| Others |
Value Chain & Pricing Dynamics
Near-infrared spectroscopy deployment across Tucumán processing lines is compressing cost structures for citral-content verification while simultaneously concentrating procurement power among processors with captive analytical infrastructure. This technology transition rewards integrated operators who embed quality-assurance capex into estate economics, squeezing spot-market packers unable to match specification mandates from Argentine distilleries and European flavor houses.
Pricing Analysis
Short lead-time premiums for SENASA-cleared export lots command substantial markups over spot inventory with pending phytosanitary documentation. Contract-based long-term offtake agreements between Tucumán estates and beverage manufacturers anchor the dominant pricing structure, with price differentiation resting on organic certification tier and controlled-atmosphere storage access. Cost compression in commodity concentrate supply runs through substitution pressure from Brazilian and Mexican lemon-derived alternatives. Smallholder suppliers without traceability infrastructure exhibit the highest price sensitivity, while integrated conglomerates with direct European retail relationships demonstrate the least.
Supply Chain Analysis
Refrigerated freight costs from Tucumán processing facilities to Buenos Aires export terminals absorb disproportionate working capital for mid-scale operators lacking dedicated logistics contracts. Geographic supply concentration centers on Argentina's northwestern citrus belt, with secondary processing capacity in Greater Buenos Aires and limited cultivation in Mendoza Province. Raw material dependencies draw from grafted rootstock, phytosanitary-certified propagation material, and groundwater allocation entitlements. Single-source vulnerability permeates the SENASA certification bottleneck, where lot-level clearance delays cascade through vessel booking windows. Distribution runs through processor-direct relationships with multinational flavor houses, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's lime sector reads as a supply-constrained story where Tucumán groundwater allocation disputes and SENASA certification bottlenecks prop pricing power for compliant operators with traceable orchard-to-port systems.
For Market Incumbents: Hedge against concentrate substitution risk by deepening backward integration into controlled-atmosphere storage infrastructure that extends the commercial export window for Persian limes. Secure multi-year supply agreements with craft distilleries to lock formulation-dependent buyers before Brazilian and Mexican lemon-derived alternatives capture additional industrial acidification share. Prioritize organic certification investment to defend margin position in German and Dutch natural food retail channels where SENASA-accredited third-party audits already satisfy European phytosanitary equivalence requirements. For New Entrants and Emerging Players: The premium-to-economy price-point gap in European organic retail channels offers accessible white-space for certified Tucumán producers with direct import relationships bypassing traditional wholesale markups. Target Buenos Aires-based specialty food platforms enabling small-batch sales for artisanal processors with limited cold-chain infrastructure. Pursue ANMAT-compliant ingredient supply positioning for processed food manufacturers requiring full traceability documentation, as this segment remains underpenetrated by estate-direct relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated estate-processor acquisitions by multinational flavor houses seeking captive supply security. Long-term viability across the analysis window hinges on water-rights security and SENASA certification infrastructure rather than commodity price exposure. Monitor EU phytosanitary equivalence negotiation outcomes as the critical inflection indicator for premium channel access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Expansion | Citromax Group's infrastructure deployment extends Persian lime commercial windows for year-round European retail scheduling. |
| Organic Certification Investment | Ledesma S.A.A.I.'s accredited orchard systems unlock premium placement in German and Dutch natural food channels. |
| Multi-Year Supply Agreements | San Miguel S.A.'s distillery contracts lock formulation consistency requirements that override short-term price optimization. |
| Near-Infrared Spectroscopy Deployment | Real-time citral content measurement unifies supplier tiers and forces smaller packers toward analytical capability investment. |
| Direct-to-Consumer Platform Integration | Buenos Aires specialty food platforms enable artisanal processors to bypass wholesale markups with limited cold-chain capex. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with citrus estate operations managers, SENASA compliance officers, beverage manufacturer procurement leads, and cold-chain logistics providers. Secondary validation drew from Argentine citrus export statistics, ANMAT ingredient registry filings, EU phytosanitary equivalence documentation, and Tucumán provincial water-use regulatory records. Bottom-up volume estimates from individual processor capacity and top-down demand calibration from beverage industry offtake data were reconciled through iterative triangulation.
Data-stream reconciliation across production volume, export shipment, and end-use consumption estimates shaped the analytical framework applied across the projection horizon. Segmentation dimensions modeled include varietal tier, end-use application, distribution channel, and packaging format, with additional granularity on SENASA certification status and organic accreditation. CAGRs were derived from trend extrapolation of historical trade flows and elasticity-adjusted demand projections. Key forecast inputs encompass groundwater allocation policy trajectories and evolving EU phytosanitary equivalence negotiation outcomes affecting premium channel access.
Underlying measurement precision varies by segment; export-grade Persian lime oil and concentrate flows carry tighter precision than small-batch domestic retail channels due to customs documentation density. Forecasts reflect assumptions regarding SENASA certification timeline stability, EU market access continuity, and Tucumán irrigation entitlement enforcement. Stakeholders should weight assumptions against their own operating context, particularly regarding water-rights security and cold-chain infrastructure capex requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Noni Fruit Powder Market