
 Fosthiazate Market | 2026-2036
Fosthiazate Market Size, Share, and Industry Trends Forecast 2026-2036
Fosthiazate Market Insights
Organophosphate nematicides is restructuring competitive dynamics as fosthiazate displaces carbofuran in soil-applied pest management. FMC Corporation leverages its proprietary formulation technology to sustain premium positioning in liquid concentrate segments. Sumitomo Chemical Co., Ltd. anchors Asian supply through integrated manufacturing in Japan and licensed production partnerships. BASF SE competes via its distribution depth across European agricultural cooperatives.
Fosthiazate is an organophosphorus nematicide with the chemical formula C9H18NO3PS2, functioning as a cholinesterase inhibitor that disrupts nematode nervous systems upon soil application. Its primary commercial purpose centers on protecting root systems of vegetables, fruits, and turf from plant-parasitic nematodes including Meloidogyne and Globodera species. Liquid formulations dominate volume due to ease of soil drench application and compatibility with irrigation systems, while emulsifiable concentrates capture margin pools through extended residual control in perennial crops. Agricultural use absorbs the bulk of demand as large-scale vegetable operations in Shandong province and tomato greenhouses in Almeria, Spain prioritize nematode management.
EPA registration under FIFRA governs fosthiazate tolerances and application rates in the United States, while ECHA's REACH framework and the EU's Sustainable Use of Pesticides Directive constrain formulation chemistry and buffer zone requirements across member states. China's MEE enforces production emission standards for organophosphate synthesis that elevate compliance costs for domestic manufacturers like Hebei Sannong Agricultural Chemical. Stakeholders must monitor regulatory divergence between jurisdictions that accept organophosphate nematicides and those accelerating phase-outs, as this split determines where formulation R&D investment and inventory positioning yield returns.
Market Dynamics
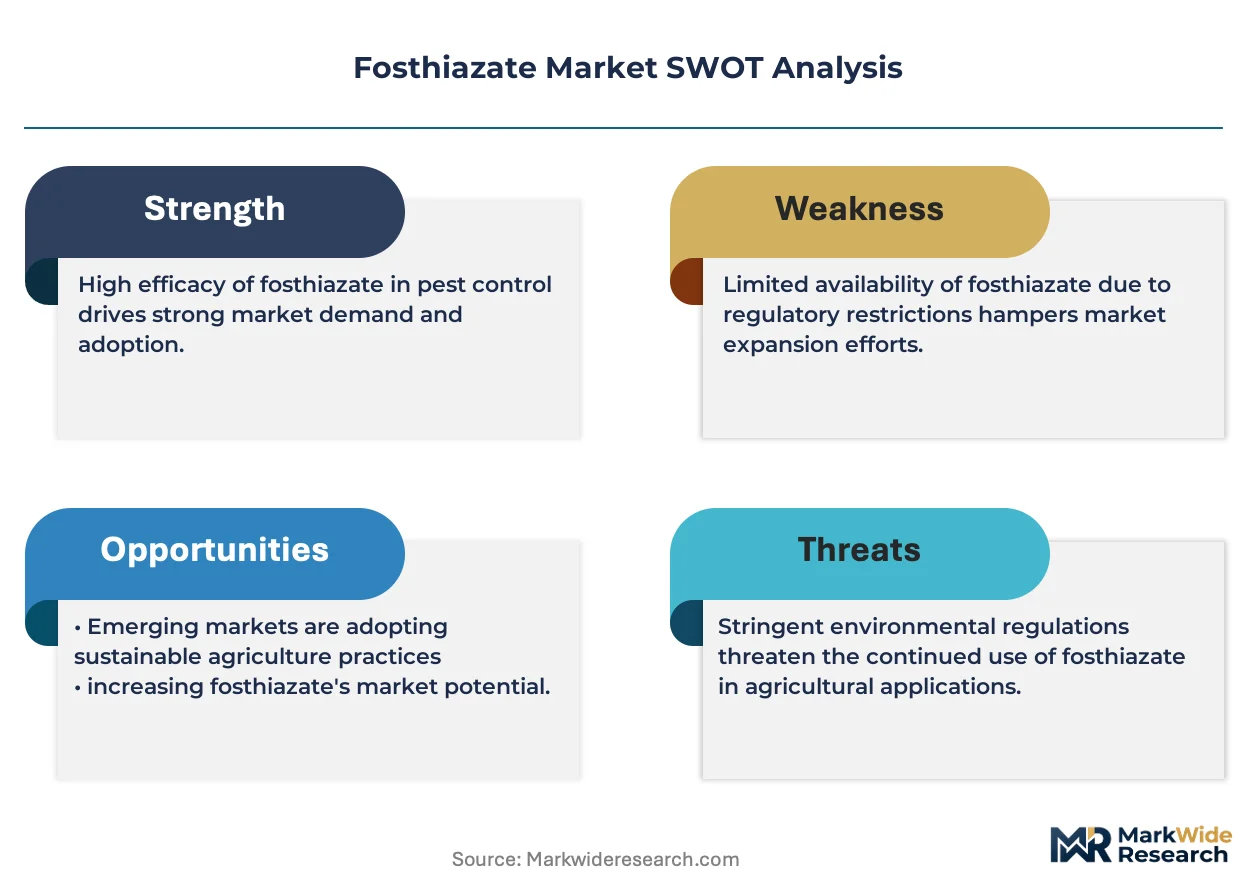
The EU's Farm to Fork strategy is forcing accelerated phase-out schedules for organophosphate nematicides while simultaneously funding bio-based alternatives, creating a bifurcated regulatory environment that fragments R&D investment and inventory positioning across jurisdictions.
Growth Catalysts
- Protected cultivation expansion:China's Shandong and Jiangsu provinces are scaling greenhouse tomato and cucumber operations that require intensive nematode management, absorbing rising fosthiazate volumes.
- REACH compliance differentiation:Formulators achieving ECHA registration for reduced-buffer-zone variants capture shelf space in European agricultural cooperatives as older organophosphates face restriction.
- Carbofuran displacement:Vegetable growers in Spain's Almeria region are switching soil-applied chemistry as legacy carbamate registrations expire and residue tolerances tighten.
Market Restraints
- Active ingredient cost volatility:Phosphorus trichloride and thiophosphoryl chloride feedstock prices fluctuate with energy markets, compressing formulation margins.
- Supply concentration risk:Technical-grade production clusters in Japan and licensed Chinese facilities create single-source vulnerability for non-integrated distributors.
- Cholinesterase inhibition liability:Operator exposure concerns trigger buffer zone expansions and personal protective equipment mandates that raise application costs.
Strategic Opportunities
- Micro-encapsulation convergence:Combining polymer shell technology with liquid concentrate bases extends residual control in perennial turf applications.
- Spanish cooperative channel:Direct supply agreements with Almeria-based horticultural consortiums bypass traditional distribution markups.
- India's horticulture subsidy schemes:Central government support for protected cultivation in Maharashtra and Karnataka creates first-mover positioning for nematicide registrants.
Industry Challenges
- Toxicology study completion timelines:EPA FIFRA registration maintenance requires updated chronic exposure data that delays label expansions.
- Legacy irrigation system compatibility:Drip-line injection of emulsifiable concentrates demands equipment recalibration that slows grower adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fosthiazate Market |
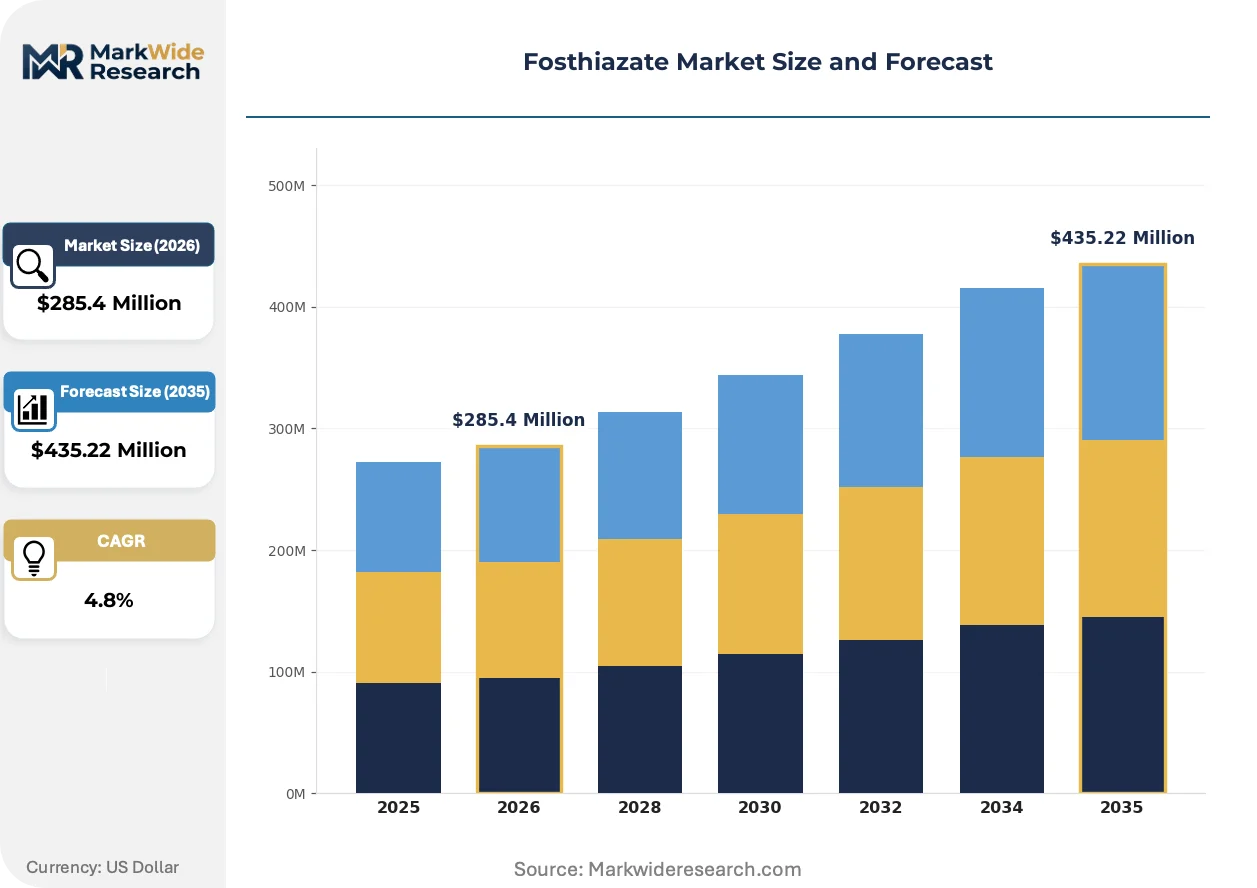
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid, Suspension, Emulsifiable Concentrate Application: Agricultural Use, Residential Use, Commercial Use, Industrial Use End User: Farmers, Distributors, Agricultural Cooperatives, Retailers Distribution Channel: Online Sales, Direct Sales, Retail Stores, Wholesalers |
| Companies Covered | FMC Corporation, SinoHarvest, Sumitomo Chemical Co., Ltd., ADAMA India Private Limited, BASF SE, ISK, Hebei Sannong Agricultural Chemical, Veyong, Nissan Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fosthiazate Market Trends and Innovations
Formulation chemistry and application infrastructure are converging around precision delivery systems that reduce active ingredient rates while maintaining efficacy thresholds. This shift is compressing the traditional volume-based pricing model.
Micro-encapsulated fosthiazate suspensions are unifying controlled-release kinetics with soil drench compatibility. Large-scale vegetable operations in China's protected cultivation sector are adopting these variants to align with MEE emission standards. The technology is compressing application frequency requirements and shifting procurement criteria toward cost-per-season rather than cost-per-liter metrics.
REACH authorization timelines for organophosphate intermediates are extending compliance horizons for European formulators. ECHA's substance evaluation workload is delaying dossier approvals by 18-24 months beyond historical baselines. Perennial crop operators in southern France and Italy are stockpiling conventional liquid concentrates ahead of anticipated restriction dates.
Certification-driven procurement is displacing price-first buying in retail-facing supply chains. Spanish supermarket chains and their contracted growers now require GLOBALG.A.P. certification that restricts organophosphate residue thresholds. Almeria's export-oriented tomato cooperatives are switching to reduced-rate micro-encapsulated products to maintain market access.
Fosthiazate Market Segmentation
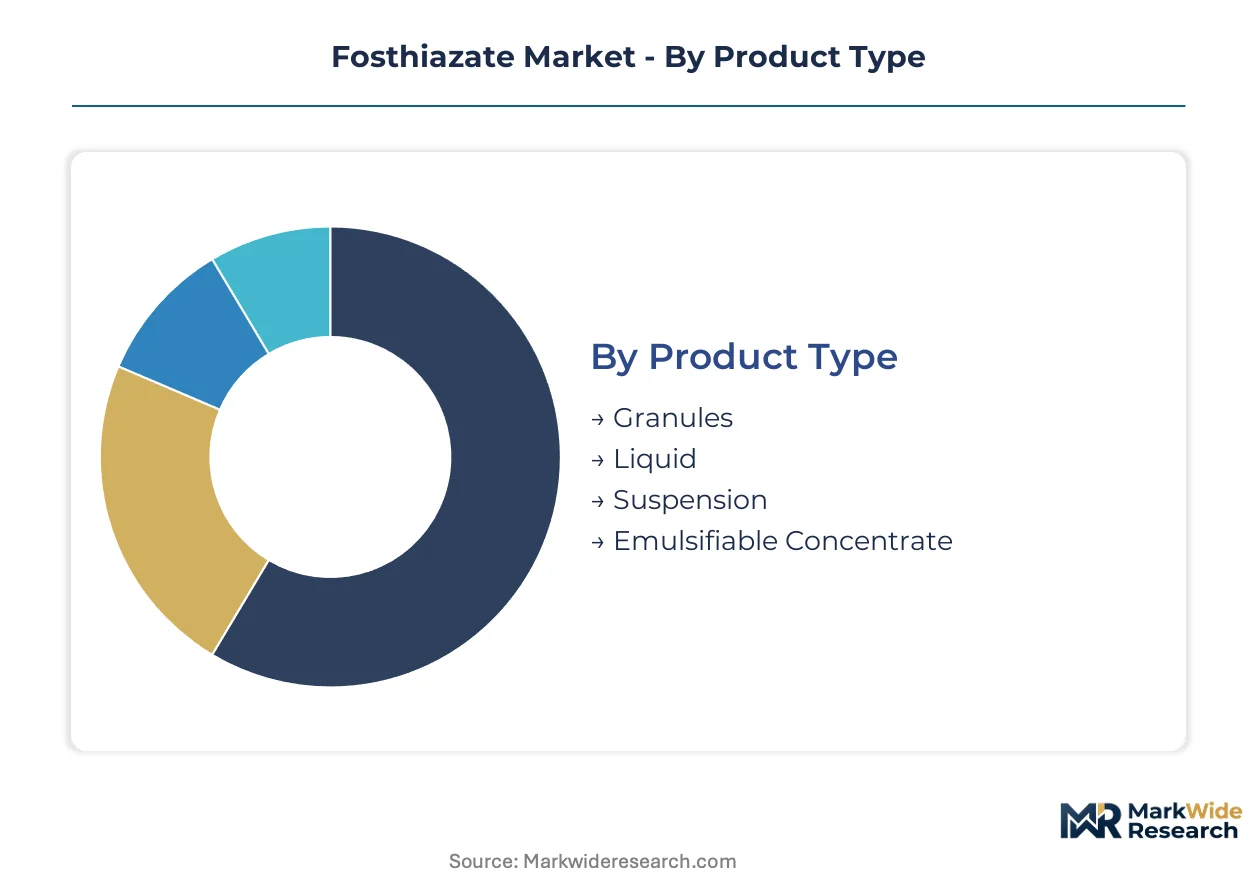
Fosthiazate procurement patterns diverge sharply across formulation types and buyer categories. Specification requirements from regulators like EPA and ECHA fragment demand into distinct technical tiers with incompatible compliance pathways.
Product Type:
Formulation chemistry determines application infrastructure compatibility and residual control profiles across cultivation systems.
- Liquid:Aqueous solutions enable direct soil drench application and seamless integration with drip irrigation infrastructure. Protected cultivation operators in China's Shandong province specify liquid concentrates for greenhouse tomato operations where equipment compatibility outweighs unit cost premiums.
- Emulsifiable Concentrate:Oil-in-water systems deliver extended residual activity through controlled release kinetics. Spanish horticultural cooperatives in Almeria favor these variants for perennial crops where application frequency reduction justifies higher per-liter pricing.
- Granules:Solid carrier formulations suit broadcast application in open-field vegetable production with minimal equipment investment.
- Suspension:Aqueous dispersed systems bridge compatibility gaps between liquid convenience and emulsifiable concentrate persistence.
Mature deployment sits with liquid concentrates. Newer deployment is concentrated in micro-encapsulated emulsifiable concentrate variants.
Application:
End-use intensity correlates with nematode pressure and crop value per hectare.
- Agricultural Use:Large-scale vegetable operations and protected cultivation facilities drive volume absorption. China's Jiangsu province cucumber greenhouses and Spain's Almeria tomato cooperatives anchor this segment through intensive soil-applied pest management protocols.
- Commercial Use:Turf management operations for golf courses and sports facilities specify reduced-rate formulations to meet operator exposure standards.
- Residential Use:Home garden applications face regulatory compression as EPA FIFRA buffer zone requirements restrict consumer-accessible packaging sizes.
- Industrial Use:Seed treatment and pre-plant soil preparation applications capture margin through technical service bundling.
Volume concentration rests with agricultural use. Regulatory pressure is accelerating fastest in residential applications.
End User:
Procurement authority shifts with scale and supply chain integration depth.
- Farmers:Direct purchasers in China's Shandong and Jiangsu provinces negotiate volume-based contracts with licensed technical-grade suppliers.
- Agricultural Cooperatives:Consolidated buying power in Spain's Almeria region enables specification of GLOBALG.A.P.-compliant reduced-residue formulations.
- Distributors:Inventory positioning intermediaries manage regulatory divergence between jurisdictions accepting organophosphates and those phasing them out.
- Retailers:Point-of-sale channels face margin compression from certification-driven procurement requirements in export-oriented supply chains.
Contracting authority concentrates with agricultural cooperatives. Direct farmer procurement is expanding fastest in China's protected cultivation corridors.
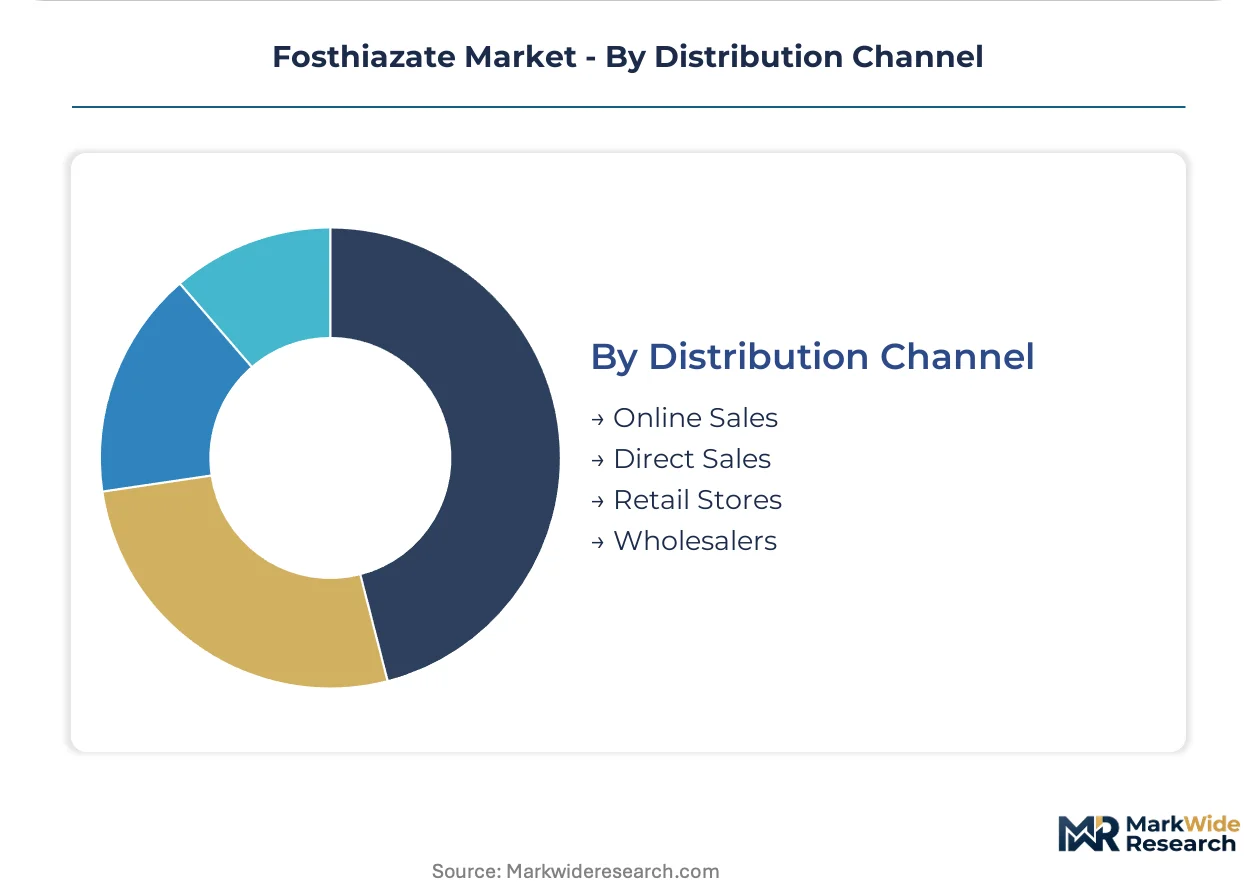
Distribution Channel:
Channel selection reflects buyer technical sophistication and regulatory compliance burden.
- Direct Sales:Technical-grade manufacturers like Sumitomo Chemical supply large-scale vegetable operations through dedicated account management.
- Wholesalers:Regional inventory aggregators serve fragmented farmer bases in China's interior provinces with formulation repackaging services.
- Online Sales:E-commerce platforms capture smallholder demand with documentation support for MEE emission standard compliance.
- Retail Stores:Physical point-of-sale channels face regulatory restriction as EPA and ECHA buffer zone mandates limit consumer-accessible packaging.
Channel maturity sits with direct sales to large-scale operators. Online platforms are gaining share fastest among geographically dispersed smallholders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's protected cultivation corridors, Spain's export-oriented horticulture zones, and India's emerging greenhouse clusters. Regulatory divergence between jurisdictions accepting organophosphate nematicides and those accelerating phase-outs fragments inventory positioning and R&D investment across these markets.
China
Shandong and Jiangsu provinces drive volume absorption through intensive greenhouse tomato and cucumber operations requiring soil-applied nematode management. MEE production emission standards for organophosphate synthesis elevate compliance costs for domestic technical-grade manufacturers. Licensed production partnerships in Hebei province supply the bulk of active ingredient volumes to coastal cultivation clusters.
Spain
Almeria's horticultural cooperatives anchor European demand as growers switch from carbofuran amid tightening residue tolerances. ECHA's REACH framework constrains formulation chemistry and buffer zone requirements across member states. Export-oriented tomato operations stockpile conventional liquid concentrates ahead of anticipated EU restriction dates.
United States
Vegetable operations in California's Central Valley and Florida's specialty crop regions specify fosthiazate for nematode management in high-value root systems. EPA FIFRA registration governs tolerances and application rates with updated chronic exposure data requirements delaying label expansions. Turf management contracts for golf courses in the Southeast drive demand for reduced-rate formulations meeting operator exposure standards.
India
Maharashtra and Karnataka greenhouse clusters absorb rising volumes through central government protected cultivation subsidy schemes. Central Insecticides Board registration requirements create procedural delays for new formulation entrants. Direct procurement contracts between large-scale vegetable operations and licensed technical-grade suppliers are expanding fastest in these western and southern corridors.
Japan
Integrated manufacturing operations supply technical-grade material to Asian formulators through established chemical synthesis infrastructure. METI chemical management policies influence regional production standards for organophosphate intermediates. Domestic horticulture applications concentrate in protected strawberry and melon cultivation regions facing Meloidogyne pressure.
Fosthiazate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates holding technical-grade production advantages and regional formulators capturing distribution proximity benefits. The vendor base organizes around three archetypes: multinational agrochemical majors with proprietary formulation platforms, Asian integrated manufacturers with captive synthesis capabilities, and regional distributors with cooperative channel relationships. Consolidation pressure operates through backward integration into phosphorus intermediate supply and forward integration into precision application equipment bundling.
Among multinational agrochemical majors, FMC Corporation and BASF SE occupy positions defined by formulation technology depth and European cooperative distribution reach respectively. Sumitomo Chemical Co., Ltd. anchors the Asian integrated manufacturer tier through established chemical synthesis infrastructure. These three exemplify how technical-grade production control and regulatory registration breadth determine competitive positioning in organophosphate nematicide supply.
| Leading Market Players |
|---|
| FMC Corporation |
| SinoHarvest |
| Sumitomo Chemical Co., Ltd. |
| ADAMA India Private Limited |
| BASF SE |
| ISK |
| Hebei Sannong Agricultural Chemical |
| Veyong |
| Nissan Chemical Corporation |
| Others |
Pricing and Supply Chain Analysis
Phosphorus trichloride feedstock costs cascade through three distinct pricing tiers, with technical-grade manufacturers in Japan and licensed Chinese facilities capturing margin upstream while European formulators absorb REACH compliance premiums downstream. Buyers in China's Shandong province negotiate volume-based contracts that bypass intermediary markups, whereas Spanish cooperatives in Almeria pay certification-driven premiums for reduced-residue formulations.
Pricing Analysis
Volume-based procurement by large-scale vegetable operations in China's protected cultivation corridors competes against margin-focused sales of micro-encapsulated variants to European perennial crop growers. Price differentiation hinges on ECHA registration status and GLOBALG.A.P. certification compliance, with buffer zone reduction authorizations commanding substantial premiums. Pricing pressure stems from energy-linked volatility in thiophosphoryl chloride inputs, compressing formulation margins. Smallholder farmers in India's emerging greenhouse clusters exhibit highest price sensitivity, while Spanish export cooperatives prioritize residue compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with technical-grade production clustered in Japan and Hebei province licensed facilities, creating concentration risk for non-integrated distributors serving Asian markets. Raw material dependencies center on phosphorus trichloride, thiophosphoryl chloride, and specialized organophosphate intermediates sourced from integrated chemical synthesis hubs. Tariff exposure on Chinese-manufactured technical grade elevates landed costs for European formulators. Distribution runs through direct sales to large-scale operators, with regional wholesalers serving fragmented farmer bases in China's interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in technical-grade manufacturing prop pricing power for integrated producers, as phosphorus intermediate capacity expansion lags demand growth from protected cultivation corridors.
For Market Incumbents: Anticipate regulatory divergence between jurisdictions accepting organophosphate nematicides and those accelerating phase-outs, and secure backward integration into phosphorus intermediate supply to defend margin position against feedstock volatility. Prioritize ECHA dossier completion for reduced-buffer-zone formulations ahead of EU restriction timelines. For New Entrants and Emerging Players: Agricultural cooperatives in India's Maharashtra and Karnataka corridors offer the most penetrable entry point, as central government subsidy schemes expand protected cultivation infrastructure without established nematicide supply relationships. Pursue direct procurement contracts with large-scale vegetable operations rather than competing through traditional distribution channels. For Investors and Strategic Acquirers: EPA FIFRA registration maintenance delays for updated chronic exposure data are the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets. Frame long-term viability around technical-grade production control and multi-jurisdiction registration breadth. Target formulators with captive synthesis infrastructure and established REACH dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Intermediates | Captive supply of thiophosphoryl chloride insulates margins from energy-linked feedstock volatility. |
| Micro-Encapsulation Technology Licensing | Polymer shell formulations extend residual control and align with MEE emission standards in China. |
| ECHA Reduced-Buffer-Zone Registration | REACH authorization for low-drift variants captures shelf space as older organophosphates face restriction. |
| Direct Supply Agreements with Almeria Cooperatives | Bypassing traditional distribution markups secures volume commitment from export-oriented tomato growers. |
| India Protected Cultivation Subsidy Alignment | Central government schemes in Maharashtra and Karnataka create first-mover positioning for new registrants. |
Research Methodology
Regulatory filings from EPA and ECHA, customs trade data for organophosphate active ingredients, and technical-grade production records formed the secondary backbone, cross-referenced against primary interviews with formulation R&D directors, procurement leads at Spanish horticultural cooperatives, and distribution channel managers in China's Shandong province. Bottom-up and top-down triangulation validated volume estimates across formulation types and end-use segments.
Bottom-up modeling of application intensity per hectare in protected cultivation systems combined with top-down reconciliation against technical-grade production capacity. Segmentation dimensions included formulation chemistry, crop type, buyer category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of nematode management expenditure patterns across the projection horizon, incorporating MEE emission standard compliance costs and EU Farm to Fork strategy phase-out schedules as industry-specific inputs.
Caveats apply where EPA chronic exposure study completion timelines or ECHA substance evaluation backlogs could materially shift the outlook for label expansions and REACH authorizations. Forecasts reflect assumptions about regulatory divergence persistence and feedstock price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Miticides Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Soybean Fungicide Seed Treatment Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
North America Molluscicides Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Avicides Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Grape Fungicides Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Europe Acaricides Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Seed Treatment Materials Market