
 Prepaid Communication Market | 2026-2036
Prepaid Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Prepaid Communication Market Insights
Retail distribution for prepaid airtime is narrowing as digital channels capture recharge volume. Vodafone leverages its agent network across African and European markets to sustain physical touchpoints. Reliance Jio anchors India's transition with app-exclusive data plans that dominate urban recharge behavior. T-Mobile competes in North America through prepaid subsidiaries that specialize in no-contract flexibility.
Prepaid communication denotes telecommunication services paid in advance through stored-value mechanisms rather than post-billed arrangements, typically involving real-time balance management via USSD codes, mobile applications, or carrier APIs with latency thresholds under 500 milliseconds for transaction confirmation. Mobile Top-Up and Data Plans lead service-type revenue pools, while Digital Vouchers displace Scratch Cards in product-type growth as QR-code redemption reduces last-mile distribution costs. Tourist and Student end-user segments represent the fastest-expanding demand pools, driven by short-stay connectivity needs and campus-bundled offerings respectively.
FCC rules in the United States mandate prepaid disclosure standards that shape carrier pricing transparency, while India's TRAI enforces minimum recharge mandates and tariff reporting that filter market access for new entrants. GDPR in Europe constrains subscriber data usage for personalized prepaid marketing, altering how carriers segment promotional offers. Stakeholders must monitor eSIM certification timelines and interoperability standards as these technical gates determine which product formats retain distribution economics.
Market Dynamics
eSIM certification timelines are compressing physical SIM logistics across carrier supply chains while India's TRAI mandates on minimum recharge thresholds reshape subscriber economics.
Growth Catalysts
- Digital recharge infrastructure:App-based top-up platforms eliminate retail distribution friction in urban India and Southeast Asian metros. Smartphone penetration among young professionals accelerates self-service adoption.
- TRAI tariff reporting mandates:Standardized disclosure requirements in India reduce consumer search costs and expand addressable subscriber bases for transparent pricing models.
- Tourist connectivity demand:Short-stay data bundles for inbound travelers create recurring revenue streams at international arrival hubs in Thailand, Vietnam, and the Philippines.
Market Restraints
- Physical SIM inventory obsolescence:Carrier distribution networks face stranded asset risk as eSIM activation displaces plastic card logistics.
- GDPR marketing constraints:European subscriber data usage restrictions limit personalized promotional segmentation and increase customer acquisition costs.
- QR-code redemption infrastructure:Last-mile digital voucher adoption requires smartphone penetration thresholds that rural distribution networks cannot yet support.
Strategic Opportunities
- Campus-bundled offerings:University partnerships in Indonesia and Malaysia lock in student segments with semester-length data plans.
- FCC disclosure standardization:US prepaid transparency rules create template compliance frameworks exportable to emerging markets.
- API-driven balance management:Real-time USSD alternatives enable embedded finance integrations for underbanked subscriber bases.
Industry Challenges
- eSIM interoperability certification:Fragmented GSMA standards across device manufacturers delay carrier rollout timelines and increase testing overhead.
- Legacy billing system integration:Prepaid real-time balance architectures clash with postpaid heritage IT stacks at established operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepaid Communication Market |
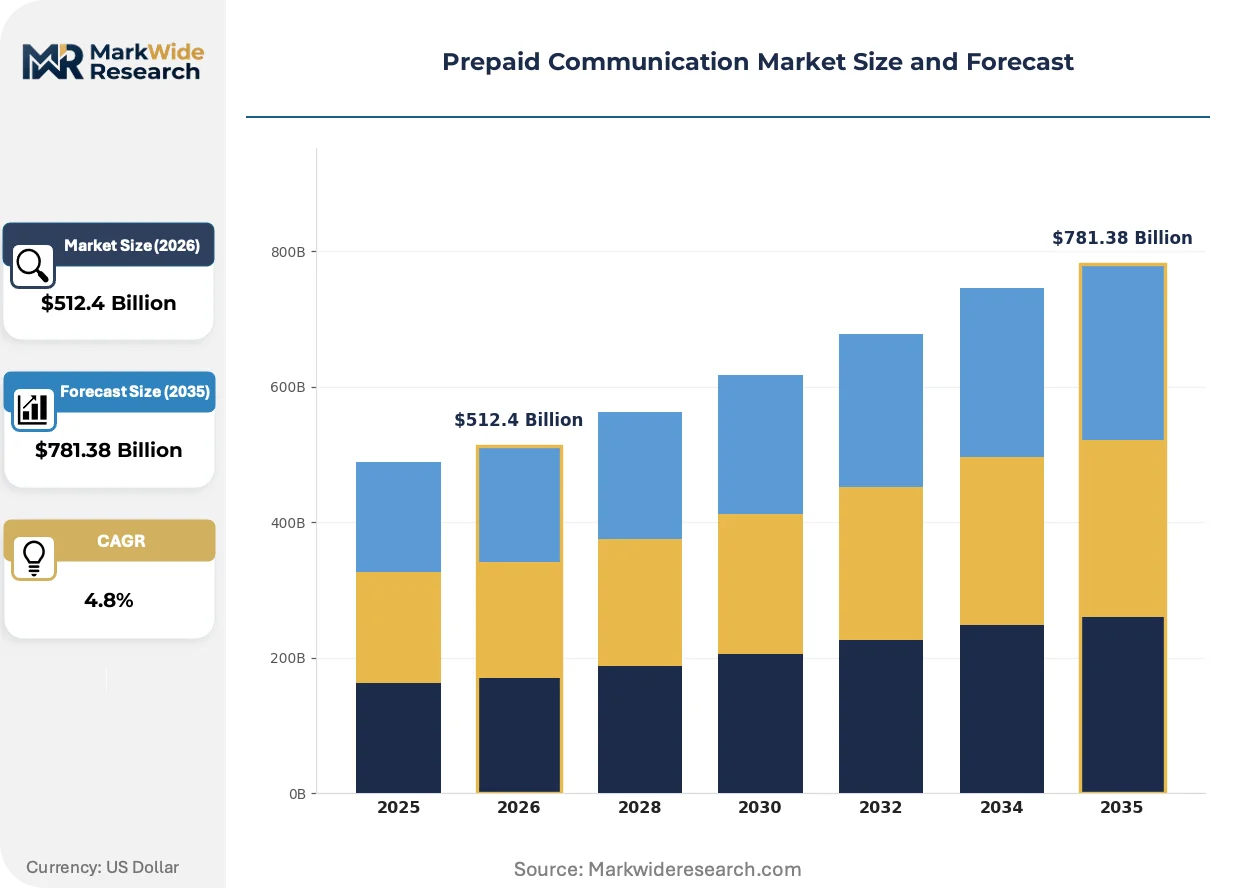
| Market Size in 2026 | $512.4 Billion |
| Market Size in 2035 | $781.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Top-Up, SMS Bundles, Data Plans, Voice Packages Product Type: SIM Cards, E-Wallets, Scratch Cards, Digital Vouchers End User: Individuals, Businesses, Tourists, Students Distribution Channel: Retail Stores, Online Platforms, Convenience Stores, Kiosks |
| Companies Covered | Vodafone, Deutsche Telekom, Verizon, China Mobile, Telefonica, AT&T, Orange, Reliance Jio, T-Mobile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepaid Communication Market Trends and Innovations
Embedded connectivity modules and regulatory transparency mandates are rewiring how subscribers discover, purchase, and exhaust prepaid services across device and distribution touchpoints.
Remote SIM provisioning technology enables over-the-air carrier profile downloads without physical card handling. Smartphone manufacturers across flagship and mid-tier segments are embedding eSIM chips as default hardware. This capability is rendering obsolete the retail logistics networks that previously managed SIM card inventory, warehousing, and point-of-sale activation.
GDPR constraints on subscriber data processing have forced European carriers to rebuild promotional engines around explicit consent frameworks. Marketing automation systems now segment offers through declared preference portals rather than behavioral inference. Prepaid subscribers in Germany and France encounter opt-in data sharing as a condition for personalized tariff recommendations.
Agent-assisted digital recharge is replacing scratch card distribution in African and South Asian markets. Mobile money interoperability allows corner shop vendors to process airtime purchases through unified payment interfaces. Kenya and Bangladesh demonstrate the highest penetration of this hybrid model where physical presence meets digital transaction completion.
Prepaid Communication Market Segmentation
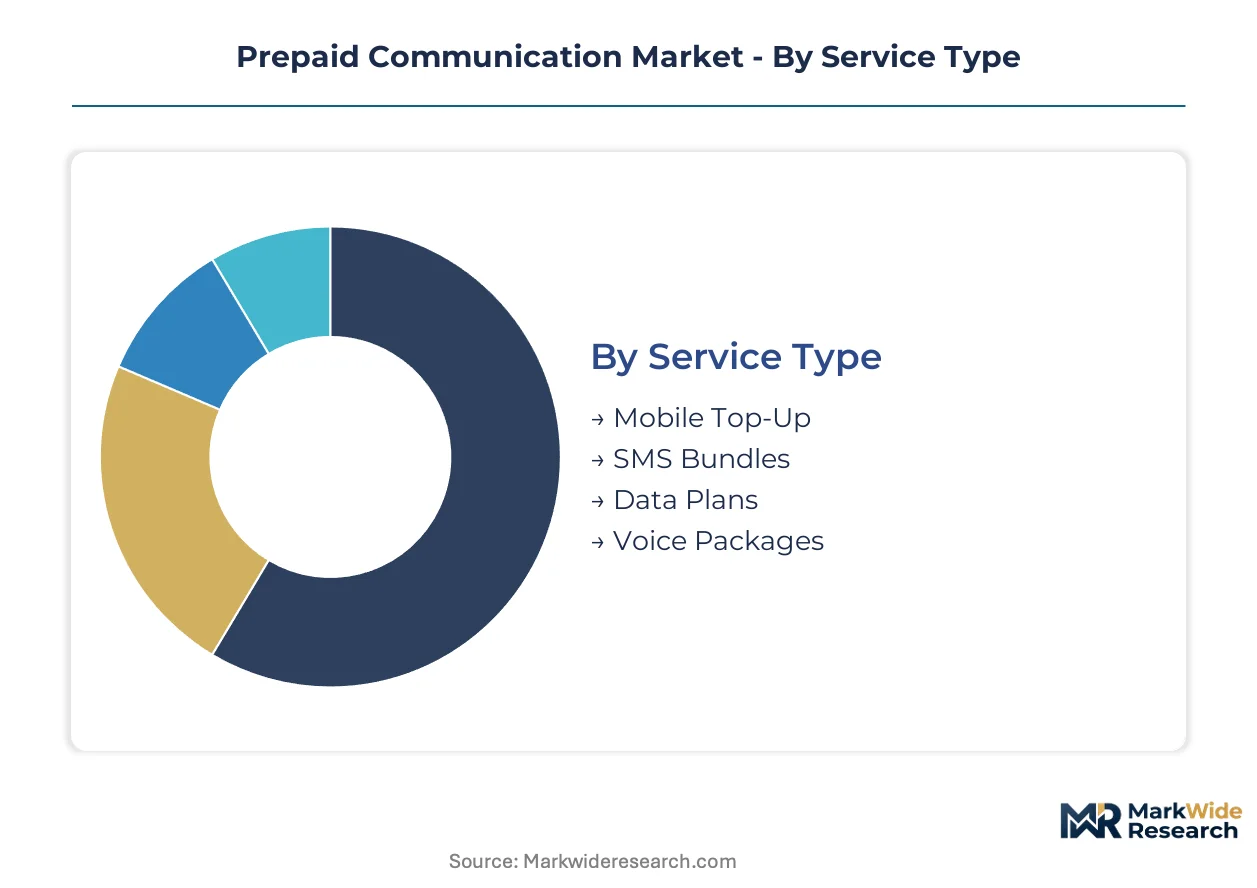
Prepaid communication markets fragment across four structural dimensions that determine pricing power, distribution economics, and subscriber lifetime value. Service and product configurations dictate margin profiles, while end-user composition and channel mix shape regional competitive dynamics.
Service Type:
Mobile Top-Up cycles fastest with daily or weekly replenishment patterns, while Voice Packages turn slowest as bundled minutes extend over 30-day windows.
- Mobile Top-Up:Real-time balance credits applied through USSD codes or carrier APIs with sub-500 millisecond confirmation latency. Urban India and Southeast Asian metros concentrate demand as young professionals manage pay-as-you-go consumption through smartphone self-service interfaces.
- Data Plans:Quota-based mobile internet packages ranging from daily sachets to annual unlimited bundles. Tourist arrivals at Thailand, Vietnam, and Philippines international hubs drive short-stay bundle adoption for inbound connectivity needs.
- SMS Bundles:Text message allotments bundled with voice or data, retaining relevance in emerging markets with lower smartphone penetration.
- Voice Packages:Prepaid minute buckets for domestic and international calling, concentrated among migrant worker remittance corridors and rural subscriber bases.
Mobile Top-Up dominates installed base. Data Plans are where expansion concentrates.
Product Type:
Cost tiers separate physical inventory-heavy formats from zero-marginal-cost digital delivery, with distribution infrastructure requirements driving pricing stratification.
- SIM Cards:Physical plastic cards requiring retail logistics networks for inventory, warehousing, and point-of-sale activation. Carrier distribution networks face stranded asset risk as embedded connectivity modules displace card-based provisioning.
- Digital Vouchers:QR-code or PIN-based electronic redemption mechanisms delivered through mobile money interfaces. Kenya and Bangladesh demonstrate highest penetration where corner shop vendors process airtime through unified payment systems.
- E-Wallets:Stored-value digital accounts linked to carrier billing or third-party financial services, enabling embedded finance integrations for underbanked populations.
- Scratch Cards:Physical prepaid cards with concealed PINs, narrowing in distribution as last-mile digital infrastructure expands in African and South Asian markets.
SIM Cards anchor legacy infrastructure. Digital Vouchers are gaining share fastest.
End User:
Customer type determines average revenue per user and churn sensitivity, with institutional contracts stabilizing revenue against individual subscriber volatility.
- Individuals:Mass-market prepaid subscribers managing personal communication expenses through self-directed recharge behavior. India's TRAI minimum recharge mandates reshape subscriber economics and reduce inactive account accumulation.
- Tourists:Short-stay inbound travelers purchasing temporary connectivity at arrival infrastructure. Thailand, Vietnam, and Philippines airport kiosks and hotel partnerships capture this demand pool.
- Students:Campus-affiliated subscribers targeted through university partnerships with semester-length data plans. Indonesia and Malaysia demonstrate concentrated carrier investment in educational institution alliances.
- Businesses:Corporate prepaid accounts for field staff, delivery fleets, and temporary workforce connectivity, requiring centralized balance management and usage reporting.
Individuals represent the largest addressable base. Tourists show the steepest expansion trajectory.
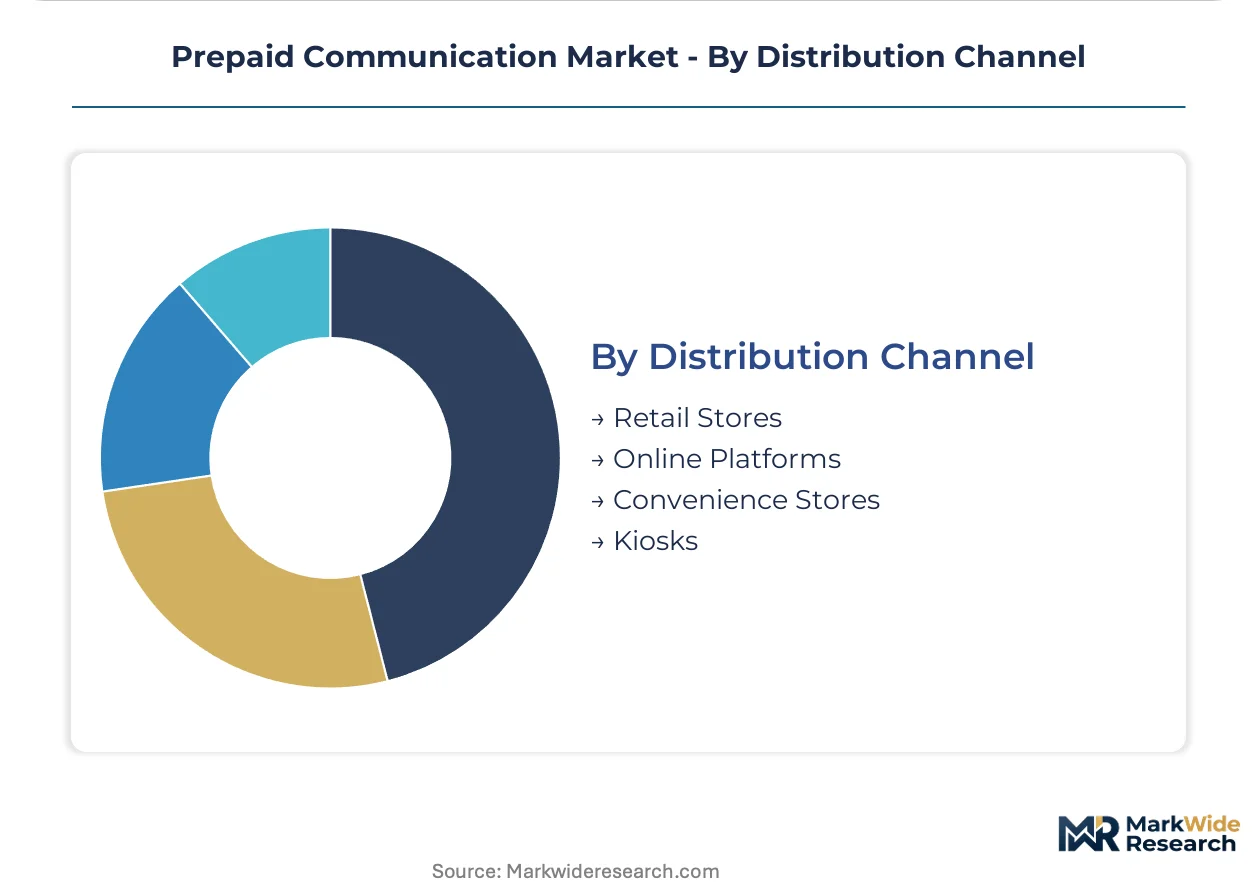
Distribution Channel:
Channel concentration varies with urban density and digital payment penetration, determining carrier customer acquisition cost structures.
- Online Platforms:App-based and web-based recharge interfaces eliminating retail friction. Reliance Jio's digital infrastructure in India exemplifies app-exclusive plan distribution dominating urban recharge behavior.
- Retail Stores:Branded carrier outlets and multi-brand mobile shops providing physical touchpoints for SIM activation and account management. Vodafone sustains this channel across African and European markets through agent network density.
- Convenience Stores:Neighborhood shops processing digital voucher redemption through mobile money interoperability, prevalent in Kenya and Bangladesh hybrid distribution models.
- Kiosks:Automated self-service terminals at transport hubs and commercial centers, concentrated in high-footfall tourist and commuter corridors.
Retail Stores maintain widest geographic coverage. Online Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The undersea cable landing stations at Chennai, Mumbai, and Cochin anchor India's role as the data throughput hub for South Asian prepaid traffic.
India
Reliance Jio's digital recharge infrastructure and TRAI's minimum recharge mandates reshape subscriber economics. TRAI tariff reporting requirements reduce consumer search costs and expand addressable bases. Mumbai and Delhi-NCR concentrate carrier investment in app-exclusive data plan distribution.
United States
T-Mobile's prepaid subsidiaries and Verizon's no-contract offerings compete for mobile-first workforces. FCC disclosure standards mandate pricing transparency that shapes carrier promotional frameworks. California and Texas metros lead eSIM activation adoption among young professional segments.
Germany
Deutsche Telekom's hybrid retail-digital channels sustain physical touchpoints alongside app-based recharge. GDPR constraints force promotional engines to rebuild around explicit consent frameworks. Berlin and Munich cluster carrier investment in opt-in data sharing portals for personalized tariff recommendations.
Thailand
Tourist connectivity demand at Bangkok Suvarnabhumi and Phuket International drives short-stay data bundle adoption. National telecom regulators enforce SIM registration mandates that filter market access. Bangkok and Pattaya concentrate airport kiosk and hotel partnership networks for inbound traveler segments.
Kenya
Agent-assisted digital recharge through M-Pesa interoperability eliminates scratch card distribution friction. Central bank mobile money regulations shape carrier-bank partnership architectures. Nairobi and Mombasa demonstrate the highest penetration of hybrid physical-digital distribution models.
Prepaid Communication Market Competitive Landscape
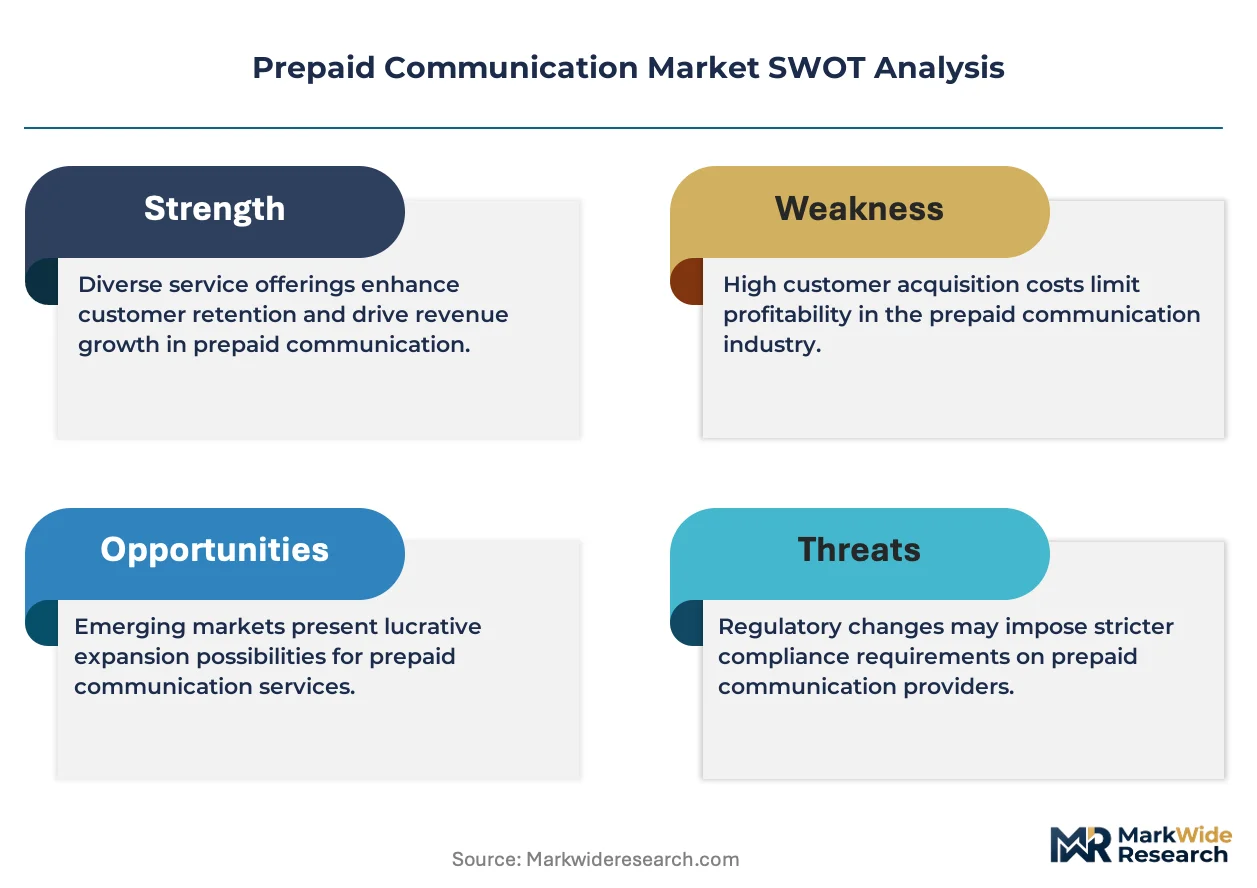
Platform integrators command the system tier; component specialists sit upstream in recharge infrastructure and SIM provisioning. The prepaid communication market structures around tiered carrier scale, with pan-regional operators, national champions, and digital-native entrants occupying distinct competitive bands. Three archetypes dominate: legacy carriers with hybrid retail-digital networks, app-first challengers with zero-touch distribution, and mobile money-integrated operators in emerging markets. Dominant competitive moves include eSIM certification acceleration and API-driven balance management partnerships with fintech platforms.
Among European-headquartered carriers, Deutsche Telekom AG, Vodafone Group Plc, and Orange S.A. exemplify the pan-regional platform tier with integrated infrastructure across multiple continents. Reliance Jio Platforms Limited occupies a distinct position as the digital-native archetype with app-exclusive distribution. T-Mobile US, Inc. represents the no-contract specialization vector in North American prepaid segments.
| Leading Market Players |
|---|
| Vodafone |
| Deutsche Telekom |
| Verizon |
| China Mobile |
| Telefonica |
| AT&T |
| Orange |
| Reliance Jio |
| T-Mobile |
| Others |
Pricing and Supply Chain Analysis
Undersea cable landing stations at Chennai, Mumbai, and Cochin anchor India's data throughput dominance, compressing international bandwidth costs for carriers while enabling sharp price differentiation between metro and rural recharge tiers. This infrastructure concentration grants Reliance Jio and Bharti Airtel procurement leverage over smaller competitors, feeding downstream pricing power that stratifies across premium unlimited plans, standard data buckets, and economy voice-centric offerings.
Pricing Analysis
Volume-discount tiering structures dominate as carriers segment prepaid offerings across daily sachets, monthly bundles, and annual unlimited plans. Price differentiation hinges on data quota ceilings and app-exclusive distribution access, with urban young professionals showing lowest price sensitivity for convenience-integrated recharge while rural subscribers concentrate in economy tiers. Pricing pressure intensifies from TRAI's minimum recharge mandates, which force carriers to absorb churn costs from low-ARPU accounts rather than pass through to active subscribers.
Supply Chain Analysis
Tariff exposure between China and India for eSIM chip components dominates supply risk calculus as embedded connectivity modules displace plastic SIM logistics. Manufacturing concentrates in China, Taiwan, and Vietnam for semiconductor substrates, while carrier distribution networks in India, Kenya, and Bangladesh draw from mobile money interoperability standards rather than physical inventory. Single-source vulnerability in GSMA certification testing facilities creates bottleneck risk, with distribution running through hybrid agent-assisted digital channels that merge corner shop presence with real-time transaction completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prepaid communication markets read as service-attach opportunities where digital recharge infrastructure and API-driven balance management expand faster than hardware-centric distribution. Recurring revenue layers from embedded finance integrations and tourist bundle subscriptions outpace SIM card margin erosion.
For Market Incumbents: Harden digital recharge infrastructure against eSIM-native challengers by accelerating API partnerships with mobile money platforms. Lock in campus and tourist segments through exclusive semester-length and short-stay bundle contracts that raise switching costs. Vertical integration into embedded finance modules preserves margin as physical SIM distribution economics deteriorate. For New Entrants and Emerging Players: Rural India's QR-code redemption gaps present the most penetrable white space, where smartphone penetration thresholds exclude incumbent digital voucher rollouts. Target agent-assisted hybrid models that leverage existing corner shop networks without requiring full-stack infrastructure build. Go-to-market through university partnership templates proven in Indonesia and Malaysia accelerates student segment capture with minimal customer acquisition cost. For Investors and Strategic Acquirers: API-first recharge infrastructure specialists with fintech integration capabilities represent the priority acquisition archetype for portfolio exposure to embedded finance convergence. Long-term viability centers on carriers that control subscriber data consent frameworks compliant with GDPR and emerging TRAI privacy mandates. Watch eSIM interoperability certification timelines as the inflection signal determining which provisioning formats retain distribution economics.| Strategic Initiative | Industry Significance |
|---|---|
| eSIM Certification Acceleration | GSMA compliance timelines determine carrier rollout speed against physical SIM incumbents. |
| Mobile Money API Integration | M-Pesa interoperability in Kenya demonstrates embedded finance attach rates for underbanked segments. |
| Campus Partnership Expansion | Indonesia's university alliances lock in semester-length subscriber bases with predictable churn profiles. |
| Tourist Bundle Localization | Thailand's airport kiosk networks capture inbound connectivity demand at arrival infrastructure. |
| TRAI Compliance Investment | Minimum recharge mandate adherence filters market access for transparent pricing models. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of TRAI tariff filings, GSMA certification databases, and mobile money interoperability standards across India, Kenya, and Bangladesh. Carrier network planning executives, mobile money platform engineers, and regulatory compliance officers at telecommunications authorities provided operational validation. Bottom-up subscriber behavior modeling triangulates against top-down carrier revenue disclosures from SEC filings and exchange disclosures.
Forecast inputs span service type segmentation across Mobile Top-Up, Data Plans, SMS Bundles, and Voice Packages; product type trajectories from physical SIM cards through Digital Vouchers and E-Wallets; end-user composition across Individuals, Tourists, Students, and Businesses; and distribution channel evolution from Retail Stores through Online Platforms. CAGRs derive from installed base projections calibrated against smartphone penetration curves and eSIM adoption timelines. Regulatory mandate implementation schedules and international tourist arrival patterns inform demand elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by eSIM-native digital challengers or mobile money platform consolidators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Smart Feature Phone Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Ireland Telecom Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Fixed Voice Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
China ICT Market
Telecommunications
Qatar Telecom Market
Telecommunications
Telecom API Platform Market
Telecommunications
Angola Telecom Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Diameter Signaling Market
Telecommunications
Vietnam Telecom Market