
 Nigeria Telecom Market | 2026-2036
Nigeria Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Telecom Market Outlook
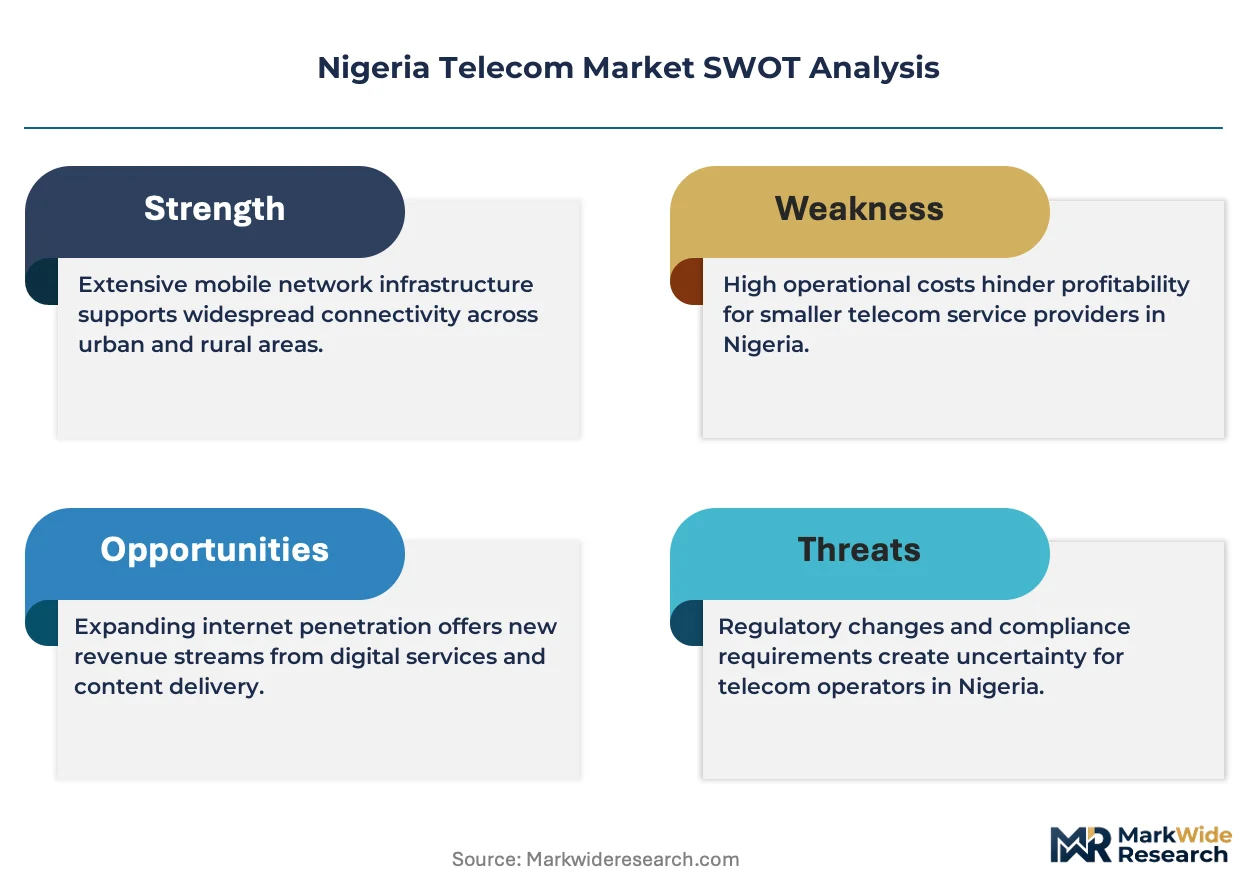
Nigeria's National Broadband Plan is decoupling infrastructure investment from pure subscriber-volume metrics, forcing operators to prioritize coverage depth over urban density. MTN Nigeria leverages its extensive fiber backbone to sustain rural expansion programs. Airtel Nigeria anchors its competitive stance through aggressive data pricing and mobile money integration. Globacom differentiates via indigenous submarine cable ownership and domestic spectrum holdings.
Nigeria Telecom encompasses the provision of electronic communication services through wireless and wireline infrastructure operating across radio frequency spectrum, fiber-optic backhaul, and IP-based core networks with throughput parameters measured in megabits per gigabits per second. These systems enable voice transmission, packet-switched data delivery, and multimedia broadcasting for consumer, commercial, and institutional end users. Data services now command the dominant revenue share as smartphone penetration deepens, while Value-Added Services including mobile financial platforms and content streaming represent the fastest-expanding margin pool. 4G technology still carries the bulk of subscriber traffic, though 5G infrastructure deployment is accelerating in Abuja and Port Harcourt corridors.
The Nigerian Communications Commission licenses spectrum and enforces quality-of-service benchmarks, while the National Information Technology Development Agency shapes cybersecurity compliance frameworks for operators. The Central Bank of Nigeria coordinates mobile money interoperability rules that directly determine telco fintech revenue streams. Stakeholders must monitor spectrum auction timelines and tower-sharing regulations to calibrate capital allocation between rural coverage obligations and enterprise 5G monetization.
Market Dynamics
Nigeria's National Broadband Plan is forcing infrastructure investment toward rural 3G coverage mandates, decoupling capital allocation from subscriber-volume metrics and prioritizing geographic depth over urban density.
Growth Catalysts
- Spectrum Policy:The Nigerian Communications Commission's universal 3G coverage mandate for underserved local government areas creates guaranteed demand pools for rural network rollout.
- Mobile Financial Services:Central Bank of Nigeria interoperability rules for mobile money platforms generate direct revenue streams for operators integrating fintech into core service bundles.
- Rural Banking Adoption:Smallholder farmers in remote agricultural zones are adopting mobile banking at accelerating rates, creating subscriber bases outside saturated urban corridors.
Market Restraints
- Diesel Cost Volatility:Tower operators depend on diesel generators for 73% of rural base station power, exposing opex to petroleum price swings and currency depreciation.
- Right-of-Way Friction:State and local governments impose inconsistent fees for fiber trenching, fragmenting national backbone deployment timelines.
- Device Affordability Ceiling:Sub-$50 smartphone scarcity limits 4G adoption among price-sensitive subscribers in northern states.
Strategic Opportunities
- South-East Geopolitical Zone:This corridor shows concentrated demand growth with underserved infrastructure relative to Lagos, offering first-mover expansion potential.
- Enterprise 5G Monetization:Abuja and Port Harcourt corridors present early enterprise verticals for fixed wireless access and industrial IoT applications.
- Tower-Sharing Regulations:Infrastructure sharing mandates reduce duplicate capital deployment and improve rural site economics for multi-tenant operators.
Industry Challenges
- Fiber Splicing Technician Scarcity:Skilled field crews for last-mile fiber deployment are concentrated in Lagos, creating recruitment bottlenecks for northern expansion programs.
- Legacy 2G Switch-Off Coordination:Decommissioning aging circuit-switched infrastructure while maintaining rural voice service continuity requires complex subscriber migration management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Telecom Market |
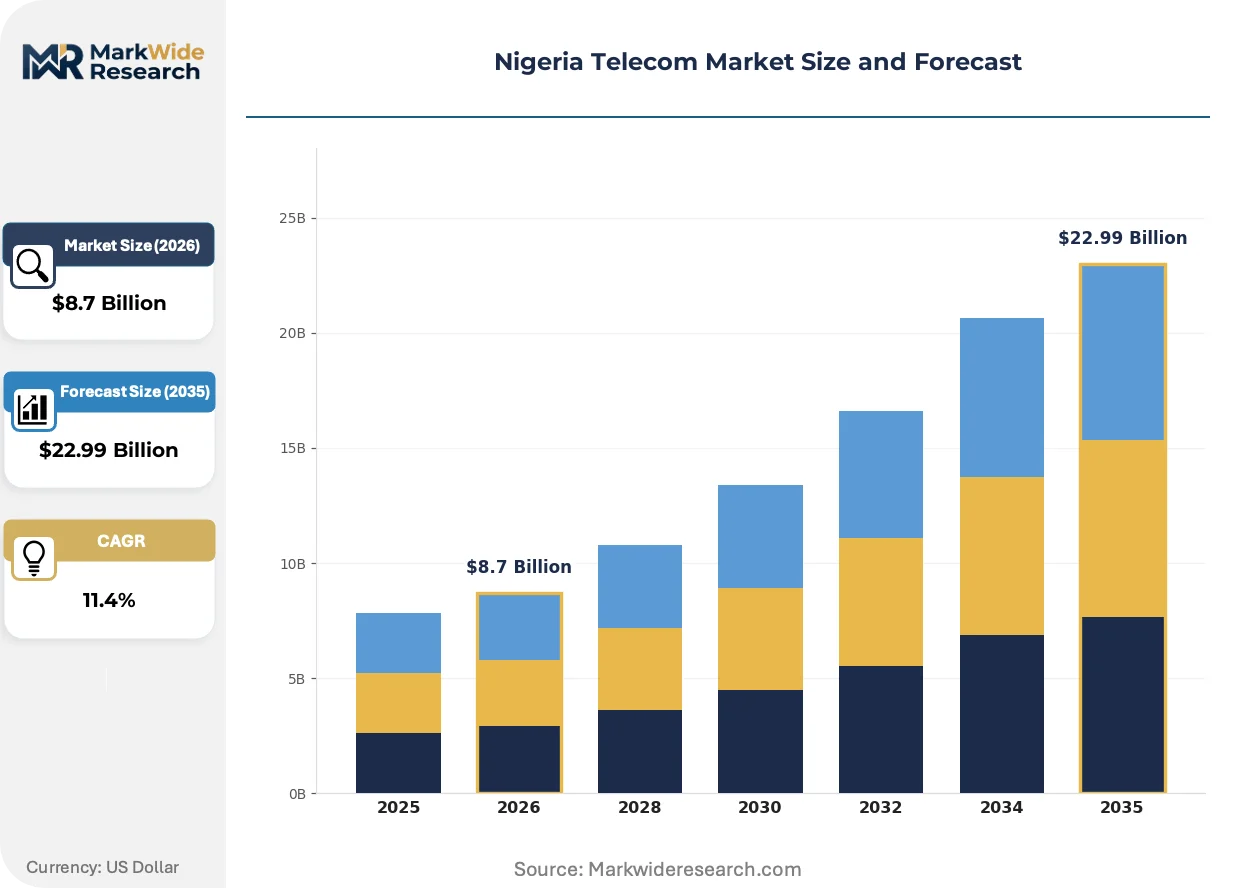
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, SMS, Data, Value-Added Services Technology: 4G, 5G, GSM, CDMA Customer Type: Residential, Business, Government, Enterprise Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Agents |
| Companies Covered | MTN Nigeria, Airtel Nigeria, Globacom, 9mobile, Smile Communications Nigeria, Mafab Communications, ipNX Nigeria, Tizeti Network, Main One Cable, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Telecom Market Strategic Shifts
Convergence between telecom infrastructure and financial services platforms is redefining operator business models, with data services and value-added platforms displacing voice as the primary revenue architecture.
Network function virtualization is unifying core network operations across radio access, packet core, and subscriber management layers. Tier-one operators in Lagos and Abuja are deploying cloud-native architectures to compress hardware refresh cycles. This unification enables faster service provisioning for enterprise customers while reducing physical infrastructure footprints in expensive urban real estate.
The Nigerian Communications Commission's quality-of-service benchmarks are tightening latency and call-drop thresholds for licensed operators. These enforcement mechanisms are accelerating capital flows toward transmission network upgrades. Mobile financial service providers face the steepest compliance costs as transaction reliability standards tighten.
Smallholder farmers are consolidating mobile banking relationships with single providers, reducing multi-SIM behavior that previously fragmented average revenue per user. Agent network density in rural Kebbi and Kaduna corridors is displacing branch-based microfinance access. This behavioral shift concentrates subscriber lifetime value for operators with established rural agent footprints.
Nigeria Telecom Market Segmentation
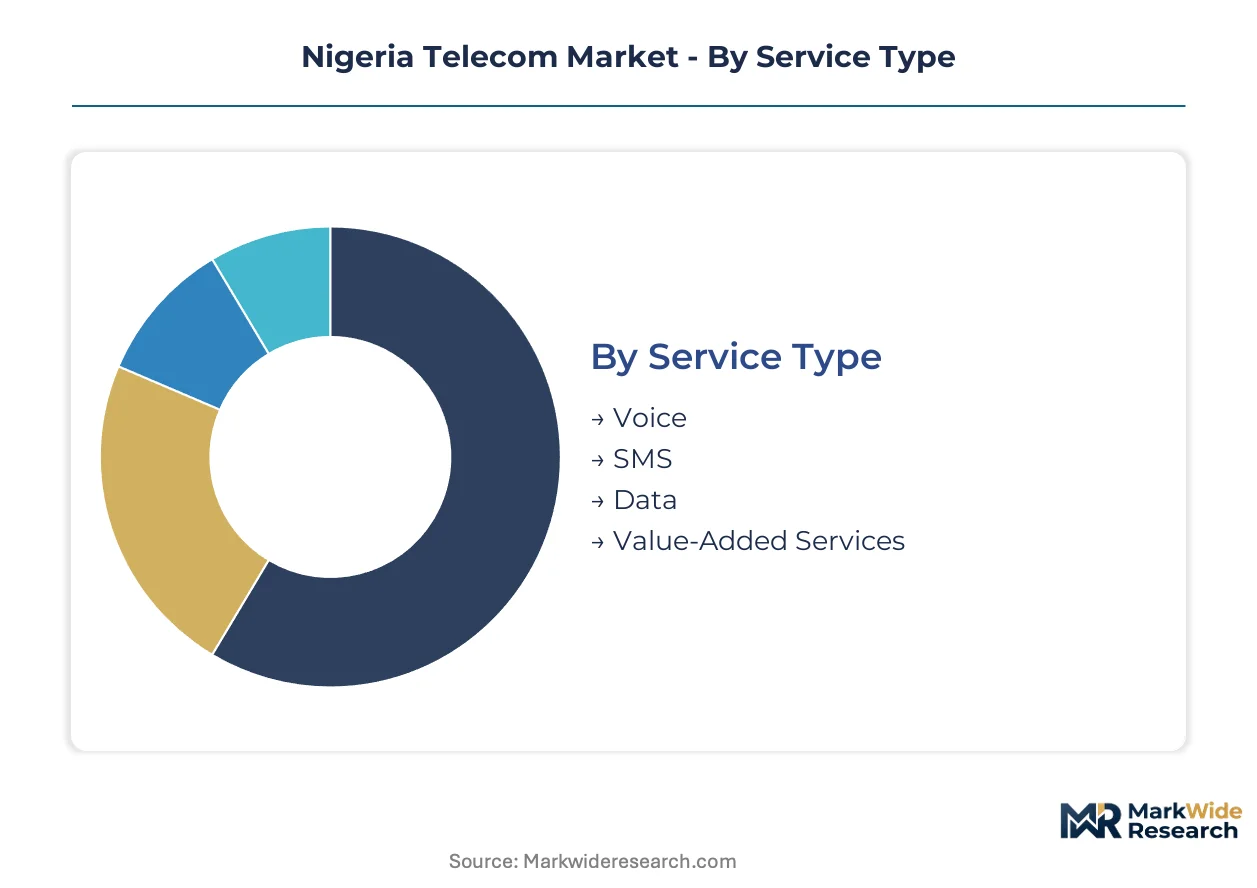
Nigeria's telecom market stratification reveals how infrastructure investment priorities diverge across revenue architectures. Service type and technology segments show the clearest divergence between mature urban monetization and mandated rural coverage obligations.
Service Type:
Supply concentration in data transmission infrastructure has shifted operator capex toward packet-switched networks, decoupling revenue generation from circuit-switched legacy systems.
- Voice:Circuit-switched services still generate substantial traffic volume in northern states where 2G infrastructure dominates subscriber equipment profiles. The Nigerian Communications Commission's universal coverage mandates preserve voice as a baseline service tier despite declining per-minute yields.
- Data:Packet-switched broadband services command the dominant revenue share as smartphone penetration deepens in Lagos State and South-East corridors. MTN Nigeria and Airtel anchor competitive positioning through tiered data bundles targeting streaming and mobile banking applications.
- SMS:Text messaging persists as a fallback channel for financial transaction alerts and authentication protocols in areas with intermittent data connectivity. Revenue contribution has flattened as over-the-top messaging platforms displace person-to-person traffic.
- Value-Added Services:Mobile financial platforms and content streaming represent the expanding margin pool, with Central Bank of Nigeria interoperability rules determining fintech revenue accessibility for integrated operators.
Today's leader: Data. Tomorrow's challenger: Value-Added Services.
Technology:
Equipment vendor relationships and spectrum license holdings concentrate competitive advantage among operators with early 4G rollout experience and 5G pioneer spectrum allocations.
- 4G:LTE networks carry the bulk of subscriber traffic nationwide, with infrastructure deployment concentrated in Lagos, Abuja, and Port Harcourt corridors. Equipment refresh cycles and fiber backhaul density determine quality-of-service differentiation.
- 5G:Fixed wireless access and industrial IoT applications are accelerating deployment in enterprise zones, though subscriber device scarcity limits mass-market penetration outside premium urban segments. Abuja and Port Harcourt corridors anchor early monetization trials.
- GSM:Second-generation infrastructure maintains voice service continuity in rural Kebbi and Kaduna corridors where National Broadband Plan mandates require 3G-equivalent coverage depth.
- CDMA:Code-division multiple access networks persist in legacy enterprise installations and specialized fixed-wireless configurations, though subscriber migration programs are decommissioning consumer-facing deployments.
The installed base tilts toward 4G. The capital pipeline flows toward 5G.
Customer Type:
Account management complexity and contract value concentration shape how operators structure sales organizations and service level agreements across subscriber tiers.
- Residential:Individual subscribers dominate volume metrics, with demand concentrating in prepaid data bundles and mobile money integration. Smallholder farmers in remote agricultural zones are consolidating banking relationships with single providers, reducing multi-SIM fragmentation.
- Business:Small and medium enterprises require managed connectivity with predictable uptime guarantees, driving demand for service level agreements with latency and packet-loss thresholds enforced by Nigerian Communications Commission benchmarks.
- Government:Public sector contracts for administrative connectivity and emergency communications infrastructure carry extended payment cycles but provide anchor tenancy for rural network economics.
- Enterprise:Large corporate accounts demand dedicated fiber access and private network configurations, with fixed wireless access emerging as a competitive alternative to terrestrial fiber in Port Harcourt industrial corridors.
Residential volume funds the network. Enterprise yield justifies the upgrade.
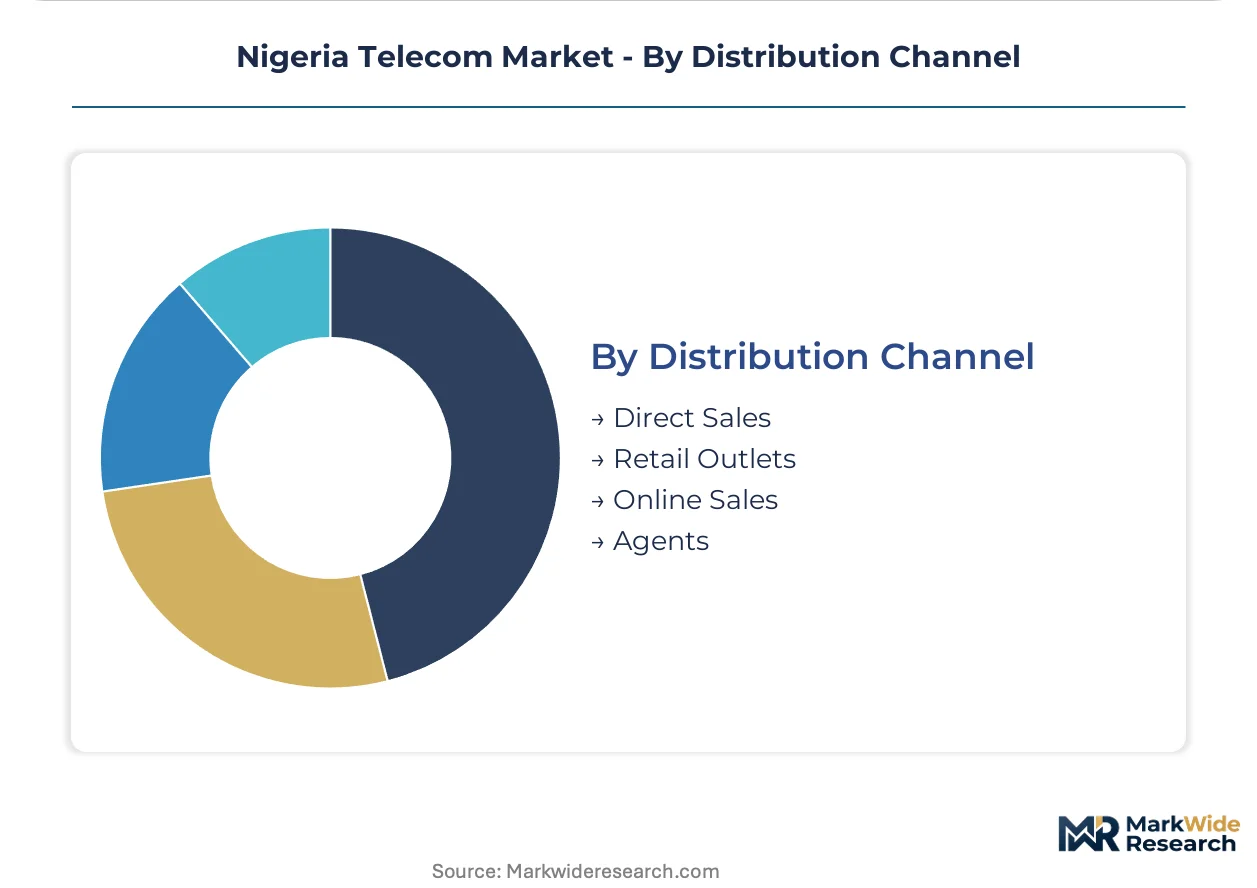
Distribution Channel:
Physical presence density in underserved local government areas determines subscriber acquisition cost and mobile money agent network viability.
- Direct Sales:Corporate account teams target enterprise and government segments with customized connectivity proposals and dedicated technical support resources.
- Retail Outlets:Branded storefronts in Lagos and South-East urban centers provide device financing and plan migration services for smartphone upgraders.
- Online Sales:Digital self-service platforms reduce subscriber acquisition costs for data plan activations among urban smartphone users with established banking relationships.
- Agents:Commission-based agent networks in rural Kebbi and Kaduna corridors displace branch-based microfinance access, concentrating subscriber lifetime value for operators with established rural footprints.
Urban efficiency favors online. Rural penetration requires agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's telecom sector traces its modern lineage to the 2001 liberalization that dismantled state monopoly and licensed private mobile operators. Infrastructure investment has since concentrated in southern commercial corridors while regulatory mandates now force geographic expansion into underserved northern and eastern territories.
Lagos State
Smartphone penetration and mobile banking adoption drive data consumption at levels unmatched elsewhere in Nigeria. The Nigerian Communications Commission enforces quality-of-service benchmarks that accelerate fiber backhaul deployment. Ikeja and Lekki industrial clusters host dense tower concentrations serving enterprise customers with dedicated connectivity agreements.
South-East Geopolitical Zone
Enugu and Anambra states exhibit concentrated demand growth with infrastructure deficits relative to subscriber density. National Broadband Plan mandates require operators to achieve 3G-equivalent coverage depth in these corridors. Aba's manufacturing hub generates enterprise connectivity requirements that outpace current fixed wireless and fiber penetration.
Federal Capital Territory
Abuja anchors early 5G deployment trials targeting government and diplomatic institutional clients. The Central Bank of Nigeria coordinates mobile money interoperability rules that determine fintech revenue accessibility for operators serving administrative districts. Jukwoyi and Kubwa satellite towns present fixed wireless access opportunities as alternatives to terrestrial fiber deployment.
Kebbi and Kaduna Corridors
Smallholder farmers in these northern agricultural zones are consolidating mobile banking relationships with single providers. Agent network density displaces branch-based microfinance access in rural local government areas. Diesel-dependent tower operations face petroleum price volatility that strains opex economics for base station power generation.
Port Harcourt Industrial Corridor
Rivers State's oil and gas infrastructure demands private network configurations and industrial IoT connectivity. Fixed wireless access emerges as a competitive alternative to fiber trenching where right-of-way fees fragment deployment timelines. Onne and Trans Amadi industrial zones require latency-sensitive connections for operational technology integration.
Nigeria Telecom Market Competitive Environment
Capital-heavy infrastructure owners compete with asset-light service resellers for subscriber relationships and enterprise contracts. The market structure consolidates around four mobile network operators with national spectrum licenses, while niche fixed wireless and fiber specialists fragment the broadband segment. Strategic archetypes separate spectrum-rich incumbents with rural coverage obligations from agile data-only challengers and infrastructure-neutral virtual operators. Dominant competitive moves include tower-sharing partnerships to reduce duplicate capital deployment and mobile money integration to capture fintech revenue streams.
Among Nigeria-based mobile operators, MTN Nigeria, Airtel Nigeria, and Globacom represent the incumbent tier with established rural agent networks and fiber backbone assets. These operators exemplify the spectrum-integrated archetype that combines radio access infrastructure with financial services platforms. MTN Nigeria occupies a position emphasizing extensive fiber backhaul for rural expansion, Airtel Nigeria anchors aggressive data pricing and mobile money integration, while Globacom sits within the indigenous submarine cable ownership model with domestic spectrum holdings. Each represents a distinct competitive response to National Broadband Plan mandates and Central Bank of Nigeria interoperability requirements.
| Leading Market Players |
|---|
| MTN Nigeria |
| Airtel Nigeria |
| Globacom |
| 9mobile |
| Smile Communications Nigeria |
| Mafab Communications |
| ipNX Nigeria |
| Tizeti Network |
| Main One Cable |
| Others |
Value Chain & Pricing Dynamics
Smallholder farmers in northern agricultural zones anchor demand concentration for entry-level data bundles, locking operators into prepaid voucher pricing models with thin margins on sub-50-naira denominations. This buyer archetype concentration forces pricing stratification that subsidizes rural connectivity through premium urban tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise SLA-backed contracts from mass-market data bundles and voice-centric prepaid vouchers. Price differentiation hinges on fiber backhaul density and quality-of-service tier enforcement by the Nigerian Communications Commission. Pricing pressure stems from diesel cost volatility straining rural base station opex, compressing margins in economy tiers. Smallholder farmers exhibit acute price sensitivity, while enterprise customers in Lagos and Port Harcourt tolerate premium rates for latency guarantees.
Supply Chain Analysis
Refurbished base station equipment and remanufactured power systems flow from decommissioned European and Asian networks into Nigerian secondary markets, extending asset lifecycles for cost-constrained rural deployments. Equipment manufacturing concentrates in China, South Korea, and Finland, with radio access unit assembly tethered to semiconductor fabrication in Taiwan. Supply chain risk centers on single-source dependency for 5G massive MIMO antennas and baseband processing chips. Distribution runs through Lagos-based system integrators with last-mile logistics to tower operators nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigeria's telecom sector functions as a regulatory compounder, with National Broadband Plan mandates and Central Bank of Nigeria interoperability rules generating structural demand for rural infrastructure and fintech integration.
For Market Incumbents: Acquire dormant spectrum holdings from distressed operators to consolidate radio access capacity in South-East corridors threatened by Mafab Communications' 5G rollout. Prioritize backward integration into captive solar-battery hybrid power systems to neutralize diesel cost volatility eroding rural site economics. For New Entrants and Emerging Players: Capture fixed wireless access white space in Abuja satellite towns and Port Harcourt industrial zones where terrestrial fiber deployment faces right-of-way friction. Target enterprise verticals with latency-sensitive operational technology requirements, leveraging cloud-native core architectures to compress provisioning timelines against incumbent hardware refresh cycles. For Investors and Strategic Acquirers: Tower operators with established multi-tenant rural portfolios are the most active acquirer category in this space, consolidating passive infrastructure assets ahead of infrastructure sharing mandate enforcement. Monitor spectrum auction timelines and diesel subsidy policy shifts as inflection indicators for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Rural 3G Coverage Expansion | Nigerian Communications Commission mandates guarantee demand pools in underserved local government areas. |
| Mobile Money Platform Integration | Central Bank of Nigeria interoperability rules unlock fintech revenue streams for integrated operators. |
| Tower-Sharing Partnership Formation | Multi-tenant site economics improve capital efficiency for mandated geographic expansion programs. |
| Fiber Backhaul Density Investment | Quality-of-service benchmarks enforce latency thresholds requiring transmission network upgrades. |
| Enterprise 5G Fixed Wireless Access | Abuja and Port Harcourt corridors present early monetization trials for industrial IoT applications. |
Study Parameters
Coverage spans Nigeria's six geopolitical zones, with primary inputs from each informing demand calibration and infrastructure deployment timelines. Interviews with Nigerian Communications Commission regulatory officers, MTN Nigeria and Airtel network planning executives, tower operator procurement leads, and rural agent network coordinators combined with secondary validation from NCC annual reports, Central Bank of Nigeria payment system statistics, and operator SEC filings. Bottom-up subscriber and revenue modeling triangulated against top-down macroeconomic projections.
Rate-of-change decomposition separates volume growth from yield compression across the projection horizon. Segmentation dimensions include service type, technology generation, customer tier, and distribution channel, with rural-urban digital divide metrics as a Nigeria-specific overlay. CAGRs derived from subscriber penetration curves, data consumption trajectories, and fintech transaction velocity. Forecast inputs incorporate National Broadband Plan milestone schedules and spectrum auction pipeline assumptions.
Underlying measurement precision varies by segment; Lagos State and South-East corridor data carry tighter precision than northern agricultural zone estimates due to informality in rural subscriber reporting. Forecasts reflect documented assumptions on regulatory enforcement timelines and diesel price normalization. Practitioners should monitor right-of-way fee harmonization progress and 5G device affordability thresholds for early signals of infrastructure deployment acceleration or delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Diameter Signaling Market
Telecommunications
Argentina Telecom Market
Telecommunications
Cloud RAN Market
Telecommunications
5G in Defense Market
Telecommunications
Global Telecommunication Market
Telecommunications
Myanmar Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Broadband Services Market
Telecommunications
South Korea Telecom Market
Telecommunications
Mobile Voice Market
Telecommunications
Global LTE Market
Telecommunications
Myanmar ICT Market
Telecommunications
Video Door Phones Market
Telecommunications
Private Branch Exchange Market
Telecommunications
North America Underwater Communication Systems Market