
 Global 5G Base Station Market | 2026-2036
Global 5G Base Station Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G Base Station Market Foresight
The EU Green Deal is recalibrating energy-efficiency requirements for network infrastructure across European member states. Huawei Technologies leverages its integrated chipset-to-antenna portfolio to sustain cost leadership in macro cell deployments. Nokia anchors its position through specialized massive MIMO R&D programs targeting dense urban environments. Samsung Electronics dominates the South Korean market while extending its Open RAN footprint into North American carrier trials.
A 5G base station comprises radio units, baseband processing equipment, and antenna arrays operating across sub-6 GHz and mmWave spectrum bands with throughput capacities exceeding 10 Gbps in optimized configurations. These installations enable ultra-reliable low-latency communication for autonomous systems, industrial automation, and enhanced mobile broadband services. Macro cells currently occupy the largest share of deployed infrastructure value due to their wide-area coverage requirements, while small cells represent the fastest-expanding product category as operators densify networks for capacity in urban corridors. Cloud RAN technology is gaining structural importance as carriers virtualize baseband functions to reduce site power consumption and enable centralized network management.
The Federal Communications Commission in the United States, the Ministry of Industry and Information Technology in China, and the European Telecommunications Standards Institute collectively shape spectrum allocation, equipment certification, and cross-border interoperability mandates that determine vendor market access. Japan's Ministry of Economy, Trade and Industry has established specific power-efficiency benchmarks for 5G infrastructure that influence procurement specifications across Asia-Pacific markets. Stakeholders must monitor evolving Open RAN interoperability standards and national security review frameworks as these mechanisms increasingly determine supplier eligibility in major economies.
Market Dynamics
Open RAN architecture mandates and national security screening frameworks are fragmenting vendor eligibility across major economies, forcing telecommunications operators to dual-source equipment and accelerate qualification timelines for second-tier suppliers.
Growth Catalysts
- Industrial IoT connectivity mandates:Manufacturing automation in Germany and South Korea requires ultra-reliable low-latency networks that only 5G macro cells can deliver.
- EU AI Act infrastructure requirements:Real-time data processing for autonomous systems compels edge computing deployments co-located with base station sites.
- Mid-band spectrum releases:The FCC's C-band auctions and comparable allocations by Japan's MIC expand addressable coverage area per installed cell.
Market Restraints
- GaN-on-SiC substrate concentration:Power amplifier chip supply depends on a concentrated wafer fabrication base in East Asia, exposing procurement to geopolitical friction.
- mmWave propagation physics:Signal attenuation through building materials limits indoor penetration, constraining addressable use cases despite higher throughput capacity.
- Site acquisition complexity:Municipal zoning in dense European and North American urban cores extends deployment timelines and elevates civil works costs.
Strategic Opportunities
- Private network deployments:Mining operations in Australia and container terminals in the Netherlands are procuring dedicated 5G infrastructure outside carrier networks.
- EU Green Deal energy-efficiency incentives:Power consumption benchmarks for network equipment create procurement preference for advanced massive MIMO architectures.
- AI-driven predictive maintenance:Machine learning integration with baseband units enables remote diagnostics that reduce truck rolls and site visits.
Industry Challenges
- Radio frequency engineering talent scarcity:Specialized expertise in beamforming algorithm development concentrates among legacy equipment vendors and a limited pool of contract researchers.
- Multi-vendor interoperability testing:Open RAN disaggregation requires extended validation cycles across radio unit, distributed unit, and centralized unit combinations that were previously integrated.
- Legacy 4G infrastructure coexistence:Dynamic spectrum sharing implementations must maintain backward compatibility while optimizing 5G throughput, complicating software-defined radio configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G Base Station Market |
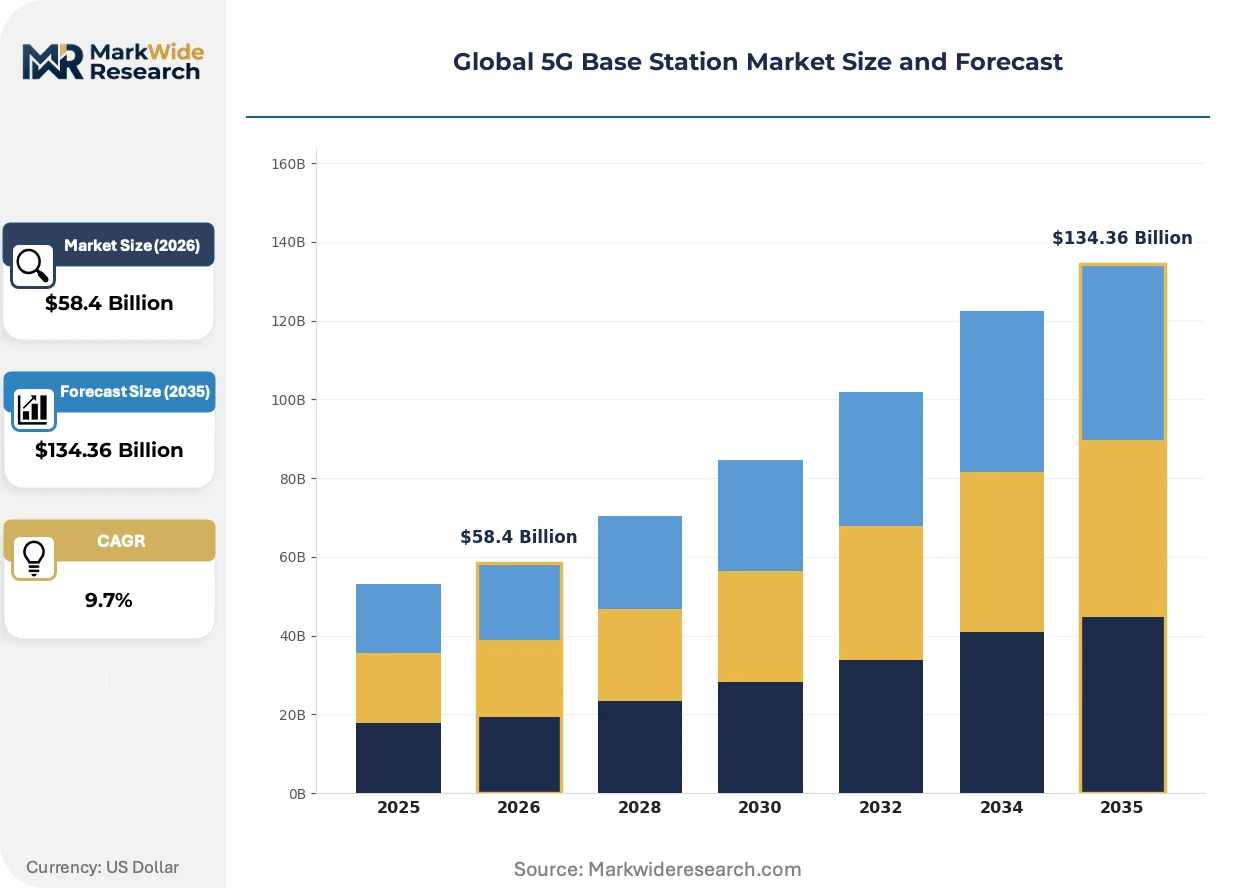
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $134.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macro Cells, Small Cells, Distributed Antenna Systems, Femto Cells Technology: Massive MIMO, Beamforming, Network Slicing, Cloud RAN End User: Telecommunications, Government, Transportation, Utilities Installation Type: Outdoor, Indoor, Rooftop, Pole Mounted |
| Companies Covered | Samsung Electronics, NEC Corporation, Huawei Technologies, Cisco Systems, Qualcomm, Ericsson, ZTE Corporation, Mavenir, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G Base Station Market Shifts & Advancements
Intelligent network management systems and virtualized baseband processing are compressing operational expenditure structures while enabling new service tiering models for enterprise connectivity.
Massive MIMO with 64T64R antenna configurations is automating beam steering optimization in real time, reducing manual radio frequency planning requirements. Tier-one carriers in South Korea and the United States are deploying these arrays at scale in stadium and transit hub environments. The technology is automating interference management that previously required drive testing and manual parameter adjustment.
Japan's METI power-efficiency benchmarks for 5G infrastructure are mandating sleep-mode algorithms and liquid cooling systems in new deployments. Equipment vendors must certify compliance through standardized measurement protocols before commercial release. Dense urban installations in Tokyo and Osaka face the strictest enforcement, accelerating replacement of first-generation equipment.
Enterprise buyers are consolidating procurement authority for private 5G networks away from IT departments toward operational technology executives who control factory and logistics site budgets. Systems integrators and industrial automation vendors are capturing this channel role from traditional telecommunications distributors. This pattern is most pronounced in German automotive manufacturing and Dutch port operations.
Global 5G Base Station Market Segmentation
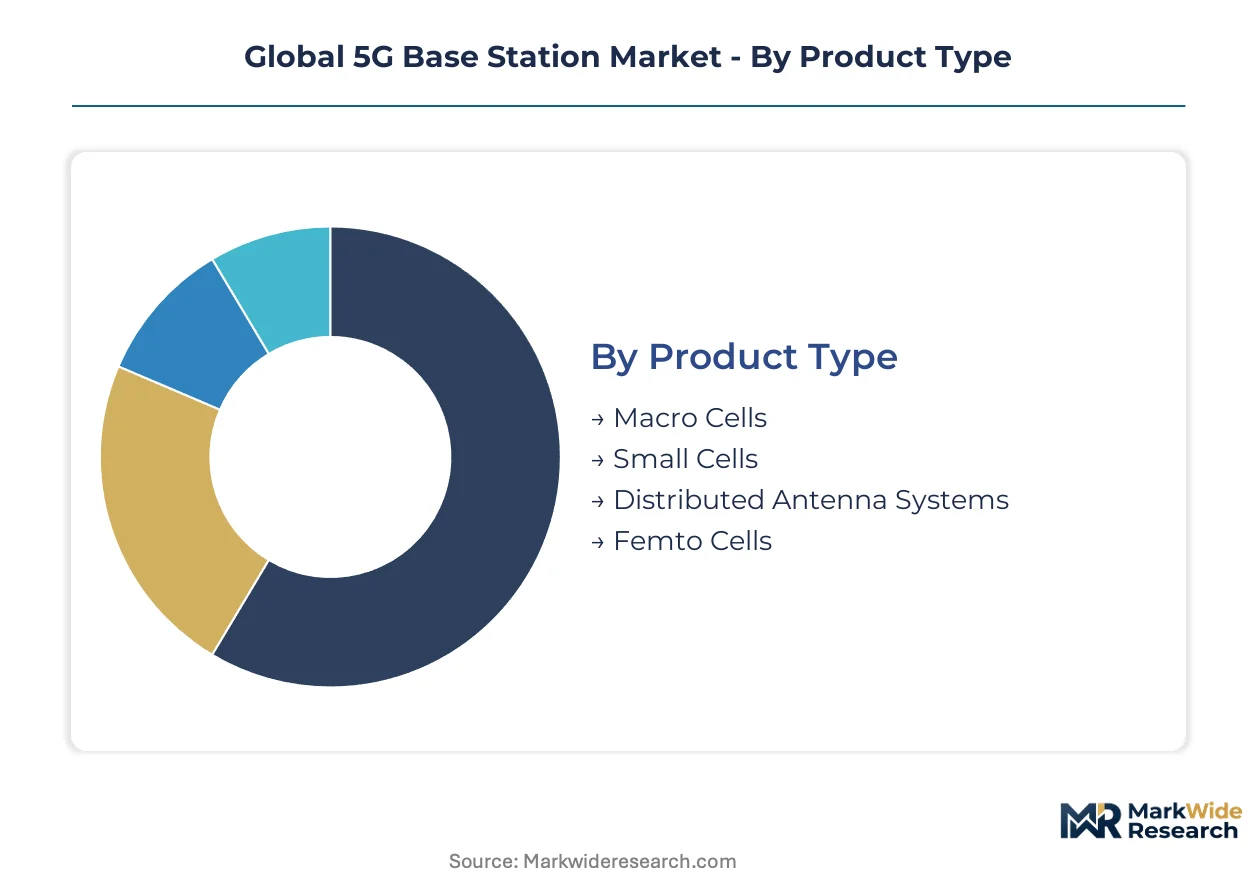
5G base station segmentation reveals how deployment economics vary dramatically across infrastructure scales and operational environments. Product architecture, signal processing technology, end-use requirements, and physical mounting constraints each create distinct procurement patterns and vendor qualification criteria.
Product Type:
Integration depth separates standalone macro deployments from embedded small-cell systems that densify existing infrastructure.
- Macro Cells:High-power radio units with integrated baseband processing serve wide-area coverage requirements across suburban and rural geographies. German and South Korean carriers prioritize these for initial 5G standalone network launches due to their capacity to serve industrial IoT clusters with minimal site density.
- Small Cells:Low-power nodes deploy in dense urban corridors where spectrum reuse demands tight inter-site spacing. Tokyo and Manhattan transit corridors drive procurement volumes as municipal authorities streamline pole attachment agreements.
- Distributed Antenna Systems:Fiber-fed antenna arrays extend coverage into stadiums, airports, and underground transit networks where direct radio propagation fails.
- Femto Cells:Subscriber-premise equipment addresses indoor coverage gaps in residential and small enterprise settings through consumer-grade installations.
Volume placements concentrate in Macro Cells; the faster expansion belongs to Small Cells.
Technology:
Cost tier separation distinguishes premium massive MIMO configurations from standardized beamforming implementations.
- Massive MIMO:64T64R antenna arrays with 3D beamforming capability automate spatial multiplexing across hundreds of simultaneous connections. South Korean stadium deployments and German automotive factory floors demand these configurations for ultra-reliable low-latency service tiers.
- Beamforming:Directional signal focusing algorithms extend cell edge throughput without additional spectrum allocation. Rural US carriers deploy these to maximize C-band coverage per installed site.
- Network Slicing:Virtualized resource partitioning enables quality-of-service guarantees for enterprise private networks.
- Cloud RAN:Centralized baseband processing pools reduce site power consumption and enable software-defined capacity scaling.
Capital commitments concentrate in Massive MIMO; Cloud RAN is climbing the fastest as virtualization mandates spread.
End User:
Customer type fragmentation separates telecommunications carrier procurement from operational technology buyers controlling industrial site budgets.
- Telecommunications:Mobile network operators deploy infrastructure under spectrum license obligations and universal service mandates. Verizon, Deutsche Telekom, and SK Telecom anchor equipment demand through multi-year rollout commitments.
- Government:Defense and public safety agencies procure hardened base stations for emergency response networks and secure communications.
- Transportation:Port authorities and railway operators deploy private infrastructure for autonomous vehicle coordination and cargo tracking.
- Utilities:Power grid operators install dedicated networks for smart meter aggregation and distribution automation.
Procurement volume concentrates in Telecommunications; Transportation is gaining share fastest as port and rail privatization accelerates.
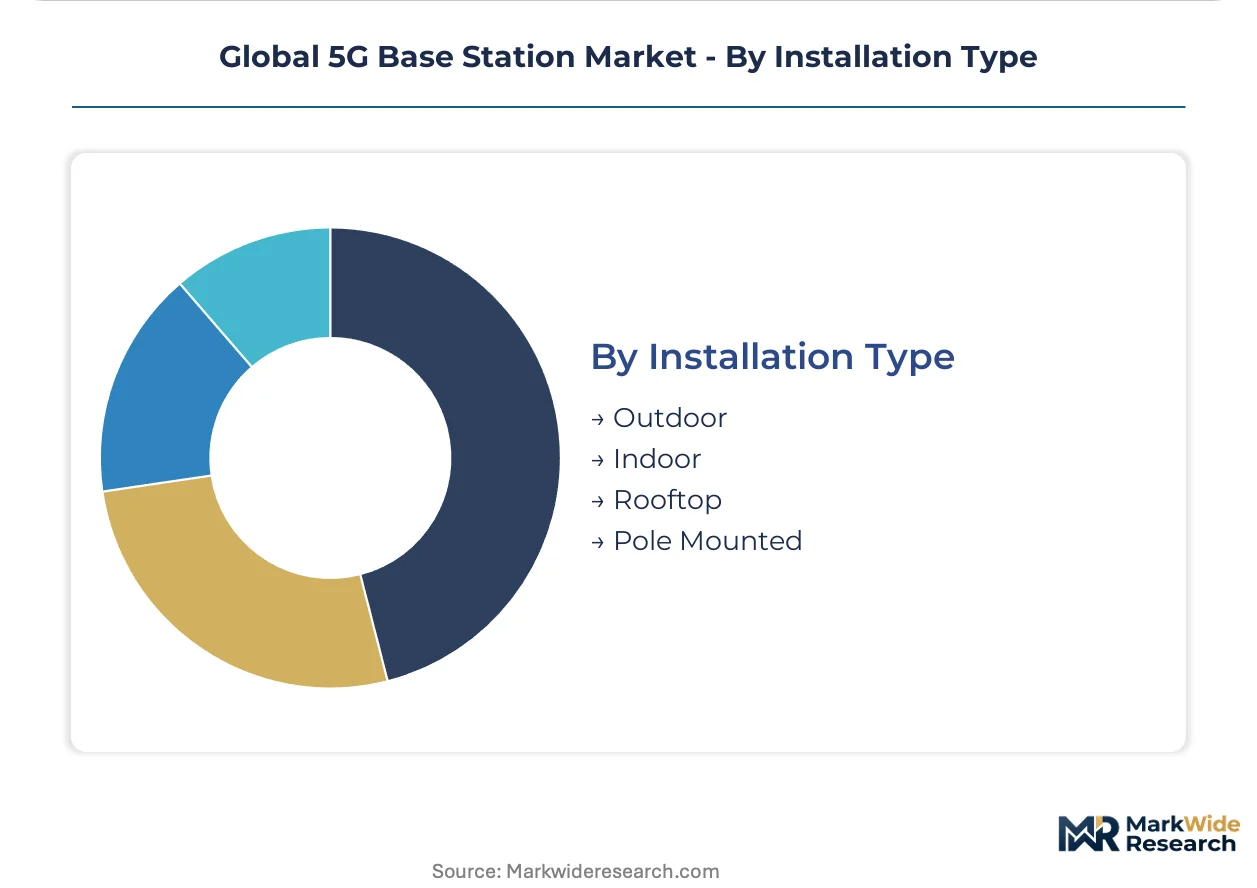
Installation Type:
Maturity differentiation separates established outdoor tower deployments from emerging indoor and rooftop categories facing novel zoning constraints.
- Outdoor:Ground-based tower and monopole installations serve macro coverage requirements across suburban and highway corridors. US and Australian rural buildouts favor these for rapid geographic footprint expansion.
- Indoor:Distributed antenna systems and small cells address coverage gaps within commercial buildings, hospitals, and manufacturing facilities. Japanese METI efficiency benchmarks accelerate replacement of first-generation indoor equipment.
- Rooftop:Urban macro and small cell deployments leverage existing building infrastructure to bypass ground-level site acquisition delays.
- Pole Mounted:Street furniture attachments enable dense small cell grids in city centers where fiber backhaul follows existing utility corridors.
Deployment volume concentrates in Outdoor; Pole Mounted shows the steepest expansion trajectory as smart city infrastructure programs multiply attachment points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the densest 5G base station deployment globally, with metropolitan site density exceeding any other urban cluster. Carrier investments concentrate in three national markets where spectrum availability and industrial demand converge.
United States
Verizon and AT&T drive macro cell procurement for C-band coverage expansion across suburban corridors. The FCC's spectrum auction framework determines deployment pacing through release schedules. Dallas-Fort Worth and Atlanta metropolitan clusters host the highest small cell densification rates for stadium and transit applications.
Germany
Automotive manufacturing automation in Baden-Württemberg and Bavaria mandates ultra-reliable low-latency infrastructure. The EU Green Deal recalibrates energy-efficiency requirements for network equipment procurement. Stuttgart's industrial corridor leads private 5G network installations outside carrier frameworks.
China
MIIT spectrum allocations prioritize sub-6 GHz nationwide coverage for industrial IoT clusters. National security review frameworks shape vendor eligibility for critical infrastructure deployment. Shenzhen and Shanghai metropolitan zones concentrate the highest base station installation volumes for smart city integration.
South Korea
SK Telecom and KT Corporation accelerate massive MIMO deployments for manufacturing automation in Gyeonggi-do. The national spectrum management authority streamlines mmWave licensing for dense urban corridors. Busan port operations drive private network procurement outside traditional carrier contracts.
Japan
METI power-efficiency benchmarks mandate sleep-mode algorithms and liquid cooling for new installations. Tokyo and Osaka metropolitan authorities enforce the strictest compliance timelines for equipment replacement. Dense urban installations prioritize indoor small cell coverage for commercial building penetration.
Global 5G Base Station Market Competitive Landscape
The competitive structure tilts toward integrated chipset-to-antenna specialists with captive semiconductor fabrication capabilities. Three tiers separate premium massive MIMO developers from standardized beamforming implementers and emerging Open RAN disaggregators. Dominant competitive moves include strategic partnerships for second-source qualification and geographic diversification of manufacturing footprints to navigate national security screening.
Within the integrated infrastructure tier, Huawei Technologies and Samsung Electronics exemplify archetypes of captive supply chain control spanning radio units through antenna arrays. ZTE Corporation occupies a position among scale-focused equipment vendors with concentrated Asia-Pacific deployment authority. NEC Corporation represents the specialized vendor archetype targeting Open RAN interoperability mandates in North American carrier trials.
| Leading Market Players |
|---|
| Samsung Electronics |
| NEC Corporation |
| Huawei Technologies |
| Cisco Systems |
| Qualcomm |
| Ericsson |
| ZTE Corporation |
| Mavenir |
| Nokia |
| Others |
Supply & Pricing Matrix
Telecommunications carrier procurement concentration in Germany, South Korea, and the United States anchors value-based pricing tied to throughput guarantees and network uptime service level agreements. Equipment vendors structure contracts around performance outcomes rather than unit hardware costs, with pricing power flowing to integrated chipset-to-antenna specialists who control captive semiconductor fabrication.
Pricing Analysis
Value-based pricing anchored to throughput capacity and latency guarantees dominates carrier procurement frameworks. Price differentiation separates massive MIMO configurations with 64T64R arrays from standardized beamforming implementations, with certification under Japan's METI power-efficiency benchmarks commanding premium positioning. Cost compression in macro cell deployments is intensifying because Open RAN disaggregation enables multi-vendor sourcing that fragments supplier pricing power. Small cell procurement shows the highest price sensitivity among municipal smart city programs, while private network deployments in German automotive manufacturing demonstrate lowest sensitivity due to operational technology budget autonomy.
Supply Chain Analysis
GaN-on-SiC substrate supply rests on concentrated wafer fabrication capacity in Japan, Taiwan, and the United States. Radio unit assembly draws from specialized power amplifier chip foundries, liquid cooling system manufacturers, and massive MIMO antenna array fabricators concentrated in East Asia. Single-source vulnerability in compound semiconductor substrates exposes procurement timelines to export control friction. Distribution runs through carrier-direct procurement channels for macro deployments, while systems integrators and industrial automation vendors capture channel role for private network installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated specialists with captive semiconductor supply, as Open RAN qualification requirements and national security screening frameworks force weaker component vendors toward acquisition or exit.
For Market Incumbents: Extend massive MIMO R&D programs targeting dense urban environments to maintain differentiation against emerging Open RAN disaggregators. Deepen backward integration into GaN-on-SiC substrate supply to defend against compound semiconductor foundry concentration in East Asia. Prioritize certification investment under Japan's METI power-efficiency benchmarks to capture EU Green Deal-aligned procurement preference. For New Entrants and Emerging Players: Capture private 5G network deployments in Australian mining operations and Dutch port terminals where operational technology buyers bypass traditional carrier channels. Target transportation and utilities verticals as the most penetrable end-use segments given fragmented incumbent presence outside telecommunications procurement. Pursue systems integrator partnerships as the dominant go-to-market angle to access factory and logistics site budgets controlled by operational technology executives. For Investors and Strategic Acquirers: The window for entry favors Open RAN software specialists with proven interoperability testing capabilities across radio unit, distributed unit, and centralized unit combinations. Long-term viability hinges on qualification timelines for second-tier suppliers accelerating under national security screening mandates. Watch FCC spectrum auction schedules and EU AI Act infrastructure requirement rollouts as inflection indicators for equipment demand pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Massive MIMO R&D Scale-Up | 64T64R antenna development automates beam steering for South Korean stadium deployments. |
| GaN-on-SiC Backward Integration | Captive substrate supply insulates against Japan-Taiwan foundry concentration risk. |
| METI Certification Investment | Liquid cooling and sleep-mode algorithm compliance unlocks Tokyo-Osaka procurement preference. |
| Open RAN Interoperability Partnership | Multi-vendor validation cycles accelerate second-source qualification under security frameworks. |
| Private Network Channel Expansion | Systems integrator relationships access German automotive operational technology budgets. |
Research Methodology
Document review covered FCC spectrum auction records, EU AI Act implementation guidance, METI power-efficiency benchmark protocols, and MIIT infrastructure deployment filings, complemented by interviews with network planning executives at tier-one carriers, procurement directors at industrial automation vendors, and regulatory affairs leads at equipment manufacturers. Secondary validation drew from SEC 10-K infrastructure revenue disclosures, ETSI interoperability standard documentation, and national spectrum authority auction outcome databases. Bottom-up deployment volume modeling triangulated against top-down addressable market sizing across the analysis window.
Unit and revenue outputs reflect segmentation modeling across product architecture, signal processing technology, end-use vertical, and physical mounting constraints. CAGRs were derived from installation run-rate trending adjusted for spectrum release schedules and industrial IoT mandate timelines. Forecast inputs incorporated Open RAN adoption curve assumptions and private network procurement pattern shifts from IT to operational technology buyer control.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical friction in compound semiconductor supply and evolving national security screening frameworks. Projections reflect assumptions regarding carrier capex commitment stability and municipal zoning streamlining for small cell densification. A small set of triggers—FCC auction pacing, EU Green Deal enforcement timelines, and Open RAN interoperability certification milestones—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Mexico MNVO Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Iceland Telecom Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Egypt Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
Thailand Telecom Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Medical 5G Market
Telecommunications
Chile Telecom Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Austria Telecom Market
Telecommunications
South Africa MNO - MVNO Market