
 Sri Lanka Telecom Market | 2026-2036
Sri Lanka Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Sri Lanka Telecom Market Outlook
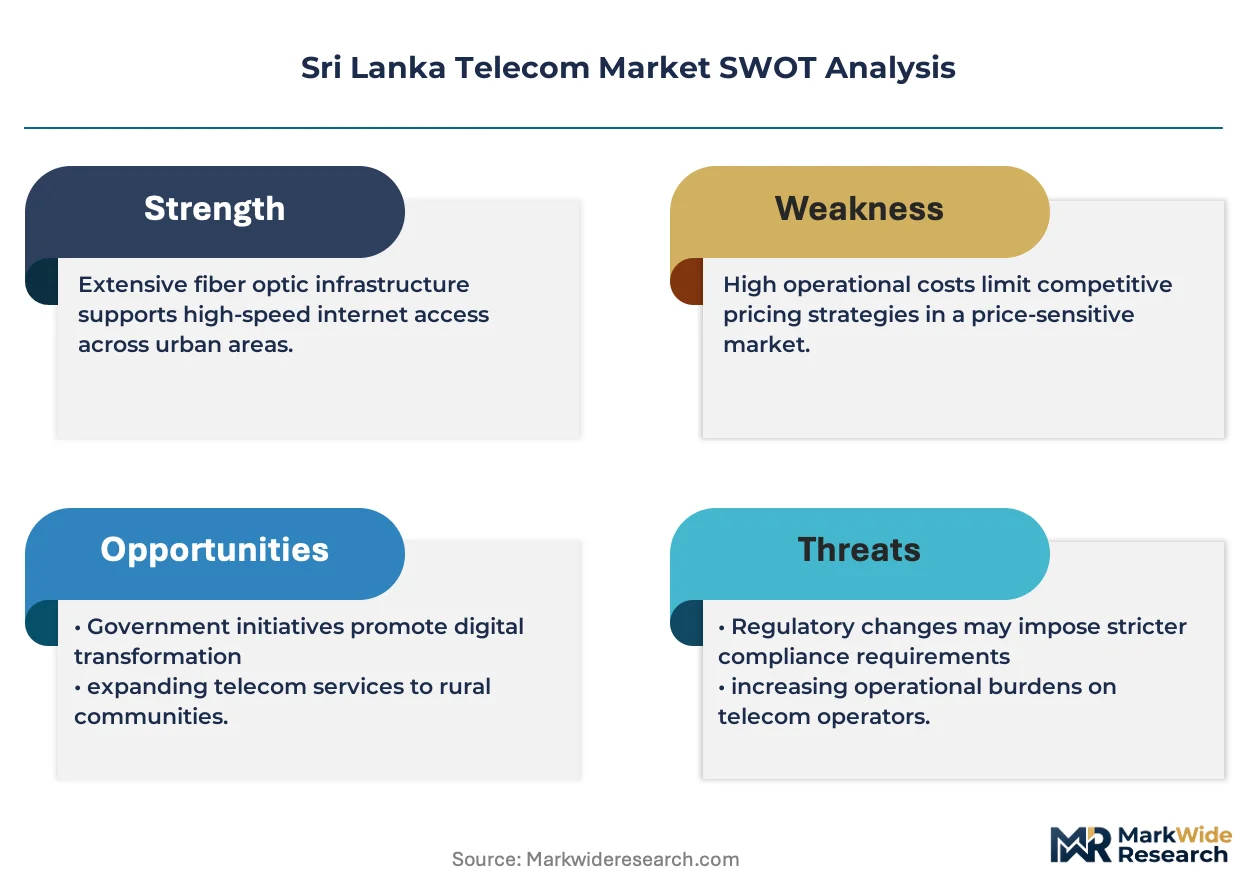
The gap between premium fiber broadband and basic mobile data is hardening as infrastructure economics diverge. Dialog Axiata PLC leverages its tower portfolio and spectrum depth to dominate Colombo's enterprise segment. SLT-Mobitel anchors national backbone capacity through its government-linked fiber expansion mandate. Hutchison Telecommunications Lanka competes on price in prepaid mobile, sacrificing margin for subscriber scale in secondary cities.
Telecom encompasses the transmission of voice, data, and video across wired and wireless infrastructure operating at frequencies from 700 MHz to 3.5 GHz and optical wavelengths of 1310–1550 nm, serving as the foundational utility for digital commerce, governance, and social connectivity. Mobile Services generates the largest revenue pool but Fiber Optic deployment under the technology dimension captures the fastest expansion trajectory as operators replace aging copper. Business customers within the Customer Type dimension command superior average revenue per user and longer contract tenures compared to residential subscribers.
The Telecommunications Regulatory Commission of Sri Lanka governs licensing and interconnection, while the Central Bank of Sri Lanka influences digital payment infrastructure that rides on telecom networks. The Information and Communication Technology Agency sets national broadband targets that direct public investment toward underserved districts. Stakeholders must weigh spectrum auction timing against fiber capex cycles as the two asset classes compete for limited institutional capital.
Market Dynamics
The Telecommunications Regulatory Commission of Sri Lanka's spectrum reallocation mandates are forcing operators to accelerate fiber deployment while simultaneously defending mobile subscriber bases against margin erosion.
Growth Catalysts
- Enterprise digitization:Colombo's financial services sector is migrating core banking infrastructure to cloud-native architectures, creating dedicated leased line demand that commands premium pricing and multi-year contracts.
- National broadband targets:The Information and Communication Technology Agency's district-level connectivity mandates are directing public capital toward fiber backhaul in underserved provinces outside Western Province.
- 5G spectrum release:Mid-band frequency assignments at 3.5 GHz are enabling fixed wireless access pilots that bridge the last-mile gap where trenching costs prohibit fiber economics.
Market Restraints
- Import dependency:Optical fiber and active equipment rely on dollar-denominated procurement, exposing capex cycles to rupee volatility and foreign exchange rationing by the Central Bank of Sri Lanka.
- Tower infrastructure concentration:Shared tower portfolios remain concentrated among two dominant players, limiting site access for challengers seeking rapid 4G densification in secondary cities.
- Copper network stranded assets:Legacy PSTN infrastructure requires maintenance expenditure that competes with fiber migration budgets, creating dual-network cost burdens during transition phases.
Strategic Opportunities
- Northern and Eastern Province underpenetration:Post-conflict infrastructure rebuilding has created greenfield fiber deployment zones where first-mover operators establish subscriber lock-in before competitive entry.
- Smart city integration:Colombo Municipal Council's IoT sensor networks for traffic and utilities management require low-latency connectivity that converges fiber backbone with edge computing nodes.
- Mobile money interoperability:Central Bank of Sri Lanka's payment system modernization is mandating telecom-wallet integration, opening transaction-fee revenue streams beyond pure connectivity.
Industry Challenges
- Fiber splicing technician scarcity:Specialized fusion splicing and OTDR certification programs have not scaled to match deployment timelines, creating field installation bottlenecks.
- Legacy billing integration:Convergent service bundles spanning fixed, mobile, and digital financial services require BSS/OSS transformation that strains IT integration capacity.
- Right-of-way negotiations:Municipal and railway corridor access permits involve fragmented approval processes that extend fiber route commissioning by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sri Lanka Telecom Market |
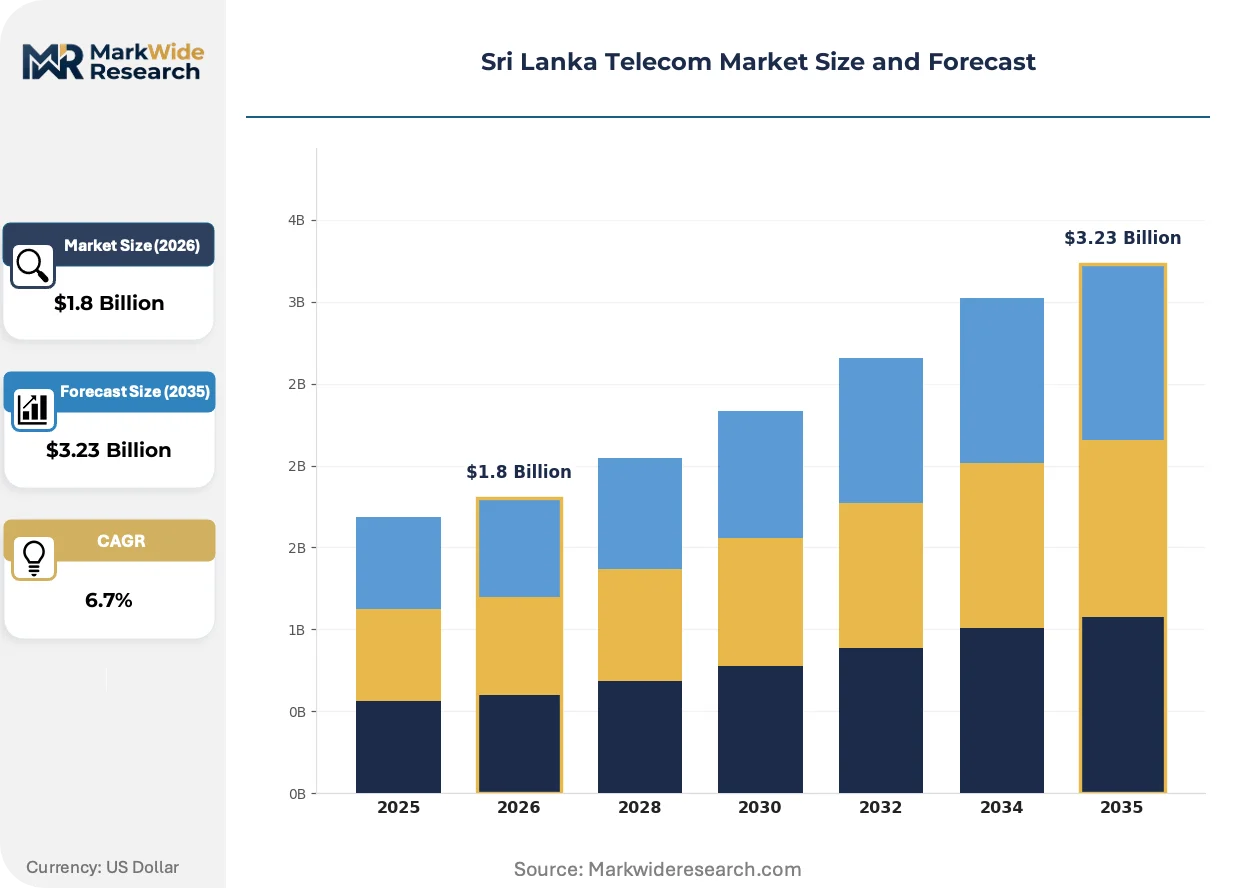
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-Line Services, Broadband Services, VoIP Services Technology: 4G LTE, Fiber Optic, DSL, Satellite Customer Type: Residential, Business, Government, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Dialog Axiata PLC, SLT-Mobitel (Sri Lanka Telecom PLC), Hutchison Telecommunications Lanka (Pvt) Ltd., Airtel, Lanka Bell, Etisalat, Nokia, Ericsson, Cisco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sri Lanka Telecom Market Strategic Shifts
Network virtualization and open-access infrastructure models are dismantling vertically integrated operator structures that dominated Sri Lanka's telecom landscape for decades.
Fiber-to-the-home infrastructure is expanding into residential precincts beyond Colombo's affluent suburbs, driven by work-from-home permanence and streaming bandwidth requirements. Estate developers in Gampaha and Kalutara districts are pre-installing GPON networks as standard amenity, compressing subscriber acquisition costs for operators. This physical layer expansion is enabling over-the-top service unbundling that separates connectivity provision from content and application layers.
The Telecommunications Regulatory Commission of Sri Lanka's infrastructure sharing mandates are compelling tower and duct co-location that reduces redundant civil works. License conditions now require dominant operators to publish reference offers for passive infrastructure access, altering competitive dynamics for network rollout speed. Smaller mobile operators in Jaffna and Batticaloa are leveraging these regulated access terms to accelerate coverage parity without proportional capital deployment.
Enterprise procurement patterns are fragmenting across multi-cloud connectivity requirements that demand diverse path redundancy. Financial services buyers in Colombo Fort and BIA precincts are unbundling primary and backup connectivity across separate operator networks, rejecting single-vendor dependency. This risk-mitigation behavior is visible most acutely among systemically important banks subject to Central Bank of Sri Lanka operational resilience guidelines.
Sri Lanka Telecom Market Segmentation
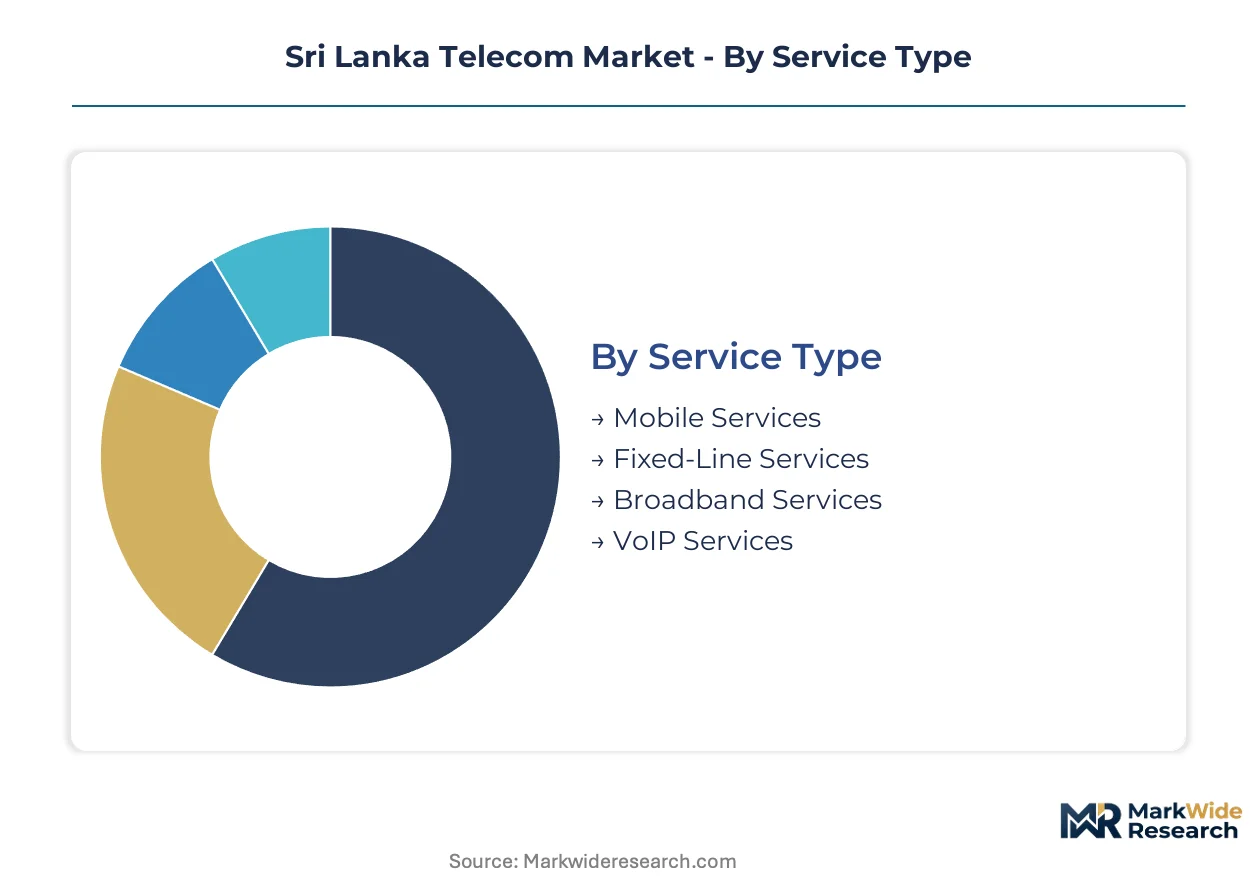
Sri Lanka's telecom segmentation reveals diverging infrastructure economics across service tiers. Each dimension carries distinct procurement patterns, regulatory exposure, and capital intensity that shape operator portfolio priorities.
Service Type:
Revenue concentration and contract duration separate enterprise buyers from mass-market subscribers across Sri Lanka's service landscape.
- Mobile Services:Voice and data transmission over cellular networks operating from 900 MHz to 2.6 GHz bands. Prepaid dominance in secondary cities outside Colombo drives volume, while postpaid enterprise accounts in the financial district anchor margin.
- Fixed-Line Services:Legacy copper PSTN infrastructure delivering voice connectivity with regulated universal service obligations. Stranded asset burdens concentrate in rural exchanges where fiber migration economics remain unfavorable.
- Broadband Services:High-speed internet access spanning fiber-to-the-home and fixed wireless formats. Western Province deployment concentrates subscriber acquisition investment from operators competing on bandwidth tiers.
- VoIP Services:Packet-switched voice over IP networks bypassing traditional circuit switching. Cost arbitrage drives adoption among SMEs in Colombo's commercial precincts with international calling requirements.
Mobile Services leads volumes today; Broadband Services is gaining share fastest.
Technology:
Capital deployment cycles and spectrum access differentiate technology choices for Sri Lankan operators.
- 4G LTE:Cellular broadband using 1800 MHz and 2100 MHz bands with MIMO antenna configurations. Dialog Axiata PLC and SLT-Mobitel densify sites in Colombo and Gampaha districts to capture data traffic growth.
- Fiber Optic:GPON and point-to-point optical transmission at 1310–1550 nm wavelengths. Western Province estate developers pre-install infrastructure, compressing subscriber acquisition costs for retail and enterprise segments.
- DSL:Copper-pair digital subscriber line delivering broadband over legacy telephone infrastructure. Maintenance obligations compete with migration budgets as fiber economics improve in urban corridors.
- Satellite:Geostationary and LEO constellations serving connectivity gaps in Northern and Eastern Province districts. Post-conflict infrastructure rebuilding creates addressable markets where terrestrial rollout remains uneconomic.
4G LTE leads volumes today; Fiber Optic is expanding most quickly.
Customer Type:
Average revenue per user and contract tenure separate procurement behaviors across Sri Lanka's subscriber base.
- Residential:Individual households consuming voice, broadband, and content bundles. Work-from-home permanence in Colombo's suburbs drives bandwidth upgrades and multi-service convergence.
- Business:Enterprises requiring dedicated leased lines, SLA-guaranteed uptime, and multi-site connectivity. Colombo Fort banks unbundle primary and backup paths across separate operator networks per Central Bank of Sri Lanka resilience guidelines.
- Government:State agencies procuring connectivity for administrative and citizen service delivery. Information and Communication Technology Agency district-level mandates direct fiber backhaul investment toward underserved provinces.
- Educational Institutions:Universities and schools requiring campus-wide networks and research connectivity. National broadband targets prioritize e-learning infrastructure in secondary cities outside Western Province.
Residential leads volumes today; Business is climbing the fastest.
Deployment:
Control over infrastructure assets versus operational outsourcing shapes enterprise procurement decisions.
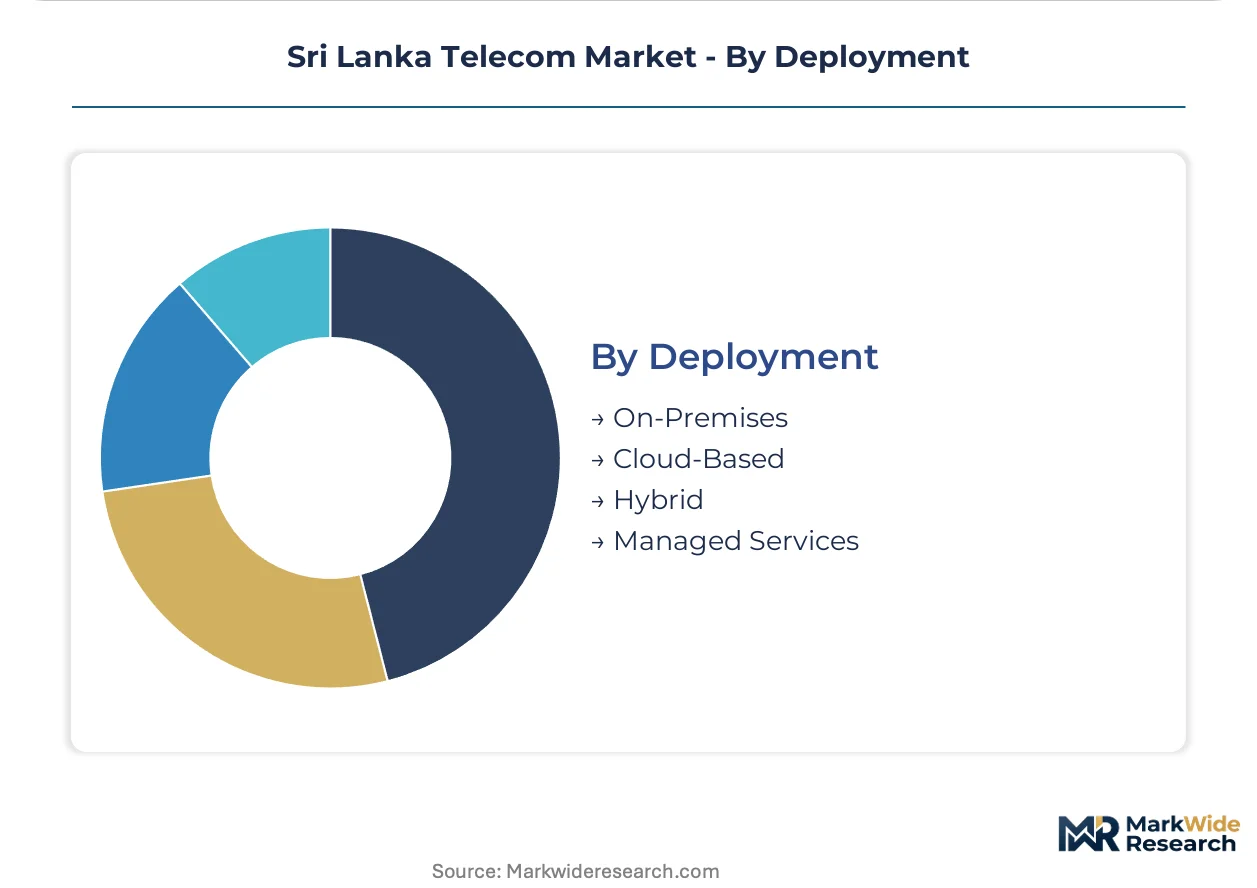
- On-Premises:Customer-owned switches, routers, and PBX systems requiring capital expenditure and internal IT management. Systemically important banks in Colombo maintain captive infrastructure for operational resilience compliance.
- Cloud-Based:Software-defined connectivity and unified communications delivered as subscription services. SMEs in commercial districts adopt rapidly to avoid hardware refresh cycles and skill scarcity.
- Hybrid:Mixed architecture combining retained core infrastructure with cloud edge services. Financial services firms partition sensitive transaction processing on-premises while offloading collaboration tools.
- Managed Services:End-to-end network operation outsourced to operator or specialist providers. Educational institutions and government agencies leverage procurement simplicity despite higher lifetime costs.
On-Premises leads volumes today; Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fiber splicing technicians and network engineers concentrate in Colombo's Western Province, anchoring Sri Lanka's telecom infrastructure workforce while secondary cities face persistent skill scarcity that constrains deployment timelines.
Western Province
Colombo's financial services digitization and Gampaha's estate developer pre-installation of GPON networks drive premium connectivity demand. The Telecommunications Regulatory Commission of Sri Lanka mandates infrastructure sharing that accelerates competitive fiber rollout across the province. Battaramulla and Rajagiriya host dense clusters of enterprise data centers requiring diverse path redundancy.
Northern Province
Jaffna's post-conflict infrastructure rebuilding creates greenfield fiber deployment zones with first-mover subscriber lock-in potential. The Information and Communication Technology Agency directs district-level broadband mandates toward underserved administrative divisions. Kilinochchi and Mullaitivu present satellite-to-terrestrial transition opportunities where fiber economics remain challenging.
Eastern Province
Batticaloa's emerging commercial activity and Trincomalee's port logistics generate enterprise leased line requirements. The Telecommunications Regulatory Commission of Sri Lanka's spectrum reallocation forces mobile operators to accelerate 4G densification. Smaller operators leverage regulated tower access terms to achieve coverage parity without proportional capital deployment.
Central Province
Kandy's educational institutions and tourism infrastructure require campus-wide networks and hospitality connectivity solutions. The Central Bank of Sri Lanka's digital payment modernization influences telecom-wallet integration priorities. Peradeniya's university research clusters demand high-bandwidth research connectivity that anchors regional network investment.
Southern Province
Galle's port expansion and Matara's manufacturing zones create industrial IoT connectivity requirements. The Information and Communication Technology Agency's national broadband targets prioritize e-learning infrastructure in secondary cities. Hambantota's logistics corridor development concentrates fiber backhaul investment from operators seeking enterprise contract anchoring.
Sri Lanka Telecom Market Competitive Environment
Top-tier vendors anchor Colombo's enterprise segment, while price-focused challengers compete for prepaid mobile scale in secondary cities. The market structure exhibits concentrated infrastructure ownership with fragmented service-layer competition. Three archetypes dominate: integrated operators with tower and spectrum depth, government-linked incumbents with backbone mandates, and margin-sacrificing challengers seeking subscriber volume. Competitive moves center on fiber-to-the-home estate pre-installation partnerships and infrastructure sharing negotiations.
Within the integrated operator tier, Dialog Axiata PLC exemplifies spectrum and tower portfolio leverage, while SLT-Mobitel represents government-linked backbone capacity anchoring. Hutchison Telecommunications Lanka occupies the challenger position, sacrificing margin for subscriber scale in prepaid mobile. These three entities collectively illustrate the strategic divergence between premium enterprise focus and mass-market volume acquisition.
| Leading Market Players |
|---|
| Dialog Axiata PLC |
| SLT-Mobitel (Sri Lanka Telecom PLC) |
| Hutchison Telecommunications Lanka (Pvt) Ltd. |
| Airtel |
| Lanka Bell |
| Etisalat |
| Nokia |
| Ericsson |
| Cisco |
| Others |
Value Chain & Pricing Dynamics
Colombo's financial services sector unbundling of primary and backup connectivity paths is compressing single-vendor pricing power and forcing operators toward transparent, contract-based tariff structures. This procurement fragmentation feeds back into supply chain reconfiguration as operators diversify equipment sourcing to meet divergent network resilience requirements.
Pricing Analysis
Bundled fixed-mobile-financial service convergence dominates enterprise accounts while unbundled connectivity-only pricing prevails in residential segments. Three-tier pricing structure across premium leased lines, standard fiber broadband, and economy prepaid mobile separates contract tenures and SLA guarantees. Cost compression in the residential fiber tier is intensifying because estate developers pre-install GPON infrastructure, eliminating subscriber acquisition subsidies. SMEs in Colombo's commercial precincts exhibit highest price sensitivity due to post-pandemic liquidity constraints, while systemically important banks show lowest sensitivity given Central Bank of Sri Lanka operational resilience mandates.
Supply Chain Analysis
Regional distribution centers in Singapore and Dubai anchor hub-and-spoke patterns for optical fiber and active equipment reaching Colombo port. Supply concentration rests on China for GPON equipment, India for copper cable remnants, and Japan for precision splicing instrumentation. Raw material dependencies include silica fiber preforms, semiconductor laser components, and aluminum alloy tower structures. Single-source vulnerability concentrates in 3.5 GHz radio equipment where vendor consolidation limits alternatives. Distribution runs through operator-direct procurement for core infrastructure and authorized dealer networks for customer-premises equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sri Lanka Telecom Market functions as a regulatory compounder where Telecommunications Regulatory Commission of Sri Lanka spectrum reallocation mandates are accelerating infrastructure replacement cycles and sustaining capital deployment demand.
For Market Incumbents: Anticipate margin erosion in prepaid mobile as Hutchison Telecommunications Lanka sacrifices profitability for subscriber scale in secondary cities. Defensive consolidation should prioritize fiber-to-the-home estate pre-installation partnerships in Gampaha and Kalutara districts to lock in residential subscriber bases before competitive entry. Vertical integration into captive tower ownership preserves site access leverage against infrastructure sharing mandates. For New Entrants and Emerging Players: Fixed wireless access at 3.5 GHz offers a technology-first wedge into Northern and Eastern Province districts where fiber trenching economics remain unfavorable. The most penetrable geography spans Jaffna and Batticaloa post-conflict rebuilding zones with greenfield infrastructure requirements. A go-to-market angle leveraging regulated tower co-location terms achieves coverage parity without proportional capital deployment against established spectrum holders. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fiber splicing service providers and OTDR-certified field engineering firms as deployment bottlenecks intensify. Long-term viability favors infrastructure-light service layer specialists over capital-intensive spectrum and tower owners facing rupee-denominated revenue against dollar procurement exposure. The signal to watch is Central Bank of Sri Lanka foreign exchange rationing severity, which would throttle equipment imports and compress rollout timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-to-the-Home Estate Pre-Installation Partnerships | Compresses subscriber acquisition costs in Gampaha and Kalutara districts where developers standardize GPON infrastructure. |
| Regulated Tower Infrastructure Co-Location | Enables smaller operators in Jaffna and Batticaloa to achieve coverage parity without proportional capital deployment. |
| Enterprise Multi-Cloud Connectivity Unbundling | Addresses Colombo Fort bank procurement patterns rejecting single-vendor dependency per Central Bank resilience guidelines. |
| Mobile Money Interoperability Integration | Captures transaction-fee revenue streams beyond pure connectivity as Central Bank mandates telecom-wallet convergence. |
| Fixed Wireless Access Pilot Deployment | Bridges last-mile gaps in Northern Province districts where trenching costs prohibit fiber economics. |
Study Parameters
Coverage spans Sri Lanka's Western, Northern, Eastern, Central, and Southern Provinces, with primary inputs from each administrative division combining interviews with network planning executives, regulatory affairs specialists, enterprise procurement managers, and fiber splicing field technicians. Secondary validation draws from Telecommunications Regulatory Commission of Sri Lanka licensing databases, Central Bank of Sri Lanka payment system modernization disclosures, Information and Communication Technology Agency district-level broadband mandate documentation, and operator annual regulatory filings. Bottom-up subscriber and revenue modeling triangulates against top-down addressable market sizing across the analysis window.
Granularity-level modeling disaggregates projections across service type, technology platform, customer archetype, and deployment architecture dimensions. The analytical framework applies segment-specific growth assumptions throughout the forecast period, with CAGRs derived from infrastructure deployment timelines, spectrum release schedules, and enterprise digitization penetration curves. Industry-specific inputs include fiber route commissioning permits, tower infrastructure sharing agreement terms, and foreign exchange rationing severity indices.
The model holds under stable rupee-dollar exchange rate assumptions and consistent regulatory enforcement; deviation in Central Bank foreign exchange rationing stringency or accelerated spectrum auction timelines would shift capital allocation priorities and deployment velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Global Broadband Services Market
Telecommunications
Russia Telecom Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Denmark ICT Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Argentina ICT Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Hungary ICT Market
Telecommunications
Utility Communications Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Mobile Value-Added Services (MVAS) Market