
 Egypt Telecom Tower Market | 2026-2036
Egypt Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Telecom Tower Market Insights
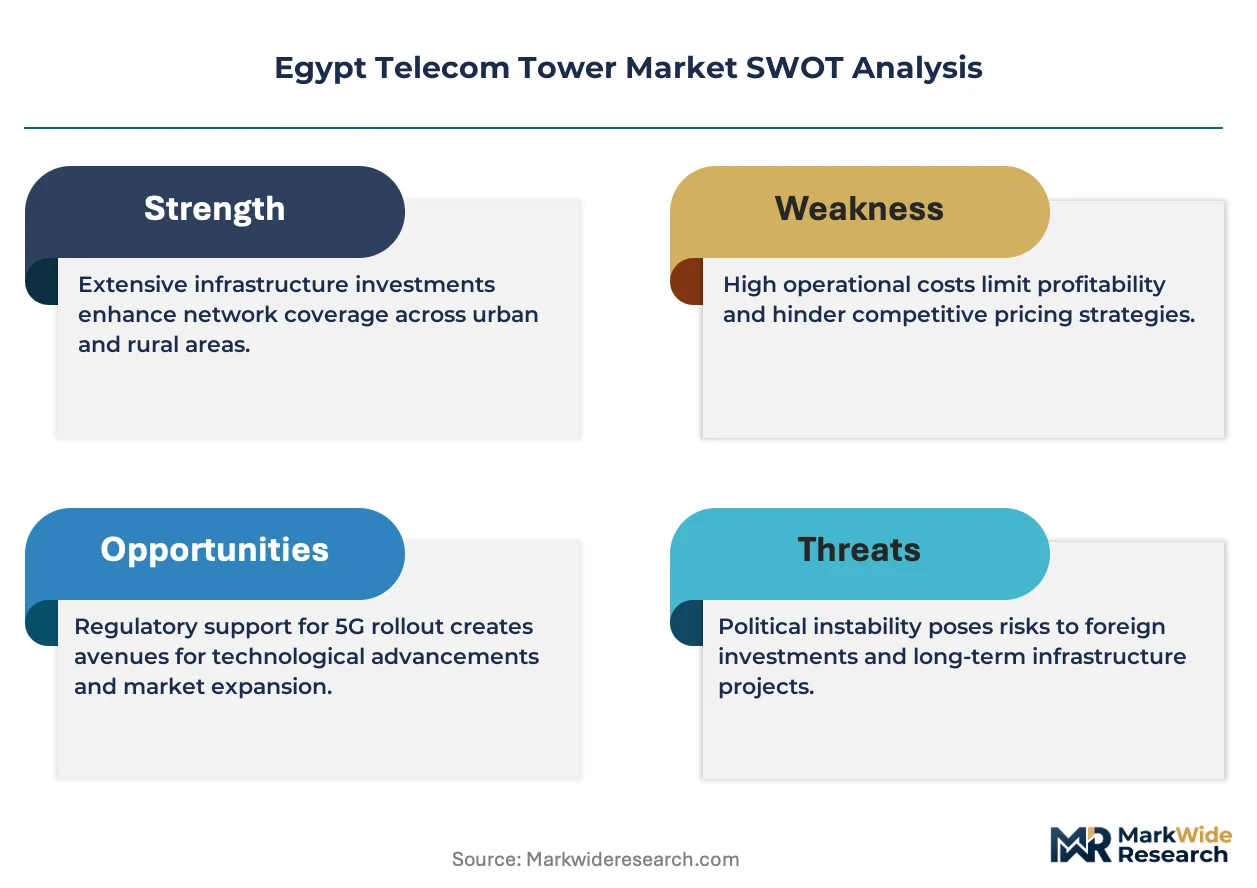
The capital-intensity divergence between tower-owning specialists and operator-captive portfolios is redrawing competitive boundaries in Egypt's telecom infrastructure sector. IHS Towers leverages its scale economies across multiple African markets to sustain lower per-site operating costs than local rivals. HOI-MEA TowerCo anchors its position through concentrated ownership of strategic rooftop and greenfield assets in dense urban zones. BenyaTower competes by specializing in turnkey build-to-suit solutions for mobile operators seeking rapid 5G rollout timelines.
Egypt telecom towers are steel or concrete structures engineered to support multiple antenna arrays, transmission equipment, and power systems at heights typically ranging from 15 to 80 meters, serving as the physical backbone for wireless signal propagation across populated areas. Macro cells dominate current installed capacity due to their superior coverage radius and established grid power access, while small cells represent the fastest-growing product type as operators densify networks for 5G capacity in Cairo's commercial districts. Fiber optic networks command premium margins among infrastructure segments because they enable high-capacity backhaul that reduces latency for mobile operators and internet service providers.
The National Telecommunications Regulatory Authority enforces infrastructure-sharing regulations that compel operators to lease rather than build duplicate towers, while the Egyptian Environmental Affairs Agency reviews electromagnetic emissions compliance for new installations. The Ministry of Communications and Information Technology coordinates spectrum auctions that directly determine tower density requirements by frequency band. Stakeholders must monitor how NTRA's evolving colocation pricing frameworks reshape returns for independent tower companies versus integrated operator models.
Market Dynamics
The National Telecommunications Regulatory Authority's infrastructure-sharing mandates are compressing tower ownership models across Egypt, forcing mobile operators to divest captive assets and lease from independent tower companies.
Growth Catalysts
- 5G densification mandates:The Ministry of Communications and Information Technology's spectrum allocations require operators to deploy small cells in Cairo and Alexandria commercial corridors, accelerating demand for multi-tenant tower infrastructure.
- Fiber backhaul integration:Telecom Egypt's fiber optic expansion enables tower operators to offer bundled connectivity services, reducing latency for mobile operators while capturing premium margins on combined infrastructure.
- Underserved governorate coverage:Mobile network operators are extending macro cell grids into Upper Egypt and Delta regions, creating greenfield build-to-suit contracts for tower specialists with rapid deployment capabilities.
Market Restraints
- Steel price volatility:Tower fabrication costs fluctuate with global steel commodity markets, compressing margins for build-to-suit contracts with fixed pricing terms.
- Grid power dependency:Macro cell towers in rural governorates face unreliable Egyptian Electricity Holding Company supply, forcing costly diesel generator backup systems and fuel logistics.
- Electromagnetic emission compliance:The Egyptian Environmental Affairs Agency's site-by-site approval processes extend permitting timelines by six to twelve months for new installations.
Strategic Opportunities
- Sinai Peninsula coverage gaps:Security-cleared tower operators can capture exclusive build-to-suit contracts for military and commercial mobile networks in restricted-access zones.
- Renewable energy hybridization:Solar-diesel hybrid power systems reduce operating expenditure for off-grid towers in remote Western Desert governorates.
- Rooftop asset aggregation:Dense urban zones in Giza and Alexandria offer concentrated acquisition targets for micro-cell hosting on commercial and residential buildings.
Industry Challenges
- RF engineering talent scarcity:Specialized network planning and radio frequency optimization skills are concentrated among a limited pool of Egyptian engineers with multinational operator experience.
- Legacy 2G/3G decommissioning coordination:Tower operators must negotiate equipment removal timelines with multiple tenants while maintaining structural integrity and power distribution for remaining 4G/5G systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Telecom Tower Market |
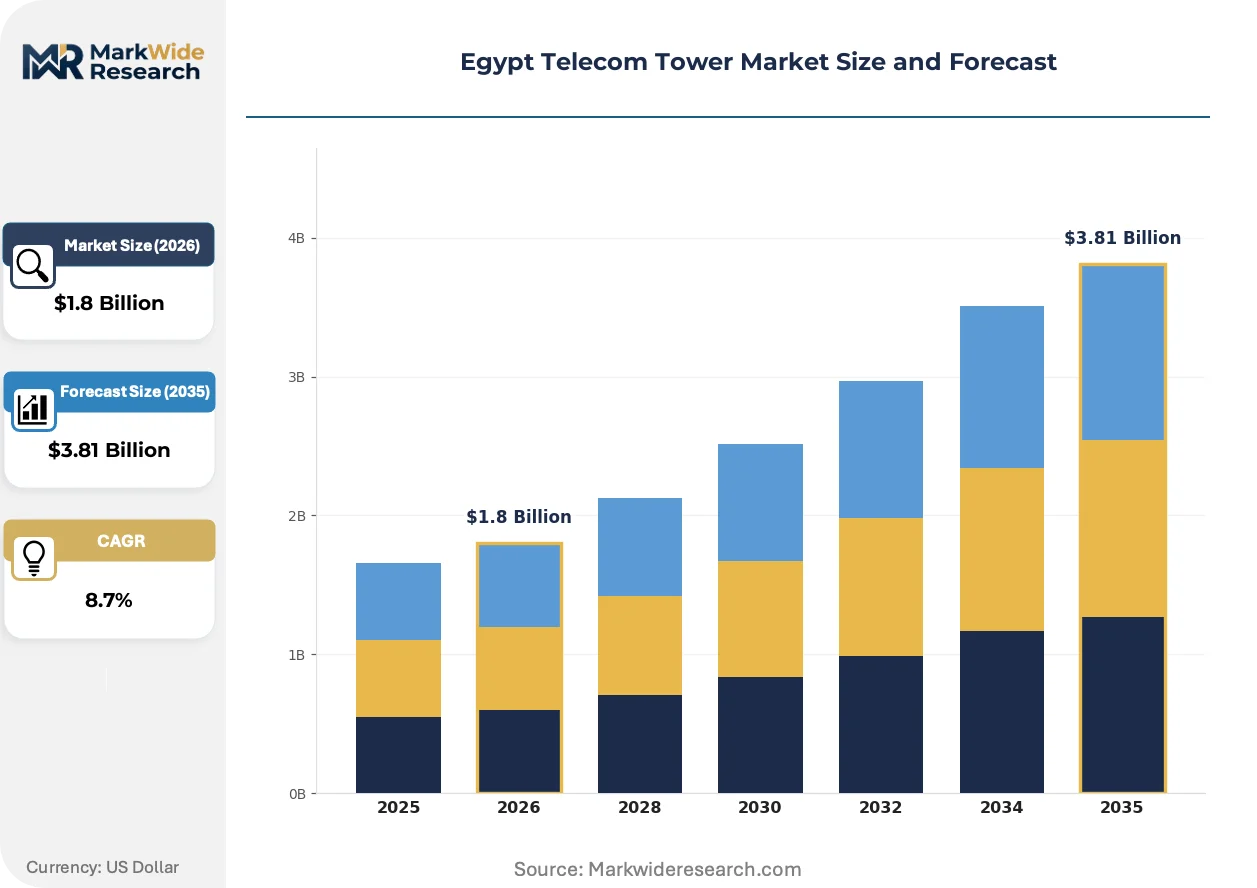
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macro Cells, Small Cells, Distributed Antenna Systems, Fiber Optic Networks End User: Mobile Operators, Internet Service Providers, Government Agencies, Enterprises Deployment: On-Premises, Off-Premises, Cloud-Based, Hybrid Technology: 4G, 5G, LTE, Wi-Fi |
| Companies Covered | IHS Towers, HOI-MEA TowerCo, BenyaTower, Telecom Egypt, Vodafone Egypt, Orange Egypt, Etisalat Misr, WE Telecom Egypt, Giza Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Telecom Tower Market Trends and Innovations
Active network sharing architectures are decomposing traditional single-tenant tower economics across Egypt's telecom infrastructure sector. Three concurrent developments are reshaping how physical assets generate returns.
Open RAN hardware specifications are decomposing proprietary vendor lock-in at Egyptian tower sites. Mobile operators are piloting multi-vendor radio access networks in Cairo test zones, accelerating equipment refresh cycles. This technology is decomposing integrated supplier relationships and creating procurement leverage for tower companies negotiating equipment sourcing.
The National Telecommunications Regulatory Authority's revised colocation pricing frameworks are standardizing lease rates across governorates. Infrastructure-sharing mandates now require published tariff schedules for anchor and secondary tenants. Rural tower portfolios face compressed yields as regulated pricing overrides negotiated premiums previously available in underserved zones.
Mobile operators are consolidating vendor relationships for tower access and maintenance services. Long-term master service agreements with independent tower companies are displacing site-by-site procurement. This concentration is most visible in the Greater Cairo corridor where Vodafone Egypt and Orange Egypt have shifted to comprehensive outsourcing models with single tower partners.
Egypt Telecom Tower Market Segmentation
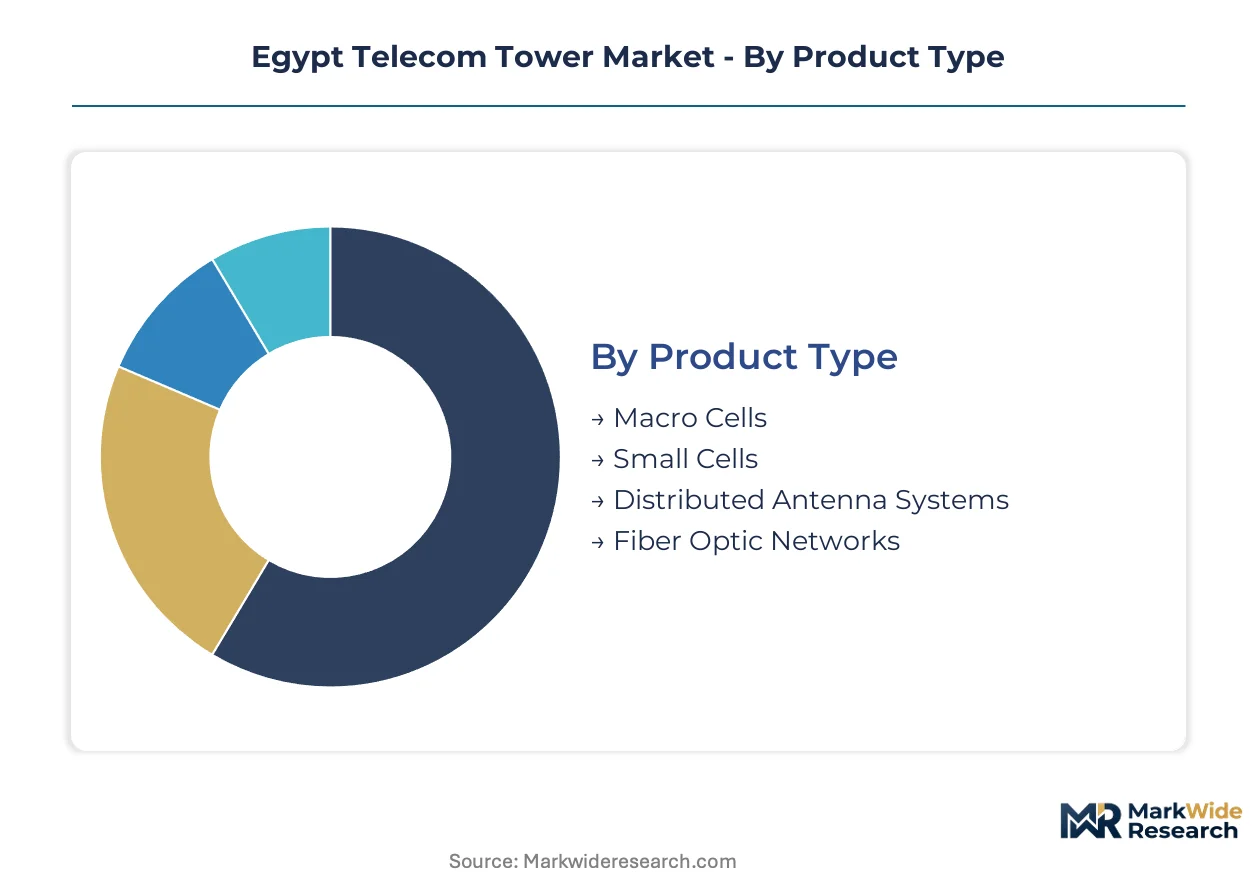
Egypt's telecom tower infrastructure fragments across multiple technical and commercial dimensions. Each segmentation axis reveals distinct deployment economics and tenant concentration patterns that shape vendor positioning.
Product Type:
Macro cells anchor rural and suburban coverage grids across Egypt's governorates, while small cells concentrate in Cairo and Alexandria commercial corridors where spectrum density requirements are strictest.
- Macro Cells:Steel or concrete structures ranging 30-80 meters support multiple antenna arrays with grid power access. Demand concentrates in Upper Egypt and Delta regions where Vodafone Egypt and Orange Egypt extend coverage into underserved governorates under NTRA infrastructure-sharing mandates.
- Small Cells:Compact 5-15 meter pole-mounted or building-mounted units enable 5G densification. Cairo's commercial districts and Alexandria's port zone generate concentrated build-to-suit contracts as operators meet Ministry of Communications and Information Technology spectrum deployment conditions.
- Distributed Antenna Systems:Indoor coverage infrastructure for stadiums, malls, and transport hubs.
- Fiber Optic Networks:High-capacity backhaul cables linking tower sites to core networks, commanding premium margins through bundled connectivity offerings.
Macro cells command the established base. The steepest expansion runs through small cells.
End User:
Mobile operators drive tower leasing volume through NTRA-mandated infrastructure sharing, while government agencies present specialized security-cleared deployment opportunities.
- Mobile Operators:Vodafone Egypt, Orange Egypt, Etisalat Misr, and Telecom Egypt anchor tenant demand through long-term master service agreements. Tower operators capture recurring revenue from colocation pricing frameworks regulated by NTRA across multiple governorates.
- Internet Service Providers:Fixed wireless access providers lease tower space for last-mile connectivity in fiber-constrained zones. Demand clusters in Greater Cairo's informal settlements where trenching costs prohibit underground cable deployment.
- Government Agencies:Military and emergency services require hardened towers in Sinai Peninsula and Western Desert zones with restricted civilian access.
- Enterprises:Mining, oil, and logistics operators procure private network infrastructure for remote facility coverage.
Mobile operators absorb the dominant revenue share. Government contracts offer the highest margin premiums.
Deployment:
On-premises tower ownership dominates Egypt's regulatory environment, while hybrid models emerge as operators balance capital efficiency against control requirements.
- On-Premises:Operator-owned or captive tower portfolios subject to NTRA divestiture pressure. Mobile operators maintain direct control over strategic urban sites while transferring rural assets to independent tower companies.
- Off-Premises:Third-party tower company ownership with leaseback arrangements. IHS Towers and HOI-MEA TowerCo aggregate these assets across multiple governorates, capturing scale economies in maintenance and power logistics.
- Cloud-Based:Virtualized network functions reducing physical equipment at tower sites, piloted in Cairo test zones.
- Hybrid:Split ownership models with shared power and backhaul but tenant-specific radio equipment.
Off-premises structures gain share fastest. On-premises retention concentrates at high-traffic urban coordinates.
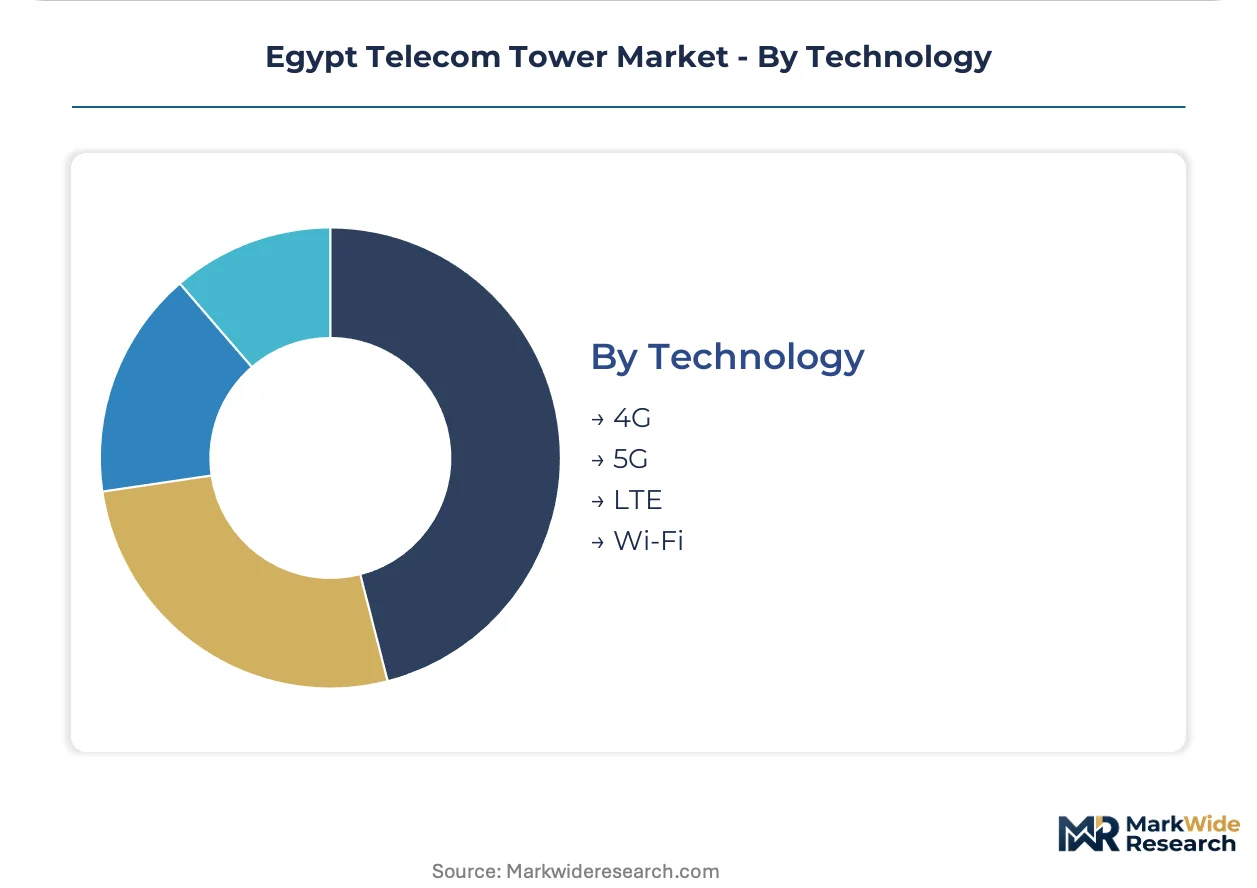
Technology:
4G equipment still dominates installed base across Egypt's governorates, while 5G deployment accelerates in spectrum-allocated urban corridors.
- 4G:Mature LTE-Advanced infrastructure supporting current subscriber traffic. Macro cell towers in rural governorates prioritize 4G coverage radius over capacity density.
- 5G:Mid-band and millimeter-wave deployments requiring small cell densification. Cairo's New Administrative Capital and Alexandria's technology zones anchor initial rollout under MCIT spectrum conditions.
- LTE:Legacy 4G equipment facing refresh cycles as operators consolidate vendor relationships.
- Wi-Fi:Unlicensed spectrum offload for high-density venues and enterprise campuses.
4G retains the installed capacity base. 5G claims the steepest deployment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Egypt's governorates. Cairo and Alexandria operators absorb premium lease rates for fiber-integrated towers, while Upper Egypt buyers prioritize diesel reliability over backhaul sophistication.
Greater Cairo
The New Administrative Capital and 6th of October City anchor 5G densification projects under Ministry of Communications and Information Technology spectrum mandates. NTRA colocation pricing frameworks compress rural yields but preserve negotiated premiums in dense urban corridors. Tower operators here bundle fiber backhaul from Telecom Egypt with multi-tenant small cell hosting.
Alexandria and Delta Region
Port logistics and industrial zones drive demand for distributed antenna systems in warehouses and container terminals. The Egyptian Environmental Affairs Agency accelerates permitting for coastal installations with pre-approved electromagnetic emission profiles. Borg El Arab's technology cluster concentrates build-to-suit contracts for operator-neutral macro cells.
Upper Egypt
Aswan and Luxor governorates present greenfield coverage gaps where mobile operators extend macro grids under universal service obligations. Grid power dependency forces solar-diesel hybrid configurations at remote sites. Security-cleared tower operators capture exclusive contracts near border zones with restricted civilian access.
Sinai Peninsula
Military and commercial network coverage requirements converge in North Sinai and South Sinai governorates. The National Telecommunications Regulatory Authority coordinates infrastructure-sharing between security agencies and civilian operators. El Arish and Sharm El Sheikh anchor dual-use tower deployments with hardened specifications.
Western Desert
Oil and gas facilities in the Western Desert generate private network demand from mining and logistics enterprises. Renewable energy hybridization reduces operating expenditure for off-grid towers serving remote extraction sites. New Valley Governorate's sparse population density favors satellite backhaul over fiber trenching economics.
Egypt Telecom Tower Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Egypt's tower infrastructure sector. IHS Towers leverages multi-country scale economies across African markets to sustain lower per-site operating costs than local rivals. HOI-MEA TowerCo anchors its position through concentrated ownership of strategic rooftop and greenfield assets in dense urban zones. BenyaTower competes by specializing in turnkey build-to-suit solutions for mobile operators seeking rapid 5G rollout timelines. Competitive dynamics center on portfolio consolidation through NTRA-mandated divestitures and master service agreement concentration with single tower partners.
Within the independent tower company tier, IHS Towers and HOI-MEA TowerCo exemplify scale-driven and asset-concentrated archetypes respectively. IHS Towers represents the multi-market operator leveraging cross-border procurement and maintenance networks. HOI-MEA TowerCo occupies a position defined by geographic density in premium urban coordinates. BenyaTower sits within the specialist tier as a build-to-suit pure-play. Among operator-captive portfolios, Telecom Egypt, Vodafone Egypt, and Orange Egypt retain strategic urban sites while transferring rural assets to independent operators under regulatory pressure.
| Leading Market Players |
|---|
| IHS Towers |
| HOI-MEA TowerCo |
| BenyaTower |
| Telecom Egypt |
| Vodafone Egypt |
| Orange Egypt |
| Etisalat Misr |
| WE Telecom Egypt |
| Giza Systems |
| Others |
Pricing and Supply Chain Analysis
NTRA's infrastructure-sharing mandates and electromagnetic emission certifications gate both supplier qualification and price differentiation across Egypt's tower infrastructure sector. Tower operators must secure site-by-site approvals from the Egyptian Environmental Affairs Agency before negotiating lease terms, compressing pricing power for non-compliant portfolios while rewarding pre-certified asset bases with premium colocation rates.
Pricing Analysis
After-sales power logistics and maintenance service contracts drive lifetime value for Egyptian tower operators more than initial build-to-suit fees. Three-tier pricing structure across premium fiber-integrated, standard grid-powered, and economy diesel-dependent tiers reflects backhaul sophistication and power reliability. Cost compression in rural macro cell deployments is intensifying because steel fabrication expenses fluctuate with global commodity markets. Mobile operators in Greater Cairo exhibit the least price sensitivity due to 5G densification urgency, while ISPs in fiber-constrained informal settlements negotiate hardest on per-site rates.
Supply Chain Analysis
Just-in-time steel procurement dominates tower fabrication given volatile commodity pricing, though strategic stockpiling of diesel generators persists for remote governorate deployments. Manufacturing concentration rests on China, Turkey, and Saudi Arabia for structural steel and antenna equipment. Raw material dependencies include high-grade steel alloys, fiber optic cables, and lithium-ion battery systems for hybrid power. Single-source vulnerability runs through Chinese telecommunications equipment suppliers subject to import licensing variability. Distribution runs through Telecom Egypt's fiber backbone and independent logistics networks serving scattered rural sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's telecom tower market is a high-growth disruption driven by 5G spectrum mandates from the Ministry of Communications and Information Technology that force rapid infrastructure densification. NTRA's colocation pricing frameworks and infrastructure-sharing requirements are redrawing competitive boundaries between integrated operators and independent tower companies.
For Market Incumbents: Fortify portfolio positions through accelerated acquisition of rooftop assets in Giza and Alexandria before regulatory caps tighten. Prioritize backward integration into solar-diesel hybrid power systems to defend margins against Egyptian Electricity Holding Company grid instability. Threats include emerging build-to-suit specialists capturing rapid-deployment contracts and NTRA-mandated yield compression in rural zones. For New Entrants and Emerging Players: Differentiate on security-cleared deployment capabilities for Sinai Peninsula and Western Desert coverage gaps where restricted-access zones limit competition. Target underserved Upper Egypt governorates with solar-hybrid power expertise as the most penetrable geography. Pursue master service agreement structures with single mobile operators rather than site-by-site procurement to accelerate scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed African tower platforms seeking Egypt exit liquidity as NTRA consolidation mandates mature. Long-term viability hinges on fiber-backhaul integration density and 5G small cell attachment rates across the analysis window. Watch NTRA's evolving colocation tariff schedules as the primary inflection signal for independent tower company yield trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Rooftop Asset Aggregation | Captures premium urban coordinates in Cairo and Alexandria ahead of regulatory saturation. |
| Fiber Backhaul Integration | Enables bundled connectivity offerings with Telecom Egypt that reduce tenant churn. |
| Renewable Energy Hybridization | Lowers opex for off-grid towers in Western Desert governorates with unreliable grid supply. |
| Security-Cleared Deployment Capability | Unlocks exclusive Sinai Peninsula contracts with military and dual-use network requirements. |
| Master Service Agreement Concentration | Displaces site-by-site procurement with Vodafone Egypt and Orange Egypt outsourcing models. |
Research Methodology
Initial hypotheses were tested against primary input from tower portfolio managers, NTRA regulatory affairs officers, mobile operator network planning directors, and fiber infrastructure procurement leads and refined through secondary validation. Tower Economics Association publications, NTRA infrastructure-sharing circulars, Egyptian Environmental Affairs Agency emission compliance databases, and Telecom Egypt fiber expansion disclosures anchored external verification. Bottom-up site-level capacity modeling and top-down governorate demand aggregation were triangulated to reconcile volume estimates.
Variance-decomposition across product type, deployment model, technology generation, and end-user segment shaped the analytical framework. CAGRs were derived from segment-level trajectory blending across the projection horizon. Forecast inputs incorporated NTRA-mandated colocation pricing phase-ins, MCIT spectrum allocation timelines, and steel commodity index volatility assumptions.
Forecasts assume regulatory continuity in NTRA infrastructure-sharing mandates and Egyptian Environmental Affairs Agency emission protocols; material policy shifts would require re-modeling. Supply disruptions from global steel markets or Egyptian Electricity Holding Company grid instability represent specific revision triggers. Practitioners should keep alternative scenarios live as NTRA pricing framework refinements and 5G deployment acceleration conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Global Virtual PBX Market
Telecommunications
C-RAN Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Cloud PBX Market
Telecommunications
Global GPON Technology Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Thailand Telecom Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Satcom Terminal Market
Telecommunications
Myanmar Telecom Market
Telecommunications
Optical Fronthaul Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Russia Telecom Market
Telecommunications
Prepaid Communication Market
Telecommunications
Sri Lanka Telecom Tower Market