
 Cambodia Telecom Tower Market | 2026-2036
Cambodia Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Telecom Tower Market Insights
Steel lattice frameworks are decoupling from traditional reinforced concrete bases in Cambodian tower construction, cutting foundation costs and shortening deployment cycles. EDOTCO Cambodia leverages its regional tower-sharing platform to consolidate multiple tenancies across Phnom Penh and provincial hubs. Viettel Cambodia sustains aggressive rollout schedules through captive engineering teams and government-backed spectrum allocations. Smart Axiata anchors premium urban coverage by controlling dense clusters of rooftop and monopole sites in the capital corridor.
A telecom tower is a steel or reinforced concrete structure engineered to heights between 30 and 120 meters, designed to mount antennas, transmission equipment, and power systems for wireless communication networks. Lattice towers dominate Cambodian installations due to their load-bearing capacity for multi-operator tenancies and resilience against monsoon wind loads. 5G infrastructure represents the fastest-expanding technology segment as operators upgrade existing 4G sites with massive MIMO arrays and fiber backhaul. Greenfield rural installations are gaining structural importance as government universal service obligations push coverage into underserved provinces where tower companies negotiate long-term anchor tenancy contracts with mobile network operators.
Cambodia's Ministry of Posts and Telecommunications and the Telecom Regulator enforce technical codes governing tower spacing, electromagnetic emissions, and structural safety certification for all new installations. These frameworks shape market access by mandating environmental impact assessments and community consultation periods before construction approval. The country's national standards body coordinates with ASEAN telecommunications working groups to align tower design protocols with regional interoperability goals. Stakeholders must monitor how spectrum auction timelines and infrastructure-sharing mandates reshape tenancy economics and capital deployment priorities across the tower ecosystem.
Market Dynamics
Tower-sharing mandates from Cambodia's Telecom Regulator are compressing tenancy economics while accelerating rural coverage obligations, forcing operators to consolidate infrastructure investments across provincial corridors.
Growth Catalysts
- Universal Service Obligations:Cambodia's Ministry of Posts and Telecommunications mandates coverage expansion into underserved provinces, creating anchor tenancy demand for new tower installations.
- 5G Massive MIMO:Mobile network operators upgrade existing 4G sites with advanced antenna arrays, requiring structural reinforcement and additional mounting capacity on legacy towers.
- Phnom Penh-Siem Reap corridor:Urban density and tourism infrastructure concentrate multi-tenancy demand, enabling tower companies to maximize revenue per site through shared access agreements.
Market Restraints
- Steel price volatility:Lattice tower fabrication depends on imported structural steel, exposing deployment budgets to regional commodity market fluctuations.
- Foundation engineering constraints:Monsoon-season soil saturation limits reinforced concrete base construction to dry months, compressing annual build windows.
- Community consultation periods:Telecom Regulator mandates local approval processes before tower construction, extending site acquisition timelines in rural districts.
Strategic Opportunities
- Ratanakiri and Mondulkiri provinces:These northeastern regions remain underserved by mobile broadband, presenting greenfield tower opportunities under government coverage targets.
- Fiber-backhaul convergence:Tower companies integrate optical fiber termination equipment with antenna mounts, creating bundled connectivity offerings for operators.
- Renewable power integration:Solar-hybrid energy systems reduce diesel generator dependence, aligning with Cambodia's rural electrification priorities and cutting operational expenditure.
Industry Challenges
- Structural engineering certification:Cambodia's national standards body requires wind-load testing for all lattice installations above 60 meters, creating bottlenecks in qualified inspection capacity.
- Multi-tenant interference management:Tower companies must coordinate antenna positioning and power settings across competing mobile network operators to prevent signal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Telecom Tower Market |
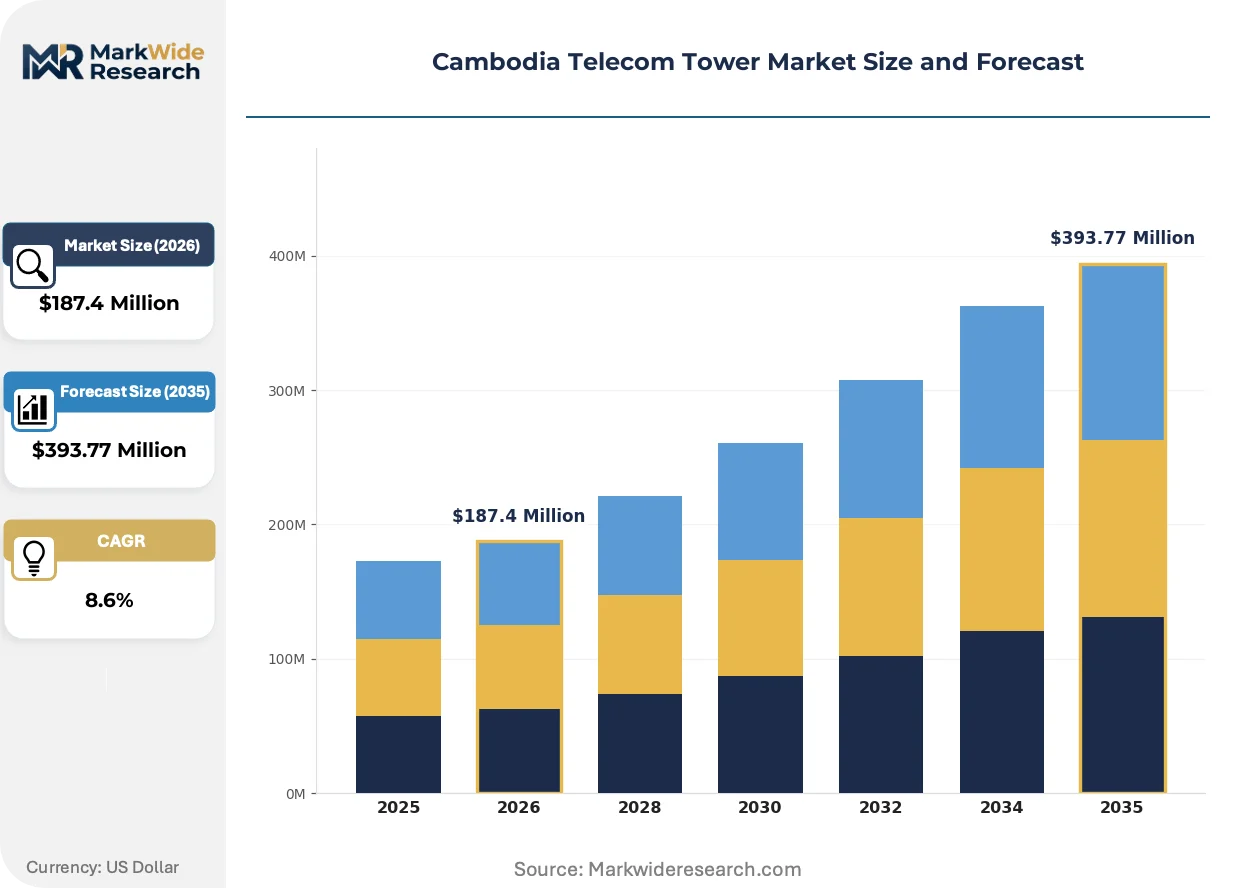
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice Tower, Stealth Tower, Guyed Tower Technology: 4G, 5G, LTE, Microwave End User: MNOs, Tower Companies, Enterprises, Government Installation Type: Onshore, Urban, Rural, Greenfield |
| Companies Covered | Metfone, Cellcard, EDOTCO Cambodia, Viettel Cambodia, Telemobile Cambodia Corporation, Cam TowerLink, Smart Axiata, Telecom Cambodia, Global Tower Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Telecom Tower Market Trends and Innovations
Deployment methodologies across Cambodia's tower sector are pivoting toward modular construction and shared infrastructure models, reducing capital intensity while expanding coverage reach.
Monopole and rapid-deploy tower designs are electrifying site rollout velocity across Cambodia's provincial markets. These structures reduce foundation footprints and enable crane-less assembly in remote locations. Mobile network operators in Battambang and Kampong Cham provinces are adopting these systems to meet universal service deadlines. The technology is electrifying competitive positioning by allowing late entrants to match incumbent coverage density without comparable historical capital deployment.
Cambodia's Telecom Regulator has streamlined electromagnetic emissions certification procedures, collapsing approval timelines for multi-tenant sites. The policy revision eliminates redundant testing when additional operators colocate on existing structures. Rural tower installations in Preah Sihanouk and Kampot provinces benefit most, as accelerated permitting enables faster revenue generation from anchor tenancy contracts.
Site acquisition through long-term land leases is displacing traditional purchase models across the Cambodian tower ecosystem. Tower companies now negotiate 15-20 year agreements with provincial landowners, preserving capital for equipment upgrades rather than real estate ownership. This shift concentrates in Siem Reap and coastal tourism zones where land values complicate outright acquisition strategies.
Cambodia Telecom Tower Market Segmentation
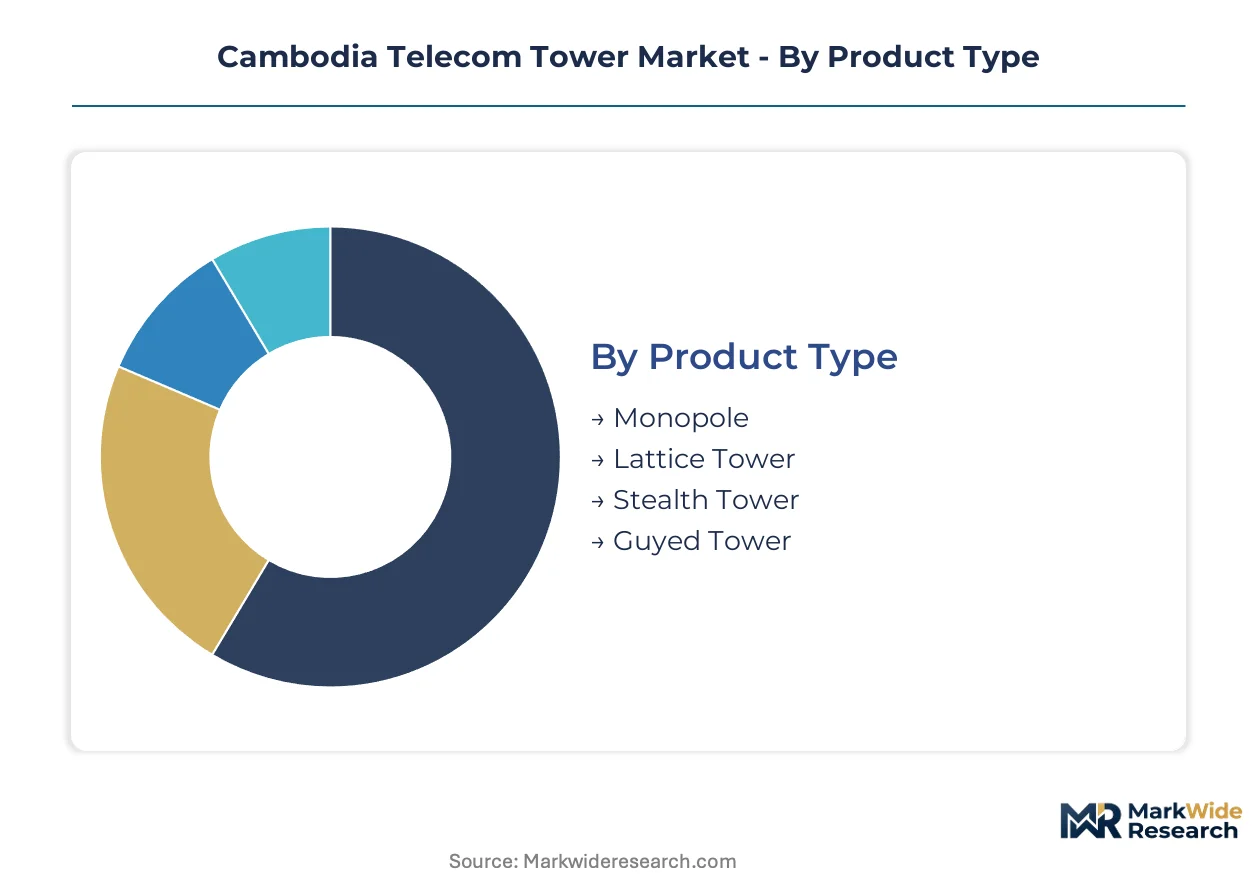
Cambodia's telecom tower market fragments across structural designs, wireless generations, customer archetypes, and deployment contexts. Each dimension shapes capital allocation, tenancy economics, and regulatory compliance requirements for infrastructure investors.
Product Type:
Structural configuration determines foundation complexity, wind-load tolerance, and multi-tenant revenue potential across Cambodian installations.
- Lattice Tower:Triangular or square steel frameworks engineered to 60-120 meter heights with bolted angle sections. Lattice structures dominate Phnom Penh and provincial hubs where EDOTCO Cambodia and Smart Axiata stack multiple operator antennas. Monsoon wind-load certification from Cambodia's national standards body adds inspection bottlenecks above 60 meters.
- Monopole:Single tubular steel shafts with smaller footprints and faster crane-less assembly. Operators in Battambang and Kampong Cham provinces deploy monopoles to meet universal service deadlines in compressed build windows.
- Stealth Tower:Concealed structures mimicking flagpoles, trees, or architectural elements. Siem Reap tourism zones and Phnom Penh heritage districts require aesthetic integration to secure municipal approvals.
- Guyed Tower:Masts stabilized by tensioned cable anchors, offering height at reduced steel tonnage. Rural greenfield sites in Ratanakiri and Mondulkiri provinces utilize guyed designs where foundation costs must minimize capital deployment.
Lattice towers lead volumes today; monopole installations are gaining share fastest.
Technology:
Wireless generation determines antenna density, power requirements, and backhaul specifications for tower-mounted equipment.
- 5G:Massive MIMO arrays and millimeter-wave equipment demanding structural reinforcement and fiber termination. Viettel Cambodia and Smart Axiata upgrade existing 4G sites with 64T64R antenna configurations, driving the steepest expansion trajectory across Cambodian infrastructure.
- 4G:Established LTE macro cells providing baseline coverage across provincial corridors. 4G installations concentrate tenancy revenue in Phnom Penh-Siem Reap corridors while serving as physical platforms for 5G overlays.
- LTE:Legacy long-term evolution equipment requiring less mounting capacity than 5G massive arrays. Rural anchor tenancies in Preah Sihanouk and Kampot provinces leverage LTE economics where subscriber density cannot justify 5G capital intensity.
- Microwave:Point-to-point backhaul links eliminating fiber trenching requirements. Microwave backhaul dominates greenfield installations in northeastern provinces where optical fiber deployment timelines extend site commissioning.
4G infrastructure anchors current tenancy revenue; 5G upgrades command the fastest capital allocation.
End User:
Customer category shapes contract duration, technical specifications, and site access protocols across the tower ecosystem.
- MNOs:Mobile network operators including Viettel Cambodia, Smart Axiata, and Cellcard seeking macro coverage expansion. MNOs negotiate anchor tenancy contracts with 10-15 year terms, dictating structural load requirements and electromagnetic emissions compliance.
- Tower Companies:Infrastructure specialists like EDOTCO Cambodia operating multi-tenant neutral host platforms. Tower companies aggregate MNO demand to maximize revenue per site while managing interference coordination across competing operators.
- Enterprises:Private network operators in mining, agriculture, and logistics sectors. Enterprise deployments concentrate in coastal economic zones and Special Economic Zones where captive connectivity reduces reliance on public mobile networks.
- Government:Universal service obligations and emergency communications infrastructure. Cambodia's Ministry of Posts and Telecommunications sponsors rural coverage programs in Mondulkiri and Ratanakiri provinces where commercial returns cannot attract private investment.
MNOs dominate tenancy contracts today; tower company outsourcing is expanding most quickly.
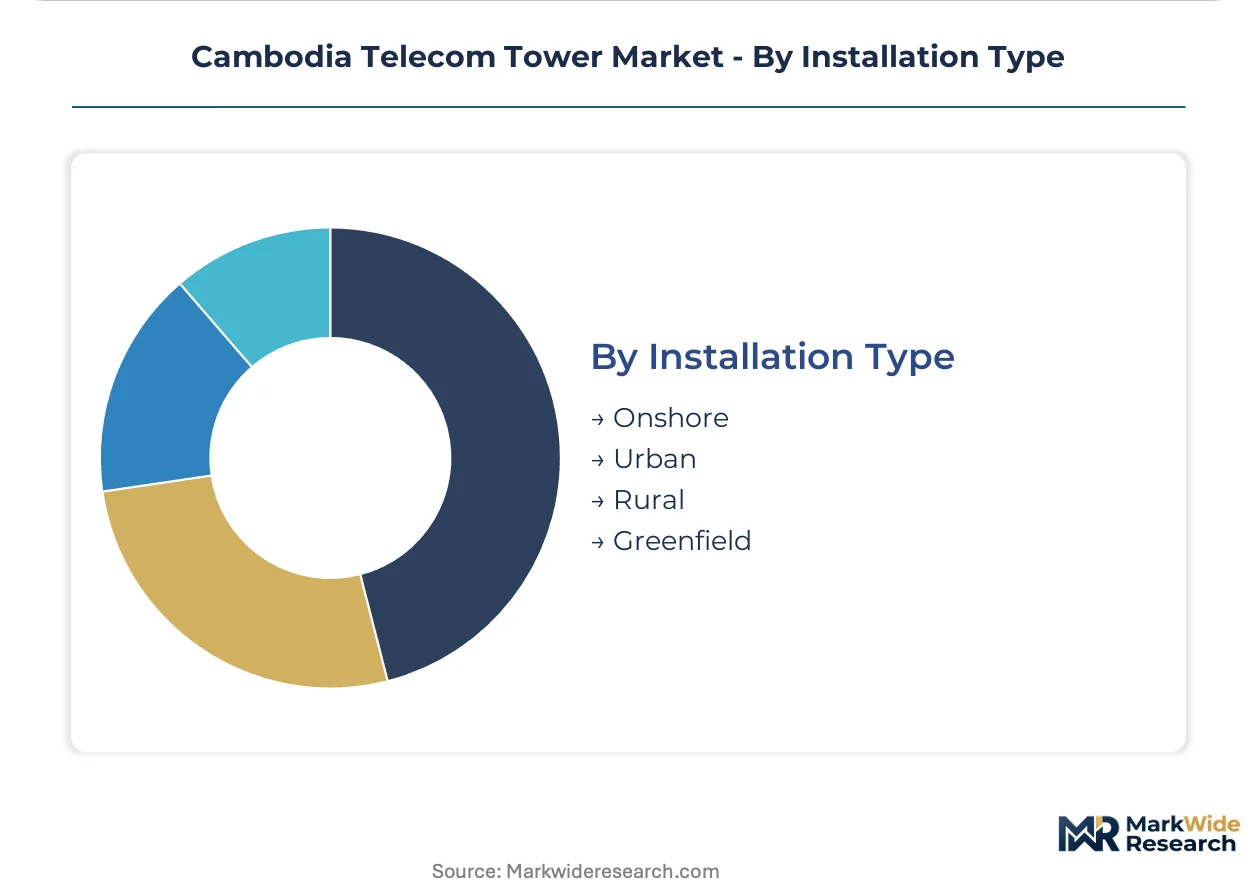
Installation Type:
Deployment context determines site acquisition complexity, construction seasonality, and regulatory approval pathways.
- Urban:Rooftop and monopole installations in Phnom Penh density corridors. Urban sites command premium tenancy rates but face municipal zoning restrictions and community consultation mandates from the Telecom Regulator.
- Rural:Provincial tower deployments outside capital region agglomeration. Rural installations in Kampong Cham and Battambang provinces follow universal service obligations with standardized structural designs and accelerated permitting.
- Greenfield:New tower construction on previously undeveloped sites. Greenfield projects in northeastern provinces require environmental impact assessments and 15-20 year land lease negotiations with provincial landowners.
- Onshore:Terrestrial installations excluding offshore or maritime platforms. Onshore classification encompasses all Cambodian tower deployment given absence of coastal offshore requirements.
Urban installations generate highest revenue per site; greenfield rural deployment is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phnom Penh anchors Cambodia's telecom tower deployment density, with tower-sharing agreements proliferating across the capital corridor and provincial hubs following streamlined licensing from the Telecom Regulator.
Phnom Penh Capital Region
Urban rooftop and monopole installations concentrate multi-tenancy demand as Smart Axiata and EDOTCO Cambodia maximize revenue per site through shared access. The Telecom Regulator mandates electromagnetic emissions compliance and community consultation before municipal construction approval. Dense clusters in Chamkarmon and Tuol Kork districts anchor premium coverage for mobile network operators upgrading 4G infrastructure with 5G massive MIMO arrays.
Siem Reap Corridor
Tourism infrastructure and heritage district zoning drive stealth tower deployments mimicking architectural elements to secure aesthetic-sensitive approvals. Cambodia's Ministry of Posts and Telecommunications coordinates with provincial authorities on universal service obligations extending coverage outward. Tower companies negotiate 15-20 year land leases with landowners in Angkor Archaeological Park buffer zones, displacing traditional purchase models to preserve capital for equipment upgrades.
Battambang and Kampong Cham Provinces
Rapid-deploy monopole systems electrify rollout velocity to meet universal service deadlines in compressed construction windows. The national standards body requires wind-load testing for lattice installations above 60 meters, creating inspection bottlenecks that push operators toward standardized monopole designs. Provincial hubs along National Road 5 concentrate anchor tenancy contracts as Viettel Cambodia sustains aggressive expansion schedules through captive engineering teams.
Preah Sihanouk and Kampot Coastal Zone
Special Economic Zone enterprise demand and port logistics infrastructure drive private network deployments alongside public mobile coverage expansion. Streamlined electromagnetic emissions certification from the Telecom Regulator collapses approval timelines for multi-tenant sites, accelerating revenue generation. Fiber-backhaul convergence integrates optical termination equipment with antenna mounts, creating bundled connectivity offerings for operators serving coastal tourism and industrial corridors.
Ratanakiri and Mondulkiri Northeastern Provinces
Greenfield rural installations gain structural importance as government universal service obligations push coverage into underserved provinces where commercial returns cannot attract private investment. Cambodia's Ministry of Posts and Telecommunications sponsors rural coverage programs through long-term anchor tenancy negotiations with tower companies. Guyed tower designs utilizing tensioned cable anchors minimize foundation costs in remote locations where capital deployment constraints dominate site selection economics.
Cambodia Telecom Tower Market Competitive Landscape
Strategic partnerships dominate the current landscape as tower-sharing mandates compress tenancy economics and accelerate rural coverage obligations. The market structures around a consolidated core of infrastructure specialists and mobile network operators with captive tower portfolios, alongside emerging neutral-host platforms. Three archetypes prevail: regional tower companies operating multi-tenant platforms, mobile network operators retaining strategic site control, and government-affiliated entities serving universal service mandates. Competitive intensity centers on site acquisition velocity and long-term lease negotiations rather than manufacturing differentiation or technology licensing.
Within the infrastructure specialist tier, EDOTCO Cambodia and Cam TowerLink exemplify the neutral-host model aggregating operator demand to maximize revenue per site. Viettel Cambodia and Smart Axiata occupy positions as mobile network operators with hybrid strategies combining owned infrastructure with third-party tenancy. Metfone and Cellcard sit within the competitive operator archetype, negotiating anchor tenancy contracts that dictate structural load requirements across Phnom Penh and provincial corridors.
| Leading Market Players |
|---|
| Metfone |
| Cellcard |
| EDOTCO Cambodia |
| Viettel Cambodia |
| Telemobile Cambodia Corporation |
| Cam TowerLink |
| Smart Axiata |
| Telecom Cambodia |
| Global Tower Corporation |
| Others |
Pricing and Supply Chain Analysis
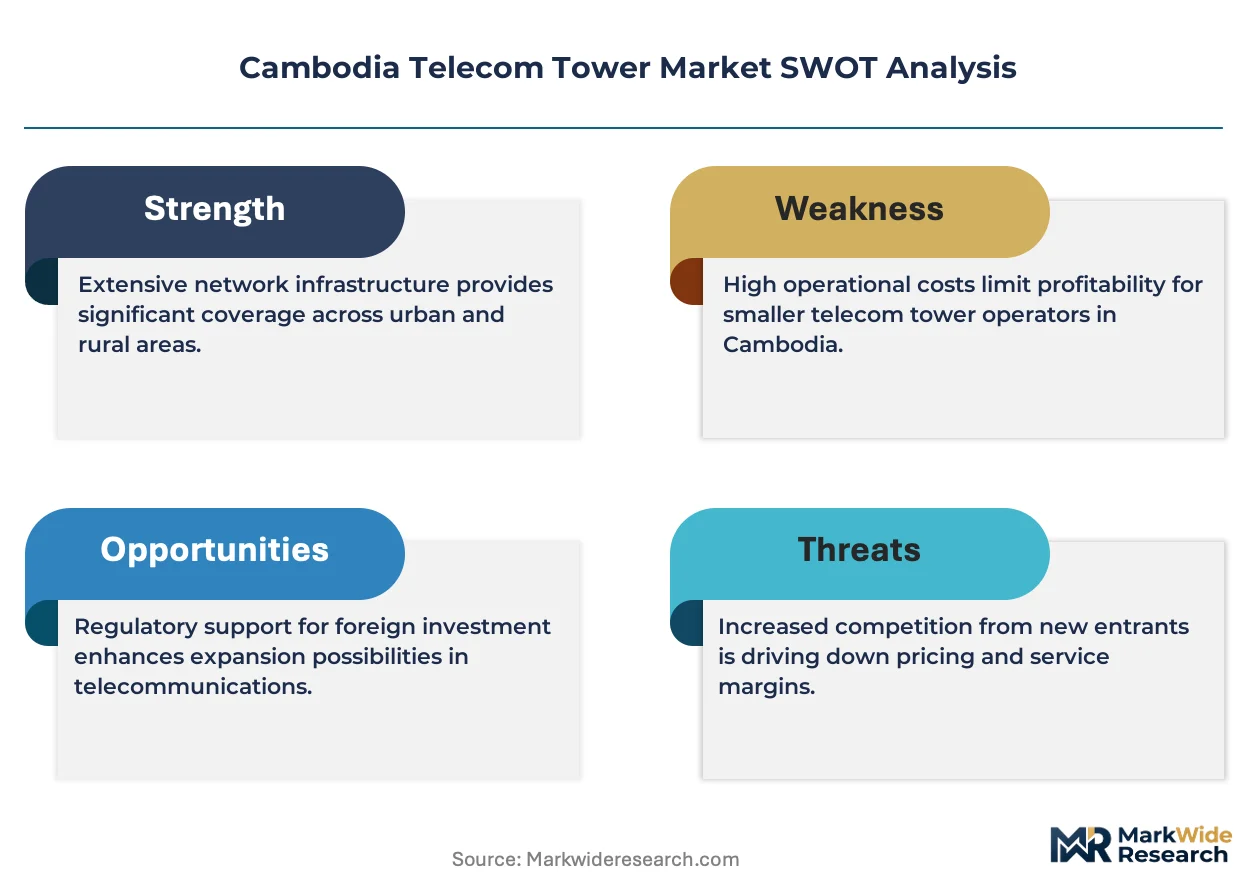
Cambodia's renewable power integration mandates for rural tower sites gate both qualified equipment supply and premium-tier pricing access for solar-hybrid installations, compressing margins for diesel-dependent operators while rewarding capital-light energy transitions.
Pricing Analysis
Imported structural steel costs pass through directly to tower fabrication quotes, with lattice frameworks commanding premium pricing over monopole alternatives due to multi-tenant load-bearing certification requirements. Price differentiation hinges on wind-load testing grades from Cambodia's national standards body and anchor tenancy contract duration. Pricing pressure intensifies in rural provinces as government universal service obligations cap tenancy rates while extending build timelines. Mobile network operators exhibit highest price sensitivity in greenfield northeastern deployments, whereas tower companies absorb premiums for Phnom Penh rooftop access.
Supply Chain Analysis
Single-source vulnerability sits with Chinese structural steel suppliers, who feed Cambodian lattice tower fabrication with limited regional alternatives. Tower construction draws from Vietnamese cement imports for reinforced concrete bases and Thai electrical components for power systems. Supply chain risk concentrates in monsoon-season logistics chokepoints along National Road 5 and Mekong riverine routes. Distribution runs through EDOTCO Cambodia's regional platform and captive engineering teams at Viettel Cambodia, with third-party logistics handling remote provincial deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cambodia's telecom tower market offers margin expansion through solar-hybrid energy retrofits, which cut diesel logistics costs while qualifying operators for rural electrification subsidies.
For Market Incumbents: Anchor tenancy economics in Phnom Penh's dense Chamkarmon clusters by consolidating rooftop access through 15-20 year lease structures that preempt competitor site acquisition. Fortify provincial hub positions in Battambang and Kampong Cham with rapid-deploy monopole inventories to capture universal service contract flows. Counter steel price volatility through bulk procurement agreements with Vietnamese fabricators ahead of monsoon construction windows. For New Entrants and Emerging Players: Begin with stealth tower deployments in Siem Reap's Angkor Archaeological Park buffer zones, where aesthetic-sensitive municipal approvals create incumbent exclusion. Target Ratanakiri and Mondulkiri provinces with guyed tower designs that minimize foundation capital in remote terrain. Pursue government-sponsored anchor tenancy contracts under Ministry of Posts and Telecommunications rural coverage programs as the primary go-to-market channel. For Investors and Strategic Acquirers: Roll-up economics work for neutral-host tower platforms because tenancy consolidation across Phnom Penh and provincial corridors generates operating leverage through shared site management. Long-term viability centers on fiber-backhaul convergence capabilities and renewable power integration scale. Monitor Telecom Regulator spectrum auction timelines as the inflection signal for 5G massive MIMO upgrade cycles and associated structural reinforcement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Tower Portfolio Consolidation | Aggregating multi-tenant sites across Phnom Penh maximizes revenue per location under streamlined Telecom Regulator licensing. |
| Solar-Hybrid Energy Transition | Reducing diesel generator dependence aligns with Cambodia's rural electrification priorities and cuts operational expenditure. |
| Fiber-Backhaul Convergence | Integrating optical termination equipment with antenna mounts creates bundled connectivity offerings for mobile network operators. |
| Rapid-Deploy Monopole Expansion | Crane-less assembly in Battambang and Kampong Cham provinces compresses build windows to meet universal service deadlines. |
| Long-Term Land Lease Structuring | 15-20 year agreements with provincial landowners preserve capital for equipment upgrades rather than real estate ownership. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tower company engineering directors, mobile network operator infrastructure leads, Telecom Regulator policy officers, and provincial land lease negotiators with secondary validation from Cambodia Ministry of Posts and Telecommunications coverage reports, ASEAN telecommunications working group protocols, and national standards body certification databases. Bottom-up site-level tenancy modeling and top-down infrastructure investment flow analysis were triangulated against regional steel import trade data.
Historical reference periods anchored the forecast window through backward-looking analysis of 4G rollout velocity and tower-sharing agreement proliferation rates across the projection horizon. Segmentation dimensions modeled include structural design type, wireless generation technology, end-user category, and installation context, with additional granularity on monsoon-season construction constraints. CAGRs were derived from tenancy revenue build-ups and capital deployment schedules, incorporating wind-load certification bottlenecks and electromagnetic emissions approval timelines as Cambodia-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced spectrum auction schedules, abrupt steel tariff adjustments, and force-majeure monsoon disruptions exceeding historical patterns. Forecasts reflect documented assumptions regarding Telecom Regulator policy continuity and Ministry of Posts and Telecommunications funding allocations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Equipment Market
Telecommunications
Qatar Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Egypt Telecom Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Philippines Telecom Market
Telecommunications
Utility Communications Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Cloud RAN Market
Telecommunications
Mobile Voice Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Middle East and Africa Telecom Market