
 Over-The-Air Software Update Market | 2026-2036
Over-The-Air Software Update Market Size, Share, and Industry Trends Forecast 2026-2036
Over-The-Air Software Update Market Analytics
Automotive embedded software engineering capacity is redrawing competitive boundaries in the Over-The-Air Software Update Market. Continental AG leverages its Tier 1 supplier relationships to sustain firmware update pipelines across European and North American OEM programs. Robert Bosch GmbH anchors its position through in-house production of secure bootloaders and telematics control units. Qualcomm Technologies, Inc. competes by dominating cellular modem integration for automotive OTA delivery.
Over-the-air software update denotes a remote firmware and application delivery mechanism that transmits encrypted binary packages across wireless links to embedded ECUs, infotainment systems, and telematics modules without physical service intervention. The technology employs delta compression algorithms and rollback safeguards to minimize bandwidth consumption and preserve system integrity during automotive, consumer electronics, and industrial deployments. Cloud-based deployment leads in scalability for automotive OEMs managing million-vehicle fleets, while edge computing architectures are gaining traction in factory automation where latency constraints preclude centralized update orchestration. Cellular technology currently occupies the largest share of automotive applications, though Wi-Fi dominates consumer electronics firmware delivery where high-bandwidth media updates are routine.
UNECE WP.29 regulations mandate cybersecurity management systems for vehicle type approval, directly compelling automotive OEMs to implement authenticated OTA update infrastructure. The EU Cyber Resilience Act extends comparable obligations to consumer electronics and industrial machinery, broadening compliance scope beyond automotive origins. The ISO/SAE 21434 standard shapes product development processes by embedding security-by-design requirements into supplier contracts and software release gates. Stakeholders must monitor how fragmented national implementations of type-approval cybersecurity rules reshape supplier qualification timelines and regional market access conditions.
Market Dynamics
Connected vehicle architectures are forcing automotive OEMs to restructure embedded software engineering organizations, compressing firmware release cycles from annual to quarterly cadences while UNECE WP.29 cybersecurity mandates harden update authentication requirements.
Growth Catalysts
- UNECE WP.29 Cybersecurity Mandates:Vehicle type-approval rules in Europe now require authenticated OTA update infrastructure, compelling OEMs to deploy secure bootloaders and encrypted delivery pipelines across production fleets.
- Delta Compression Algorithms:Bandwidth-efficient binary differencing reduces cellular data consumption by transmitting only changed code segments, enabling cost-effective updates for telematics and infotainment modules.
- German Automotive Engineering Clusters:Stuttgart and Munich anchor concentrated embedded systems talent pools that supply firmware architecture expertise to Continental AG and Robert Bosch GmbH development centers.
Market Restraints
- Cellular Modem Supply Concentration:Qualcomm Technologies dominates automotive-grade 5G modem integration, creating single-source dependencies for OTA delivery hardware in premium vehicle segments.
- Rollback Safeguard Complexity:Fail-safe firmware reversion mechanisms require redundant ECU memory partitioning that adds bill-of-materials cost and validation timeline extension.
- EU Cyber Resilience Act Compliance Burden:Consumer electronics and industrial machinery face new conformity assessment obligations that fragment supplier qualification timelines across product categories.
Strategic Opportunities
- Edge Computing Architectures:Factory automation systems with sub-100-millisecond latency constraints favor localized update orchestration over cloud-dependent deployment models.
- Wi-Fi Media Delivery Channels:Consumer electronics manufacturers leverage home broadband infrastructure for high-bandwidth firmware updates to smart televisions and streaming devices.
- ISO/SAE 21434 Contract Integration:Security-by-design requirements embedded in supplier agreements create recurring revenue streams for cybersecurity audit and certification services.
Industry Challenges
- Embedded Cryptography Talent Scarcity:Secure boot implementation and hardware security module integration require specialized firmware engineering skills concentrated in Germany and the United States.
- Multi-ECU Integration Complexity:Heterogeneous vehicle networks with legacy CAN bus and modern Ethernet backbone demand protocol translation layers that complicate update verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over-The-Air Software Update Market |
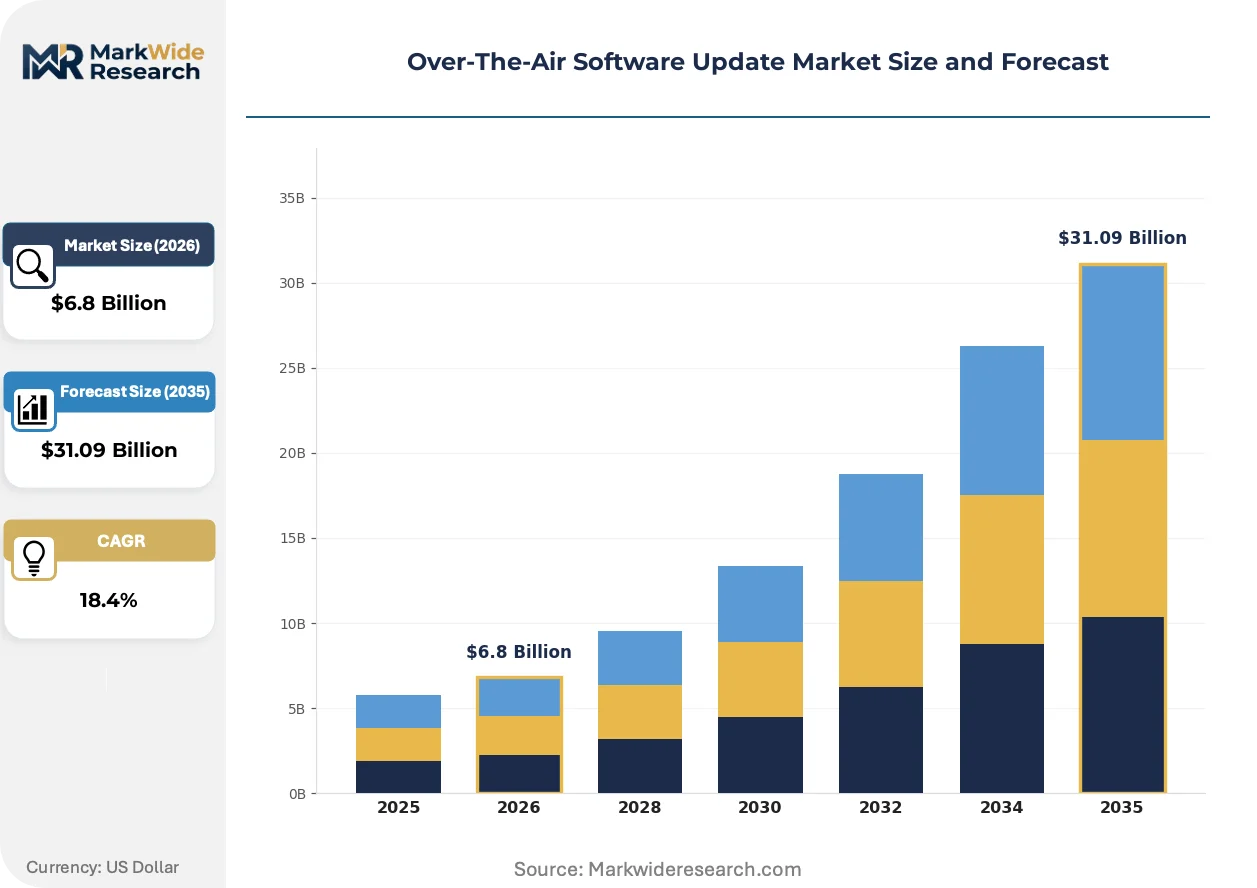
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, Edge Computing, Hybrid Model, On-Premise End User: Automotive OEMs, Consumer Electronics, Telecommunications, Industrial Machinery Technology: Wi-Fi, Cellular, Bluetooth, Satellite Application: Navigation, Infotainment, Vehicle Diagnostics, Firmware Updates |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Aptiv PLC, Infineon Technologies AG, Qualcomm Technologies, Inc., Airbiquity Inc., BlackBerry Limited, Garmin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over-The-Air Software Update Market Evolving Landscape
Firmware delivery mechanisms are fragmenting across cellular, Wi-Fi, and satellite backhaul options as automotive OEMs diversify connectivity redundancy and industrial operators prioritize deterministic update timing.
Automotive telematics control units are miniaturizing through system-on-chip integration that consolidates cellular modem, secure element, and application processor into single-package solutions. Tier 1 suppliers are adopting these consolidated designs to reduce ECU footprint and wiring harness complexity. This integration is miniaturizing hardware bills of materials while compressing supplier qualification cycles for connected vehicle programs.
REACH chemical substance restrictions and RoHS substance limits are tightening solder and component material specifications for automotive electronics manufacturing. European component suppliers are reformulating alloy compositions and substrate materials to maintain type-approval eligibility. German OEM supply chains face the steepest compliance recertification burdens as KBA enforcement tightens documentation requirements.
Fleet operators are consolidating software procurement decisions at the corporate level rather than delegating to regional maintenance units. Centralized IT governance is displacing distributed service-center autonomy for update scheduling and version control. This concentration is most visible in North American commercial vehicle leasing operations where uptime guarantees drive standardization across mixed-brand fleets.
Over-The-Air Software Update Market Segmentation
Segmentation in the Over-The-Air Software Update Market exposes how regulatory mandates, connectivity infrastructure, and end-use complexity fragment vendor strategies across deployment architectures and delivery channels. Understanding these divides clarifies where engineering investments concentrate and which customer types command premium pricing.
Deployment:
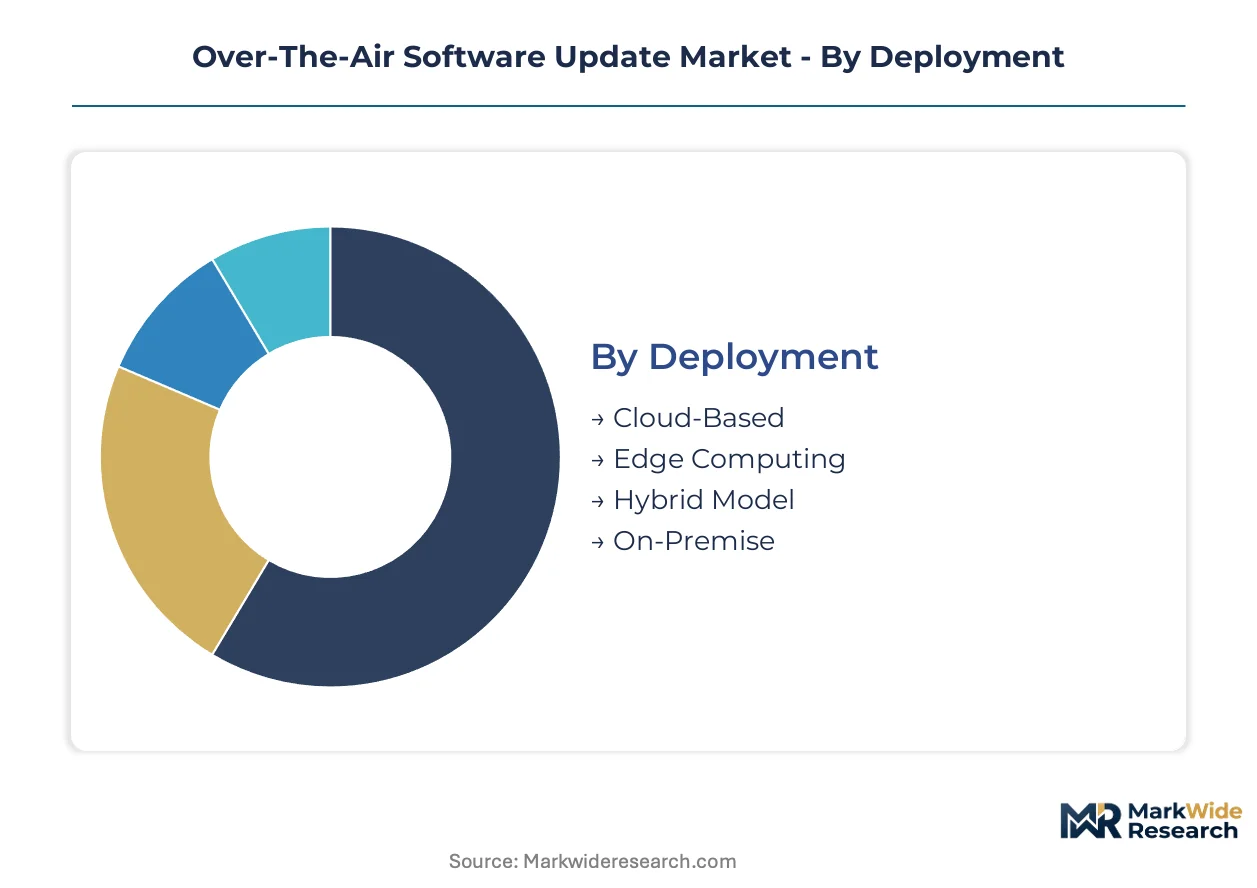
UNECE WP.29 vehicle type-approval rules in Europe mandate centralized cybersecurity management systems, creating divergent compliance burdens between cloud-dependent and localized deployment models.
- Cloud-Based:Centralized orchestration platforms manage encrypted firmware distribution across million-vehicle fleets with automated rollback protocols. Automotive OEMs in Germany and the United States dominate demand as connected vehicle architectures proliferate and UNECE WP.29 mandates harden authentication requirements.
- Edge Computing:Localized update servers process binary packages within factory premises or vehicle depots, eliminating latency for deterministic industrial control systems. Manufacturing clusters in Stuttgart and Munich favor this architecture where sub-100-millisecond response times preclude cloud dependency.
- Hybrid Model:Combines cloud orchestration with edge caching to balance scalability against latency constraints in mixed fleet environments.
- On-Premise:Fully isolated infrastructure serving defense and critical infrastructure operators with air-gapped security requirements.
Established volume favors Cloud-Based deployment; emerging adoption favors Edge Computing.
End User:
Customer procurement sophistication varies sharply, with automotive OEMs embedding OTA requirements into Tier 1 supplier contracts while consumer electronics manufacturers treat firmware delivery as a cost-center function.
- Automotive OEMs:Type-approval cybersecurity regulations in Europe, the United States, and Japan compel authenticated update pipelines across production vehicle fleets. German manufacturers anchor engineering talent concentration, while Japanese OEMs integrate OTA into hybrid powertrain control strategies.
- Consumer Electronics:Smart television and streaming device manufacturers leverage home Wi-Fi infrastructure for high-bandwidth media firmware delivery. South Korean and Chinese electronics clusters drive volume through rapid product refresh cycles.
- Telecommunications:Base station and router vendors require remote firmware management across distributed network infrastructure.
- Industrial Machinery:Factory automation systems demand deterministic update timing with redundant fail-safe mechanisms.
Procurement sophistication peaks with Automotive OEMs; volume expansion is climbing the fastest in Consumer Electronics.
Technology:
Connectivity backhaul selection hinges on bandwidth requirements, geographic coverage, and hardware bill-of-materials constraints across target end-use applications.
- Cellular:Automotive-grade 5G modems enable encrypted firmware delivery to vehicles in motion across wide geographic footprints. Qualcomm Technologies dominates modem integration, creating supply concentration in premium vehicle segments subject to UNECE WP.29 mandates.
- Wi-Fi:High-throughput local connectivity serves consumer electronics and residential IoT where stationary devices access home broadband. Chinese smart home ecosystems and South Korean electronics manufacturers anchor demand concentration.
- Bluetooth:Low-energy protocols support peripheral and wearable device updates with minimal power consumption.
- Satellite:Backhaul redundancy for remote asset tracking and maritime applications beyond cellular coverage.
Cellular commands premium pricing in automotive; Wi-Fi delivers volume scale in consumer applications.
Application:
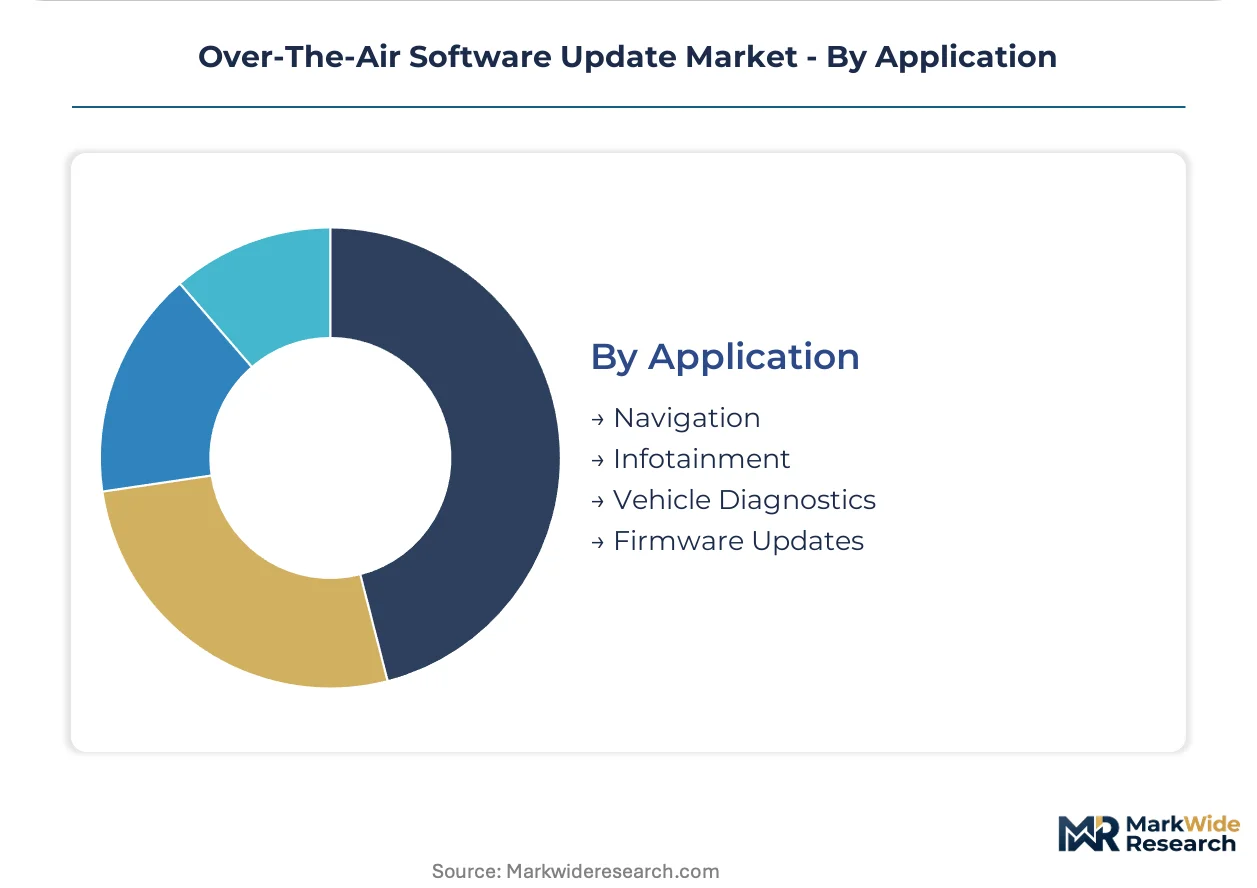
Functional criticality determines update frequency, rollback complexity, and regulatory scrutiny across embedded system categories.
- Infotainment:High-bandwidth media and application updates occur quarterly with user-visible feature enhancements. German and Japanese OEMs prioritize over-the-air content delivery to reduce dealership service burdens.
- Firmware Updates:Core ECU binary patches demand cryptographic authentication and redundant memory partitioning under ISO/SAE 21434 development processes. European automotive suppliers face the steepest validation timelines as KBA enforcement tightens documentation requirements.
- Navigation:Map data and routing algorithm updates require periodic connectivity but tolerate brief service interruptions.
- Vehicle Diagnostics:Remote health monitoring enables predictive maintenance scheduling and warranty cost reduction.
Firmware Updates absorb the highest engineering investment; Infotainment shows the steepest expansion trajectory in consumer-facing feature velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA enforcement of UNECE WP.29 vehicle type-approval rules in Germany is reshaping supplier qualification timelines across European automotive supply chains. National regulators in Japan, the United States, and China are issuing parallel cybersecurity mandates that fragment compliance architectures.
Germany
Automotive OEMs in Stuttgart and Munich are compressing firmware release cycles from annual to quarterly cadences under KBA documentation requirements. The country's national automotive regulator enforces ISO/SAE 21434 security-by-design standards through supplier contract audits. Continental AG and Robert Bosch GmbH development centers in Baden-Württemberg and Bavaria anchor embedded cryptography talent pools for secure bootloader implementation.
United States
NHTSA cybersecurity guidance is compelling domestic OEMs to deploy authenticated OTA pipelines across production fleets. The national highway safety regulator coordinates with FCC on spectrum allocation for cellular modem integration. Michigan and California engineering clusters concentrate telematics control unit design expertise serving Detroit and Silicon Valley automotive programs.
Japan
METI connected vehicle initiatives are integrating OTA requirements into hybrid powertrain control strategies. The ministry's technology standards shape JIS certification processes for encrypted firmware delivery. Toyota City and Nagoya industrial corridors host concentrated embedded systems engineering for automotive-grade secure element production.
China
MIIT vehicle-network security standards mandate remote update authentication for domestic OEM type approval. The ministry's GB standards framework governs cellular modem integration in connected vehicle architectures. Shenzhen and Shanghai electronics clusters supply system-on-chip solutions consolidating modem and secure element functions.
South Korea
MFDS cybersecurity guidelines for automotive software are extending to infotainment system update mechanisms. The national pharmaceutical and medical device regulator's framework influences adjacent electronics certification processes. Seoul Capital Area manufacturing complexes produce high-volume telematics modules for Hyundai and Kia production programs.
Over-The-Air Software Update Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Over-The-Air Software Update Market. Tier 1 automotive suppliers with captive firmware engineering organizations occupy the upper tier, while semiconductor and software specialists populate the fragmented lower tier. Two strategic archetypes dominate: integrated hardware-software platform vendors and pure-play cybersecurity authentication providers. Competitive moves center on backward integration into secure element production and geographic expansion through European OEM supplier qualification programs.
Among German-based integrated suppliers, Continental AG and Robert Bosch GmbH exemplify the platform-vendor archetype through their embedded software engineering capacity. Qualcomm Technologies, Inc. occupies a distinct position representing cellular modem integration specialists. These three companies anchor different competitive vectors: Continental AG and Robert Bosch GmbH through Tier 1 supplier relationships, Qualcomm Technologies through semiconductor hardware dominance.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Aptiv PLC |
| Infineon Technologies AG |
| Qualcomm Technologies, Inc. |
| Airbiquity Inc. |
| BlackBerry Limited |
| Garmin Ltd |
| Others |
Value Network & Pricing Analysis
UNECE WP.29 vehicle type-approval cybersecurity requirements gate both supplier qualification timelines and price differentiation across automotive OTA deployment tiers, compressing margins for uncertified vendors while premiumizing authenticated infrastructure.
Pricing Analysis
Long-term offtake contracts dominate automotive OTA procurement, with German OEMs locking in multi-year firmware delivery agreements that embed ISO/SAE 21434 certification costs upfront. Price differentiation hinges on cybersecurity audit depth and cellular modem integration grade, with Qualcomm-enabled premium tiers commanding substantial premiums over Wi-Fi-dependent economy configurations. Cost compression in consumer electronics firmware delivery is intensifying because South Korean and Chinese manufacturers compete on volume scale with minimal authentication overhead. Fleet operators exhibit the lowest price sensitivity due to uptime guarantee penalties, while consumer electronics manufacturers treat OTA as a cost-center function with aggressive vendor consolidation.
Supply Chain Analysis
Just-in-time inventory strategies prevail in automotive telematics manufacturing, though strategic stockpiling of secure elements and automotive-grade 5G modems has emerged among German Tier 1 suppliers anticipating Qualcomm allocation constraints. Geographic supply concentration centers on Germany, South Korea, and Taiwan, with Baden-Württemberg anchoring embedded cryptography talent, Seoul supplying high-volume modem integration, and Hsinchu feeding system-on-chip consolidation. Raw material dependencies span silicon wafers, rare earth elements for magnet components, and specialized solder alloys compliant with REACH restrictions. Single-source vulnerability in Qualcomm's automotive modem portfolio creates systemic exposure for European OEM programs. Distribution runs through Tier 1 supplier direct-ship arrangements to OEM assembly plants, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Over-The-Air Software Update Market sits in early-cycle expansion as UNECE WP.29 regulatory mandates force laggard OEMs into accelerated procurement of authenticated infrastructure, creating a compliance-driven demand tailwind with years of runway ahead.
For Market Incumbents: Fortify supplier lock-in through backward integration into secure element production and captive firmware engineering capacity in Stuttgart and Munich development centers. The threat of semiconductor specialists encroaching on telematics integration demands preemptive certification investment in ISO/SAE 21434 audit capabilities. Channel control through long-term offtake agreements with German OEMs remains the priority defensive lever against modular platform competitors.
For New Entrants and Emerging Players: EU Cyber Resilience Act fast-track certification for consumer electronics and industrial machinery segments offers the most penetrable entry vector, as automotive supplier qualification timelines extend 18-24 months for unproven vendors. White-space concentration sits in factory automation edge-computing deployments where sub-100-millisecond latency requirements preclude incumbent cloud architectures. A channel partnership route through European industrial machinery OEMs bypasses direct automotive Tier 1 competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pure-play cybersecurity authentication services as software margins expand relative to hardware-dependent modem integration. Long-term viability over a 5-10 year window favors acquisition targets with embedded cryptography talent pools and existing UNECE WP.29 supplier qualification status. The signal to watch is KBA documentation enforcement tightening, which would accelerate consolidation among uncertified firmware engineering boutiques.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Bootloader Certification Investment | KBA audit readiness accelerates German OEM supplier qualification timelines. |
| Cellular Modem Supply Agreement | Qualcomm allocation security de-risks premium vehicle program launches. |
| Edge Computing Architecture Deployment | Factory automation latency requirements favor localized update orchestration. |
| ISO/SAE 21434 Contract Integration | Security-by-design clauses create recurring cybersecurity audit revenue streams. |
| System-on-Chip Consolidation Partnership | Single-package modem and secure element integration reduces ECU footprint. |
Research Methodology
A spread of perspectives from automotive platform engineers, Tier 1 supplier procurement leads, cybersecurity certification auditors, and industrial automation systems integrators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against UNECE WP.29 regulatory filings, KBA type-approval documentation, MIIT vehicle-network security standards, and automotive OEM supplier contract disclosures. Bottom-up triangulation across deployment architecture adoption curves and top-down reconciliation against cellular modem shipment data anchored volume estimates.
Segmentation dimensions modeled span cloud-based, edge computing, hybrid, and on-premise deployment architectures; automotive OEM, consumer electronics, telecommunications, and industrial machinery end-user categories; cellular, Wi-Fi, Bluetooth, and satellite technology channels; and infotainment, firmware, navigation, and diagnostics application types. CAGRs were derived from fitted adoption curves across the projection horizon, with automotive content-per-vehicle trajectories and consumer electronics refresh cycle compression serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained UNECE WP.29 enforcement consistency and Qualcomm supply continuity would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and cellular infrastructure deployment trajectories. Revision becomes warranted when KBA documentation requirements or MIIT cybersecurity standards cross enforcement thresholds that fragment supplier qualification architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Handyman Software Market
Software & Services
Tenant Billing System Market
Software & Services
Binary Drivers Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Email Applications Market
Software & Services
Enterprise Mobility Software Market
Software & Services
User Feedback Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Labeling Software Market
Software & Services
Global Document Control Software Market
Software & Services
Smartphone Applications Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Machine Translation Software Market
Software & Services
Global Healthcare Contract Management Software Market