
 Robocall Mitigation Market | 2026-2036
Robocall Mitigation Market Size, Share, and Industry Trends Forecast 2026-2036
Robocall Mitigation Market Analytics
Carrier-grade authentication standards are bifurcating the competitive landscape between legacy firewall vendors and real-time signaling specialists. First Orion leverages deep network integration with tier-one mobile operators to sustain its installed base across North American carriers. Numeracle differentiates through certified caller identity restoration services that anchor enterprise trust programs. Hiya competes via consumer-facing mobile applications that extend brand protection into endpoint devices.
Robocall mitigation encompasses real-time call authentication, caller ID verification, and traffic anomaly detection systems operating at the signaling layer of voice networks. These platforms analyze SIP invite headers, originating number reputation scores, and behavioral call patterns to block fraudulent or unsolicited voice communications before completion. Cloud-based deployment now leads service type expansion as telecom operators shift capital expenditure models toward subscription architectures. Machine learning capabilities within number verification represent the fastest-growing technology segment, where margin pools concentrate around continuous model retraining and threat intelligence feeds. Call blocking retains volume dominance but faces commoditization pressure from carrier-native implementations.
The FCC's STIR/SHAKEN framework and corresponding enforcement actions directly shape product roadmaps and procurement specifications across US telecom operators. Health Canada's parallel consultation on caller ID authentication creates compliance complexity for vendors serving cross-border carrier groups. Enterprises must monitor evolving traceback obligations and attestation tier requirements to maintain voice channel deliverability.
Market Dynamics
Carrier-grade STIR/SHAKEN attestation tiers are compressing margins for standalone verification vendors while embedding authentication deeper into core network infrastructure. This technical mandate is forcing enterprise buyers to requalify voice service providers against attestation-level guarantees.
Growth Catalysts
- FCC Enforcement Escalation:Civil penalties exceeding $200 million against non-compliant carriers are accelerating procurement of certified authentication gateways. Tier-one mobile operators now require A-level attestation for all enterprise trunking contracts.
- Financial Services Voice Channel Defense:Banks and insurance carriers face account-takeover fraud via voice spoofing. Real-time caller identity verification has become mandatory for high-value transaction confirmations.
- Cloud-Native SIP Architecture:Telecom operators migrating from TDM to all-IP cores can deploy software-based verification without hardware swaps. This infrastructure refresh cycle opens retrofit opportunities for signaling-layer security vendors.
Market Restraints
- Attestation Tier Complexity:B-level and C-level call classifications create deliverability uncertainty for legitimate high-volume callers. Healthcare appointment reminders and utility outage notifications face erroneous blocking.
- Cross-Border Authentication Gaps:STIR/SHAKEN certificates issued by US credentialing authorities lack reciprocal recognition in Canadian and Mexican networks. International carrier groups must maintain parallel verification stacks.
- Signaling Processing Latency:Real-time SIP header analysis adds 15-40 milliseconds per call leg. Low-latency trading floors and emergency dispatch centers resist deployment where milliseconds determine operational outcomes.
Strategic Opportunities
- India TRAI Authentication Mandate:India's telecom regulator is consulting on caller ID verification frameworks analogous to STIR/SHAKEN. Early-mover vendors can anchor standards development and capture operator procurement cycles.
- Enterprise Brand Identity Restoration:Spoofed numbers damage consumer trust in legitimate brands. Certified caller identity services that restore answer rates represent a recurring-revenue white space beyond carrier core networks.
- Machine Learning Convergence with Threat Intelligence:Behavioral anomaly detection fused with real-time number reputation scoring enables preemptive blocking before ring events. This technology stack differentiation commands premium pricing against rule-based alternatives.
Industry Challenges
- Signaling Protocol Expertise Scarcity:Deep knowledge of SS7 and SIP interoperability is concentrated among legacy telecom engineering cohorts. Vendors compete aggressively for protocol specialists capable of carrier integration.
- Certification Timeline Compression:FCC Safe Harbor deadlines and state-level mini-SHAKEN laws create overlapping compliance windows. Product teams must parallel-track multiple attestation implementations.
- Legacy PBX Integration Friction:Enterprises with on-premise Avaya and Cisco voice infrastructure require session border controller upgrades to pass authenticated signaling. Migration complexity delays authentication deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robocall Mitigation Market |
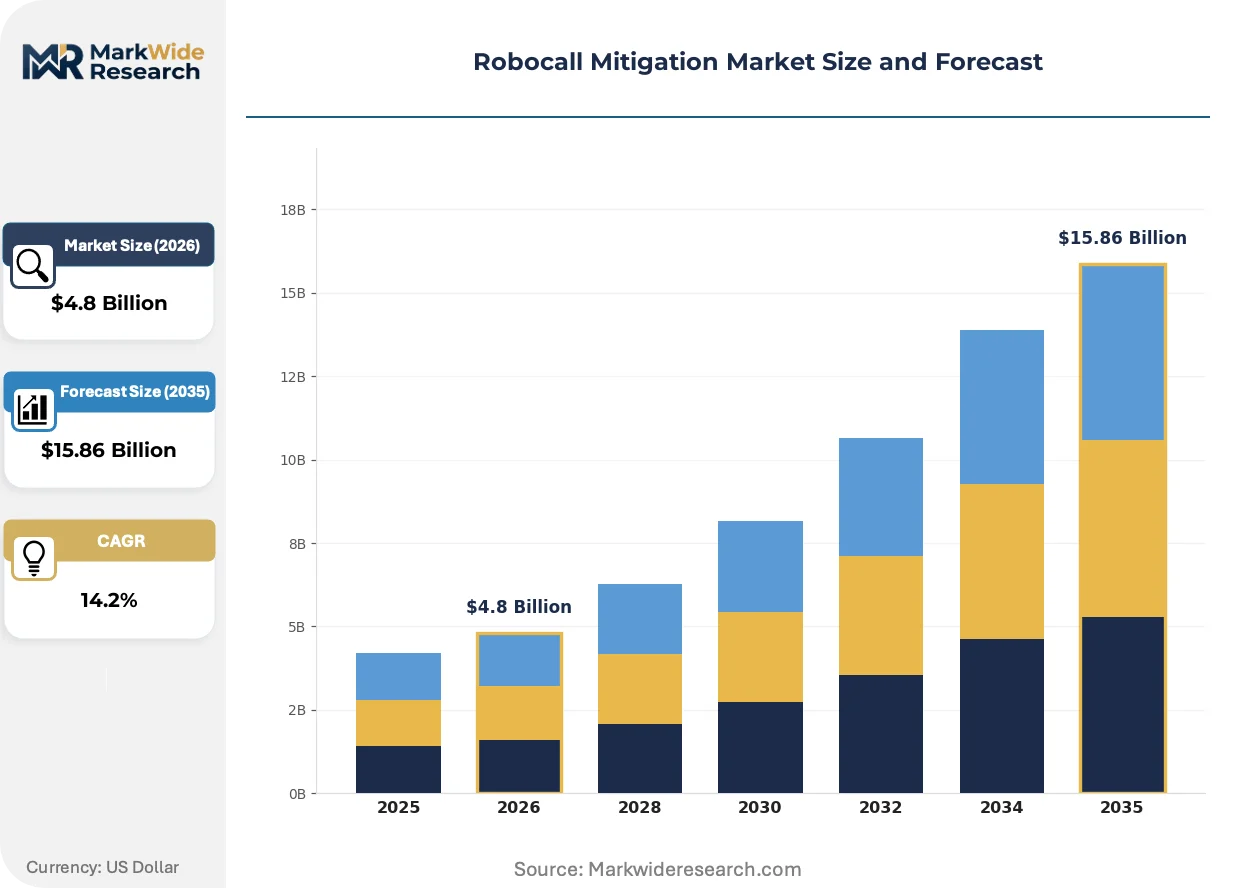
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Call Blocking, Number Verification, Reporting Solutions, Compliance Tools Deployment: On-Premises, Cloud-Based, Hybrid Systems, Mobile Applications End User: Telecom Operators, Enterprises, Government Agencies, Consumers Technology: Machine Learning, Artificial Intelligence, Data Analytics, Telephony |
| Companies Covered | LANCK Telecom, Mobileum, First Orion, Numeracle, Neural Technologies, Hiya, Metaswitch, NUSO, iconectiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robocall Mitigation Market Evolving Landscape
Artificial intelligence is embedding deeper into real-time call analysis, shifting competitive advantage from static blocklists to continuously learning threat models. This transition is redrawing vendor capabilities and buyer evaluation criteria.
Machine learning-based number reputation scoring is fragmenting the competitive landscape between specialized AI vendors and carrier-native analytics teams. Tier-one operators are building in-house models using proprietary call data, while mid-tier carriers license third-party scoring APIs. This capability divergence is compressing margins for standalone algorithm providers while creating integration service opportunities.
The FCC's expanded traceback mandate now requires carriers to identify call originators within 24 hours of complaint filing. This enforcement mechanism is forcing voice service providers to maintain granular call detail records and automated query interfaces. Wholesale carriers serving reseller channels face the steepest compliance burden as they lack direct subscriber relationships.
Enterprise buyers are unbundling voice security from bundled telecom contracts, creating direct procurement relationships with authentication specialists. Healthcare providers and financial institutions now issue separate RFPs for caller identity verification independent of transport services. This purchasing pattern shift is most visible in the United States, where STIR/SHAKEN compliance liability concentrates with terminating carriers.
Robocall Mitigation Market Segmentation
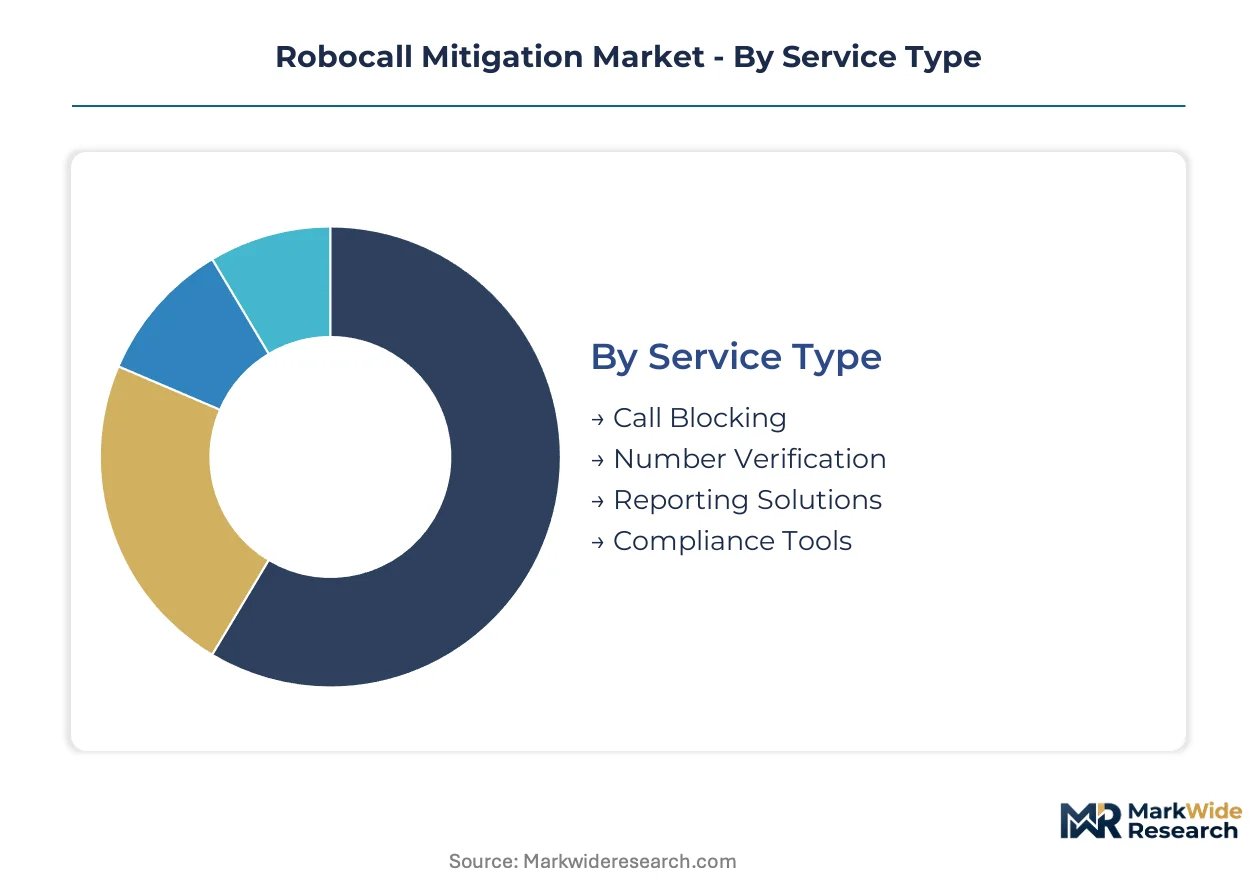
Robocall mitigation vendors configure product portfolios around distinct deployment architectures and buyer risk profiles. Segmentation reveals where authentication technology commands premium pricing versus commodity substitution.
Service Type:
Carrier procurement channels favor bundled authentication suites, while enterprise buyers increasingly unbundle verification services from transport contracts.
- Call Blocking:Rule-based and heuristic filtering systems intercept suspicious calls before ring events. Telecom operators in the United States deploy these at network edges to satisfy FCC traceback mandates with minimal latency overhead.
- Number Verification:Real-time STIR/SHAKEN attestation and caller identity restoration anchor enterprise trust programs. Financial institutions in North America now require A-level attestation guarantees for high-value transaction confirmations.
- Reporting Solutions:Automated complaint aggregation and traceback query interfaces address FCC enforcement requirements.
- Compliance Tools:Certification management and attestation tier monitoring reduce regulatory liability for wholesale carriers.
By volume, Call Blocking leads. By growth pace, Number Verification is ahead.
Deployment:
Capital expenditure constraints push mid-tier carriers toward subscription models, while latency-sensitive buyers retain on-premise control.
- Cloud-Based:Software-defined verification scales across SIP trunking without hardware swaps. Canadian operators migrating from TDM cores favor this architecture for rapid STIR/SHAKEN compliance.
- On-Premises:Session border controllers and signaling gateways process authentication within carrier data centers. Trading floors and emergency dispatch centers in the United States resist cloud migration where milliseconds determine outcomes.
- Hybrid Systems:Split processing between edge appliances and cloud analytics balances latency with scalability.
- Mobile Applications:Consumer-facing brand protection extends caller identity verification to endpoint devices.
Cloud-Based deployments now dominate new procurement. Hybrid Systems are climbing the fastest as incumbents bridge legacy infrastructure.
End User:
Compliance liability concentrates with terminating carriers, but enterprise direct procurement is accelerating.
- Telecom Operators:Tier-one mobile and wireline carriers bear primary STIR/SHAKEN implementation burden. United States operators now embed authentication deep into core network infrastructure.
- Enterprises:Banks, insurers, and healthcare providers issue separate RFPs for caller identity verification. Voice spoofing defenses have become mandatory for account-takeover protection.
- Government Agencies:Federal and state entities procure traceback capabilities for enforcement support.
- Consumers:Mobile application downloads drive brand protection into personal devices.
Telecom Operators absorb the largest share of authentication spending. Enterprise procurement is gaining share fastest.
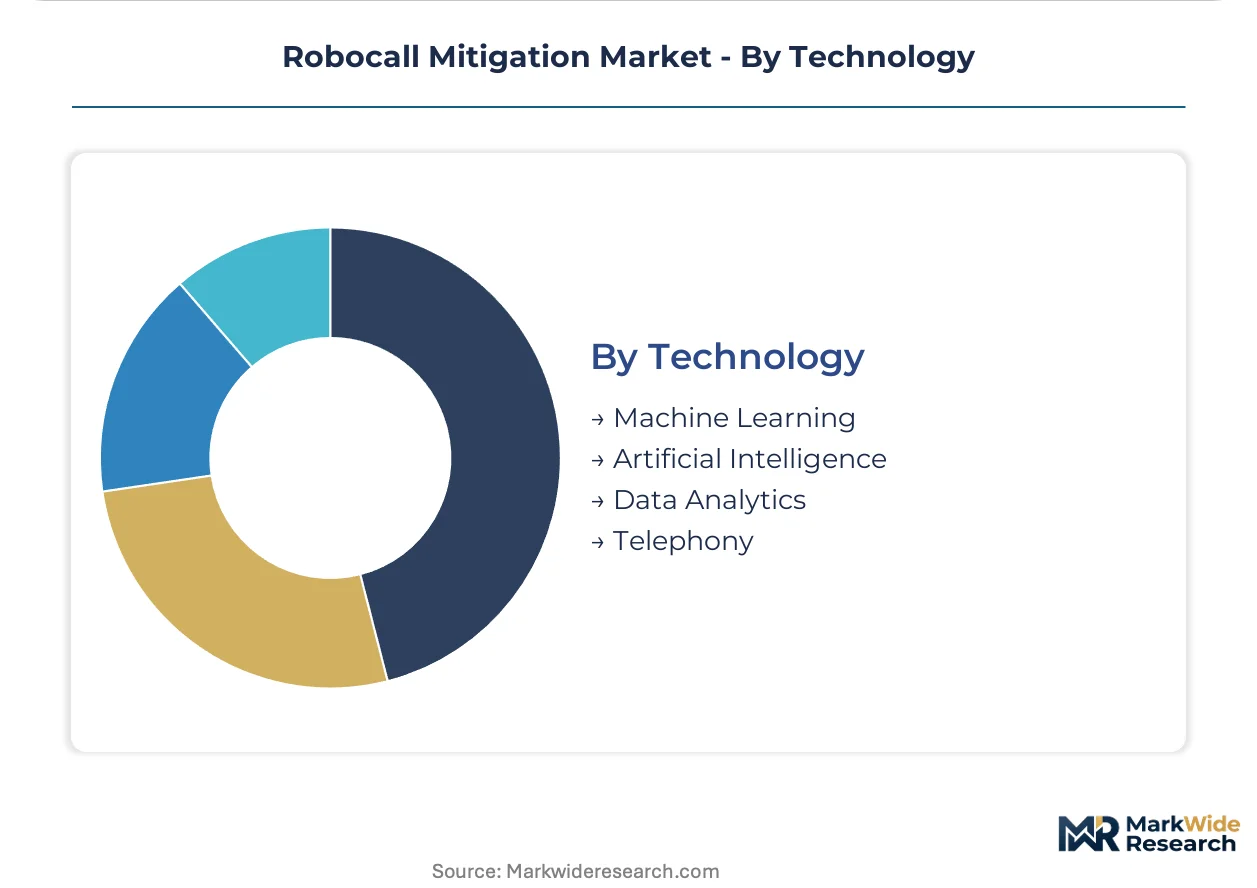
Technology:
Margin pools concentrate around continuous model retraining and threat intelligence integration.
- Machine Learning:Behavioral anomaly detection and number reputation scoring enable preemptive blocking. Tier-one operators build proprietary models using call data, while mid-tier carriers license third-party APIs.
- Artificial Intelligence:Natural language processing and voice biometrics verify caller identity in real time.
- Data Analytics:Pattern recognition across call detail records supports traceback and fraud investigation.
- Telephony:SS7 and SIP protocol expertise underpins carrier-grade authentication gateway development.
Machine Learning commands the steepest expansion trajectory as static blocklists lose effectiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border voice traffic imbalances shape authentication infrastructure deployment, with net-importing markets accelerating compliance investment faster than export-heavy corridors. Regulatory asymmetries between adjacent jurisdictions create parallel certification burdens for international carrier groups.
United States
Tier-one mobile operators and wholesale voice carriers drive procurement volume under FCC enforcement pressure. The STIR/SHAKEN mandate and Safe Harbor deadlines compress vendor certification timelines. Dallas-Fort Worth and Northern Virginia data center clusters host the densest concentration of signaling gateway deployments.
Canada
Incumbent wireline operators and cable voice providers retrofit TDM cores for IP-based authentication compliance. Health Canada's parallel consultation on caller ID verification creates attestation complexity for cross-border trunking groups. Toronto and Montreal anchor the primary carrier infrastructure investment zones.
United Kingdom
Ofcom's emerging authentication framework consultation shapes operator procurement specifications ahead of mandate finalization. BT Group and alternative network providers evaluate STIR/SHAKEN-compatible architectures. London's telehouse ecosystem concentrates vendor proof-of-concept and interoperability testing activity.
Germany
Deutsche Telekom and regional carrier associations pilot caller verification protocols through the national telecom regulator's working groups. The Bundesnetzagentur coordinates with EU counterparts on cross-border certificate reciprocity. Frankfurt's internet exchange hub attracts authentication gateway peering investments.
India
TRAI's consultation on caller ID verification frameworks positions the market for standards-aligned procurement cycles. Reliance Jio and Bharti Airtel evaluate real-time signaling analysis for spam call reduction. Bengaluru and Hyderabad technology corridors host vendor development centers targeting operator integration partnerships.
Robocall Mitigation Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and customer access dimensions, creating a bifurcated vendor ecosystem. Tier-one carriers favor established suppliers with balance sheet depth for long-term service contracts, while mid-market operators source from agile private vendors. Three archetypes dominate: network-integrated authentication providers, enterprise-facing identity restoration specialists, and consumer endpoint application developers. Consolidation pressure intensifies through strategic partnerships between signaling infrastructure vendors and cloud analytics platforms.
Within the network-integrated tier, First Orion and Numeracle exemplify divergent positioning strategies. First Orion anchors deep carrier relationships through tier-one mobile operator deployments. Numeracle occupies a certified caller identity restoration niche serving enterprise trust programs. Hiya represents the consumer-facing application archetype, extending brand protection into mobile endpoint devices without direct carrier infrastructure dependency.
| Leading Market Players |
|---|
| LANCK Telecom |
| Mobileum |
| First Orion |
| Numeracle |
| Neural Technologies |
| Hiya |
| Metaswitch |
| NUSO |
| iconectiv |
| Others |
Value Network & Pricing Analysis
Ninety-day certification timelines for STIR/SHAKEN gateway deployments compress procurement cycles and concentrate pricing power among vendors with pre-approved FCC credentialing, while carrier-native implementations force standalone authentication specialists toward SaaS-tiered subscription models to defend margin retention.
Pricing Analysis
Enterprise voice service buyers anchor pricing stratification across A-level attestation premiums, B-level verification standards, and C-level economy tiers differentiated by call volume commitments and real-time analytics depth. Price differentiation hinges on FCC Safe Harbor certification tier and cross-border certificate reciprocity coverage. Cost compression in mid-tier verification APIs is intensifying because tier-one operators are building proprietary machine learning models in-house. Wholesale carriers serving reseller channels exhibit the highest price sensitivity due to thin termination margins.
Supply Chain Analysis
SS7 and SIP protocol engineering talent concentration in the United States, India, and Germany creates a chokepoint that constrains carrier integration velocity for authentication gateway vendors. Component dependencies span cloud infrastructure from hyperscalers, threat intelligence feeds from cybersecurity specialists, and telecommunications-grade hardware from session border controller manufacturers. Single-source vulnerability in FCC-certified credentialing authorities exposes international carrier groups to compliance timeline risk. Distribution runs through direct operator procurement teams and enterprise voice security RFP channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robocall mitigation market operates as a regulatory-moat business where FCC STIR/SHAKEN entrenchment creates high switching costs for carrier customers once authentication infrastructure is embedded.
For Market Incumbents: Fortify carrier relationships through exclusive tier-one mobile operator integration partnerships that preempt standalone verification vendor displacement. Deepen backward integration into proprietary machine learning model development to reduce API licensing dependency and capture margin pools from continuous threat intelligence retraining. For New Entrants and Emerging Players: FCC Safe Harbor fast-track certification for hybrid cloud-on-premise deployments unlocks wholesale carrier segments underserved by legacy firewall vendors. Target healthcare appointment reminder services and utility notification systems facing B-level attestation deliverability uncertainty. Lead with API-first integration positioning that minimizes session border controller upgrade friction for Avaya and Cisco voice infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications infrastructure conglomerates seeking to divest non-core signaling security units amid cloud-native architecture transitions. Long-term viability centers on recurring revenue from certified caller identity restoration services rather than one-time gateway licensing. Watch TRAI mandate finalization in India as the primary inflection signal for emerging market authentication procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| STIR/SHAKEN Gateway Certification | FCC Safe Harbor approval secures tier-one operator procurement preference and liability protection. |
| Machine Learning Model Proprietary Development | In-house behavioral anomaly detection reduces third-party API dependency and captures premium pricing. |
| Enterprise Brand Identity Restoration Service Launch | Certified caller identity programs restore answer rates for financial institutions and healthcare providers. |
| Cross-Border Certificate Reciprocity Partnership | Mutual recognition agreements between FCC, Health Canada, and Ofcom reduce parallel compliance stacks. |
| Hybrid Cloud-Edge Architecture Deployment | Split processing balances latency requirements for trading floors with scalability for mid-tier carriers. |
Research Methodology
The analysis maps call blocking, number verification, reporting solutions, and compliance tools, each validated through network operations executives at tier-one carriers, enterprise voice procurement officers, FCC enforcement attorneys, and signaling protocol engineers. Primary fieldwork combined with secondary validation from FCC enforcement orders, STIR/SHAKEN governance authority filings, carrier capex disclosures, and Health Canada consultation documents. Bottom-up deployment volume estimates triangulated against top-down regulatory mandate compliance spending.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end-user category, and technology stack complexity. CAGRs were derived from carrier infrastructure refresh cycle timing and enterprise unbundling procurement patterns. Forecast inputs incorporate FCC penalty escalation trajectories and international mandate adoption curves.
Underlying assumptions cover sustained FCC enforcement intensity and cross-border certificate reciprocity progress, with deviation risk concentrated in TRAI mandate delays and legacy PBX migration friction. Practitioners should keep alternative scenarios live as regulatory timeline compression and signaling protocol expertise scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Mass Notification System Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Online Background Check Market
Security Software
Device Vulnerability Management Market
Security Software
Key Management Service Market
Security Software
Hardware OTP Token Authentication Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Endpoint Detection and Response Market
Security Software
United States Lawful Interception Market
Security Software
Network Camera Market
Security Software
Data Leakage Prevention Product Market
Security Software
Secaas Market
Security Software
Decentralized Identity Software Market
Security Software
Website Monitoring Software Market
Security Software
Global Data Masking Market
Security Software
Global Insider Threat Management ITM Software Market