
 Global Form Automation Software Market | 2026-2036
Global Form Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Form Automation Software Market Analysis
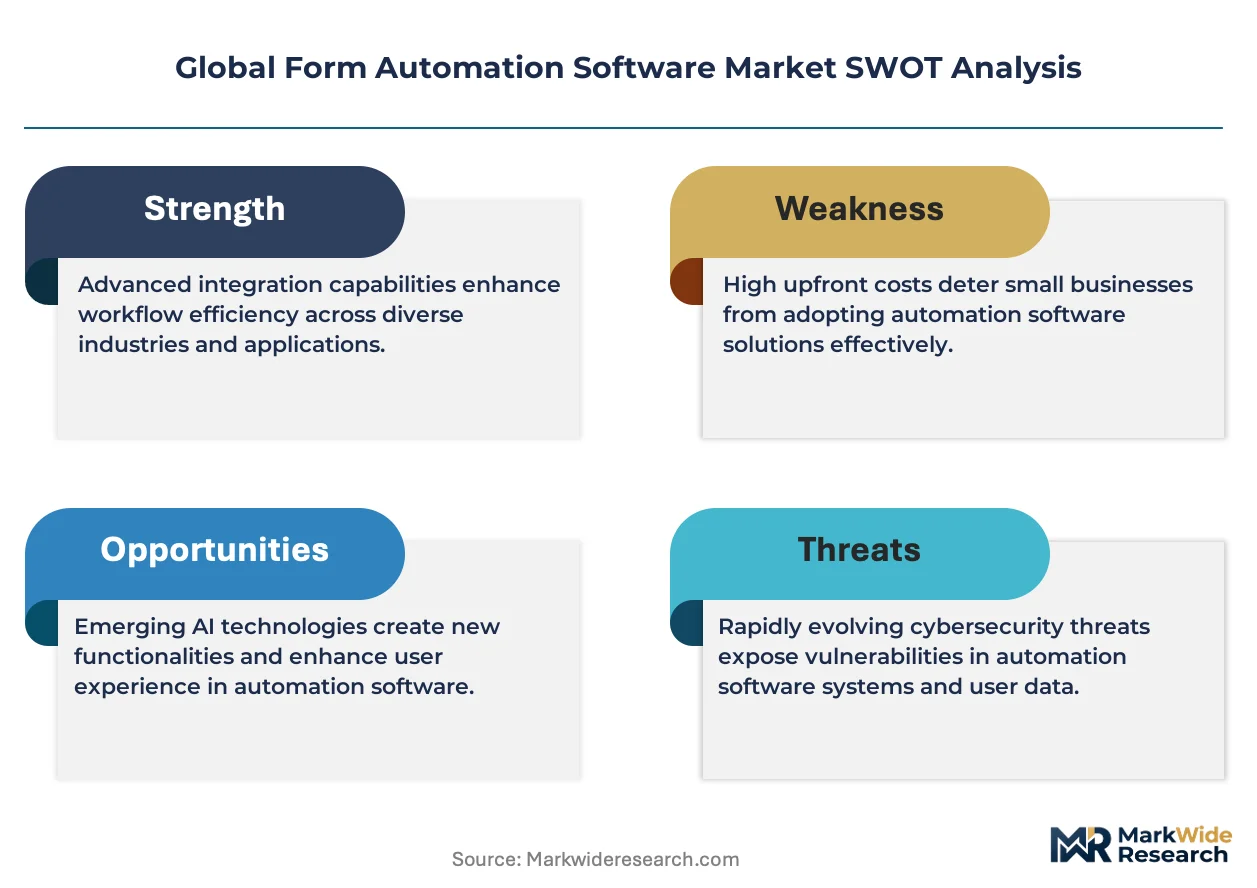
Low-code integration with enterprise CRM and ERP systems is rewriting how form automation platforms embed into core business processes. Microsoft Corporation leverages its Azure cloud infrastructure and Office 365 distribution to sustain dominance in enterprise deployments. Adobe Inc. anchors its position through document-centric workflow specialization that spans creative and enterprise segments. Salesforce.com Inc competes by embedding form automation natively within its customer relationship management stack, reducing friction for sales operations teams.
Form automation software comprises digital platforms that capture, validate, route, and store structured data through configurable interfaces, typically featuring API connectivity, conditional logic engines, and role-based access controls for audit trails. The technology eliminates manual data re-entry, accelerates approval cycles, and enforces compliance across distributed organizations. Cloud-based deployment leads the market as organizations prioritize scalability and remote accessibility over capital-intensive on-premises infrastructure. Workflow optimization functionality commands premium pricing due to its direct impact on operational efficiency metrics. Healthcare and finance verticals drive specialized demand for HIPAA and SOX-compliant form architectures with immutable audit logs.
The U.S. Food and Drug Administration enforces 21 CFR Part 11 requirements for electronic records in pharmaceutical and clinical settings, mandating form systems with digital signatures and tamper-evident controls. The European Medicines Agency and GDPR regulators across EU member states require explicit consent capture, data portability, and breach notification capabilities within form platforms processing personal information. The Securities and Exchange Commission's disclosure rules and Japan's METI data governance guidelines add further compliance layers for multinational deployments. Stakeholders must evaluate whether their form automation vendor maintains current certifications across all jurisdictions where data subjects reside, as regulatory divergence accelerates platform fragmentation.

Market Dynamics
Low-code integration with enterprise CRM and ERP systems is rewriting how form automation platforms embed into core business processes. This structural shift compresses deployment cycles from months to weeks while forcing incumbent vendors to open their architectures or lose integration battles.
Growth Catalysts
- EU AI Act compliance mandates:Organizations across Germany, France, and Italy require auditable automated workflows with explainable decision trails, accelerating replacement of legacy paper-based systems.
- Healthcare digital intake specialization:HIPAA-compliant form architectures with immutable audit logs are becoming standard requirements for hospital networks and clinical research organizations processing patient data.
- India's government digitization:National e-Governance initiatives and the PLI scheme for IT hardware are driving public sector adoption of cloud-based form platforms for citizen service delivery.
Market Restraints
- GDPR cross-border data friction:Divergent member state interpretations of lawful basis for processing create compliance uncertainty for multinational form deployments spanning EU jurisdictions.
- Cloud infrastructure concentration:Heavy reliance on hyperscale providers in the United States creates data sovereignty risks for European and Asian enterprises subject to local residency requirements.
- Legacy system entrenchment:Decades of customized on-premises ERP investments in manufacturing and financial services create technical debt that resists API-based form integration.
Strategic Opportunities
- Brazil's regulatory modernization:ANVISA's electronic submission requirements for pharmaceutical trials create demand for 21 CFR Part 11-aligned form platforms with Portuguese-language localization.
- Convergence of RPA and form automation:Robotic process automation vendors are acquiring form capabilities to offer end-to-end document-to-action workflows, opening partnership channels for pure-play form specialists.
- Saudi Arabia's Vision 2030:MOHAP mandates for healthcare digitization and government service transformation are driving public sector procurement of Arabic-compliant form systems.
Industry Challenges
- API talent scarcity:Enterprise integration projects stall due to shortage of developers proficient in both legacy SOAP architectures and modern REST API frameworks.
- Multi-jurisdiction certification timelines:Vendors face 12-18 month approval cycles to obtain FDA 21 CFR Part 11, EU MDR, and Japan PMDA validations simultaneously for life science deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Form Automation Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Tenant User Type: Small Businesses, Enterprises, Government Agencies, Non-Profits Functionality: Data Entry Automation, Document Management, Workflow Optimization, Reporting Industry Vertical: Finance, Education, Healthcare, Manufacturing |
| Companies Covered | Microsoft Corporation, Adobe Inc., Salesforce.com Inc, Oracle Corporation, IBM Corporation, Zoho Corporation, JotForm, FormStack, Typeform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Form Automation Software Market Emerging Trajectories
Artificial intelligence is embedding into form automation at the validation and routing layers, compressing error rates while raising new governance questions. This technological infusion is redrawing competitive boundaries between pure-play form vendors and adjacent workflow automation platforms.
Intelligent document processing with natural language extraction is virtualizing the data capture layer that once required manual field mapping. Healthcare revenue cycle teams in the United States are deploying these tools to auto-populate patient registration forms from unstructured insurance cards and referral documents. The technology is virtualizing traditional template-based form design, enabling dynamic field generation that adapts to document type without pre-configuration.
The EU AI Act's risk classification framework is forcing form vendors to implement human-in-the-loop controls for automated decision workflows. Systems processing loan applications or insurance claims in France and Germany now require explicit override capabilities and decision explanation logs. Financial services deployments across the Eurozone are restructuring their form logic to isolate high-risk AI components from standard data collection modules.
Subscription-based pricing with usage tiers is displacing perpetual license models across mid-market buyer segments. Manufacturing and professional services firms in India and Southeast Asia prefer per-form-submission pricing that aligns costs with actual transaction volumes. This consumption pattern shift favors cloud-native vendors with elastic infrastructure over on-premises legacy providers locked into seat-based licensing.
Global Form Automation Software Market Segmentation
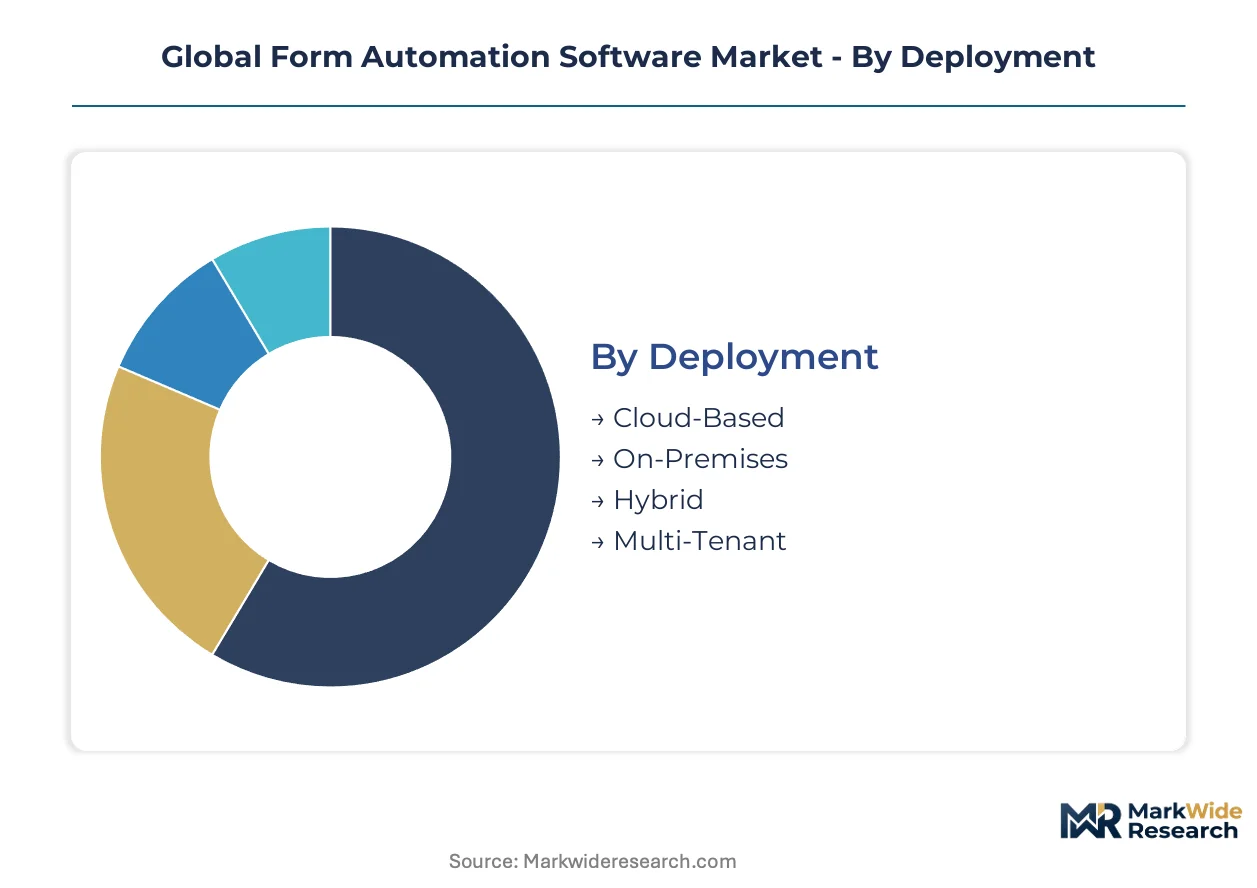
Segmentation in form automation software reveals divergent technology requirements across deployment architectures, organizational scale, functional depth, and regulatory exposure. Understanding these fault lines enables vendors to calibrate pricing, compliance certification, and integration strategies to specific buyer profiles rather than pursuing undifferentiated market coverage.
Deployment:
Cloud-based deployments turn over fastest as organizations cycle through trial subscriptions and platform migrations, while on-premises installations exhibit decade-long replacement cycles locked to ERP refresh timelines.
- Cloud-Based:Scalable SaaS architectures with elastic compute and automatic patching dominate new procurement. Healthcare networks in the United States prioritize HIPAA-compliant cloud instances with Business Associate Agreements from hyperscale providers.
- On-Premises:Dedicated infrastructure with full data sovereignty remains entrenched in German manufacturing and Japanese financial services where GDPR and METI guidelines mandate local residency. Capital intensity and 3-5 year depreciation cycles slow adoption.
- Hybrid:Split architectures route sensitive data to private infrastructure while pushing generic workflows to public cloud. Indian public sector banks under RBI guidelines deploy hybrid models for citizen-facing forms.
- Multi-Tenant:Shared infrastructure with logical isolation enables cost-efficient scaling for mid-market professional services firms. French software vendors leverage multi-tenancy to serve distributed EU clients under single GDPR compliance frameworks.
On-premises dominates installed base. Cloud-based is where expansion concentrates.
User Type:
Cost tier segmentation separates seat-based enterprise contracts from transaction-priced small business tiers, with government procurement operating under distinct public tender frameworks.
- Enterprises:Complex deployments requiring API integration with SAP, Oracle, and Salesforce ecosystems. German automotive suppliers mandate ISO 27001-certified platforms with dedicated customer success managers.
- Small Businesses:Self-service onboarding with template libraries and per-form pricing. Indian MSMEs under PLI scheme incentives adopt lightweight solutions for vendor onboarding and tax documentation.
- Government Agencies:Sovereign cloud requirements and accessibility standards (WCAG 2.1) dominate selection criteria. Saudi Arabia's Vision 2030 digitization mandates drive Arabic-compliant procurement.
- Non-Profits:Donation-optimized pricing with grant reporting functionality. U.S. 501(c)(3) organizations prioritize platforms with pre-built IRS Form 990 templates.
Enterprises command revenue concentration. Small businesses are gaining share fastest through product-led growth channels.
Functionality:
Application depth determines implementation complexity, with workflow optimization requiring process engineering engagement while data entry automation deploys through citizen-developer interfaces.
- Workflow Optimization:Conditional routing, approval hierarchies, and SLA tracking compress cycle times. Financial services firms in the United States deploy these capabilities to meet SEC disclosure deadlines.
- Data Entry Automation:Field validation, auto-fill, and mobile capture reduce manual input. Clinical research organizations use these tools to populate FDA 21 CFR Part 11-compliant case report forms.
- Document Management:Version control, e-signature integration, and retention policies. German legal services firms require qualified electronic signatures under eIDAS regulation.
- Reporting:Dashboard visualization and audit trail export. Indian healthcare providers generate CDSCO-mandated pharmacovigilance reports from form submission data.
Data entry automation dominates transaction volume. Workflow optimization commands the steepest expansion trajectory as process mining adoption accelerates.
Industry Vertical:
Regulatory maturity separates verticals, with finance and healthcare subject to stringent audit requirements while education and manufacturing operate under lighter compliance burdens.
- Healthcare:HIPAA-compliant architectures with immutable audit logs and patient consent management. U.S. hospital networks prioritize FDA 21 CFR Part 11 validation for clinical trial forms.
- Finance:SOX-compliant workflows with segregation of duties and tamper-evident controls. EU banks under ECB supervision implement GDPR Article 30 record-keeping through automated form trails.
- Manufacturing:Shop-floor integration with MES systems and supplier quality documentation. German Industrie 4.0 initiatives drive form automation for corrective action requests.
- Education:Student information system integration and FERPA-compliant data handling. Indian universities under UGC guidelines digitize admission and examination forms.
Healthcare anchors premium pricing. Finance is climbing the fastest as ESG disclosure requirements expand form volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud-native form automation platforms to European enterprises navigating GDPR and EU AI Act compliance mandates. German manufacturers and French financial institutions represent the largest buyer geographies outside North America.
United States
Hospital networks and clinical research organizations drive specialized demand for FDA 21 CFR Part 11-compliant form architectures. The Securities and Exchange Commission's disclosure rules accelerate workflow automation adoption among asset managers and broker-dealers. Boston's biotech corridor and San Francisco's enterprise software cluster host the densest concentration of form automation deployments.
Germany
Automotive suppliers and Industrie 4.0 manufacturing operations mandate ISO 27001-certified platforms with dedicated data residency. The EU AI Act's risk classification framework forces explicit human-in-the-loop controls for automated decision workflows. Munich and Stuttgart industrial clusters lead procurement of shop-floor-integrated form systems for supplier quality documentation.
India
National e-Governance initiatives and PLI scheme incentives for IT hardware drive public sector digitization of citizen service delivery. RBI guidelines for public sector banks mandate hybrid deployment models with sensitive data retained on private infrastructure. Bengaluru's SaaS ecosystem and Mumbai's financial services corridor anchor enterprise adoption.
France
ANSM and CNIL regulators enforce explicit consent capture and data portability requirements for healthcare and insurance form platforms. GDPR Article 30 record-keeping obligations push ECB-supervised banks toward automated audit trail generation. Paris-based insurance groups and Lyon healthcare networks represent concentrated procurement.
Saudi Arabia
MOHAP mandates for healthcare digitization and Vision 2030 government service transformation drive public sector procurement of Arabic-compliant systems. Data localization requirements under national cloud-first policies restrict foreign vendor participation without local partnership structures. Riyadh and Jeddah concentrate implementation of citizen-facing digital intake systems.
Global Form Automation Software Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around cloud-native platforms with deep CRM and ERP integration. Microsoft Corporation leverages Azure infrastructure and Office 365 distribution to sustain enterprise dominance. Adobe Inc. anchors position through document-centric workflow specialization. Salesforce.com Inc embeds form automation natively within customer relationship management stacks. Strategic moves concentrate on API ecosystem expansion and vertical-specific compliance certification.
Within the cloud-platform tier, Microsoft Corporation and Salesforce.com Inc exemplify channel-control strategies through existing enterprise relationships and infrastructure lock-in. Adobe Inc. represents the document-centric specialist archetype with creative-to-enterprise workflow continuity. Zoho Corporation and Oracle Corporation occupy positions bridging mid-market accessibility with enterprise-grade compliance capabilities.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Adobe Inc. |
| Salesforce.com Inc |
| Oracle Corporation |
| IBM Corporation |
| Zoho Corporation |
| JotForm |
| FormStack |
| Typeform |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud infrastructure concentration in the United States anchors cost structures for SaaS-native form automation vendors, compressing margin pools for European and Asian providers forced into local data residency compliance. This upstream compute dependency translates into pricing power asymmetries where Azure and AWS-backed platforms undercut sovereign-cloud competitors on unit economics.
Pricing Analysis
Next-generation AI-augmented validation engines command 40-60% subscription premiums over legacy template-based systems, while prior-generation on-premises perpetual licenses face accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth—FDA 21 CFR Part 11-validated tiers extract maximum value from pharmaceutical buyers, while self-serve economy tiers target Indian MSMEs with per-form transactional models. Cost compression in the mid-market tier intensifies because pure-play vendors compete against bundled CRM-embedded alternatives. Small businesses exhibit highest price sensitivity, whereas German automotive suppliers demonstrate lowest sensitivity when ISO 27001 certification and dedicated customer success management attach.
Supply Chain Analysis
Extended payment terms from enterprise buyers in the United States and Germany now stretch to 90-120 days, forcing mid-tier vendors into supply-chain finance facilities to bridge working capital gaps. Cloud infrastructure provisioning concentrates in the United States, Ireland, and Singapore, with compute and storage capacity anchoring delivery economics. Software development labor pools in India, Poland, and Vietnam feed engineering talent into platform development pipelines. Single-source vulnerability runs through hyperscale API dependencies—outages at major cloud providers cascade into form automation service interruptions. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and self-serve product-led growth channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework is disrupting competitive positioning, forcing every vendor to re-architect automated decision workflows with human-in-the-loop controls or forfeit regulated industry revenue.
For Market Incumbents: Harden API ecosystem moats by embedding form automation deeper into SAP and Oracle ERP workflows, neutralizing the threat from standalone low-code platforms. Prioritize vertical integration into healthcare compliance certification pipelines, compressing FDA 21 CFR Part 11 validation timelines below competitor benchmarks. Channel control through existing Office 365 and Salesforce distribution relationships remains the critical defensive lever. For New Entrants and Emerging Players: Mid-market professional services firms in Southeast Asia represent the most penetrable entry point, with limited incumbent presence and price-sensitive demand for per-form transactional models. Arabic-compliant government digitization projects under Saudi Vision 2030 offer white-space procurement channels insulated from Western vendor dominance. A partnership-first go-to-market angle with local systems integrators accelerates trust-building in data-sovereignty-conscious jurisdictions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed form automation specialists carrying 2018-2021 vintage valuations and urgent liquidity timelines. Long-term viability hinges on cloud-native architecture and vertical-specific compliance depth rather than horizontal feature breadth. Watch FDA validation backlog clearance rates as an inflection indicator—accelerated approvals signal expanding pharmaceutical addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Compliance Certification | FDA 21 CFR Part 11 validation unlocks pharmaceutical procurement budgets and creates switching costs. |
| Hyperscaler Partnership | Azure and AWS marketplace listings compress enterprise sales cycles through procurement pre-approval. |
| Intelligent Document Processing Acquisition | Natural language extraction capabilities virtualize manual field mapping and expand addressable use cases. |
| Geographic Localization | Arabic and Portuguese language support opens Saudi and Brazilian public sector tender participation. |
| API Ecosystem Expansion | Native Salesforce and SAP connectors reduce integration friction and defend against bundled competitors. |
Methodological Framework
A spread of perspectives from enterprise IT procurement officers, healthcare compliance directors, platform integration specialists, and SaaS vendor executives converged on the working assumptions driving this analysis. Primary interviews with CTOs at German automotive suppliers, hospital network CIOs in the United States, and Indian public sector bank technology heads combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory impact assessments. Bottom-up sizing of vendor-reported subscription metrics and top-down triangulation against cloud infrastructure spending patterns anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with deployment model, organization scale, vertical industry, and regional regulatory cluster serving as core segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to historical SaaS adoption patterns and forward-looking compliance mandate timelines. Integration complexity tiers and API ecosystem maturity indices fed scenario-weighted projections.
Practitioners should monitor FDA guidance document releases, EU AI Act implementing act clarifications, and hyperscaler data residency expansion announcements for early signals of forecast revision triggers. Macroeconomic deviation in enterprise software spending, regulatory enforcement intensity variation across member states, or generative AI capability disruption would prompt forecast reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Digital Process Automation Market
Automation
Workload Scheduling and Automation Market
Automation
APAC Water Automation and Instrumentation Market
Automation
Network Automation Market
Automation
Automation-As-A-Service Market
Automation
Service Delivery Automation (SDA) Market
Automation
Automation Lifecycle Services Market
Automation
Global Remote Monitoring and Control Market
Automation
Distributed Control System Market
Automation
Global Smart Vending Machines Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
Global Warehouse Barcode System Market
Automation
Global Water Automation and Instrumentation Market
Automation
Workflow Automation Market
Automation
Data Center Automation Market
Automation
Self Bag Drop Machine Market