
 Global Water Automation and Instrumentation Market | 2026-2036
Global Water Automation and Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Automation and Instrumentation Market Intelligence
The push for greater water security, as outlined in OECD principles on water governance, is rebalancing demand toward integrated, real-time monitoring systems. This shift favors vendors with deep expertise in both industrial automation and digital software. Siemens AG leverages its extensive portfolio in SCADA and PLC systems to serve large municipal utilities. Schneider Electric SE differentiates through its EcoStruxure platform, which integrates energy and water management for industrial clients.
Water automation and instrumentation encompasses the network of sensors, controllers, and software used to monitor and manage water and wastewater infrastructure. These systems utilize components like ultrasonic flow meters, which measure flow rates without process intrusion, to provide critical operational data for enhancing efficiency and minimizing water loss. While SCADA systems and PLCs form the foundational product segments, advanced analyzers for real-time quality monitoring are expanding rapidly. Wastewater treatment commands the largest application share, but irrigation management shows significant growth potential.
Regulatory frameworks create non-negotiable demand for precise monitoring. Directives from the US Environmental Protection Agency (EPA) and the EU's Water Framework Directive set strict standards for utilities. Concurrently, standards from China's Ministry of Ecology and Environment (MEE) on industrial discharge compel investment by manufacturers. The central decision for asset owners is phasing investments in new AI-based monitoring to gain intelligence without disrupting service.
Market Dynamics
The central structural force shaping the water automation market is the non-negotiable regulatory mandate for enhanced water security and efficiency, which compels utilities to overlay digital monitoring systems onto aging physical infrastructure, creating a persistent tension between capital investment and operational continuity.
Growth Catalysts
- EU Green Deal Implementation:This European policy framework mandates significant improvements in water use efficiency and pollution reduction, directly stimulating investment in advanced automation and real-time monitoring systems across municipal and industrial water cycles.
- Infrastructure Modernization in India:Large-scale national projects, such as the Jal Jeevan Mission, are creating sustained, large-volume demand for foundational automation components like flow meters, PLCs, and SCADA systems to upgrade the country's water distribution networks.
- Wastewater Treatment Demands:The rapid expansion of advanced analyzers for real-time quality monitoring is driven by the wastewater sector's need for continuous data on effluent quality to meet stringent environmental discharge standards.
Market Restraints
- High Initial Capital Outlay:The substantial upfront cost required to deploy comprehensive SCADA systems and sensor networks across geographically dispersed water and wastewater infrastructure acts as a primary deterrent for budget-constrained municipal utilities.
- Legacy System Interoperability:Significant technical hurdles exist in integrating modern digital instrumentation with decades-old analog equipment, leading to complex, costly, and often delayed modernization projects that risk service disruption.
- Component Supply Chain Concentration:The reliance on a limited number of suppliers, primarily in East Asia, for critical electronic components like high-precision microprocessors and sensors, introduces significant price volatility and supply chain risk for instrumentation manufacturers.
Strategic Opportunities
- Precision Irrigation Systems:Developing and deploying cost-effective, scalable automation solutions tailored for irrigation management addresses a largely underpenetrated segment with significant growth potential, driven by global food security and water scarcity concerns.
- AI-Driven Predictive Maintenance:Integrating artificial intelligence and machine learning algorithms with existing SCADA and PLC data streams enables the creation of high-value services for predictive leak detection and asset failure analysis.
- Industrial Discharge Monitoring:Stricter standards from bodies like China's Ministry of Ecology and Environment (MEE) create a captive market for specialized instrumentation vendors that can provide robust monitoring solutions for industrial wastewater treatment facilities.
Industry Challenges
- Technical Skills Gap:A persistent shortage of engineers and technicians possessing dual expertise in both traditional water process engineering and modern OT/IT integration complicates the deployment, maintenance, and optimization of advanced automation systems.
- Risk of Service Disruption:The critical nature of water and wastewater services means that phasing in new monitoring technologies must be done without interrupting operations, a complex logistical challenge that elevates project risk and cost.
- Lack of Data Standardization:The absence of universally accepted communication protocols for IoT devices and sensors in the water sector inhibits the development of truly interoperable, city-scale smart water grids and vendor-agnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Automation and Instrumentation Market |
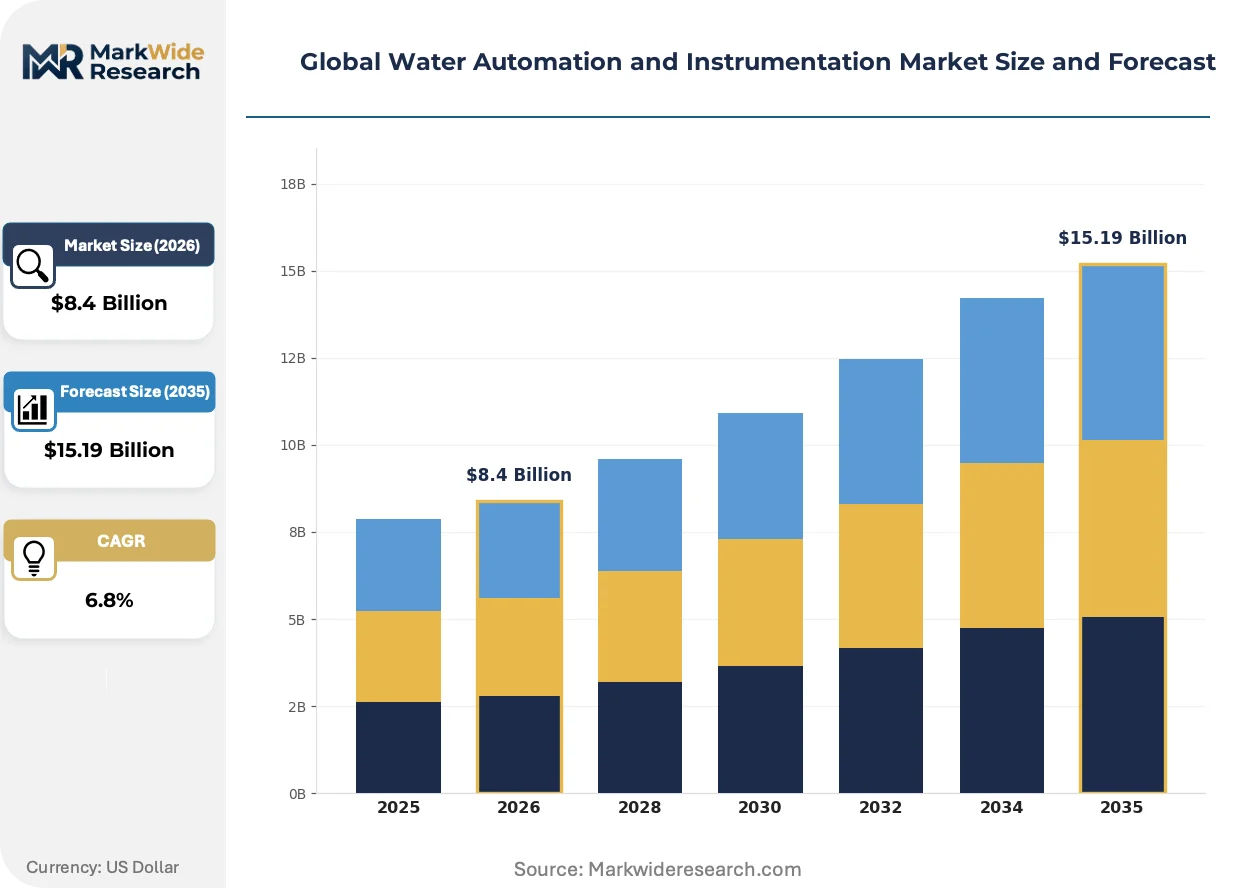
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Meters, Pressure Sensors, Level Transmitters, PLCs, SCADA Systems, Analyzers Technology: Wireless Communication, IoT Integration, AI-Based Monitoring, Cloud Computing, Edge Computing, Data Analytics Application: Wastewater Treatment, Drinking Water Supply, Irrigation Management, Industrial Process Control, Desalination, Stormwater Monitoring End User: Water Utilities, Agricultural Operators, Manufacturing Plants, Municipal Corporations, Research Laboratories, Environmental Agencies |
| Companies Covered | ABB Group, Siemens AG, Schneider Electric SE, Emerson Electric, Rockwell Automation Inc., Yokogawa Electric Corporation, Endress+Hauser, General Electric, Mitsubishi Electric Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Automation and Instrumentation Market Strategic Shifts & Innovations
The convergence of digital software with physical hardware is fundamentally redefining system capabilities in water management. This evolution is shifting the market's focus from isolated process control toward predictive, network-wide intelligence that optimizes entire water and wastewater systems.
Non-intrusive sensors, such as clamp-on ultrasonic flow meters, provide a method to measure flow rates without cutting pipes or halting processes. Municipal utilities are adopting these devices at an accelerated pace during system upgrades and for spot-checking in older networks. This clamp-on measurement technology is overtaking traditional intrusive methods like magmeters in retrofit projects due to superior installation speed and lower lifecycle costs.
New directives from regulatory bodies like the US Environmental Protection Agency (EPA) establish stricter standards for contaminant levels and require more frequent reporting on water quality. This compliance burden forces utilities to invest in automated, real-time monitoring instrumentation to generate auditable data logs. The wastewater treatment segment is most impacted, spurring adoption of advanced analyzers that can continuously track effluent parameters.
A notable behavioral shift sees asset owners moving from one-time capital equipment purchases toward subscription-based service models for advanced monitoring. This approach lowers the initial financial barrier for utilities and transfers the risk of technology obsolescence to the vendor. The trend is most pronounced in North American and European municipal markets, where predictable operational expenditures are favored over large, infrequent capital outlays.
Global Water Automation and Instrumentation Market Segmentation
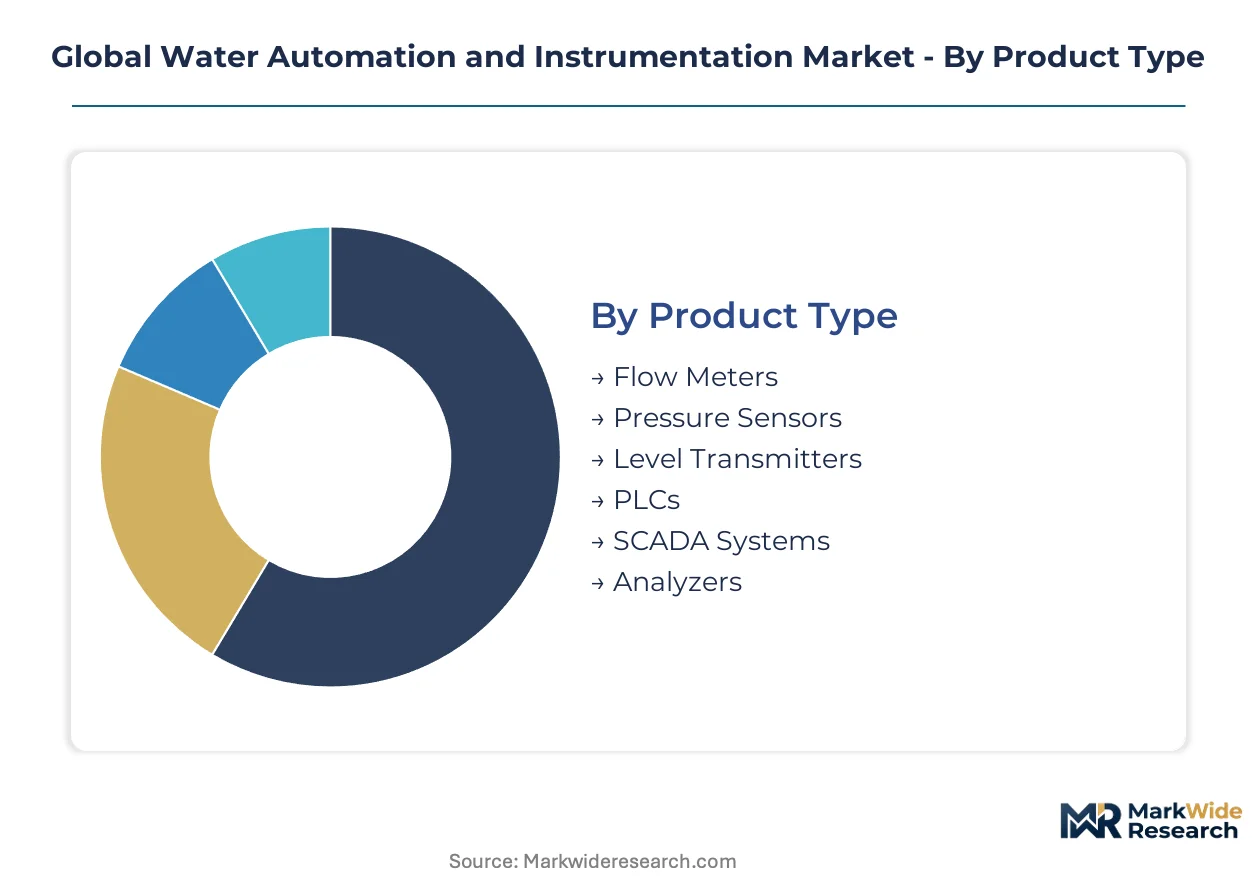
The segmentation of the global water automation and instrumentation market provides a granular view of how diverse technological solutions and product types address specific operational challenges across various end-use applications. This detailed breakdown is crucial for understanding investment priorities and the strategic positioning of vendors within this expanding sector.
Product Type:
The product type segmentation highlights how utilities prioritize investments in new monitoring capabilities during infrastructure upgrade cycles and for replacing aging equipment.
- SCADA Systems:These supervisory control and data acquisition systems provide centralized monitoring and control over entire water networks, integrating data from various sensors and devices. Demand is concentrating in municipal utilities globally, driven by the need for integrated operational visibility and regulatory compliance.
- Analyzers:Advanced analytical instruments perform real-time assessment of water quality parameters, including pH, turbidity, and chemical composition, crucial for ensuring water safety and environmental protection. The wastewater treatment sector shows significant demand, compelled by stringent discharge standards from bodies like the US EPA and China's MEE.
- Flow Meters:Devices like clamp-on ultrasonic flow meters accurately measure water movement without process intrusion, supporting efficiency and leak detection efforts.
- PLCs:Programmable Logic Controllers automate specific processes within water and wastewater treatment plants, enhancing operational efficiency and reliability.
- Pressure Sensors:These instruments monitor water pressure across distribution networks, providing critical data for leak detection and system optimization.
- Level Transmitters:Used to measure and control water levels in tanks, reservoirs, and treatment basins for effective resource management.
Volume placements concentrate in PLCs; the faster expansion belongs to Analyzers.
Technology:
The technology segmentation reflects the varying levels of digital maturity and adoption rates across different water management operations.
- AI-Based Monitoring:These systems leverage artificial intelligence and machine learning algorithms to predict asset failures, optimize processes, and detect anomalies within water infrastructure. Demand is concentrating in developed municipal markets such as Germany and the US, seeking predictive maintenance capabilities and enhanced operational intelligence.
- IoT Integration:Internet of Things integration connects diverse sensors and devices, enabling real-time data collection and remote management of water assets across vast geographical areas. Global water utilities are increasingly adopting IoT solutions for network-wide visibility and efficiency gains.
- Wireless Communication:Enables data transmission from remote sensors and devices without physical cabling, facilitating deployment in challenging or dispersed locations.
- Cloud Computing:Offers scalable data storage and processing power for water management analytics and applications, supporting large-scale data analysis.
- Data Analytics:Transforms raw operational data into actionable insights for decision-making in water utilities, improving resource allocation and problem-solving.
- Edge Computing:Processes data closer to the source, reducing latency for critical real-time water control applications and enhancing system responsiveness.
The integration of IoT Integration technologies with existing SCADA hardware is driving significant efficiency gains across water networks.
Application:
The application segmentation illustrates where the largest volumes of water automation equipment are deployed, reflecting critical operational needs.
- Wastewater Treatment:This application segment involves monitoring and controlling processes to treat industrial and municipal wastewater before discharge or reuse, ensuring environmental compliance. Stringent environmental regulations from bodies like the EU's Water Framework Directive and US EPA drive investment in advanced instrumentation for effluent quality.
- Drinking Water Supply:Encompasses the automation of water intake, purification, storage, and distribution to ensure safe and reliable potable water for communities. Modernization projects in countries like India are creating sustained demand for foundational automation components in this sector.
- Irrigation Management:Optimizes water usage in agriculture through automated control of pumps, valves, and soil moisture sensors, crucial for sustainable farming.
- Industrial Process Control:Applies automation to manage water usage within manufacturing facilities, driven by efficiency, waste reduction, and discharge regulations.
- Stormwater Monitoring:Involves sensors and systems to manage and mitigate urban runoff and flood risks, protecting infrastructure and public safety.
- Desalination:Utilizes automation for efficient operation of desalination plants, particularly in water-scarce regions like Saudi Arabia, ensuring consistent water production.
While Wastewater Treatment remains the dominant segment, Irrigation Management is expanding most quickly due to global food security and water scarcity concerns.
End User:
The end user segmentation delineates the distinct operational priorities and purchasing behaviors of various customer types within the water sector.
- Water Utilities:This segment includes public and private entities responsible for managing municipal water and wastewater services for residential and commercial users. Their demand is driven by large-scale infrastructure projects, regulatory compliance, and the need for system-wide efficiency across extensive networks.
- Manufacturing Plants:Industrial facilities utilize water automation for process control, water treatment, and effluent monitoring to meet production requirements and environmental discharge limits. China's Ministry of Ecology and Environment (MEE) directives compel significant investment in this end-user group.
- Agricultural Operators:These users adopt automation for precision irrigation, optimizing water consumption for crop production and reducing operational costs.
- Municipal Corporations:Government bodies often oversee water infrastructure development and regulatory enforcement, influencing technology adoption.
- Environmental Agencies:Utilize instrumentation for monitoring water quality and compliance enforcement across various water bodies, ensuring ecological health.
- Research Laboratories:Employ specialized instrumentation for water quality analysis and technological development, driving innovation in the sector.
The procurement patterns of Water Utilities are increasingly influencing innovation in AI-driven monitoring solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Delhi's focus on water infrastructure modernization anchors significant demand for automation and instrumentation in South Asia. This national push for water security drives investment across municipal utilities. Demand extends to foundational components and advanced monitoring.
India
India's large-scale water infrastructure modernization, including the Jal Jeevan Mission, creates sustained demand for foundational automation components. This national program compels investment in flow meters and PLCs for rural households. Water utilities in New Delhi are rapidly deploying SCADA systems for integrated operational visibility.
Germany
Germany's water sector experiences demand for advanced automation, driven by the EU Green Deal's mandates for water efficiency and pollution reduction. These European policies stimulate investment in real-time monitoring systems. Municipal utilities in Berlin are adopting AI-based monitoring for predictive maintenance capabilities.
United States
Strict directives from the US Environmental Protection Agency (EPA) compel investment in precise water quality monitoring and reporting. These regulations establish stricter contaminant standards, driving adoption of automated instrumentation. Water treatment plants in California are upgrading to advanced analyzers for continuous effluent parameter tracking.
China
China's Ministry of Ecology and Environment (MEE) standards on industrial discharge compel significant investment by manufacturers in water automation. These stringent regulations create a captive market for specialized instrumentation vendors. Manufacturing plants in the Yangtze River Delta invest in robust monitoring solutions.
Saudi Arabia
Saudi Arabia, facing acute water scarcity, drives demand for automation in desalination plants to ensure consistent water production. National water security initiatives prioritize efficient operation of these critical facilities. Desalination plants in Jubail utilize advanced automation systems for process control.
Global Water Automation and Instrumentation Market Key Industry Players
The competitive structure tilts toward integrated solution providers, with a tiered landscape encompassing established industrial automation giants and specialized instrumentation firms. This market exhibits a blend of consolidation among core technology providers and fragmentation within niche application segments. Diversified technology companies represent one strategic archetype, while focused sensor manufacturers form another. Geographic expansion and strategic partnerships are dominant competitive moves, aiming to capture demand in modernizing infrastructure.
Within the integrated solution provider tier, Siemens AG, a German-based AG company, represents expertise in industrial automation and digital software platforms. Schneider Electric SE, a European-headquartered SE, exemplifies a focus on energy and water management integration for industrial clients. Emerson Electric, an Inc. company from the United States, also occupies a position among these diversified technology providers. These entities anchor comprehensive offerings spanning SCADA systems, PLCs, and advanced monitoring solutions, catering to both municipal and industrial clients. Their global presence and broad product portfolios enable them to serve large utilities and industrial sectors effectively worldwide.
| Leading Market Players |
|---|
| ABB Group |
| Siemens AG |
| Schneider Electric SE |
| Emerson Electric |
| Rockwell Automation Inc. |
| Yokogawa Electric Corporation |
| Endress+Hauser |
| General Electric |
| Mitsubishi Electric Corp |
| Others |
Cost & Logistics Intelligence
Non-intrusive sensor technology, enabling measurements without process interruption, simultaneously reshapes cost economics by reducing installation time and concentrates supply chain reliance on specialized component manufacturers. This shift emphasizes efficiency gains while highlighting vulnerabilities in global component sourcing.
Pricing Analysis
Value-based pricing, tied to outcomes like reduced water loss and predictive maintenance, anchors this market. Pricing stratifies across performance tiers, with advanced AI-driven solutions commanding a premium due to their intelligence capabilities and customization level for specific utility needs. Pricing pressure stems from the high initial capital outlay required for comprehensive SCADA systems, particularly for budget-constrained municipal utilities in emerging markets. Water utilities in developed regions, seeking advanced analytics, demonstrate lower price sensitivity compared to those focused on foundational component upgrades.
Supply Chain Analysis
Critical electronic components, including high-precision microprocessors and sensors, largely source from East Asia, creating a concentrated supply base. This reliance on a limited number of suppliers introduces significant price volatility and supply chain risk for instrumentation manufacturers. Single-source vulnerability for specialized components represents a structural risk for the broader market. Distribution runs through a blend of integrated solution providers and specialized instrumentation firms, catering to diverse client needs from large municipal utilities to niche industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a technology-transition phase, where AI-based monitoring is rapidly displacing traditional process control to optimize water management systems.
For Market Incumbents:Deepen integrated offerings by embedding AI and machine learning algorithms into existing SCADA and PLC systems. This protects against emerging specialized tech threats and leverages an established client base. Strategic partnerships with digital software firms can bridge the technical skills gap, enhancing predictive maintenance capabilities. Incumbents should invest in expanding their service models, shifting towards subscription-based operational expenditure solutions to mitigate initial capital outlay concerns for utilities.
For New Entrants and Emerging Players:Agricultural operators in regions facing water scarcity represent an underserved buyer archetype for automation. Develop cost-effective, scalable precision irrigation systems tailored for small to medium-sized farms. A focused go-to-market angle involves leveraging regional governmental incentives for water-efficient agriculture. Another white-space target includes specialized real-time industrial discharge monitoring solutions for manufacturers in regions with stringent environmental regulations, such as China's Ministry of Ecology and Environment.
For Investors and Strategic Acquirers:Exit pathways concentrate in strategic acquisitions by diversified technology companies seeking to expand their environmental and industrial automation portfolios. The long-term viability of this market, spanning the next decade, is underpinned by non-negotiable regulatory mandates and global infrastructure modernization. Target specialized instrumentation firms with proven AI and IoT integration capabilities. A small set of named triggers warrants ongoing watch, particularly the accelerated adoption of subscription-based monitoring services by municipal utilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Driven Predictive Maintenance | Enables utilities to anticipate failures, reducing operational disruptions and costs across water networks. |
| Form Strategic IoT Integration Partnerships | Expands capabilities for real-time data collection and remote management of dispersed water assets. |
| Acquire Niche Sensor Technology Firms | Enhances product portfolios with advanced, non-intrusive measurement devices for critical applications. |
| Target Infrastructure Modernization in India | Captures large-volume demand for foundational automation components within a rapidly expanding market. |
| Shift to Subscription-Based Service Models | Lowers financial barriers for utilities, transferring technology obsolescence risk to vendors and ensuring predictable revenue. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with water utility managers, plant engineers, environmental agency officials, and industrial procurement leads. This approach facilitated a robust understanding of market dynamics, integrating insights from both industry experts and official documentation. Bottom-up and top-down triangulation methods were applied to validate market sizing and segment forecasts.
Data-stream reconciliation formed the core of the analytical framework, modeling market behavior across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory compliance levels. Compound annual growth rates were derived through a combination of historical data extrapolation and expert consensus, incorporating industry-specific forecast inputs such as infrastructure spending commitments and regulatory enforcement timelines.
Revisions become necessary when unforeseen changes in environmental regulations or global supply chain disruptions for critical components materialize. Forecasts reflect assumptions regarding technological adoption rates and investment priorities. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Industrial Vending Machines Market
Automation
North America Marketing Automation Software Market
Automation
RFID Kanban Systems Market
Automation
CNC Controller Market
Automation
Asia Pacific Marketing Automation Software Market
Automation
United States Laboratory Automation Market
Automation
Europe Laboratory Automation Market
Automation
Home Automation Market
Automation
Automation-As-A-Service Market
Automation
Asia-Pacific Automated Liquid Handling Market
Automation
Indonesia Automation and Control System Market
Automation
Cognitive Process Automation Market
Automation
Hyperautomation Market
Automation
Digital Process Automation Market
Automation
Global Field Force Automation Market
Automation
Database Automation Market