
 Global Smart Air Conditioning Market | 2026-2036
Global Smart Air Conditioning Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Air Conditioning Market Outlook
Equipment-as-a-service and third-party leasing models is tilting capital requirements away from building owners toward OEM balance sheets. Daikin Industries leverages captive financing arms to lock in multi-year service contracts. Gree Electric Appliances anchors its position through backward integration into compressor manufacturing. Samsung Electronics differentiates via ecosystem integration with its broader smart-home platform.
Smart air conditioning denotes climate-control systems embedding bidirectional connectivity, environmental sensing, and algorithmic load modulation to optimize thermal output against occupancy patterns and grid pricing signals. Units typically integrate refrigerant-cycle inverters, particulate sensors, and cloud-connected control boards enabling remote diagnostics and demand-response participation. Split systems dominate installed base value due to retrofit compatibility across Asia-Pacific apartment stock, while smart thermostats represent the fastest-expanding margin pool as software recurring revenue attaches to hardware sales. Sensor-based zoning technology is displacing conventional central-system controls in commercial retrofits where granular occupancy data justifies capital outlay.
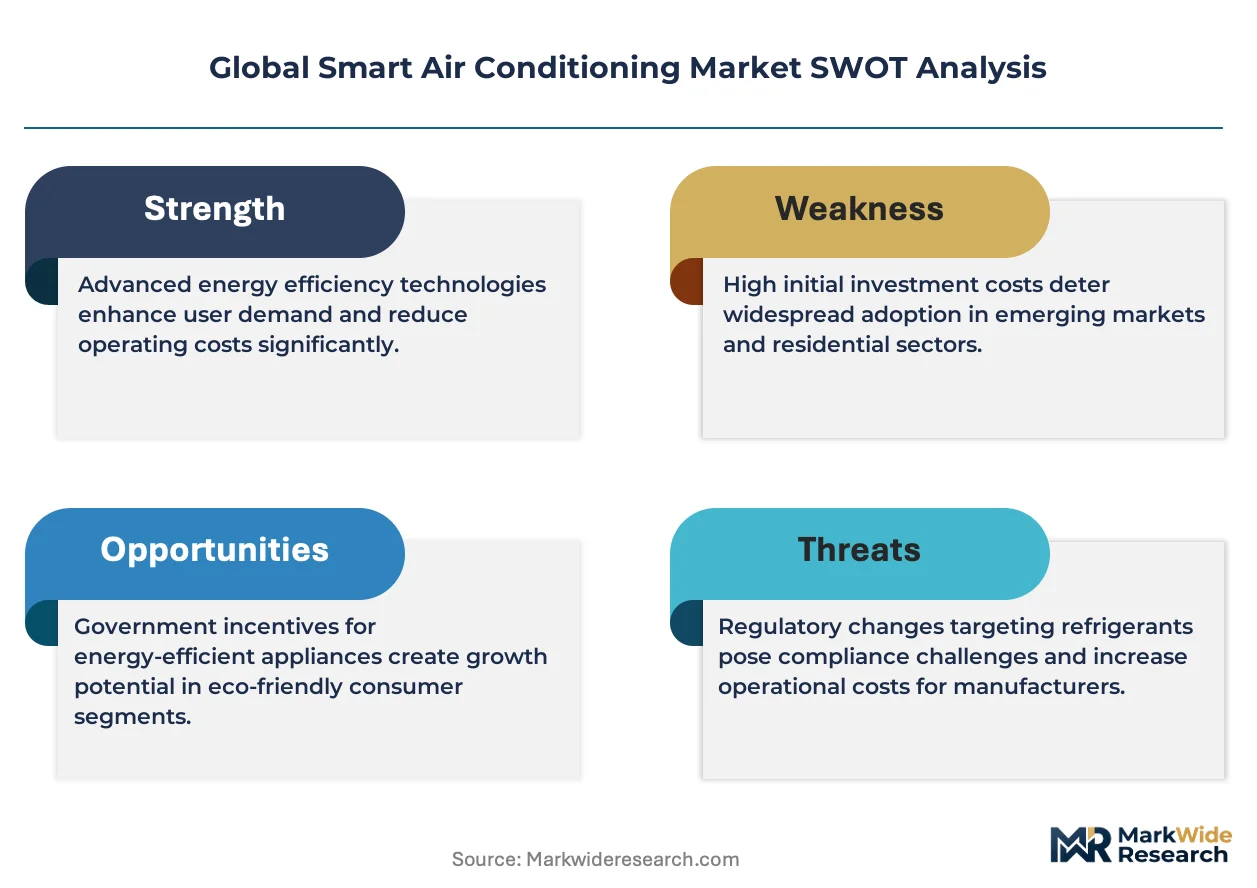
EPA refrigerant phasedown mandates under the AIM Act reshape product roadmaps for North American suppliers, while ECHA REACH restrictions on hydrofluorocarbon feedstocks constrain European formulation choices. China's GB standards on appliance connectivity interoperability, enforced by SAMR, create compliance gates for foreign OEMs seeking residential tenders. Stakeholders must decide whether to absorb certification costs for multi-standard compatibility or accept geographic portfolio segmentation.
Market Dynamics
Equipment-as-a-service financing is redistributing capital risk from building operators to OEM balance sheets, while refrigerant-phaseout mandates force simultaneous R&D and compliance spending across all major production zones.
Growth Catalysts
- Hospitality Retrofit Cycles:Hotels across Spain, Italy, and Thailand are replacing legacy chillers with connected split systems to meet energy-efficiency benchmarks and avoid carbon penalties.
- EPA AIM Act Phasedown:The US refrigerant phasedown timeline accelerates manufacturer transitions to low-GWP alternatives, creating replacement demand for installed base obsolescence.
- Demand-Response Grid Integration:Utility programs in California, Texas, and South Australia compensate smart AC units for load curtailment, monetizing idle thermal capacity.
Market Restraints
- Copper and Rare-Earth Input Volatility:Compressor motor laminations and refrigerant piping face price swings from Chilean copper concentrate and Chinese rare-earth processing concentration.
- EU F-Gas Compliance Friction:The regulation's quota system restricts hydrofluorocarbon supply for servicing legacy European installations, raising maintenance costs.
- Technical Limitation in Zoning Retrofits:Existing ducted infrastructure in US commercial buildings limits sensor deployment density, constraining granular climate control.
Strategic Opportunities
- India Residential Tower Penetration:Mumbai and Bangalore high-rise developers specify Wi-Fi-enabled multisplit systems as standard fit-out, bypassing retrofit economics.
- Convergence of Air Quality and Thermal Control:Particulate and VOC sensing modules are merging with thermostat logic, opening premium positioning in Chinese and South Korean urban markets.
- Third-Party Leasing Channels:Facility management firms in Germany and Japan now bundle smart AC hardware with energy-performance contracts, capturing long-term service revenue.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:The transition to mildly flammable A2L refrigerants requires technician retraining under EPA Section 608 and EU F-Gas certification schemes, constraining installation capacity.
- Interoperability Standard Fragmentation:China's GB/T connectivity protocols diverge from ISO/IEC frameworks, forcing OEMs to maintain parallel firmware branches for tender eligibility.
- Legacy Building Control Integration:BACnet and Modbus protocol translation to cloud-native APIs demands middleware development, extending deployment timelines in US and European commercial retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Air Conditioning Market |
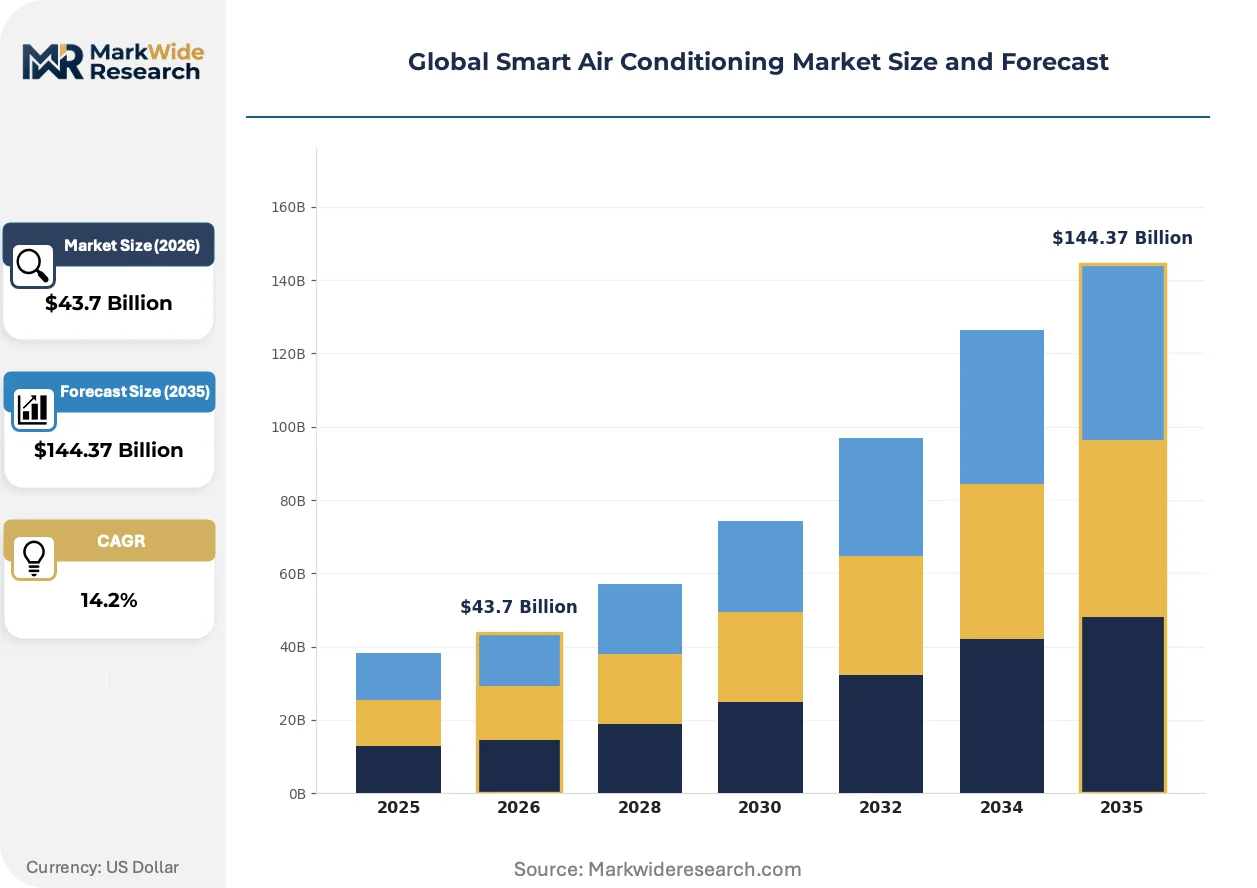
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $144.37 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window Units, Split Systems, Portable Units, Central Systems Technology: Wi-Fi Enabled, Sensor-Based, Inverter Technology, Smart Thermostats End User: Residential, Commercial, Industrial, Hospitality Installation: Wall-Mounted, Ceiling-Mounted, Floor-Mounted, Standalone |
| Companies Covered | Daikin Industries, LG Electronics, Samsung Electronics, Mitsubishi Electric, Panasonic Corporation, Carrier, Honeywell International, Johnson Controls, Gree Electric Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Air Conditioning Market Strategic Shifts
Thermal management systems are converging with air quality monitoring and grid-interactive load control, shifting value capture from hardware margins to recurring software and energy-service revenue streams.
Reversible heat pump technology is hybridizing with dedicated dehumidification cycles and domestic hot water production. Scandinavian and northeastern US residential adopters are specifying these triple-function units at accelerating rates. The technology is hybridizing what were three separate mechanical systems into single-package offerings, compressing contractor installation schedules and displacing standalone boiler and water heater categories.
The EU F-Gas Regulation's quota mechanism tightens hydrofluorocarbon supply through 2030. European OEMs are reformulating product lines around propane and CO2 transcritical cycles ahead of the constraint curve. Commercial refrigeration and light commercial AC segments face the steepest cost adjustments, with German and Polish distributors pre-positioning inventory ahead of quota price spikes.
Building operators in Singapore, Dubai, and Sydney are unbundling equipment ownership from thermal service delivery. Energy service companies assume capital responsibility, charging per-occupied-hour or per-kWh-cooled fees. This model concentrates in hospitality and healthcare verticals where occupancy volatility makes fixed depreciation burdens uneconomical.
Global Smart Air Conditioning Market Segmentation
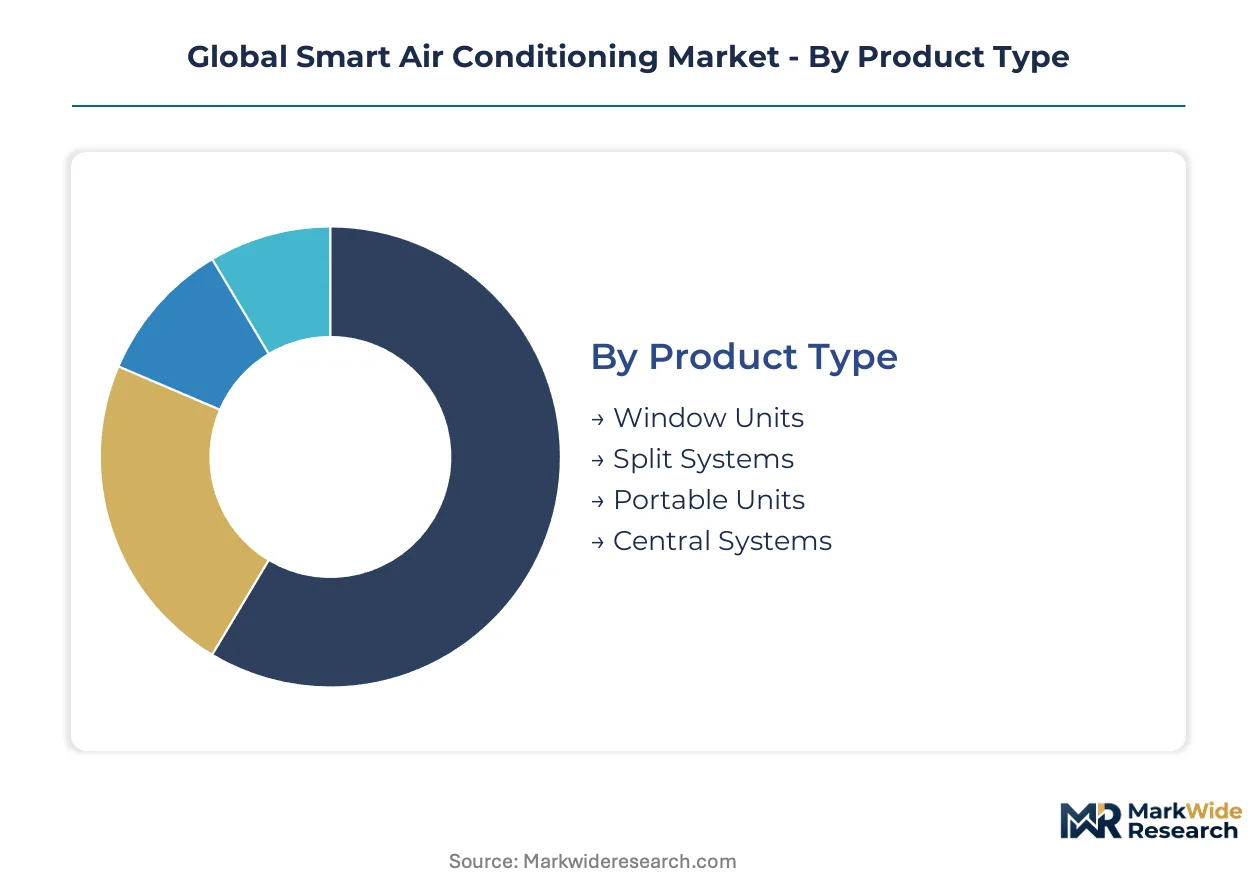
Smart air conditioning segmentation reveals divergent technology requirements across retrofit versus new-build contexts, with connectivity protocols and refrigerant compatibility acting as cross-cutting filters on product-market fit. Understanding these dimensional splits enables suppliers to align R&D roadmaps with regulatory windows and procurement cycles.
Product Type:
Installations span single-room retrofits through whole-building central plant replacements, with each format imposing distinct constraints on refrigerant line routing, electrical capacity, and control system integration.
- Split Systems:Wall-mounted and concealed duct configurations pair variable-speed compressors with refrigerant lines running between indoor evaporators and outdoor condensers. Demand concentrates in Chinese residential towers where developers specify Wi-Fi-enabled multisplits as standard fit-out, driven by SAMR GB standards mandating connectivity interoperability in new construction tenders.
- Central Systems:Chiller-based or packaged rooftop units distribute conditioned air through ducted infrastructure, integrating with building management systems via BACnet or Modbus protocols. Hospitality retrofits across Spain and Italy are replacing legacy chillers with connected central plant to meet EU energy-efficiency benchmarks and avoid carbon penalties.
- Window Units:Self-contained through-wall systems serve rental housing and temporary cooling needs where permanent installation is prohibited. North American urban multi-family stock and Southeast Asian budget residential segments sustain volume.
- Portable Units:Mobile units with exhaust hose deployment address spot cooling in leased commercial space and residential applications with restrictive building codes. German facility management firms bundle these with short-term energy-performance contracts for occupancy-volatile hospitality verticals.
The dominant share belongs to Split Systems, while Central Systems is closing the gap fastest as commercial retrofits accelerate.
Technology:
Cost tiers separate basic connectivity modules from full ecosystem integration, with margin pools concentrating where software recurring revenue attaches to hardware sales.
- Smart Thermostats:Cloud-connected control interfaces aggregate environmental sensing, occupancy detection, and utility demand-response signals into algorithmic setpoint management. Software subscription revenue and utility program participation fees in California, Texas, and South Australia expand margins beyond hardware replacement cycles.
- Inverter Technology:Variable-frequency drives modulate compressor motor speed against thermal load rather than cycling on-off, cutting energy consumption by 30-50% versus fixed-speed equivalents. Japanese and South Korean OEMs leverage captive power electronics manufacturing to defend price positioning.
- Wi-Fi Enabled:Basic cloud connectivity for remote control and scheduling via smartphone applications, typically integrated at factory level for tender compliance. Chinese GB/T protocol requirements force parallel firmware development for geographic eligibility.
- Sensor-Based:Granular environmental monitoring incorporating particulate, VOC, humidity, and occupancy detection to enable zoned conditioning. Premium positioning in Chinese and South Korean urban markets where air quality and thermal control are converging.
Smart Thermostats commands the value-accretive tier, though Inverter Technology penetration is expanding most quickly as minimum efficiency regulations tighten.
End User:
Customer type determines procurement channel, financing structure, and service contract attachment rates.
- Residential:Individual household purchases through retail and e-commerce channels, with installation typically outsourced to regional contractor networks. Mumbai and Bangalore high-rise developers are specifying connected multisplits as standard, bypassing retrofit economics.
- Hospitality:Hotel and resort operators with volatile occupancy patterns favor equipment-as-a-service models where energy service companies assume capital responsibility. Singapore, Dubai, and Sydney operators charge per-occupied-hour fees, concentrating thermal service delivery risk with vendors.
- Commercial:Office and retail building operators procuring through facility management firms or direct OEM relationships, with longer replacement cycles tied to lease structures. US commercial retrofits face technical constraints from existing ducted infrastructure limiting sensor deployment density.
- Industrial:Process cooling and critical environment applications requiring precision temperature and humidity control, with integration into plant automation systems. Heavy manufacturing and data center verticals drive specification.
Residential holds the installed base volume, yet Hospitality is gaining share fastest as service-based financing redistributes capital risk.
Installation:
Mounting configuration dictates contractor skill requirements, aesthetic integration, and spatial planning constraints.
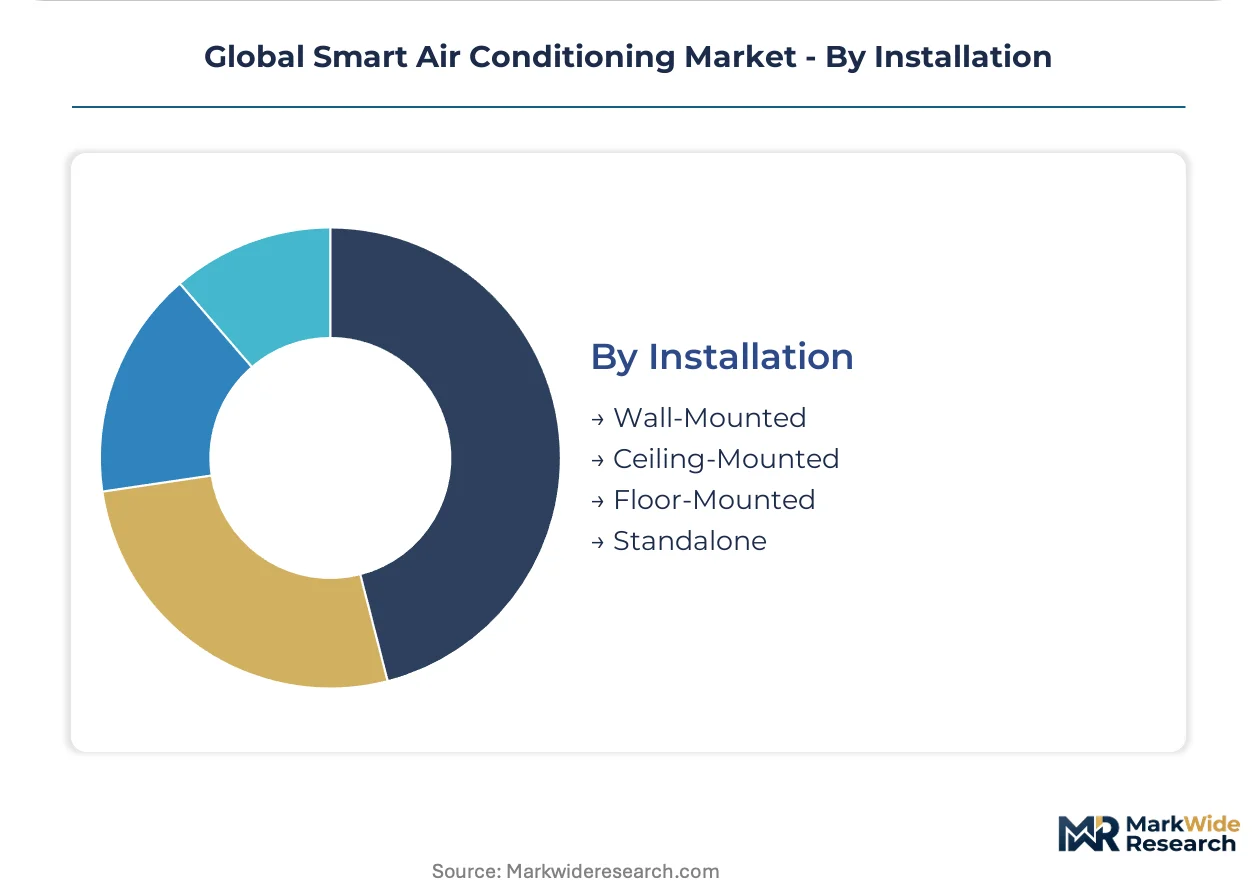
- Wall-Mounted:High-wall indoor units dominating residential split system deployment across Asia-Pacific apartment stock. Standardized mounting brackets and refrigerant line concealment options streamline installation.
- Ceiling-Mounted:Cassette and ducted concealed units serving commercial spaces where floor and wall area carry opportunity cost. Ceiling void depth and structural loading limit retrofit applicability.
- Floor-Mounted:Low-wall or console units addressing heating-dominant climates and spaces with limited wall height or sloped ceilings. Scandinavian reversible heat pump adoption favors this format for hybrid heating duty.
- Standalone:Portable and window units requiring no permanent mounting, traded through retail channels with minimal contractor involvement. Seasonal demand spikes in European and North American peak summer periods.
Wall-Mounted retains the volume lead, but Ceiling-Mounted is climbing fastest as commercial new-build specifications prioritize space efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal stark asymmetries in smart air conditioning trade. China runs substantial surpluses as domestic OEMs feed Southeast Asian and Middle Eastern markets, while the United States and Germany remain net importers of high-connectivity units despite sizable domestic production bases.
United States
Data center construction in Northern Virginia and Phoenix drives precision cooling demand. EPA AIM Act refrigerant phasedown timelines force OEMs to retool production lines for low-GWP alternatives. Texas utility demand-response programs monetize residential smart AC load curtailment.
China
Mega-city residential towers in Shanghai and Shenzhen specify Wi-Fi-enabled multisplit systems as standard fit-out. SAMR GB standards mandate connectivity interoperability for tender eligibility. Yangtze River Delta manufacturing clusters dominate compressor and power electronics output.
Germany
Commercial building retrofits in Munich and Hamburg replace legacy chillers with connected central plant. EU F-Gas Regulation quotas constrain hydrofluorocarbon supply for servicing installations. Facility management firms bundle smart AC hardware with energy-performance contracts.
Japan
Reversible heat pump adoption accelerates in Tokyo and Osaka residential stock for hybrid heating duty. METI efficiency standards tighten inverter performance thresholds. Kanto region OEMs leverage captive power electronics manufacturing to defend positioning.
India
Mumbai and Bangalore high-rise developers specify connected multisplits as standard, bypassing retrofit economics. BIS appliance safety standards create compliance gates for foreign OEMs. Western India manufacturing corridors expand compressor assembly capacity.
Global Smart Air Conditioning Market Competitive Environment
On the supply side, the industry is consolidating around integrated OEMs with captive financing and component manufacturing capabilities. Japanese and South Korean conglomerates anchor premium positioning through ecosystem integration and power electronics control. Chinese manufacturers compete on scale and backward integration into compressors. Strategic moves concentrate on equipment-as-a-service financing models and refrigerant-transition R&D spending.
Within the integrated conglomerate tier, Daikin Industries and Mitsubishi Electric exemplify premium positioning through captive supply chains and multi-year service contract attachment. Gree Electric Appliances occupies a scale-driven position anchored by domestic manufacturing depth. Samsung Electronics represents ecosystem-first positioning through smart-home platform integration.
| Leading Market Players |
|---|
| Daikin Industries |
| LG Electronics |
| Samsung Electronics |
| Mitsubishi Electric |
| Panasonic Corporation |
| Carrier |
| Honeywell International |
| Johnson Controls |
| Gree Electric Appliances |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese compressor manufacturing is compressing supplier margins and forcing tiered pricing stratification across Wi-Fi-enabled split systems, with OEMs absorbing input volatility to defend market share in tender-driven residential tower procurement.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by inverter efficiency certification and after-sales service bundling. Cost compression in economy tiers is intensifying because of copper concentrate volatility from Chilean supply. Residential developers in Mumbai and Bangalore exhibit highest price sensitivity, while hospitality operators in Singapore and Dubai prioritize service reliability over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for smart air conditioning OEMs. Manufacturing concentrates in China, Japan, and South Korea, with production drawing from Chilean copper, Chinese rare-earth processing, and Korean power electronics. Single-source vulnerability in refrigerant precursor chemicals from Chinese chemical clusters threatens formulation continuity. Distribution runs through regional HVAC contractor networks and facility management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart air conditioning market sits in early-cycle expansion, with equipment-as-a-service financing unlocking penetration in occupancy-volatile verticals that previously deferred capital deployment.
For Market Incumbents: Harden captive financing capabilities to lock in multi-year service contracts before low-GWP refrigerant transitions disrupt installer relationships. Deepen backward integration into compressor manufacturing to offset copper and rare-earth input volatility. Prioritize EPA Section 608 and EU F-Gas certification pre-positioning ahead of A2L refrigerant handling bottlenecks.
For New Entrants and Emerging Players: Establish a beachhead in India's residential tower specification channel, where BIS compliance gates have kept foreign OEM penetration below saturation. Target German facility management firms bundling hardware with energy-performance contracts. Lead with sensor-based air quality convergence as a premium positioning wedge against scale-driven Chinese competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward OEMs with captive power electronics manufacturing and established demand-response utility program participation. Long-term viability hinges on refrigerant-transition R&D execution and cloud-native control platform development. Watch for inflection in A2L refrigerant installation capacity constraints as a signal of margin recovery timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Financing Launch | Redistributes capital risk from building operators to OEM balance sheets in hospitality verticals. |
| Low-GWP Refrigerant Product Line Reformulation | Aligns with EPA AIM Act and EU F-Gas Regulation phasedown timelines ahead of quota constraints. |
| Demand-Response Platform Integration | Captures utility program revenue from California, Texas, and South Australia grid operators. |
| Sensor-Based Zoning Technology Development | Displaces conventional central-system controls in US commercial retrofits with granular occupancy data. |
| Backward Integration into Compressor Manufacturing | Defends margin positioning against copper and rare-earth input volatility from Chilean and Chinese sources. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with HVAC OEM product managers, facility management procurement directors, utility demand-response program administrators, and refrigerant handling certification trainers; alongside secondary validation through EPA AIM Act filings, EU F-Gas Regulation quota tracking, SAMR GB standard documentation, and SEC 10-K equipment revenue disclosures. Bottom-up unit shipment modeling and top-down energy-efficiency regulatory impact assessment were triangulated against regional construction permit data.
Forecast inputs span product type splits, technology tier penetration, end-user procurement channel evolution, and installation format preferences across the projection horizon. CAGRs were derived from segment-level adoption curves weighted by regulatory compliance deadlines and utility incentive program scaling. Modeled variables include refrigerant-transition capital expenditure timing, equipment-as-a-service contract attachment rates, and sensor-based zoning retrofit economics.
Sensitivities concentrate around refrigerant-handling certification capacity bottlenecks, copper concentrate supply disruptions, and interoperability standard fragmentation between Chinese GB/T protocols and ISO/IEC frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
District Cooling Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market