
 Dropshipping Automation Software Market | 2026-2036
Dropshipping Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Dropshipping Automation Software Market Insights
Direct-to-consumer fulfillment channels is reshaping how merchants source and ship products without holding inventory. AutoDS leverages proprietary supplier networks to sustain automation depth across AliExpress and private-label integrations. Spocket anchors its position through US and EU supplier concentration, competing on faster delivery windows against Asian-sourced alternatives. DSers differentiates via bulk-order processing tools that dominate Shopify merchant workflows.
Dropshipping automation software comprises cloud-native and on-premise platforms that synchronize inventory data, route orders to third-party suppliers, and track fulfillment status through API connections or plugin architectures. These systems reduce manual intervention by enabling real-time stock-level monitoring and automated purchase-order generation across multi-channel storefronts. Cloud-Based deployment leads the segment mix due to lower upfront infrastructure costs and faster onboarding for small merchants, while API Integration commands margin pools as enterprise sellers demand custom warehouse connections. Order Fulfillment services within the Service Type dimension are expanding fastest, reflecting merchant priority on shipping-speed optimization over basic inventory visibility.
The US Federal Trade Commission scrutinizes deceptive shipping-time claims and false origin labeling in dropshipping advertisements, pressuring platforms to embed compliance checks into automated listing tools. The EU's General Data Protection Regulation and Digital Services Act impose data-handling and transparency obligations on cross-border seller platforms that aggregate consumer information across jurisdictions. China's SAMR enforces e-commerce operator accountability rules that affect supplier verification protocols for software bridging domestic manufacturers to Western storefronts. Stakeholders must monitor evolving platform-liability frameworks as regulators shift responsibility for product quality and delivery accuracy from individual sellers to the automation layers they employ.
Market Dynamics
API-first architectures are compressing integration timelines between merchant storefronts and third-party logistics networks, forcing legacy platform providers to reengineer their connector frameworks or lose enterprise accounts to cloud-native competitors.
Growth Catalysts
- FTC enforcement on shipping transparency:The US Federal Trade Commission's scrutiny of deceptive delivery claims compels automation vendors to embed real-time tracking verification into their listing tools, raising platform stickiness among compliance-conscious merchants.
- Cloud migration among small merchants:Reduced upfront infrastructure costs accelerate onboarding velocity for Shopify and WooCommerce sellers seeking multi-channel inventory synchronization without dedicated DevOps resources.
- EU Digital Services Act compliance layers:Cross-border seller platforms aggregate consumer data across jurisdictions, creating demand for embedded GDPR and transparency-obligation modules within automation stacks.
Market Restraints
- Supplier verification protocol costs:China's SAMR enforcement of e-commerce operator accountability rules requires software bridging domestic manufacturers to Western storefronts to maintain expensive supplier-audit trails.
- API rate-limiting bottlenecks:Major marketplace platforms impose throttling constraints on inventory-sync frequency, capping automation responsiveness during high-velocity sales events.
- Cross-border payment friction:Currency conversion spreads and frozen-fund risks on Asian sourcing platforms erode margin predictability for merchants automating purchase-order generation.
Strategic Opportunities
- Private-label integration white space:Automation vendors can deepen supplier-network control by building captive connections to white-label manufacturers, bypassing commodity sourcing platforms entirely.
- India's BIS certification automation:The Bureau of Indian Standards' expanding e-commerce product-safety mandates create openings for compliance-checking modules targeting cross-border sellers entering the subcontinent.
- Headless commerce convergence:Merging API-first dropshipping tools with headless storefront architectures enables custom frontend experiences without sacrificing backend supplier connectivity.
Industry Challenges
- Legacy ERP integration complexity:Enterprise merchants running SAP or Oracle systems require expensive custom middleware development to synchronize dropshipping workflows with established procurement hierarchies.
- Real-time inventory accuracy gaps:Supplier-side stock-level latency creates oversell incidents that damage merchant ratings, demanding costly buffer-inventory algorithms or manual reconciliation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dropshipping Automation Software Market |
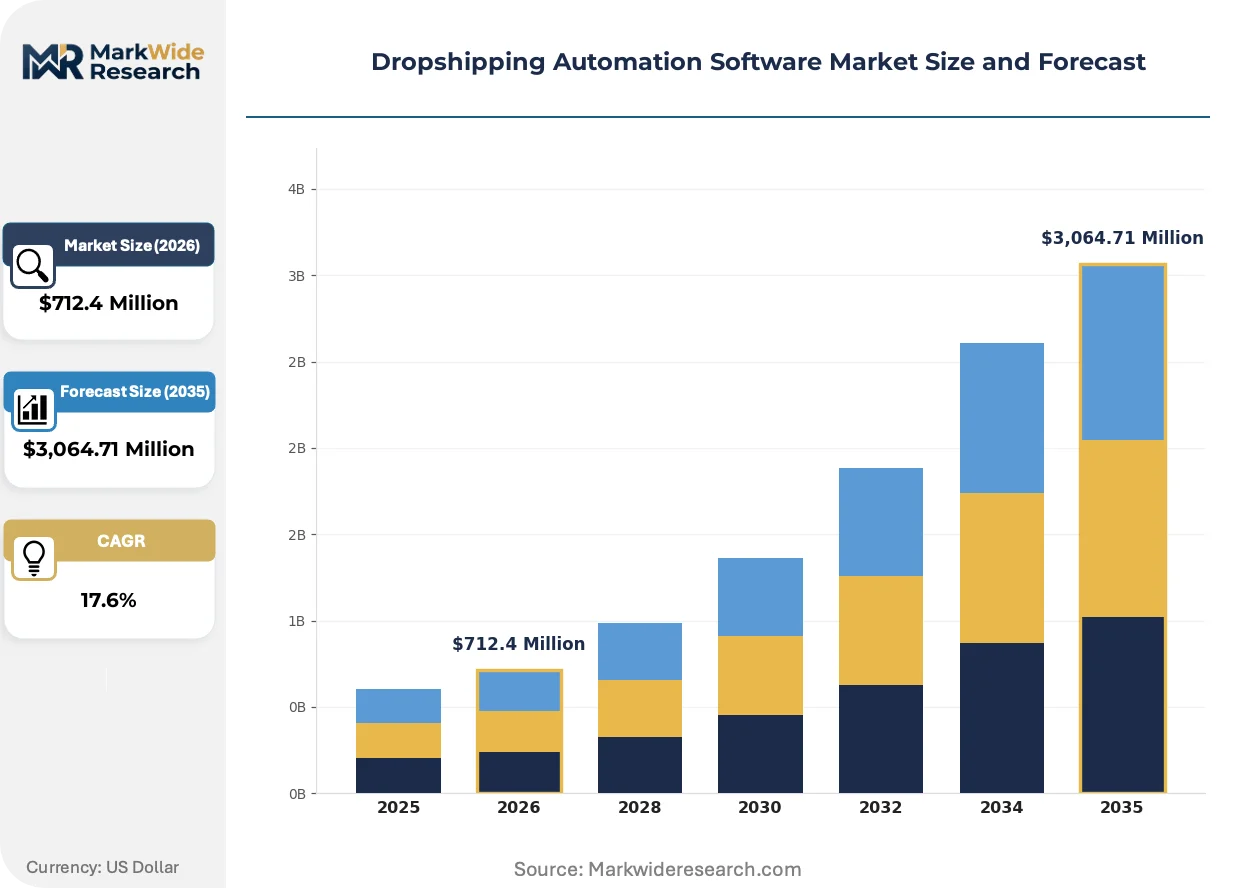
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $3,064.71 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Service Type: Inventory Management, Order Fulfillment, Customer Support, Analytics End User: E-commerce Businesses, Retailers, Startups, Agencies Integration Level: API Integration, Plugin Integration, Manual Sync, Automated Sync |
| Companies Covered | AutoDS, DSers, Spocket, Spark Shipping, Zendrop, Inventory Source, Syncee, Easync, Dropship.IO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dropshipping Automation Software Market Trends and Innovations
Merchant expectations are pivoting from basic order-routing to predictive fulfillment optimization, compressing the competitive window for vendors lacking machine-learning capabilities or direct supplier-network control.
Headless commerce architectures are digitizing how storefronts consume supplier data by decoupling presentation layers from backend inventory systems. Mid-market merchants adopting composable stacks are migrating fastest, typically within 90-day implementation windows. This digitizing pressure is compressing margins for plugin-dependent competitors unable to offer custom API endpoints.
The EU's Digital Services Act imposes algorithmic transparency obligations on platforms aggregating third-party seller data. Automation vendors must now expose ranking and recommendation logic to regulators, increasing compliance engineering overhead. Cross-border storefront operators in Germany and France are responding by localizing data-processing infrastructure to satisfy CNIL and BfDI scrutiny.
Merchant procurement patterns are fragmenting across specialized supplier networks rather than consolidating on dominant Asian platforms. Shopify Plus sellers are diversifying sourcing toward US and EU-based fulfillment partners, displacing AliExpress-dependent workflows. This rotation is most visible in California and Texas, where two-day delivery guarantees now dictate supplier selection criteria ahead of unit economics.
Dropshipping Automation Software Market Segmentation
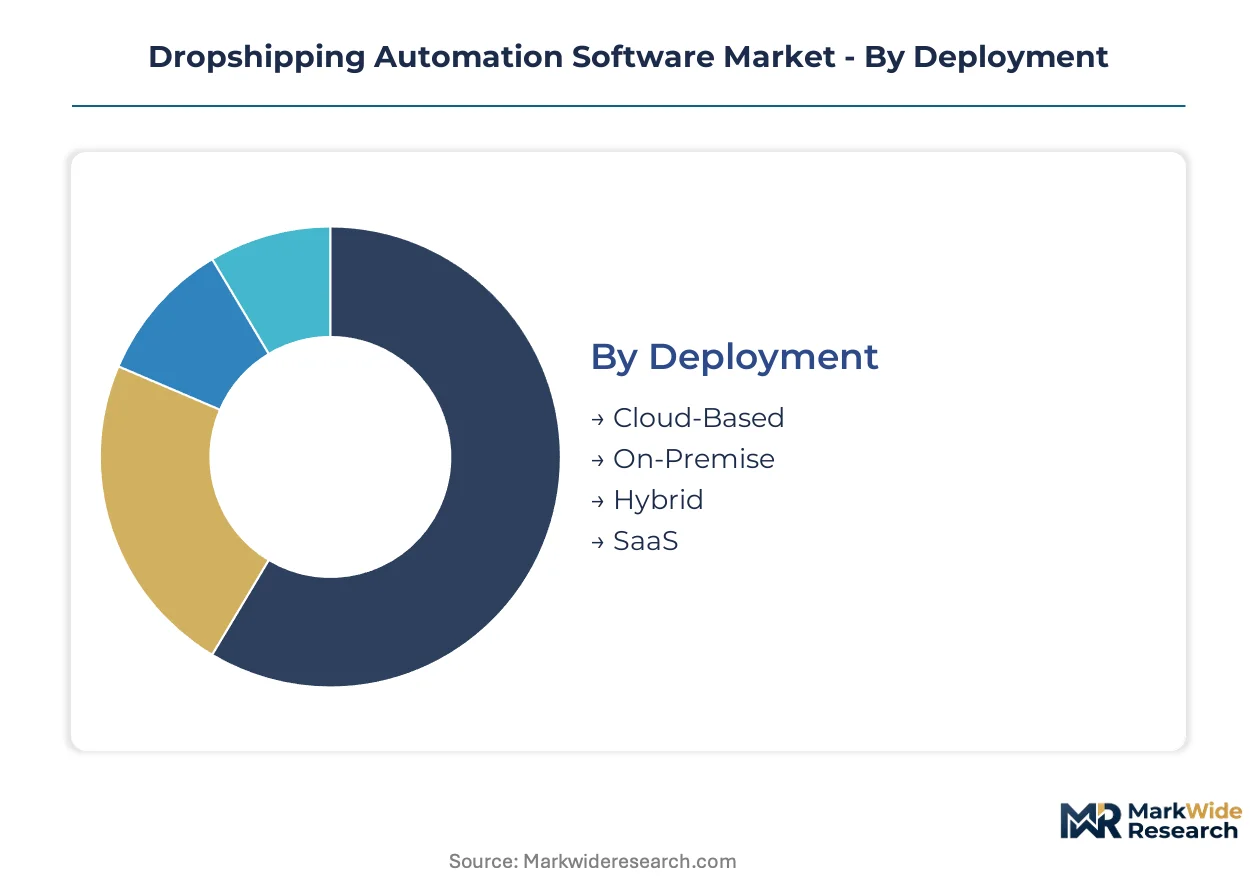
Deployment architecture determines how quickly merchants can onboard and scale automation capabilities. Integration depth and service modularity separate vendors serving high-velocity sellers from those supporting slower-turnover operations.
Deployment:
Cloud-Based deployments compress implementation cycles to days, while On-Premise installations stretch across quarters. SaaS models iterate fastest on feature releases, whereas Hybrid configurations balance control with speed.
- Cloud-Based:Multi-tenant architectures host inventory synchronization and order routing on shared infrastructure, eliminating server procurement delays. Shopify and WooCommerce merchants in California and Texas gravitate here for sub-24-hour onboarding. The FTC's shipping-transparency enforcement pressures vendors to embed real-time tracking verification into these platforms.
- SaaS:Subscription pricing aligns costs with transaction volume, attracting capital-constrained startups. The EU's Digital Services Act compliance modules are landing first in SaaS stacks due to faster update cycles.
- On-Premise:Dedicated servers behind merchant firewalls satisfy data-sovereignty requirements in Germany and France under CNIL and BfDI scrutiny.
- Hybrid:Sensitive supplier credentials reside on-premise while storefront-facing APIs run cloud-native, splitting latency exposure.
Cloud-Based dominates installed base. SaaS is where expansion concentrates.
Service Type:
Order Fulfillment commands premium pricing due to direct customer-exposure risk, while Analytics layers absorb slower procurement cycles as merchants prioritize operational over strategic tools.
- Order Fulfillment:Automated purchase-order generation, shipping-label creation, and carrier-selection algorithms compress delivery windows. E-commerce businesses in the United States pay premium rates for two-day guarantee orchestration.
- Inventory Management:Real-time stock-level monitoring across multi-channel storefronts prevents oversell incidents. API rate-limiting from Amazon and eBay throttles sync frequency, capping responsiveness.
- Customer Support:Ticket routing and returns-processing automation reduces merchant headcount in high-volume operations.
- Analytics:Demand-forecasting and margin-optimization dashboards attract enterprise sellers with established data science teams.
Inventory Management anchors revenue. Order Fulfillment is climbing the fastest.
End User:
E-commerce Businesses cycle through vendor evaluations quarterly, while Agencies lock in annual contracts spanning multiple client accounts.
- E-commerce Businesses:Direct-to-consumer merchants operating Shopify Plus or Amazon Seller Central accounts demand deep platform-native integrations. These users expand automation spending fastest as order volumes scale.
- Agencies:Multi-tenant management portals let service providers orchestrate dropshipping across dozens of merchant accounts from unified dashboards.
- Retailers:Brick-and-click operators bridging physical POS systems with online dropshipping workflows require legacy ERP connectors.
- Startups:Pre-revenue founders prioritize free-tier API access over advanced features, converting to paid tiers at revenue milestones.
E-commerce Businesses drive volume. Agencies represent the steepest expansion trajectory.
Integration Level:
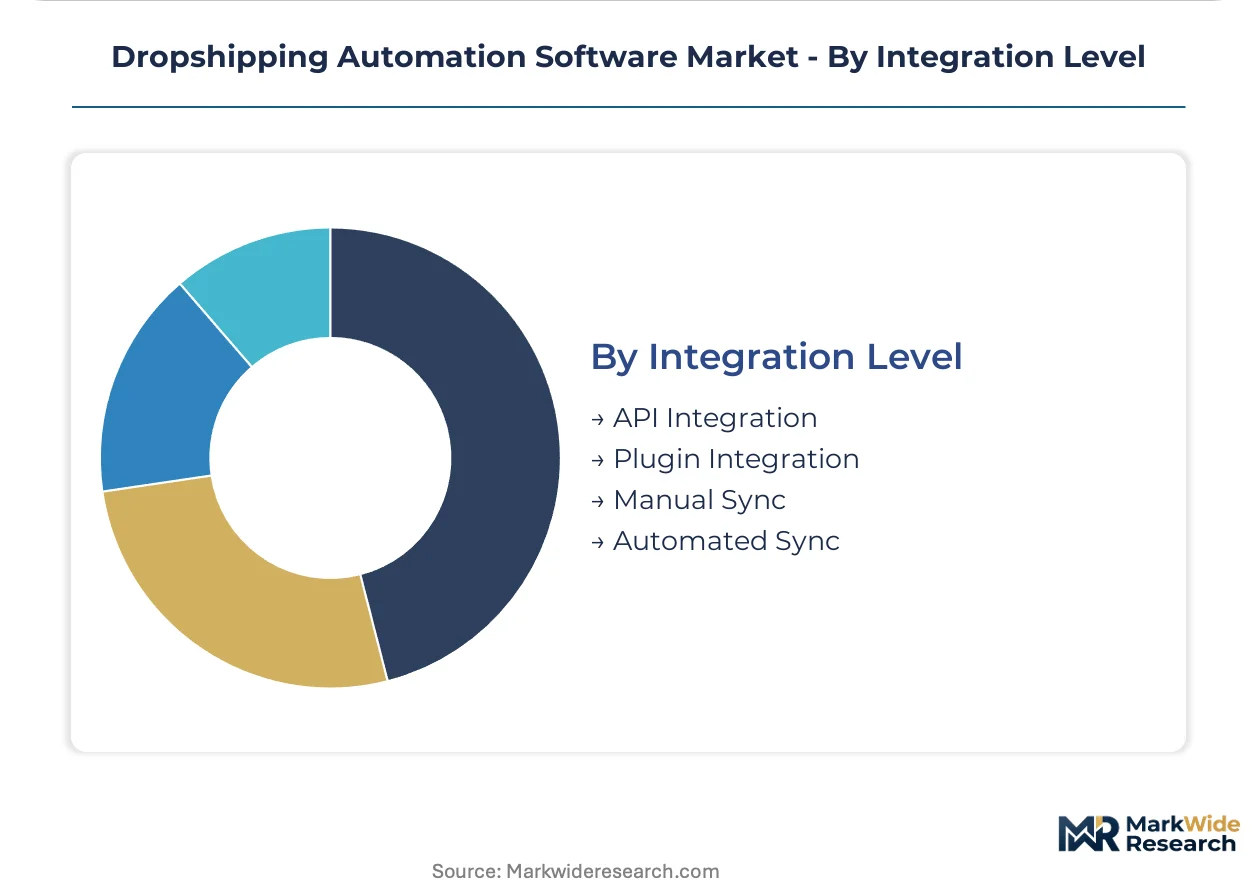
API Integration demands engineering resources but unlocks custom warehouse connections, while Plugin Integration sacrifices flexibility for speed-to-deployment.
- API Integration:Direct endpoint connections to supplier ERPs and 3PL networks enable sub-minute inventory sync. Enterprise merchants in the United States pay premium implementation fees for SAP and Oracle middleware.
- Automated Sync:Pre-built connectors to AliExpress, Spocket, and CJ Dropshipping reduce technical barriers for mid-market sellers.
- Plugin Integration:Shopify App Store and WooCommerce marketplace listings drive discovery among non-technical merchants.
- Manual Sync:CSV upload and spreadsheet-based workflows persist among legacy sellers with low order velocity.
Plugin Integration dominates merchant counts. API Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC's shipping-transparency enforcement anchors merchant compliance spending in the United States, while cross-border data obligations from the EU's Digital Services Act reshape vendor engineering priorities in Germany and France.
United States
Shopify Plus and Amazon Seller Central ecosystems concentrate automation demand in California and Texas, where two-day delivery guarantees dictate supplier selection. The FTC's scrutiny of deceptive shipping-time claims pressures platforms to embed real-time tracking verification into listing tools. Los Angeles and Austin merchant clusters drive the fastest expansion in API-first integration spending.
Germany
Data-sovereignty requirements under BfDI scrutiny push enterprise merchants toward on-premise deployments and hybrid configurations. The EU's Digital Services Act imposes algorithmic transparency obligations on platforms aggregating third-party seller data. Berlin and Munich industrial clusters localize data-processing infrastructure to satisfy CNIL-equivalent compliance layers.
China
SAMR enforcement of e-commerce operator accountability rules affects supplier verification protocols for software bridging domestic manufacturers to Western storefronts. Shenzhen and Guangzhou manufacturing hubs concentrate white-label integration demand as merchants seek captive supplier-network control. Cross-border payment friction on Asian sourcing platforms erodes margin predictability for automated purchase-order systems.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for cross-border storefront operators navigating GDPR residual obligations and new UK-specific data-handling frameworks. London merchant clusters prioritize SaaS deployments for faster update cycles on transparency-obligation modules. Manchester and Birmingham logistics hubs drive demand for EU supplier diversification away from AliExpress-dependent workflows.
India
BIS certification mandates for e-commerce product safety create openings for compliance-checking modules targeting cross-border sellers entering the subcontinent. Mumbai and Bangalore startup ecosystems gravitate toward cloud-based deployments with subscription pricing aligned to transaction volume. The DGFT's evolving import-documentation requirements pressure automation vendors to embed customs-clearance verification into order-routing systems.
Dropshipping Automation Software Market Competitive Landscape
Platform-native specialists and API-first integrators split the market between merchant-facing workflow tools and enterprise-grade supplier connectivity. The vendor base concentrates around three strategic archetypes: cloud-native SaaS providers with rapid feature iteration, legacy plugin-dependent platforms defending merchant counts, and hybrid-stack vendors balancing control with deployment velocity. Dominant competitive moves include backward integration into captive supplier networks and geographic expansion through localized compliance modules.
Within the platform-native tier, AutoDS and DSers occupy positions exemplifying divergent automation philosophies. AutoDS anchors the proprietary supplier-network approach through deep AliExpress and private-label integrations. DSers represents the bulk-order processing specialization dominating Shopify merchant workflows. Spocket sits within the US-EU supplier concentration archetype, competing on delivery-window compression against Asian-sourced alternatives.
| Leading Market Players |
|---|
| AutoDS |
| DSers |
| Spocket |
| Spark Shipping |
| Zendrop |
| Inventory Source |
| Syncee |
| Easync |
| Dropship.IO |
| Others |
Pricing and Supply Chain Analysis
China's Shenzhen and Guangzhou manufacturing clusters concentrate white-label supplier networks, anchoring margin pools in automation software layers that bridge these production hubs to Western storefronts. SaaS vendors capture recurring revenue premiums by embedding compliance modules that absorb cross-border regulatory friction, while merchant-facing tools face cost compression from API rate-limiting and payment-friction erosion.
Pricing Analysis
Geographic price spreads between US-EU and Asian-sourced supplier tiers drive merchant willingness-to-pay for automation platforms guaranteeing delivery-window compression. Three-tier pricing structure across premium API-integration, standard plugin-based, and economy manual-sync levels stratifies by integration depth and compliance-bundling. Pricing pressure stems from cloud-native entrants undercutting legacy on-premise deployments with faster onboarding cycles. Capital-constrained startups exhibit highest price sensitivity, while enterprise merchants running SAP middleware show lowest elasticity due to switching-cost lock-in.
Supply Chain Analysis
Export-control scrutiny on cross-border data flows and API infrastructure shapes supplier verification protocol costs for software bridging Chinese manufacturers to Western storefronts. Supply concentration centers on China for white-label manufacturing, the United States for Shopify-Amazon platform ecosystems, and Germany for data-sovereignty-compliant hosting infrastructure. Component dependencies include cloud-compute capacity, payment-gateway integrations, and carrier-API connectivity. Single-source vulnerability pervades AliExpress-dependent inventory sync workflows. Distribution runs through SaaS marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant procurement fragmentation toward specialized supplier networks threatens incumbent platforms anchored on dominant Asian sourcing platforms, demanding defensive repositioning around captive network control.
For Market Incumbents: Harden platform stickiness by backward integration into captive US-EU supplier networks that guarantee two-day delivery windows, displacing commodity AliExpress dependencies. Invest in compliance-engineering capacity to embed FTC shipping-transparency verification and EU Digital Services Act algorithmic-exposure modules ahead of regulatory enforcement waves. API-first architecture retention serves as the critical defensive lever against cloud-native entrants. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification automation whitespace, where cross-border seller compliance-checking modules face minimal incumbent saturation. Target Mumbai and Bangalore startup ecosystems with subscription-priced cloud deployments aligned to transaction-volume scaling. Lead with customs-clearance verification embedded in order-routing systems as the differentiated go-to-market angle against generic inventory-sync tools. For Investors and Strategic Acquirers: Capital is best deployed toward API-first integrators with demonstrated enterprise middleware capabilities for SAP-Oracle connectivity, as legacy ERP synchronization complexity creates durable moats. Long-term viability hinges on supplier-network control depth rather than merchant-count scale. Watch for inflection signals in FTC enforcement intensity that would accelerate compliance-module procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Supplier Network Development | Backward integration into white-label manufacturers bypasses commodity sourcing platforms entirely. |
| Compliance Module Embedding | FTC and EU Digital Services Act enforcement pressures create embedded verification demand. |
| API-First Architecture Migration | Headless commerce convergence enables custom frontend experiences without sacrificing backend connectivity. |
| Geographic Compliance Localization | India BIS and China SAMR mandates require jurisdiction-specific automation layers. |
| Enterprise ERP Middleware Expansion | SAP and Oracle integration capabilities unlock premium implementation fees from high-velocity sellers. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with dropshipping platform executives, Shopify Plus merchant operators, supply-chain integration specialists, and regulatory compliance officers; and secondary validation through SEC SaaS company filings, App Store marketplace data, FTC enforcement action records, and EU Digital Services Act implementation guidance. Bottom-up merchant-spending estimates triangulated against top-down platform-revenue aggregation.
Forecast inputs considered deployment architecture adoption curves, service-type spending prioritization, and end-user segment expansion velocities across the projection horizon. Segmentation dimensions modeled include cloud-SaaS-on-premise-hybrid deployment mix, order fulfillment-inventory management-customer support-analytics service type, and API-automated sync-plugin-manual integration level. CAGRs derived from segment-level growth rate blending weighted by installed-base composition. API rate-limiting constraints and cross-border payment friction assumptions shaped automation responsiveness ceilings.
Stress conditions across FTC enforcement intensity, EU regulatory implementation timelines, and supplier-verification protocol cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on merchant onboarding velocity and platform-native integration depth. Material shifts in SAMR accountability rule enforcement or BIS certification mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
United States Laboratory Automation Market
Automation
Universal Process Control Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Escalator Control Systems Market
Automation
US Workload Scheduling and Automation Market
Automation
Industrial Vending Machines Market
Automation
CNC Controller Market
Automation
Digital Process Automation Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Computer Numerical Control Market
Automation
Postal Automation System Market
Automation
Home Automation Market
Automation
Global Cloud Automation Market
Automation
Europe Laboratory Automation Market
Automation
Europe Marketing Automation Software Market
Automation
Voice Picking Solutions Market