
 Intraosseous Infusion Device Market | 2026-2036
Intraosseous Infusion Device Market Size, Share, and Industry Trends Forecast 2026-2036
Intraosseous Infusion Device Market Analysis
A shift from single-source to multi-source procurement of intraosseous needles is broadening vendor access for emergency departments and military buyers. Teleflex Incorporated leverages its critical care portfolio to sustain hospital channel dominance across North American trauma centers. Becton, Dickinson and Company anchors its position through deep distribution into emergency medical services fleets. PerSys Medical specializes in battlefield-ready powered devices that compete directly with conventional manual alternatives.
An intraosseous infusion device is a rigid needle or drill-based system designed to penetrate cortical bone and deliver fluids, medications, or blood products directly into the medullary cavity, typically achieving access in under sixty seconds during vascular collapse. Its primary purpose is to secure emergency vascular access when peripheral veins are inaccessible due to shock, burns, or obesity. Powered devices command premium placement in advanced trauma settings where speed and first-attempt success rates determine clinical outcomes, while disposable devices capture volume in military and pre-hospital deployments where sterility and field portability override unit economics. Manual devices retain entrenched positions in resource-constrained hospitals where capital budgets limit powered system adoption.
The FDA governs intraosseous devices under Class II medical device standards requiring 510(k) clearance, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for powered systems seeking CE marking. These frameworks elevate barriers for new entrants and reward incumbents with established quality management systems and predicate device histories. Stakeholders must monitor evolving pre-hospital care protocols and military doctrine shifts that could accelerate powered device standardization or redirect procurement toward single-use disposables.
Market Dynamics
Powered intraosseous systems are compressing manual device margins across trauma centers as first-attempt success rates become the dominant procurement criterion for emergency departments and military buyers.
Growth Catalysts
- Emergency Medical Services Fleet Modernization:Pre-hospital care protocols in the United States now mandate intraosseous access competency for paramedic certification, expanding device pull-through into ambulance and air-medical units.
- FDA 510(k) Pathway Efficiency:Class II medical device clearance standards for intraosseous needles reward predicate device histories, accelerating market entry for manufacturers with established quality management systems.
- Military Doctrine Standardization:NATO trauma care guidelines now specify powered intraosseous devices for tactical combat casualty care, creating institutional demand across allied defense procurement channels.
Market Restraints
- Capital Budget Constraints:Powered device acquisition costs limit penetration in resource-constrained hospitals where manual alternatives satisfy minimum clinical requirements.
- Single-Use Disposable Economics:Per-procedure costs for sterile intraosseous needles create procurement friction against reusable manual systems in high-volume emergency departments.
- Training Infrastructure Gaps:Competency maintenance requirements for powered device operators strain continuing medical education budgets in rural and community hospital settings.
Strategic Opportunities
- Pediatric Emergency Expansion:Underpenetrated neonatal and pediatric emergency departments present white space for device manufacturers offering size-optimized needle sets.
- EU Medical Device Regulation Alignment:Enhanced clinical evidence requirements for powered systems seeking CE marking create competitive moats for incumbents with robust predicate histories.
- Telemedicine-Integrated Training:Remote procedural coaching platforms enable device vendors to bypass traditional clinical specialist networks and reach distributed emergency departments directly.
Industry Challenges
- Competency Decay Management:Infrequent clinical use of intraosseous access in low-acuity settings drives skill atrophy and complicates operator certification maintenance.
- Interoperability with Electronic Health Records:Device data capture and documentation integration requires capital investment in health information technology infrastructure.
- Supply Chain Sterility Assurance:Single-use packaging integrity and expiration management create logistics complexity for military and disaster response stockpiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraosseous Infusion Device Market |
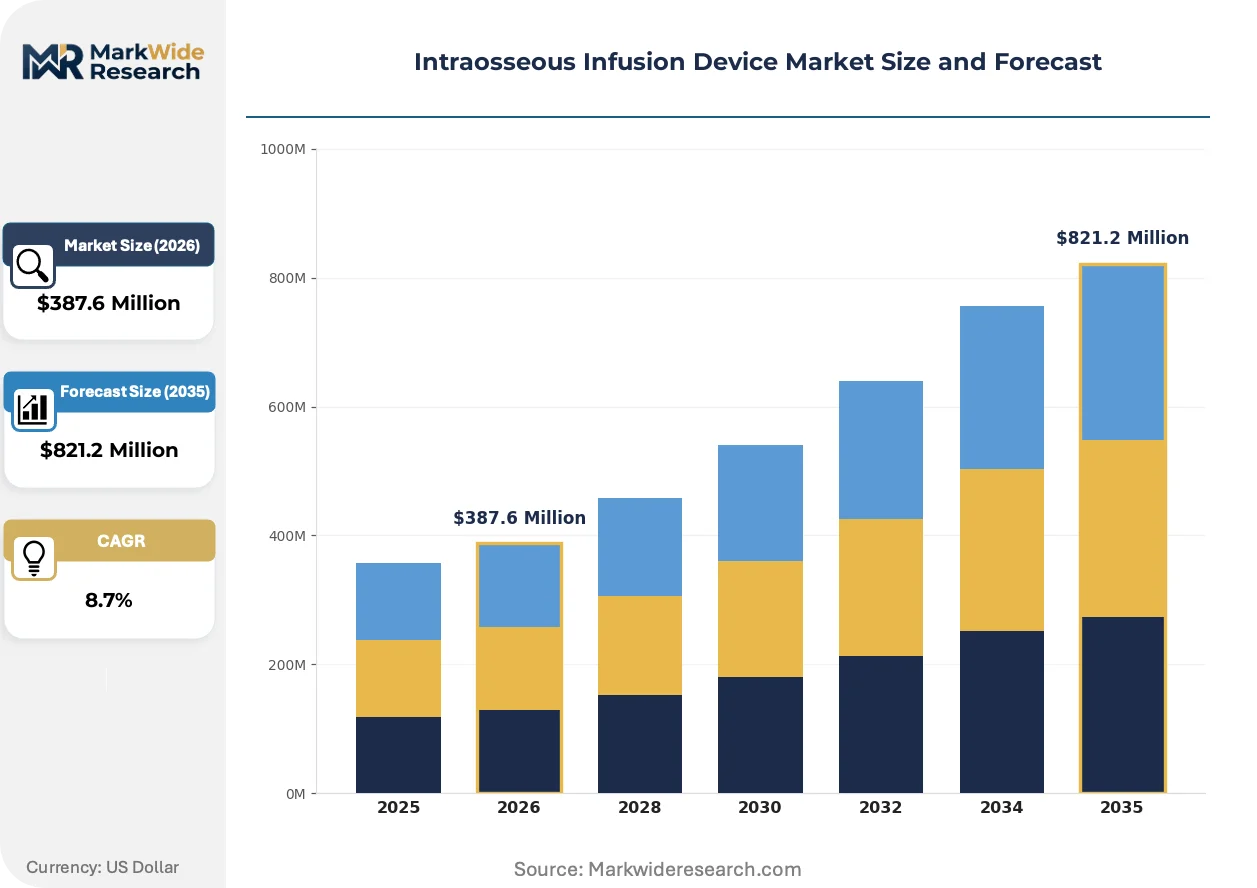
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Devices, Powered Devices, Disposable Devices, Reusable Devices End User: Hospitals, Emergency Medical Services, Military, Home Care Usage Frequency: Single Use, Multiple Use, Emergency Use, Routine Use Application: Trauma Care, Medication Administration, Fluid Resuscitation, Shock Treatment |
| Companies Covered | Cardinal Health, Inc., PerSys Medical, Teleflex Incorporated, Biopsybell S.r.l., Aero Healthcare AU Pty Ltd., Becton, Dickinson and Company, SAM Medical, PAVmed Inc., Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraosseous Infusion Device Market Emerging Trajectories
Device architecture is converging around battery-powered drill systems with integrated depth control, while regulatory frameworks and procurement behaviors reshape competitive access across emergency care settings.
Battery-powered intraosseous drivers with automated depth-stop mechanisms are consolidating clinical preference in advanced trauma centers. Emergency departments with high-volume penetrating trauma caseloads now specify these systems in capital equipment tenders. The technology is consolidating vendor relationships around fewer suppliers capable of delivering both device reliability and training infrastructure.
The EU Medical Device Regulation imposes enhanced clinical evidence requirements for powered intraosseous systems seeking CE marking. Manufacturers must now submit post-market surveillance data and risk management documentation beyond previous Medical Device Directive standards. Powered device categories face extended review timelines, compressing market entry windows for new entrants while rewarding incumbents with established notified body relationships.
Hospital purchasing cooperatives are aggregating intraosseous device procurement across multi-facility health systems. Emergency department supply managers now negotiate master agreements covering needles, drivers, and training services as bundled contracts. This concentration is most visible in United States integrated delivery networks where standardization across trauma centers overrides individual physician preference.
Intraosseous Infusion Device Market Segmentation
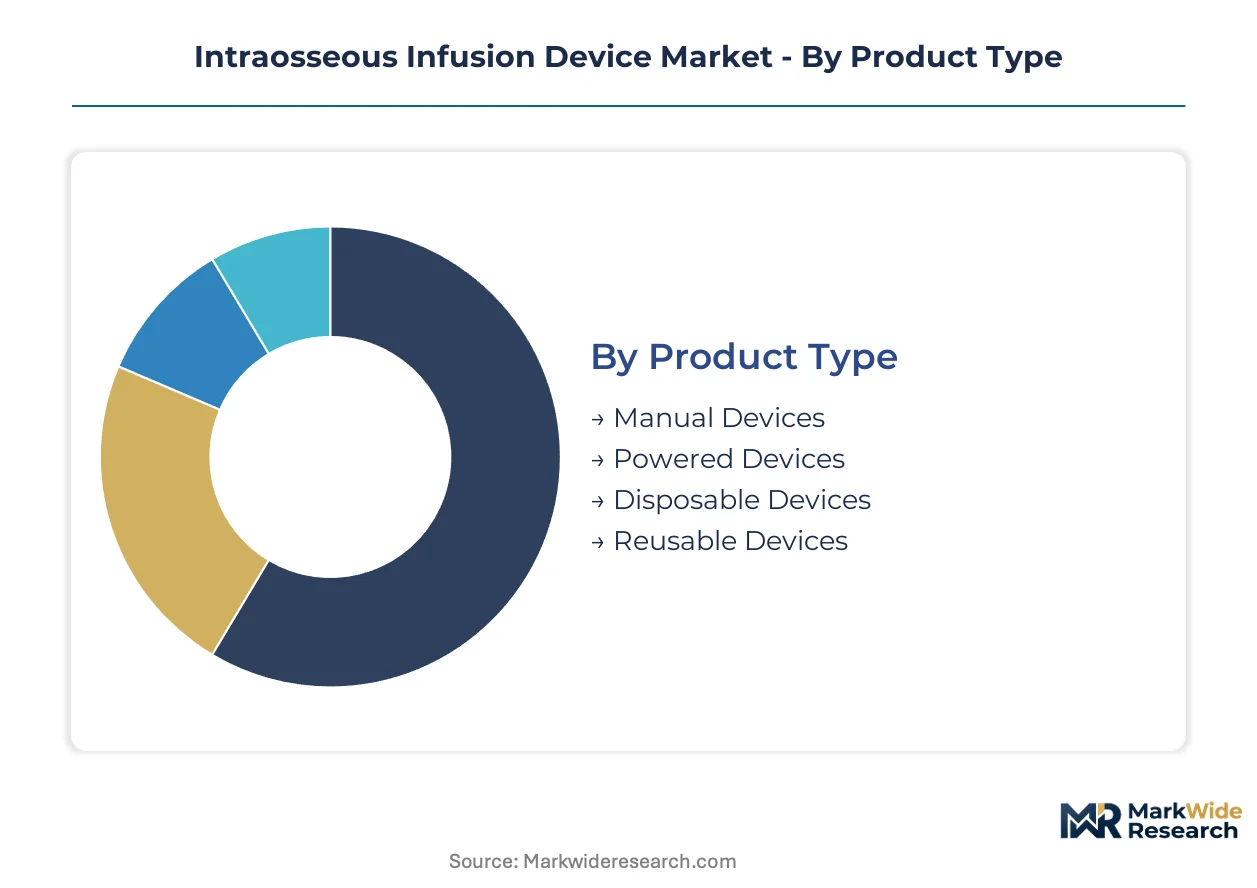
Segmentation in intraosseous infusion devices reveals how clinical settings, procurement economics, and regulatory pathways fragment demand across fundamentally different buyer profiles. Understanding these divisions exposes where technology premiums command placement versus where commoditization pressures dominate.
Product Type:
Technology architecture determines capital intensity, operator training requirements, and regulatory clearance pathways across the installed base.
- Powered Devices:Battery-driven drill systems with automated depth-stop mechanisms penetrate cortical bone in under ten seconds. Demand concentrates in Level I trauma centers and military field hospitals where first-attempt success rates above 95% justify acquisition costs exceeding manual alternatives by 8-12x.
- Manual Devices:Spring-loaded or screw-driven needles requiring operator-applied pressure and rotation. These retain entrenched positions in resource-constrained community hospitals across the United States where capital budgets prioritize multi-use instruments over disposable economics.
- Disposable Devices:Single-use sterile needle sets designed for field deployment without sterilization infrastructure. Military procurement programs and disaster response stockpiles drive volume, with sterility assurance overriding per-procedure cost considerations.
- Reusable Devices:Metal needle systems with autoclavable components for high-volume emergency departments. These satisfy minimum clinical requirements in facilities with central sterilization capabilities and high procedure throughput.
Mature deployment sits with manual devices. Newer deployment is concentrated in powered systems.
End User:
Procurement authority and reimbursement structures create divergent purchasing behaviors across institutional buyers.
- Hospitals:Integrated delivery networks negotiate master agreements bundling devices, needles, and training services across multi-facility trauma centers. Capital equipment committees evaluate total cost of ownership including competency maintenance and device longevity.
- Emergency Medical Services:Fleet modernization programs in the United States now mandate intraosseous access competency for paramedic certification, pulling devices into ambulance and air-medical units through state-level procurement vehicles.
- Military:NATO trauma care guidelines specify powered devices for tactical combat casualty care, creating institutional demand through defense procurement channels with multi-year stocking agreements.
- Home Care:Limited penetration due to training infrastructure requirements and liability concerns, with occasional deployment in palliative care settings for patients with chronic vascular access challenges.
Volume concentration rests with hospital systems. Steepest expansion trajectory belongs to emergency medical services.
Usage Frequency:
Single versus multiple use economics reshape vendor relationships and supply chain configurations.
- Single Use:Sterile packaged needles eliminate cross-contamination risk and documentation burden. Military stockpiles and pre-hospital deployments favor this category where field sterilization is impractical.
- Multiple Use:Reusable drivers with replaceable needle cartridges spread capital costs across procedures. Hospital emergency departments with predictable trauma volumes optimize procurement through this hybrid model.
- Emergency Use:Devices held in reserve for mass casualty events and disaster response. These require extended shelf-life validation and packaging integrity protocols that add logistics complexity.
- Routine Use:Scheduled replacement cycles in high-volume trauma centers where intraosseous access is standard of care for specific patient presentations.
Procurement standardization favors multiple use in fixed facilities. Emergency use commands premium pricing for sterility assurance.
Application:
Clinical indication determines device specification, operator training intensity, and outcome measurement requirements.
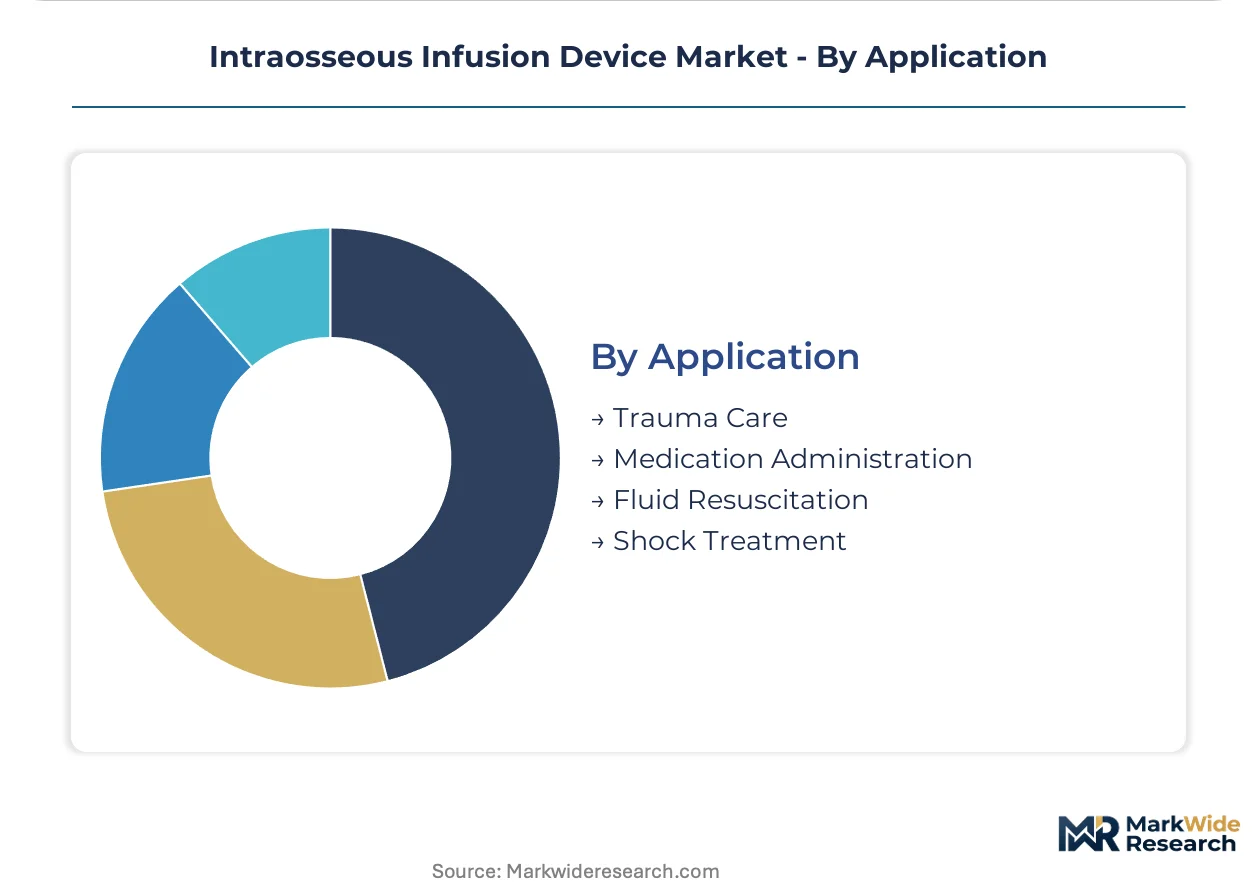
- Trauma Care:Penetrating trauma and polytrauma presentations require rapid vascular access when peripheral veins collapse. Powered devices with integrated depth control dominate Level I trauma center specifications.
- Medication Administration:Emergency drug delivery during cardiac arrest or anaphylaxis where intravenous access fails. This application spans hospital and pre-hospital settings with varying device preferences.
- Fluid Resuscitation:Massive transfusion protocols in hemorrhagic shock. Flow rate requirements influence needle gauge selection and driver torque specifications.
- Shock Treatment:Vasopressor-dependent patients with peripheral vascular collapse. Success metrics center on time-to-access and first-attempt completion rates.
Technology leadership anchors in trauma care. Volume expansion is gaining share fastest in medication administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium needle stock from Sheffield, UK and medical-grade polymer feedstocks from Ludwigshafen, Germany anchor manufacturing geography for intraosseous device production. Trauma care infrastructure maturity and defense procurement scale determine regional demand concentration.
United States
Level I trauma centers in Baltimore and Houston drive powered device specifications through capital equipment committees. The FDA's 510(k) premarket notification pathway accelerates clearance for manufacturers with predicate device histories. Military procurement through Defense Logistics Agency channels concentrates in San Antonio, Texas, where tactical combat casualty care doctrine standardization creates institutional pull-through.
Germany
Automotive supplier networks in Stuttgart and Munich supply precision machining capabilities for battery-powered drill systems. The EU Medical Device Regulation imposes enhanced clinical evidence requirements through notified bodies in Berlin and Cologne. Baden-Württemberg hosts manufacturing clusters serving both domestic hospital systems and export markets across Central Europe.
United Kingdom
NHS England trauma network standardization mandates intraosseous access competency for paramedic certification in London and Manchester. The Medicines and Healthcare products Regulatory Agency oversees post-market surveillance for powered systems deployed in helicopter emergency medical services. Sheffield's advanced manufacturing corridor supplies titanium components for needle fabrication.
Japan
Tokyo and Osaka emergency medical services fleets modernize through Ministry of Health, Labour and Welfare reimbursement alignment for pre-hospital vascular access. The Pharmaceuticals and Medical Devices Agency requires clinical trial data for powered device approvals beyond manual alternatives. Kansai region medical device clusters specialize in miniaturized battery systems for pediatric applications.
Australia
Rural ambulance services across Queensland and Western Australia expand intraosseous deployment where helicopter retrieval distances exceed intravenous access windows. The Therapeutic Goods Administration registers devices through comparable overseas regulator pathways, accelerating entry for FDA-cleared products. Sydney and Melbourne trauma centers specify powered systems for penetrating trauma protocols.
Intraosseous Infusion Device Market Vendor Landscape
Strategic partnerships dominate the current landscape as device manufacturers align with training platform providers and emergency medical services distributors. The vendor base concentrates around three tiers: diversified critical care conglomerates with hospital channel dominance, military-focused specialists with defense procurement relationships, and regional disposable needle fabricators serving price-sensitive segments. Archetypes include integrated delivery network suppliers, battlefield-ready technology developers, and single-use sterile packaging specialists. M&A activity and distribution licensing agreements represent the primary competitive moves reshaping market access.
Among diversified critical care suppliers, Teleflex Incorporated and Becton, Dickinson and Company exemplify the hospital channel archetype through deep trauma center relationships and emergency medical services fleet penetration. PerSys Medical occupies a distinct position as a battlefield-focused developer with NATO defense procurement alignment. Cardinal Health, Inc. represents the distribution scale tier with logistics infrastructure spanning acute care and alternate site channels. These three anchors demonstrate how regulatory predicate histories and training infrastructure investments create competitive moats distinct from pure product differentiation.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| PerSys Medical |
| Teleflex Incorporated |
| Biopsybell S.r.l. |
| Aero Healthcare AU Pty Ltd. |
| Becton, Dickinson and Company |
| SAM Medical |
| PAVmed Inc. |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Backward integration into titanium needle fabrication and battery-powered driver assembly anchors both supply security and pricing power for device manufacturers competing across trauma center procurement channels. This captive production model insulates incumbents from medical-grade polymer feedstock volatility while enabling bundled service offerings that command premium placement.
Pricing Analysis
Warranty and training-service bundling separates powered device vendors from manual needle competitors in hospital capital equipment tenders. Three-tier pricing structure across premium powered systems, standard manual devices, and economy disposable needles reflects FDA 510(k) certification depth and operator training infrastructure inclusion. Pricing pressure stems from integrated delivery networks aggregating procurement across multi-facility systems and demanding volume discounts. Emergency medical services fleets exhibit highest price sensitivity due to per-procedure budget constraints, while military buyers prioritize sterility assurance over unit economics.
Supply Chain Analysis
Freight cost escalation for sterile single-use packaging reshapes inventory positioning for manufacturers serving distributed pre-hospital deployments. Titanium stock draws from Sheffield in the United Kingdom and Stuttgart precision machining clusters in Germany, with medical-grade polymers sourcing from Ludwigshafen chemical corridors. Single-source vulnerability concentrates in battery cell supply for powered drivers, where Korean and Japanese component makers dominate. Distribution runs through hospital purchasing cooperatives and defense logistics channels rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with established FDA predicate device histories and NATO defense procurement relationships, as the EU Medical Device Regulation's enhanced clinical evidence requirements force capital-constrained competitors toward exit.
For Market Incumbents: Anticipate margin compression from hospital purchasing cooperative aggregation by deepening training infrastructure investments that lock in multi-year service contracts. Secure backward integration into titanium needle fabrication to defend against raw material cost volatility. Prioritize CE marking pathway completion for powered systems before MDR review timelines extend further. For New Entrants and Emerging Players: Pediatric-specific needle sizing technology offers the most penetrable wedge against entrenched trauma center suppliers. Target neonatal emergency departments where size-optimized device gaps persist and procurement committees lack incumbent loyalty. Pursue telemedicine-integrated training partnerships as the go-to-market angle to bypass established clinical specialist networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified critical care conglomerates seeking trauma center channel expansion. Five-to-ten year viability hinges on regulatory predicate device libraries rather than pure technology differentiation. Monitor NATO trauma care guideline revisions as the signal for powered device standardization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device history accelerates clearance timelines for powered intraosseous systems. |
| CE Marking Pathway | MDR compliance creates competitive moats through enhanced clinical evidence requirements. |
| Hospital System Partnership | Master service agreements bundle devices, needles, and training across integrated delivery networks. |
| Software Companion Development | Remote procedural coaching platforms enable direct reach to distributed emergency departments. |
| Reimbursement Strategy | Pre-hospital care protocol alignment pulls devices into ambulance and air-medical fleet procurement. |
Methodological Framework
Independent corroboration across emergency medicine clinicians, hospital purchasing committee members, and defense procurement officers underwrites the qualitative findings in this study. Primary fieldwork encompassed biomedical engineers at Level I trauma centers, GPO contracts managers, and paramedic training directors. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, and NATO trauma care guideline repositories. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition anchored the forecast framework across product type, end user, and regional regulatory cluster dimensions. CAGRs derived from procedure volume elasticity to trauma center infrastructure expansion and military doctrine standardization. Powered device penetration curves and manual device replacement cycles fed segment-specific growth trajectories throughout the projection horizon.
Several conditions sit outside the modeled scope, including pandemic-driven emergency department utilization shocks and abrupt defense budget reallocation. Forecasts reflect assumptions about training infrastructure investment continuity and reimbursement alignment stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Interatrial Shunt Devices Market