
 GCC Dental Implants Market | 2026-2036
GCC Dental Implants Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Dental Implants Market Intelligence
Distributor networks across the Gulf is tilting toward direct manufacturer partnerships as clinics seek faster turnaround on specialized titanium fixtures. Institut Straumann AG leverages its Swiss precision manufacturing heritage to sustain premium positioning in Abu Dhabi and Doha. Osstem Implant Co., Ltd. anchors volume penetration through competitive pricing and localized training academies. Zimmer Biomet differentiates via its comprehensive digital dentistry ecosystem spanning surgical planning to final prosthesis.
Dental implants are screw-like medical devices, typically machined from commercially pure titanium or zirconia ceramic, that osseointegrate with jawbone to replace missing tooth roots and support crowns, bridges, or dentures. Endosteal variants dominate procedural volumes across GCC states due to established surgical protocols and predictable outcomes. Titanium material grades command the largest share of current procurement budgets, though zirconia attracts aesthetic-focused practices serving veneer-conscious patients in Dubai and Jeddah. Dental clinics represent the primary end-user channel, with hospital-based oral surgery departments capturing complex zygomatic and transosteal cases requiring general anesthesia.
Saudi Food and Drug Authority registration requirements and UAE Ministry of Health and Prevention import controls shape product entry pathways, favoring manufacturers with established Gulf compliance dossiers. ISO 13485 quality management certification and CE marking serve as baseline credentials for supplier qualification across Kuwait, Bahrain, and Oman markets. Stakeholders must weigh digital workflow investments against conventional implantology training infrastructure as Gulf healthcare systems diversify reimbursement models.
Market Dynamics
Digital surgical planning platforms are compressing treatment timelines across Gulf dental networks, forcing traditional impression-based workflows into obsolescence while elevating capital requirements for clinic-level technology adoption.
Growth Catalysts
- SFDA Registration Standards:The Saudi Food and Drug Authority's tightened medical device dossier requirements are filtering out marginal suppliers and elevating average product quality thresholds across the Kingdom's procurement channels.
- Titanium Fixture Demand:Aging demographics in Riyadh and Dubai are expanding the addressable patient base for endosteal implant procedures, particularly among diabetic and osteoporotic candidates previously excluded from candidacy.
- Medical Tourism Infrastructure:Dubai Health Authority's specialized visa pathways for dental patients are attracting premium-aesthetic cases from Sub-Saharan Africa and South Asia, concentrating high-margin procedural volumes in the emirate's private clinics.
Market Restraints
- Titanium Feedstock Volatility:Aerospace and defense sector competition for commercially pure titanium grades is compressing margins for implant manufacturers dependent on spot-market material sourcing.
- MOHAP Import Licensing:UAE Ministry of Health and Prevention's extended device registration timelines create working capital strain for distributors without established Gulf compliance infrastructure.
- Zirconia Brittleness Limitations:Ceramic implant fracture rates in posterior molar applications restrict aesthetic material adoption to anterior and premolar zones, capping addressable procedural share.
Strategic Opportunities
- Oman and Bahrain Penetration:Underdeveloped distributor networks in Muscat and Manama create first-mover advantages for manufacturers willing to build localized training academies and direct service capabilities.
- Same-Day Prosthesis Workflows:Chairside milling and 3D printing convergence enables single-visit implant restoration, compressing traditional laboratory outsourcing and capturing premium patient willingness-to-pay.
- Digital Workflow Bundling:Integrated surgical planning-to-prosthesis systems allow manufacturers to displace standalone component suppliers and capture recurring software subscription revenue streams.
Industry Challenges
- Prosthodontist Training Bottlenecks:Gulf universities graduate insufficient implantology specialists relative to clinic expansion rates, forcing private providers to recruit from European and South Asian labor pools.
- ISO 13485 Certification Timelines:Quality management system audits for new market entrants average 14-18 months, delaying product launch windows and accelerating competitive disadvantage against incumbent dossier holders.
- Legacy PMS Integration Friction:Digital implant planning software requires costly practice management system overhauls, creating adoption resistance among established clinics with sunk investments in conventional infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Dental Implants Market |
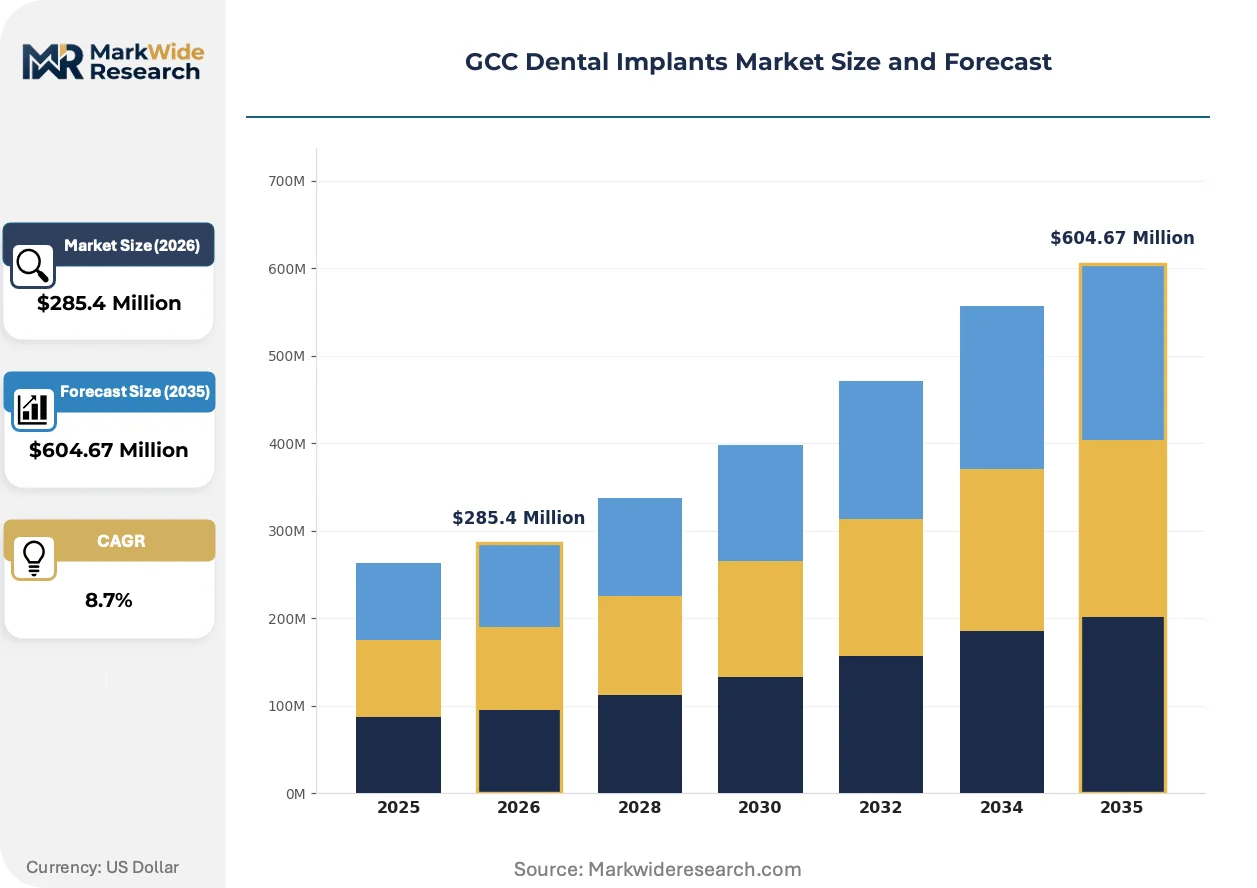
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosteal, Subperiosteal, Zygomatic, Transosteal Material: Titanium, Zirconia, Stainless Steel, Polymers End User: Dental Clinics, Hospitals, Research Institutions, Aesthetic Centers Distribution Channel: Direct Sales, Retail Pharmacies, Online Sales, Wholesalers |
| Companies Covered | Envista Holdings Corporation, Dentium Co., Ltd., Institut Straumann AG, BioHorizons, Nobel Biocare, Dentsply Sirona, Osstem Implant Co., Ltd., Kyocera Medical Corp, Zimmer Biomet, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Dental Implants Market Strategic Shifts & Innovations
Convergence between additive manufacturing and real-time surgical navigation is redefining procedural economics across Gulf dental networks, compressing laboratory intermediation while elevating precision thresholds for acceptable clinical outcomes.
Guided surgery templates fabricated through selective laser sintering of medical-grade polymers are replacing freehand osteotomy protocols in high-volume Saudi and Emirati practices. Specialist oral surgery centers in Jeddah and Abu Dhabi are adopting these systems at accelerating rates, reducing chair time per implant placement by standardizing drill trajectory and depth. This manufacturing precision is hybridizing with conventional tactile surgical skill, creating a bifurcated market between technology-enabled premium providers and cost-pressured conventional operators.
SFDA's 2023 medical device traceability mandates require unique device identifiers on all implantable fixtures sold in Saudi Arabia, extending serialization requirements from pharmaceuticals into the dental device category. Manufacturers must now maintain lot-level tracking databases accessible to regulator audits, increasing compliance overhead but creating competitive moats against gray-market imports. Kuwait's national pharmaceutical regulator is drafting parallel requirements, suggesting Gulf-wide harmonization toward European MDR-equivalent standards.
Clinic procurement committees in Dubai's medical tourism corridor are consolidating vendor relationships around full-stack digital dentistry providers, displacing multi-supplier component sourcing. Group purchasing organizations affiliated with hospital networks in Riyadh and Doha are negotiating enterprise software licenses bundled with hardware commitments, shifting supplier selection criteria from unit pricing toward total workflow integration. This vendor consolidation is most visible among multi-location dental chains seeking standardized protocols across their clinic footprints.
GCC Dental Implants Market Segmentation
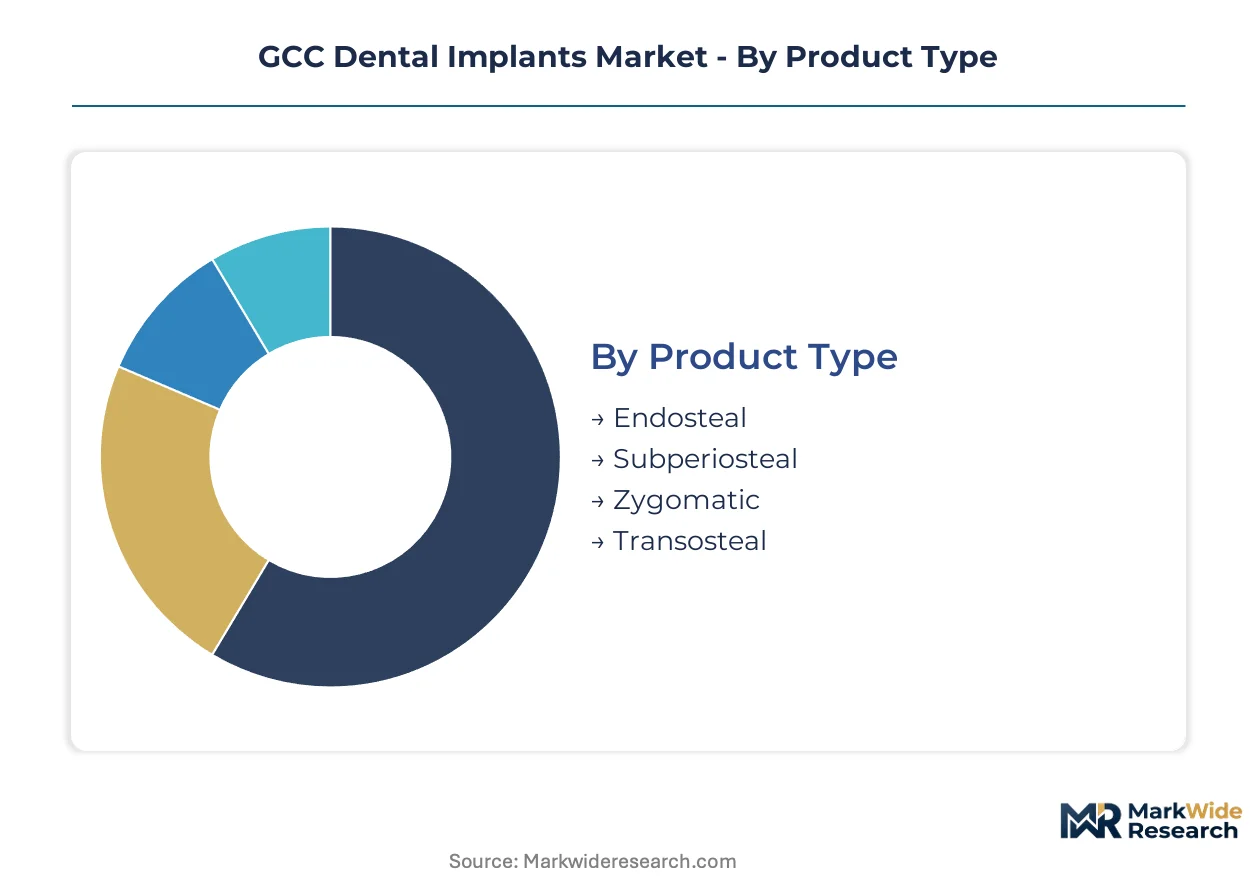
Implant procurement patterns across Gulf states diverge sharply by clinical setting and patient profile, requiring manufacturers to calibrate service intensity and technical support depth to each channel's operational rhythm. Segmentation discipline separates volume-driven standardized fixture suppliers from premium-positioned full-arch restoration specialists competing for Dubai's medical tourism corridor and Riyadh's private hospital networks.
Product Type:
After-sales service intensity varies dramatically across implant categories, with complex zygomatic and transosteal systems demanding surgical field support that simpler endosteal fixtures do not require.
- Endosteal:Screw-shaped fixtures inserted directly into jawbone constitute the procedural standard across Saudi and Emirati dental networks. Demand concentrates in Dubai's aesthetic-focused clinics and Riyadh's diabetes-prevalent patient base, where bone density challenges favor threaded titanium designs with aggressive surface topography.
- Zygomatic:Extended-length implants anchor in cheekbone rather than maxilla for severe atrophy cases. Abu Dhabi's oral surgery centers and Jeddah's hospital-based departments drive adoption, though general anesthesia requirements restrict placement to hospital settings with anesthesiology coverage.
- Subperiosteal:Custom-cast metal frameworks sit atop bone beneath periosteum for patients rejecting bone grafting. Kuwaiti and Bahraini clinics with limited surgical infrastructure favor this reduced-invasiveness alternative.
- Transosteal:Penetrating fixtures passing through mandible address extreme resorption. Complex placement protocols relegate this variant to Doha and Muscat's specialist referral centers with maxillofacial surgery capabilities.
Endosteal configurations hold the largest share; momentum sits with zygomatic systems as Gulf clinics expand full-arch restoration services for edentulous medical tourism patients.
Material:
Cost tier stratification separates premium biocompatible metals from economy alternatives, with reimbursement eligibility and aesthetic patient willingness-to-pay determining material selection across clinic types.
- Titanium:Commercially pure grades and Ti-6Al-4V alloys dominate Gulf procurement volumes due to proven osseointegration kinetics. Saudi Food and Drug Authority registration dossiers overwhelmingly feature titanium substrates, reflecting established clinical evidence requirements.
- Zirconia:Ceramic formulations appeal to Dubai and Jeddah's veneer-conscious patient segments demanding metal-free aesthetics. Brittleness constraints in posterior applications limit placement to anterior zones, capping volume expansion.
- Stainless Steel:Lower-cost alloys persist in Bahrain and Oman's price-sensitive public health procurement, though corrosion concerns restrict long-term placement acceptance.
- Polymers:Experimental resorbable and PEEK-based fixtures occupy niche research applications at Doha's academic medical centers, lacking SFDA approval pathways for commercial deployment.
Titanium commands institutional procurement; zirconia is climbing the fastest among private aesthetic practices serving premium patient segments.
End User:
Customer type determines technical support requirements, with hospital oral surgery departments demanding 24-hour surgical field coverage that standalone clinics do not require.
- Dental Clinics:Independent and chain-affiliated practices across Dubai and Riyadh generate the majority of implant placements, driving demand for chairside digital workflow integration and same-day provisional restoration capabilities.
- Hospitals:General and specialty hospitals in Abu Dhabi and Jeddah handle complex zygomatic cases, trauma reconstruction, and immunocompromised patients requiring inpatient monitoring. Anesthesiology integration elevates capital and staffing thresholds.
- Research Institutions:Academic medical centers in Doha and Riyadh conduct clinical trials for novel surface treatments and guided surgery protocols, generating limited commercial volume but outsized influence on future standards.
- Aesthetic Centers:Cosmetic surgery clinics in Dubai's medical tourism corridor bundle implant placement with facial rejuvenation procedures, demanding premium prosthetic outcomes and accelerated healing protocols.
Dental clinics represent the dominant channel; aesthetic centers are gaining share fastest as Dubai Health Authority expands specialized visa pathways for dental tourists.
Distribution Channel:
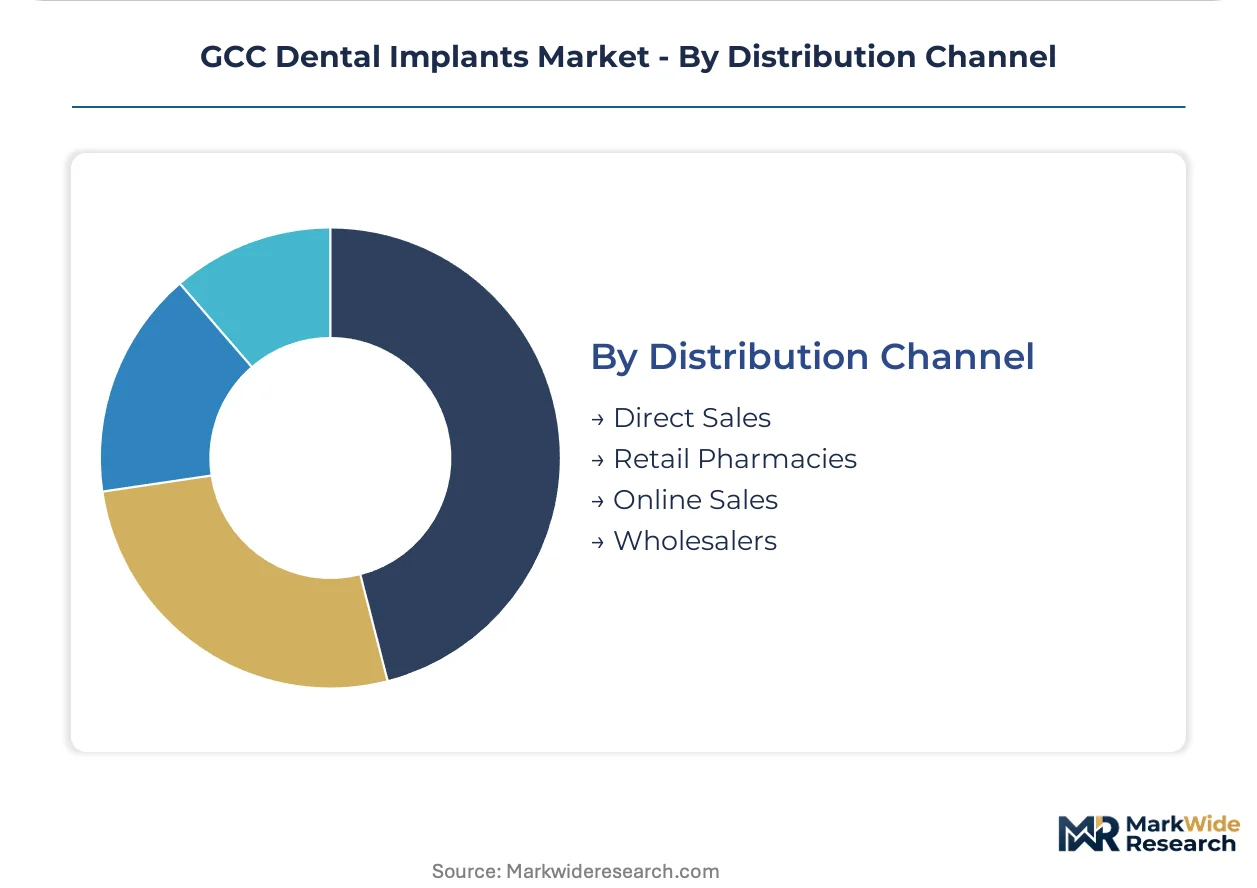
Supply concentration around direct manufacturer relationships is displacing traditional wholesale intermediation as clinics seek faster technical response and inventory optimization.
- Direct Sales:Manufacturer representatives serve high-volume Saudi and Emirati clinic chains with consignment inventory, surgical planning software licensing, and specialist training academies. SFDA traceability mandates favor direct relationships with established compliance infrastructure.
- Retail Pharmacies:Community pharmacy networks in Kuwait and Oman stock basic implant components and prosthetic supplies, though surgical fixture placement remains outside their scope.
- Online Sales:E-procurement platforms gain traction among smaller Bahraini and Omani clinics for consumables and replacement components, constrained by temperature-controlled logistics requirements for biological surface treatments.
- Wholesalers:Traditional distributors retain relevance in fragmented markets lacking manufacturer direct presence, though margin compression and extended MOHAP registration timelines strain working capital.
Direct sales channels hold the largest share; online platforms are expanding most quickly among independent clinics seeking procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dubai's medical tourism corridor while Riyadh's institutional procurement channels compress margins through volume aggregation. This asymmetry shapes manufacturer channel strategy across the Gulf Cooperation Council states.
Saudi Arabia
Aging demographics in Riyadh and Jeddah expand the addressable patient base for endosteal procedures, particularly among diabetic candidates. The Saudi Food and Drug Authority's 2023 medical device traceability mandates require unique device identifiers on all implantable fixtures. Riyadh's private healthcare zone attracts premium-positioned manufacturers establishing direct sales infrastructure.
United Arab Emirates
Dubai Health Authority's specialized visa pathways for dental patients attract premium-aesthetic cases from Sub-Saharan Africa and South Asia. The UAE Ministry of Health and Prevention's extended device registration timelines create working capital strain for distributors without established Gulf compliance infrastructure. Dubai's medical tourism corridor concentrates high-margin procedural volumes in private clinics bundling implant placement with facial rejuvenation.
Kuwait
Clinics with limited surgical infrastructure favor subperiosteal frameworks as reduced-invasiveness alternatives to bone grafting. The national pharmaceutical regulator is drafting parallel traceability requirements to Saudi Arabia's SFDA mandates. Kuwait City's private dental networks consolidate vendor relationships around full-stack digital dentistry providers.
Qatar
Academic medical centers in Doha conduct clinical trials for novel surface treatments and guided surgery protocols. Institutional procurement through hospital networks favors enterprise software licenses bundled with hardware commitments. Doha's specialist referral centers with maxillofacial surgery capabilities handle complex transosteal placements.
Oman
Underdeveloped distributor networks in Muscat create first-mover advantages for manufacturers building localized training academies. Community pharmacy networks stock basic implant components though surgical fixture placement remains outside their scope. Muscat's independent clinics increasingly turn to e-procurement platforms for consumables and replacement components.
GCC Dental Implants Market Key Industry Players
Premium-positioned Swiss manufacturers and volume-driven Korean suppliers split the market along price-performance vectors. Strategic archetypes include precision-engineering heritage players competing on clinical evidence depth, scale-driven fabricators penetrating through competitive pricing and training infrastructure, and integrated digital workflow providers capturing recurring software revenue. Dominant competitive moves encompass direct manufacturer partnerships displacing wholesale intermediation and digital surgical planning platforms compressing traditional impression-based workflows into obsolescence.
Within the premium heritage tier, Institut Straumann AG and Nobel Biocare exemplify precision-manufacturing positioning sustained through clinical evidence portfolios. Osstem Implant Co., Ltd. anchors the volume-penetration archetype through localized training academies and competitive fixture pricing. Zimmer Biomet occupies the integrated-systems position, bundling surgical planning software with hardware commitments to capture enterprise procurement decisions.
| Leading Market Players |
|---|
| Envista Holdings Corporation |
| Dentium Co., Ltd. |
| Institut Straumann AG |
| BioHorizons |
| Nobel Biocare |
| Dentsply Sirona |
| Osstem Implant Co., Ltd. |
| Kyocera Medical Corp |
| Zimmer Biomet |
| Others |
Cost & Logistics Intelligence
Swiss and South Korean precision manufacturers anchor upstream titanium fixture supply, concentrating margin capture in digital workflow bundling and surgical training academies rather than commodity hardware. This upstream concentration funnels pricing power toward integrated system providers while compressing standalone component suppliers into cost-competitive tiers.
Pricing Analysis
The customization-premium spread separates chairside-milled provisional restorations from standard off-the-shelf titanium fixtures. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13485 certification depth and surface treatment complexity. Price differentiation hinges on CE marking tier and after-sales surgical field support intensity. Cost compression in economy-grade titanium fixtures is intensifying because aerospace sector competition for commercially pure grades elevates feedstock spot-market exposure. Public health procurement channels across Bahrain and Oman exhibit highest price sensitivity; Dubai's medical tourism corridor demonstrates lowest sensitivity due to bundled aesthetic outcome guarantees.
Supply Chain Analysis
Contract manufacturing concentration rests with Swiss precision machining houses and Korean vertically integrated implant fabricators holding dedicated medical-grade titanium capacity. Geographic supply concentration draws from Switzerland, South Korea, and Germany for precision-machined fixtures; China and Japan for zirconia ceramic blanks; and the United States for surgical planning software kernels. Raw material dependencies hinge on commercially pure titanium sponge, medical-grade zirconia powder, and biocompatible polymer resins for guided surgery templates. Single-source vulnerability characterizes aerospace-qualified titanium grade supply, with defense sector offtake precedence creating allocation risk. Distribution runs through direct manufacturer partnerships with Saudi and Emirati clinic chains, displacing traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring software subscription revenue and surgical training certification programs expand faster than hardware unit sales. The attach rate for digital planning platforms now exceeds standalone fixture procurement in Dubai's premium clinic segment.
For Market Incumbents: Harden compliance infrastructure against SFDA traceability mandates by investing in lot-level serialization databases accessible to regulator audits. Deepen backward integration into titanium feedstock through long-term offtake agreements with aerospace-qualified mills, insulating margin structures from spot-market volatility. Defensive priority centers on neutralizing Korean volume players through differentiated chairside workflow integration that commoditizes standalone fixture pricing.
For New Entrants and Emerging Players: Muscat and Manama's underdeveloped distributor networks offer first-mover positioning for manufacturers willing to build localized training academies and direct service capabilities. The most penetrable segment sits in subperiosteal frameworks for Kuwaiti and Bahraini clinics lacking bone grafting infrastructure. Go-to-market angle should emphasize reduced-invasiveness protocols and rapid surgical training certification against incumbent complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward digital workflow integrators with established Gulf compliance dossiers and recurring software revenue streams. Long-term viability over the next decade rests on capturing enterprise procurement decisions at multi-location dental chains standardizing protocols across clinic footprints. Acquisition target archetype encompasses guided surgery template manufacturers with selective laser sintering capabilities and existing SFDA registration pathways. Signal to monitor: consolidation velocity among Dubai's medical tourism corridor clinics as group purchasing organizations negotiate bundled enterprise licenses.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Traceability Compliance Investment | Lot-level serialization databases create competitive moats against gray-market imports in Saudi Arabia. |
| Localized Training Academy Buildout | Surgical certification programs in Muscat and Manama accelerate market penetration ahead of distributor consolidation. |
| Digital Workflow Bundle Licensing | Enterprise software licenses with hardware commitments displace standalone component suppliers in Riyadh clinic chains. |
| Chairside Milling Capability Integration | Same-day provisional restoration captures premium willingness-to-pay in Dubai's aesthetic-focused practices. |
| Titanium Feedstock Backward Integration | Long-term aerospace-grade mill offtake agreements insulate margins from defense sector allocation competition. |
Research Approach
The analysis maps endosteal, zygomatic, and subperiosteal implant categories, each validated through prosthodontists, dental clinic procurement managers, biomedical engineers, and GPO contracts managers across Saudi Arabia, UAE, Kuwait, Qatar, Bahrain, and Oman. Primary interviews with oral surgery department heads and distributor network principals combined with secondary validation from SFDA registration databases, MOHAP import licensing records, hospital procurement systems, and ISO 13485 certification registries. Bottom-up fixture shipment aggregation triangulates against top-down healthcare expenditure modeling across the analysis window.
Assumptions held constant include SFDA traceability mandate enforcement timelines, MOHAP registration processing durations, and titanium feedstock allocation priorities between medical and aerospace sectors. Segmentation dimensions modeled span product type, material grade, end-user channel, and distribution pathway across the projection horizon. CAGRs derive from procedural volume elasticity to aging demographic penetration, medical tourism visa pathway expansion, and digital workflow adoption curves. Industry-specific forecast inputs incorporate diabetic patient candidacy expansion rates and zirconia ceramic brittleness constraints in posterior applications.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Korean volume manufacturers or accelerated CE marking harmonization by Kuwait's national pharmaceutical regulator would shift outcomes. Specific risk factors encompass titanium feedstock spot-price spikes, extended MOHAP registration delays, and prosthodontist training bottlenecks constraining clinic expansion. Quarterly review of SFDA audit disclosure patterns, Dubai Health Authority visa issuance volumes, and aerospace titanium contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Dental Handpieces Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Dental Impression System Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Implants Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Dental Sealants Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental CAD Market