
 Middle East and Africa Dental Lab Market | 2026-2036
Middle East and Africa Dental Lab Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dental Lab Market Foresight
Cosmetic dentistry demand among private clinic networks is recalibrating procurement patterns across the Middle East and Africa. Envista leverages its implant-abutment portfolio to anchor premium positioning in Gulf Cooperation Council markets. Dentsply Sirona sustains technology leadership through integrated CAD/CAM scanner-milling ecosystems. Henry Schein, Inc. competes on distribution density, particularly in South Africa's metropolitan dental corridors.
A dental lab manufactures custom oral prosthetics and restorative devices from biocompatible materials using precision casting, milling, or additive processes to achieve sub-50-micron marginal fit tolerances for permanent patient installation. Crowns and bridges occupy the largest volume share due to high replacement rates among aging populations, while implants represent the fastest-expanding margin pool as osseointegration success rates improve. CAD/CAM technology dominates capital investment flows, though 3D printing for resin pattern production is displacing conventional wax casting in cost-sensitive segments.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority frameworks govern biocompatibility certification and import registration for dental alloys and ceramics, extending product approval timelines for non-domestic manufacturers. CE marking requirements under EU MDR create parallel compliance burdens for European-sourced equipment entering Middle Eastern markets. Stakeholders must monitor regulatory harmonization between Gulf Standardization Organization members and national health authorities to anticipate market access shifts.
Market Dynamics
Digital workflow migration is compressing production cycles across Middle East and Africa dental labs, with chairside CAD/CAM systems eliminating conventional impression-to-cast logistics and forcing capital reallocation toward milling centers and intraoral scanner networks.
Growth Catalysts
- Saudi Health Privatization:Crown and bridge outsourcing demand concentrates in Riyadh and Jeddah as public hospitals divest fabrication capacity to private operators.
- CAD/CAM Chairside Systems:Digital impression capture replaces alginate and silicone methods, cutting turnaround times from weeks to same-day delivery for single-unit restorations.
- Gulf Cooperation Council Cosmetic Dentistry:Private clinic chains expand in-house lab capabilities to capture premium aesthetic cases previously referred to independent laboratories.
Market Restraints
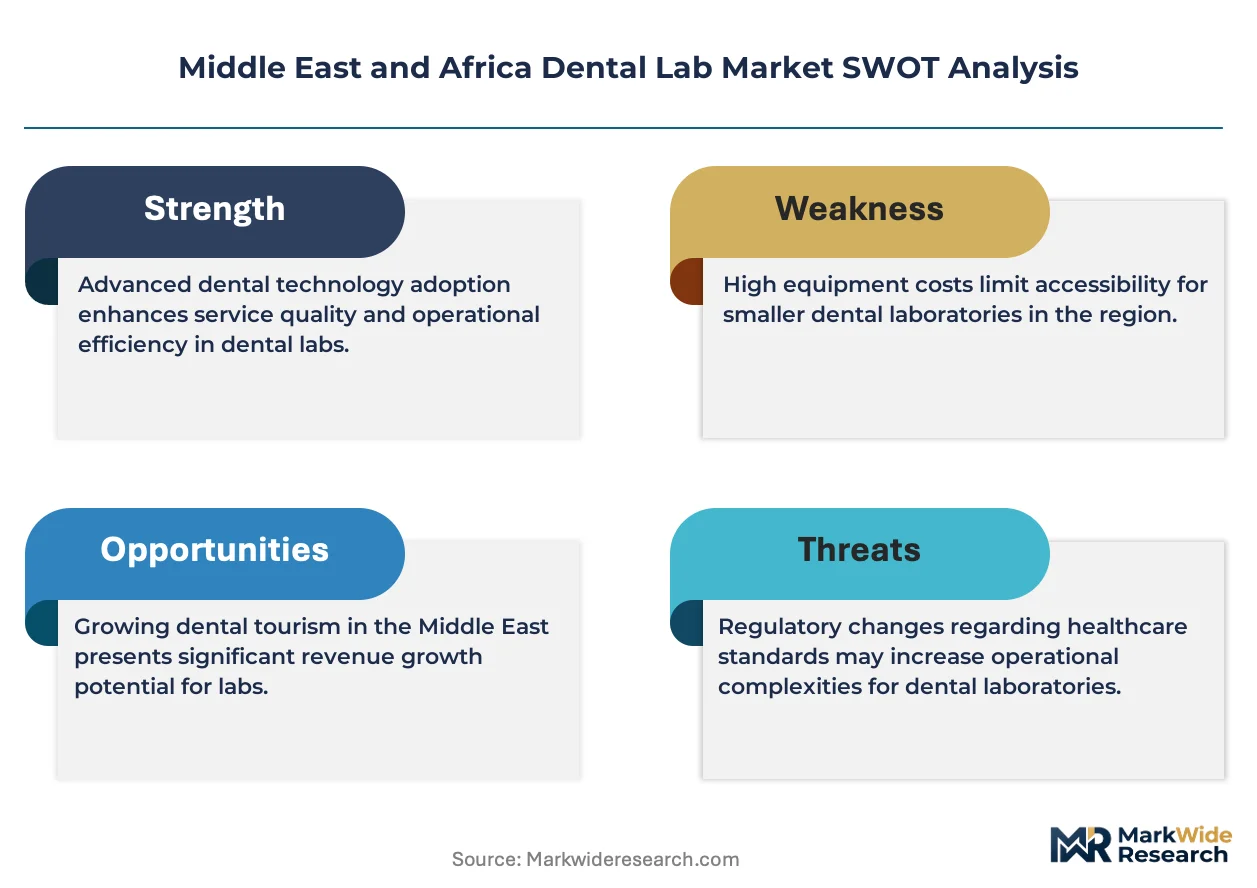
- Biocompatibility Certification Delays:Saudi Food and Drug Authority and South African Health Products Regulatory Authority extend approval timelines for imported dental alloys and zirconia blanks.
- Capital Equipment Concentration:High-performance milling machines and sintering furnaces concentrate supply among German and Japanese original equipment manufacturers, creating import dependency.
- CE Marking Parallel Burden:EU MDR requirements create redundant compliance costs for European-sourced equipment entering Middle Eastern markets through distribution channels.
Strategic Opportunities
- Egypt and Morocco Lab Services:Underpenetrated North African markets present first-mover potential for outsourced crown fabrication serving uninsured patient populations.
- 3D Printing Resin Pattern Production:Additive manufacturing converges with conventional casting workflows to displace wax pattern labor in cost-sensitive removable prosthetic segments.
- Tele-dental Lab Networks:Digital file transmission enables remote design centers in South Africa to serve satellite clinics across sub-Saharan Africa without physical logistics infrastructure.
Industry Challenges
- CAD/CAM Technician Scarcity:Digital design software proficiency lags equipment installation rates, creating bottlenecks in file optimization and milling parameter calibration.
- Legacy Equipment Stranding:Conventional porcelain-fused-to-metal ovens and vacuum mixers face accelerated obsolescence as clinics bypass lab networks entirely for chairside production.
- Osseointegration Case Complexity:Implant restoration workflows demand cross-functional coordination between surgeons, restorative dentists, and lab technicians that existing training pipelines fail to address.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dental Lab Market |
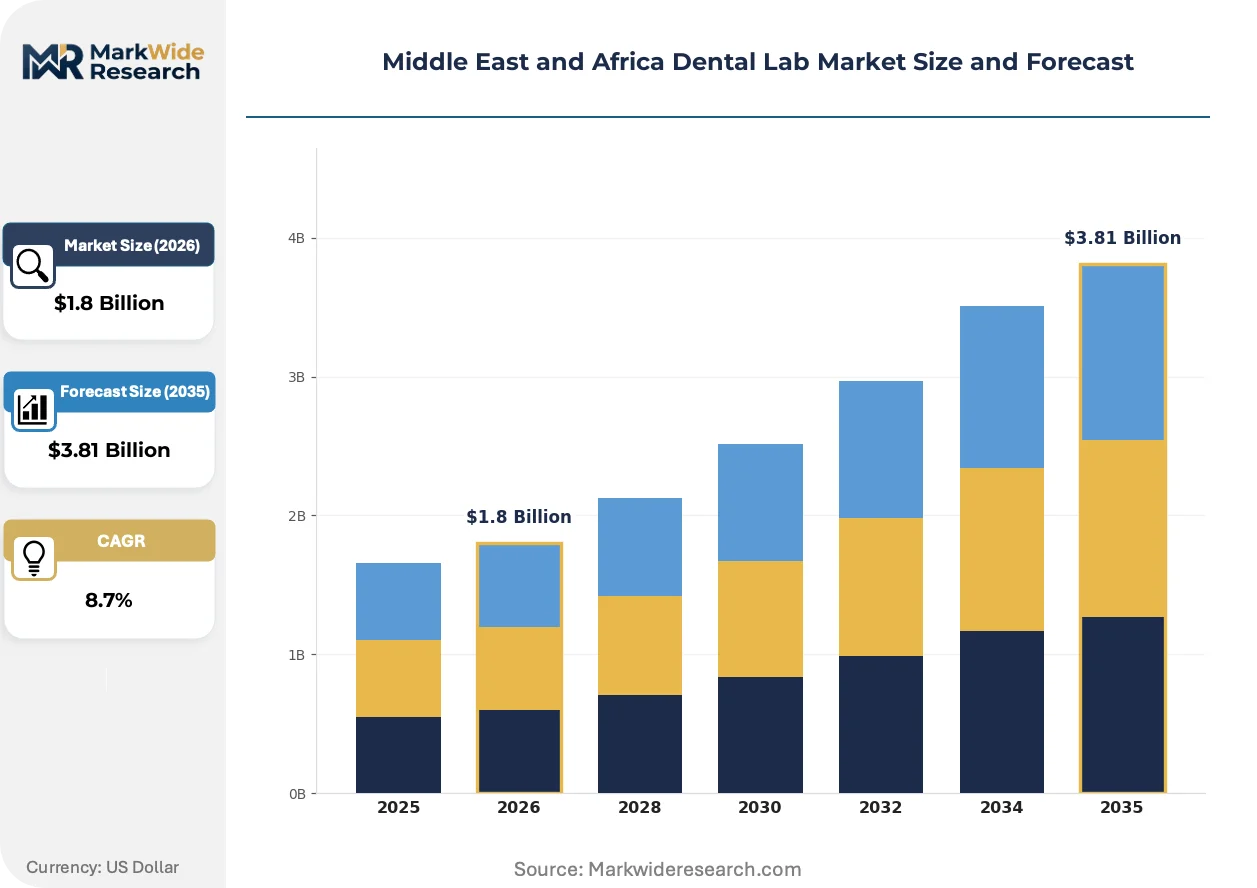
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bridges, Crowns, Dentures, Implants Technology: CAD/CAM, 3D Printing, Casting, Milling End User: Dental Clinics, Hospitals, Orthodontics, Dental Schools Material: Metals, Ceramics, Composites, Acrylics |
| Companies Covered | Envista, Planmeca OY, Dentsply Sirona, Zimvie Inc., Carestream Health, Institut Straumann AG, 3M, Ultradent Products Inc., Henry Schein, Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dental Lab Market Shifts & Advancements
Workflow digitization is reconfiguring competitive advantage around speed-to-delivery and marginal fit precision rather than geographic proximity to dental clinics. Three developments are compressing traditional lab-clinic relationships.
Intraoral scanning is overtaking conventional impression methods across Gulf Cooperation Council private practice networks. Dubai and Abu Dhabi clinic chains deploy chairside scanners to eliminate physical model shipping, compressing crown delivery from ten days to forty-eight hours. This technology is overtaking regional logistics-dependent business models and consolidating fabrication volume toward centralized milling centers with multi-axis capabilities.
Saudi Food and Drug Authority implemented stricter biocompatibility documentation requirements for imported dental ceramics and base metal alloys in 2023. Manufacturers now submit extended cytotoxicity and sensitization test data, delaying product registration by four to six months. European suppliers with existing CE MDR technical files adapt faster than Asian competitors lacking parallel documentation systems.
Private clinic procurement now favors single-source digital ecosystem contracts over multi-vendor component sourcing. Henry Schein and Dentsply Sirona bundle scanner-milling-software packages that lock laboratories into proprietary file formats and consumable streams. This concentration is most visible in South Africa's metropolitan corridors where dental group practices standardize equipment fleets across twenty-plus locations.
Middle East and Africa Dental Lab Market Segmentation
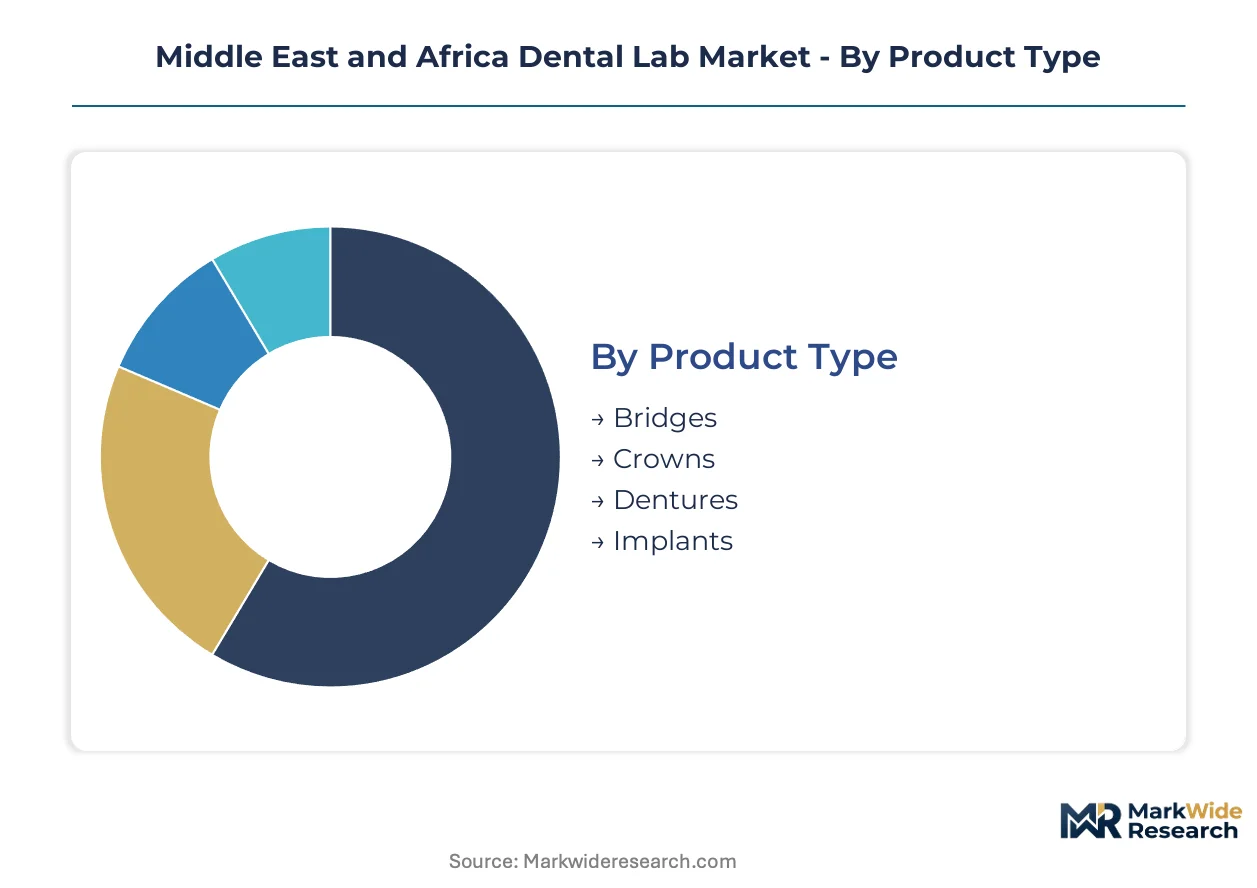
Dental lab market segmentation reveals distinct procurement patterns across product categories, with material selection and fabrication technology determining margin structures and turnaround capabilities. Understanding these divides clarifies where capital investment concentrates and which segments face displacement from chairside digital systems.
Product Type:
Standalone prosthetics dominate high-volume fabrication workflows, while implant-abutment assemblies require deeper integration with surgical planning software and restorative protocols.
- Crowns:Single-unit restorations fabricated from zirconia or lithium disilicate blanks achieve sub-50-micron marginal fit tolerances through CAD/CAM milling. Demand concentrates in Saudi Arabia's privatizing hospital networks and South African metropolitan clinic chains where same-day delivery contracts are displacing traditional two-week turnaround models.
- Bridges:Multi-unit fixed prosthetics span edentulous spaces using either monolithic zirconia or porcelain-fused-to-metal substructures. Gulf Cooperation Council cosmetic dentistry networks drive specification toward high-translucency ceramics for anterior cases, though posterior bridges in cost-sensitive Egyptian and Moroccan markets retain metal-ceramic hybrid designs.
- Dentures:Removable prosthetics rely on conventional acrylic processing or digital denture workflows using milled polymethyl methacrylate bases.
- Implants:Titanium or zirconia abutments with custom screw-retained crowns command premium positioning in Riyadh and Jeddah private clinics.
Crowns lead volumes today; implants are gaining share fastest.
Technology:
Cost tiers separate capital-intensive digital systems from labor-dependent conventional methods, with hybrid workflows emerging at mid-market price points.
- CAD/CAM:Computer-aided design and manufacturing integrates intraoral scanning with five-axis milling for same-day crown delivery. South Africa's dental corridor clinic networks standardize on closed-system scanner-miller bundles that lock laboratories into proprietary consumable streams.
- Milling:Subtractive machining of zirconia, titanium, and polymeric blanks produces final restorations or pre-sintered frameworks requiring downstream sintering or porcelain application.
- 3D Printing:Vat photopolymerization and material jetting generate resin patterns for investment casting or definitive flexible denture bases.
- Casting:Traditional lost-wax techniques using noble or base metal alloys persist for removable partial denture frameworks in markets with limited digital infrastructure.
CAD/CAM leads volumes today; 3D printing is gaining share fastest.
End User:
Customer type determines order volume profiles and technical specification complexity, with institutional buyers driving standardization and private operators demanding customization.
- Dental Clinics:Private practice networks across Dubai and Abu Dhabi deploy chairside systems that bypass external laboratories for single-unit cases while outsourcing complex implant restorations.
- Hospitals:Saudi public hospital divestment of in-house fabrication capacity concentrates outsourced crown and bridge demand with private dental laboratory operators in Riyadh and Jeddah.
- Orthodontics:Clear aligner production and indirect bonding trays require specialized thermoforming and 3D printing capabilities distinct from restorative workflows.
- Dental Schools:Training institutions maintain conventional equipment fleets for pedagogical completeness despite clinical market digitization.
Dental clinics lead volumes today; hospitals are gaining share fastest.
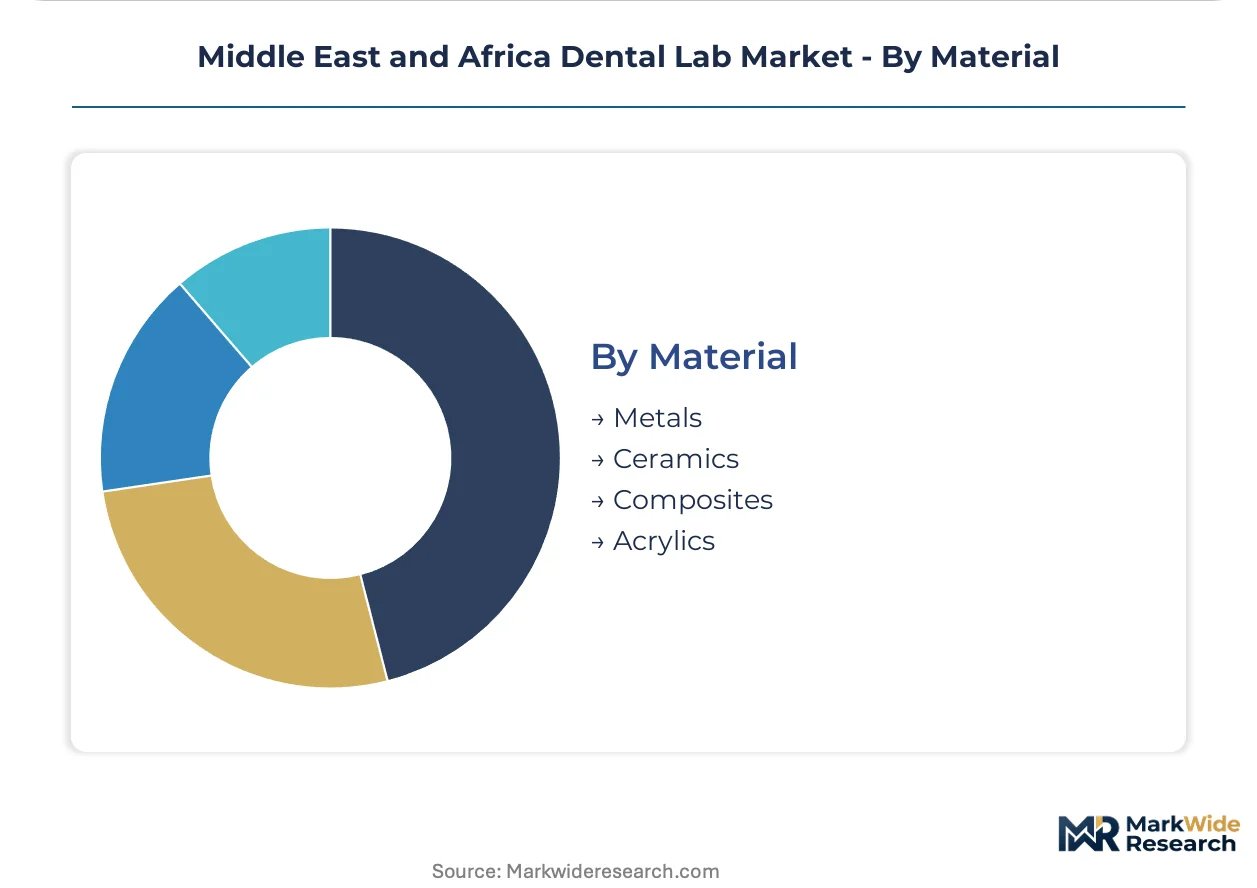
Material:
Margin structures diverge sharply between commodity acrylics and premium ceramics, with biocompatibility certification timelines creating supply bottlenecks for imported advanced materials.
- Ceramics:Zirconia and lithium disilicate deliver aesthetic translucency with flexural strength exceeding 900 MPa for posterior applications. SFDA extended cytotoxicity documentation requirements delay registration of new ceramic formulations by four to six months.
- Metals:Cobalt-chromium and nickel-chromium alloys for removable partial denture frameworks face declining demand in Gulf markets while retaining volume in North African cost-sensitive segments.
- Composites:Fiber-reinforced materials and hybrid ceramics occupy niche indications for temporary restorations and implant provisionalization.
- Acrylics:Polymethyl methacrylate remains standard for denture bases and orthodontic appliances despite digital denture displacement in premium segments.
Ceramics lead volumes today; composites are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dental lab investment toward jurisdictions where biocompatibility certification timelines and import duty structures create cost-of-compliance advantages. Manufacturers locate milling centers and design operations across the Middle East and Africa to exploit gaps between Saudi Food and Drug Authority processing periods and South African Health Products Regulatory Authority documentation requirements.
Saudi Arabia
Crown and bridge outsourcing demand concentrates in Riyadh and Jeddah as public hospitals divest fabrication capacity under health privatization mandates. Saudi Food and Drug Authority extended cytotoxicity documentation requirements for imported dental ceramics in 2023, delaying product registration by four to six months. Riyadh-based private laboratory operators capture volume from former hospital in-house units.
United Arab Emirates
Dubai and Abu Dhabi private clinic chains deploy chairside CAD/CAM systems that eliminate physical model shipping and compress delivery from ten days to forty-eight hours. MOHAP governs medical device registration with streamlined pathways for CE-marked equipment. Dubai Healthcare City clusters milling centers serving GCC cosmetic dentistry networks with multi-axis capabilities.
South Africa
Metropolitan dental corridors in Johannesburg and Cape Town drive procurement standardization across dental group practices with twenty-plus locations. South African Health Products Regulatory Authority extends approval timelines for imported dental alloys and zirconia blanks. Cape Town hosts tele-dental design centers transmitting files to satellite clinics across sub-Saharan Africa.
Egypt
Cairo and Alexandria present first-mover potential for outsourced crown fabrication serving uninsured patient populations with cost-sensitive metal-ceramic hybrid designs. The country's national pharmaceutical regulator maintains evolving frameworks for dental device import registration. Nile Delta laboratory clusters retain conventional casting workflows for removable partial denture frameworks.
Morocco
Casablanca and Rabat dental laboratories serve underpenetrated North African markets with acrylic denture processing and digital denture workflow adoption. National health authorities align biocompatibility certification with CE marking requirements under parallel compliance structures. Tangier-Med port logistics support ceramic blank importation for zirconia milling operations.
Middle East and Africa Dental Lab Market Competitive Landscape
Technology licensing dominates the current landscape as equipment manufacturers bundle scanner-milling-software packages to lock laboratories into proprietary consumable streams. The vendor base separates into three tiers: multinational dental conglomerates with integrated CAD/CAM ecosystems, regional distribution specialists with dense metropolitan coverage, and independent milling centers competing on turnaround speed. Two strategic archetypes anchor competitive positioning: closed-system platform providers and open-architecture component suppliers. M&A activity concentrates on digital workflow software assets, while geographic expansion targets underpenetrated North African markets.
Among Switzerland-based implant specialists, Institut Straumann AG exemplifies the premium-tier archetype through its surgical planning software integration. Dentsply Sirona occupies a position within the closed-system platform tier, representing bundled scanner-miller offerings that standardize equipment fleets across clinic networks. Henry Schein, Inc. sits within the distribution-density archetype, anchoring competitive positioning through metropolitan corridor penetration in South Africa and the Gulf states.
| Leading Market Players |
|---|
| Envista |
| Planmeca OY |
| Dentsply Sirona |
| Zimvie Inc. |
| Carestream Health |
| Institut Straumann AG |
| 3M |
| Ultradent Products Inc. |
| Henry Schein, Inc. |
| Others |
Supply & Pricing Matrix
CAD/CAM chairside system adoption across Gulf Cooperation Council private clinics is simultaneously collapsing traditional lab-clinic logistics costs and concentrating fabrication volume toward centralized milling centers with multi-axis capabilities. This technology shift reallocates margin capture from geographic proximity premiums toward digital file transmission economies and consumable lock-in contracts.
Pricing Analysis
Distributor margins on European-sourced milling equipment and zirconia blanks absorb 15-25 percent of final delivered cost in Saudi Arabia and South Africa. Pricing stratifies across premium zirconia systems with closed consumable streams, standard open-architecture CAD/CAM platforms, and economy-tier conventional casting workflows for North African markets. Cost compression in economy segments is intensifying because Egyptian and Moroccan laboratories retain wax-pattern labor rather than investing in chairside infrastructure. Uninsured patient populations in Cairo and Alexandria exhibit highest price sensitivity, while Riyadh private clinic chains prioritize same-day delivery premiums over unit cost.
Supply Chain Analysis
Saudi Food and Drug Authority domestic-content documentation requirements for imported dental alloys are reshaping sourcing patterns toward regional milling centers with established SFDA technical files. German and Japanese original equipment manufacturers supply high-performance five-axis milling machines and sintering furnaces, while Chinese ceramic blank producers feed cost-sensitive segments. Single-source vulnerability concentrates in cobalt-chromium alloy supply chains subject to extended SFDA cytotoxicity review timelines. Distribution runs through Henry Schein and Dentsply Sirona bundled ecosystem contracts that lock laboratories into proprietary scanner-miller-software packages across South Africa's metropolitan dental corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where four-to-six-month SFDA registration delays for imported ceramics create first-mover advantages for laboratories with pre-established technical documentation in Riyadh and Jeddah.
For Market Incumbents: Anticipate chairside CAD/CAM adoption by private clinic chains to erode single-unit crown outsourcing volumes, and respond by deepening implant-abutment custom screw-retained capabilities that resist in-house production. Acquire or partner with tele-dental design centers in Cape Town to extend file-optimization services across sub-Saharan satellite clinics without physical logistics infrastructure. Certification investment in SFDA parallel documentation systems for zirconia and lithium disilicate formulations anchors defensive positioning against Asian competitors lacking CE MDR technical files. For New Entrants and Emerging Players: Capture white-space opportunity in Egypt and Morocco outsourced crown fabrication serving uninsured populations with metal-ceramic hybrid designs at 40-60 percent below Gulf market pricing. Target Casablanca and Alexandria laboratory clusters where conventional casting workflows persist and digital denture adoption lags premium segments by three to five years. Go-to-market angle: bundle tele-dental design services with local acrylic processing partnerships to bypass capital-intensive milling equipment requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among independent milling centers with open-architecture platforms and established SFDA registration portfolios but limited brand recognition in Gulf Cooperation Council cosmetic dentistry networks. Long-term viability hinges on software companion development for surgical planning integration and cross-selling into implant restoration workflows. Watch for SFDA regulatory harmonization with Gulf Standardization Organization members as inflection signal for regional consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Platform Integration | Closed-system scanner-miller-software bundles lock laboratories into proprietary consumable streams across South African metropolitan corridors. |
| SFDA Certification Investment | Parallel CE MDR technical file development accelerates ceramic blank registration timelines against Asian competitors. |
| Tele-Dental Network Expansion | Remote design centers in Cape Town transmit files to satellite clinics across sub-Saharan Africa without physical logistics. |
| Implant-Abutment Capability Buildout | Custom screw-retained crowns resist chairside displacement and command premium positioning in Riyadh private clinics. |
| North African Market Entry | Cairo and Alexandria outsourcing demand for cost-sensitive metal-ceramic hybrids remains underpenetrated by Gulf laboratory networks. |
Research Methodology
Bottom-up dental clinic and hospital procurement modeling reconciled against top-down milling equipment import tracking forms the analytical core of this study. Primary interviews with dental laboratory technicians, CAD/CAM equipment distributors, biomedical engineers at Saudi privatizing hospitals, and GPO contracts managers at South African dental group practices combined with secondary validation from SFDA registration databases, MOHAP medical device filings, customs trade data for zirconia blank imports, and CE MDR technical file repositories. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of digital workflow adoption rates across Gulf Cooperation Council private clinic networks established baseline penetration curves extended across the projection horizon. Segmentation dimensions modeled include product type (crowns, bridges, dentures, implants), technology tier (CAD/CAM, milling, 3D printing, casting), end-user category (dental clinics, hospitals, orthodontics, dental schools), and material specification (ceramics, metals, composites, acrylics). CAGRs derived from equipment installation trajectories and consumable utilization rates calibrated against clinic expansion pipelines.
SFDA regulatory harmonization delays, South African Health Products Regulatory Authority approval timeline extensions, and Gulf Cooperation Council health privatization schedule shifts are the dominant revision risks to forecast assumptions. Currency volatility affecting German and Japanese equipment import costs and technician training pipeline bottlenecks for digital design software proficiency present secondary uncertainty vectors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Splints Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Chile Dental Devices Market
Dental Devices
Dental Units Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Implants and Dental Prosthetics Market