
 Dental Anaesthetic Market | 2026-2036
Dental Anaesthetic Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Anaesthetic Market Outlook
Needle-free jet injection technology is rewriting how dental anaesthetics reach soft tissue and bone, eliminating patient anxiety around traditional syringes while improving dose precision. Septodont leverages its European manufacturing base to sustain leadership in articaine formulations. Dentsply Sirona anchors North American distribution through its integrated dental equipment and consumables platform. Henry Schein competes on channel density, controlling procurement pathways for thousands of independent dental practices.
Dental anaesthetics comprise amide and ester-class compounds formulated with vasoconstrictors to prolong nerve blockade, typically delivered at concentrations between two and four percent depending on procedural depth and vascularity of the injection site. These agents temporarily inhibit sodium ion channels in peripheral nerves, enabling pain-free operative dentistry and oral surgery. Articaine formulations lead product type demand due to superior bone penetration and faster metabolization, while nerve block delivery methods command premium positioning for third-molar extractions and implantology. Sedation applications within the application dimension represent the fastest-growing margin pool as patient comfort expectations escalate.
The FDA oversees local anaesthetic safety through New Drug Application pathways and adverse event monitoring, while the EMA's Committee for Medicinal Products for Human Use evaluates articaine-containing products for European market authorization. ISO 13485 quality management standards govern manufacturing consistency across international supply chains, directly shaping batch release protocols and facility audit schedules. Stakeholders must monitor evolving EPA regulations on pharmaceutical manufacturing effluents, as wastewater discharge rules for active pharmaceutical ingredient production tighten compliance burdens for formulation facilities.
Market Dynamics
Articaine's displacement of lidocaine in complex oral surgery is compressing formulation margins while forcing manufacturers to reconfigure active pharmaceutical ingredient sourcing toward European synthesis capabilities.
Growth Catalysts
- FDA Safety Guidance:The FDA's updated local anaesthetic manufacturing standards are accelerating facility upgrades that improve batch consistency and reduce adverse event liability for domestic producers.
- Needle-Free Delivery Systems:Jet injection technology is penetrating paediatric and anxiety-practice segments, expanding addressable patient populations previously refusing traditional syringe administration.
- Ambulatory Surgical Centre Expansion:United States outpatient facilities are upgrading anaesthetic protocols to support same-day implantology and third-molar extraction volumes.
Market Restraints
- API Supply Concentration:Articaine base synthesis concentrates in German and Italian chemical manufacturing clusters, creating single-source vulnerability for North American formulators.
- Ester-Class Substitution:Prilocaine and mepivacaine retain cost advantages in routine restorative procedures, limiting articaine penetration in price-sensitive practice segments.
- EPA Effluent Rules:Tightening pharmaceutical manufacturing wastewater discharge standards are extending compliance timelines and raising capital requirements for formulation facilities.
Strategic Opportunities
- Sedation Protocol Integration:Conscious sedation applications in implantology and periodontal surgery represent margin expansion beyond conventional nerve block pricing.
- ISO 13485 Certification Arbitrage:Manufacturers achieving updated quality management certification can access European and Middle Eastern procurement tenders closed to uncertified competitors.
- Digital Workflow Convergence:Integration of anaesthetic dosing algorithms with cone-beam CT and surgical navigation systems is creating software-hardware bundled positioning.
Industry Challenges
- Compounding Pharmacy Oversight:State-level variations in 503B outsourcing facility regulation create compliance fragmentation for multi-state dental service organizations.
- Vasoconstrictor Sourcing:Epinephrine API availability constraints are forcing reformulation timelines and inventory management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Anaesthetic Market |
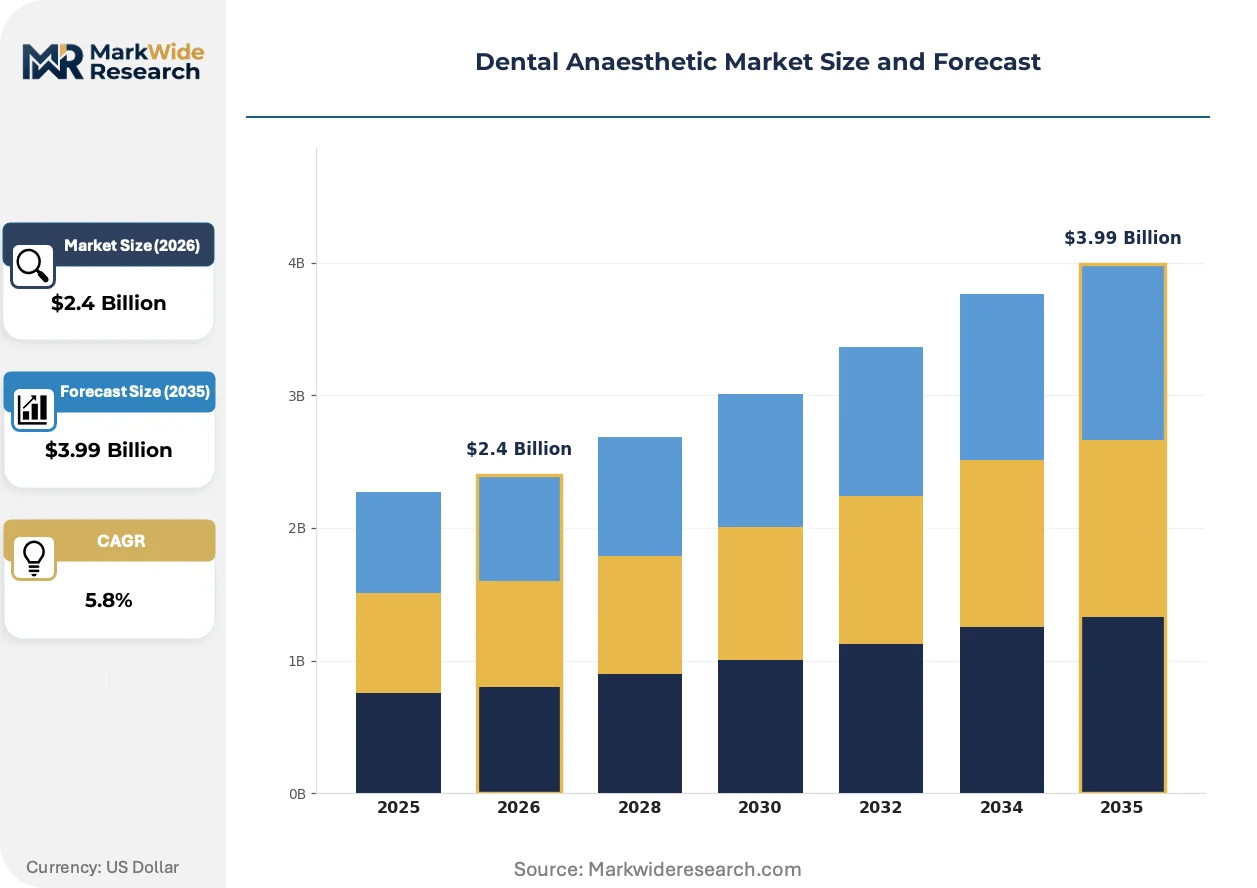
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lidocaine, Bupivacaine, Articaine, Mepivacaine Delivery Method: Topical, Infiltration, Nerve Block, Intravenous End User: Dental Clinics, Hospitals, Research Laboratories, Academic Institutions Application: Routine Procedures, Surgical Procedures, Pain Management, Sedation |
| Companies Covered | Dentsply Sirona, Septodont, Henry Schein, Pierrel, Laboratorios Inibsa, Primex Pharmaceuticals, Aspen Group, Huons Global, Cetylite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Anaesthetic Market Strategic Shifts
Delivery mechanism virtualization and regulatory harmonization pressures are compressing traditional competitive moats while opening new value-capture layers in digital-integrated care protocols.
Computer-controlled local anaesthetic delivery is virtualizing the injection experience through pressure-sensing algorithms that adapt flow rates to tissue resistance in real time. Paediatric and geriatric practices are adopting these systems fastest, with anxiety-reduction outcomes driving referral network expansion. The technology is virtualizing the skill premium previously commanded by experienced administrators, enabling consistent outcomes across operator experience levels.
EMA's Committee for Medicinal Products for Human Use is tightening articaine-containing product authorization requirements through enhanced pharmacovigilance data demands. European manufacturers face extended approval timelines and post-market study obligations that raise competitive barriers for new entrants. Articaine formulation specialists with established European market presence are consolidating regulatory affairs capabilities to manage this burden.
Group purchasing organizations are consolidating procurement authority across United States dental service organizations, compressing vendor counts and demanding outcome-based contract terms. Independent practices are losing negotiating leverage as regional DSOs aggregate volume and standardize formulary selection. This concentration is most visible in Sun Belt metropolitan markets where private equity-backed dental platforms are scaling fastest.
Dental Anaesthetic Market Segmentation
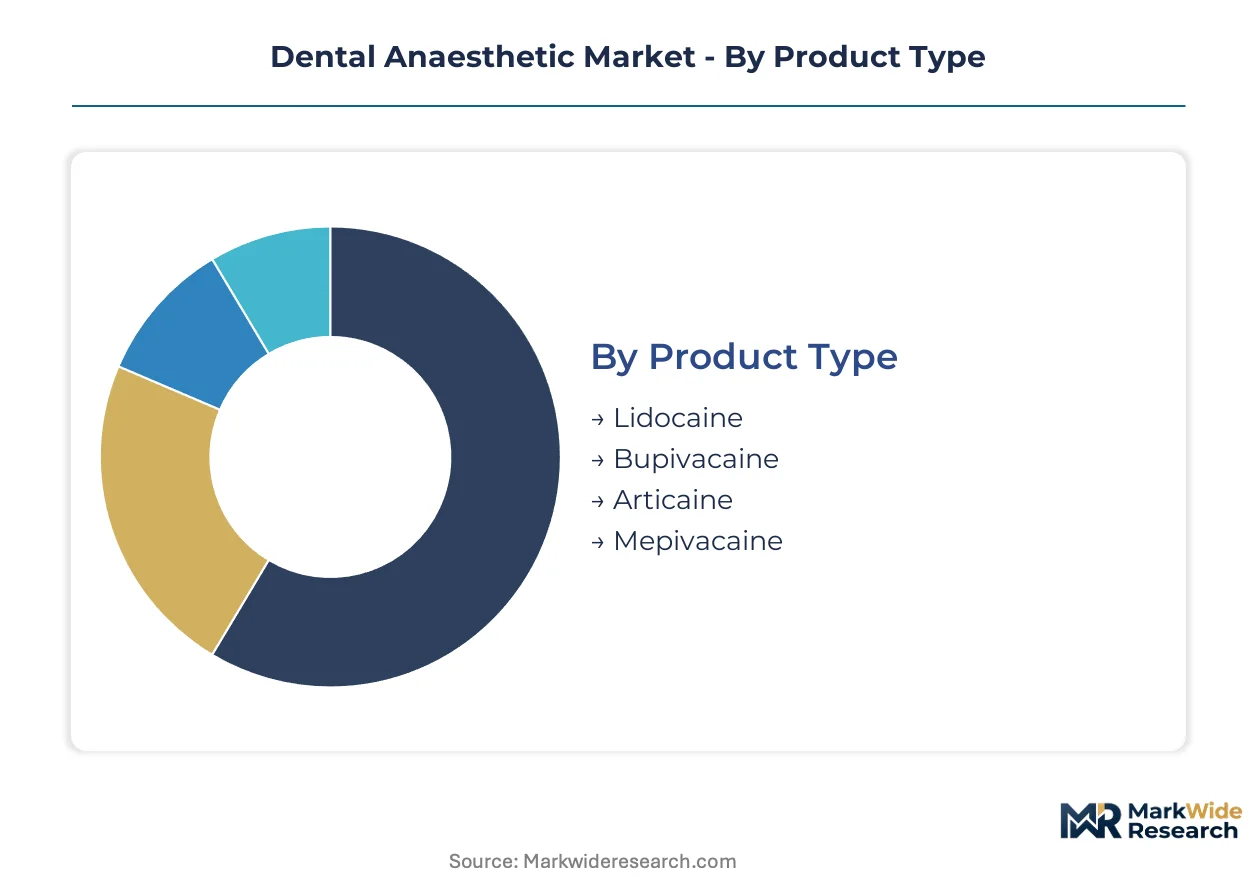
Product differentiation in dental anaesthetics hinges on metabolic pathway, tissue penetration depth, and vasoconstrictor compatibility. Segmentation reveals how formulation chemistry and administration modality shape procurement decisions across practice settings.
Product Type:
Cost tier stratification separates premium articaine formulations from commodity lidocaine alternatives, with metabolic clearance rates and bone penetration defining clinical positioning.
- Articaine:Superior bone penetration and rapid plasma esterase hydrolysis enable shorter recovery windows in implantology and third-molar surgery. United States ambulatory surgical centres are standardizing articaine protocols for complex oral surgery volumes.
- Lidocaine:Amide-class metabolism and established safety profile sustain volume leadership in routine restorative procedures. Cost-sensitive dental clinics in price-competitive markets retain lidocaine as default infiltration anaesthetic.
- Bupivacaine:Extended duration nerve blockade suits post-operative pain management protocols. Slower onset limits use in time-pressed clinical environments.
- Mepivacaine:Vasoconstrictor-free formulations serve hypertensive patient populations. Reduced cardiovascular stress drives selection in geriatric practices.
Articaine holds installed capacity. Mepivacaine is rotating up the share rankings.
Delivery Method:
Application complexity determines modality selection, with tissue depth and procedural invasiveness driving migration from surface to deep blockade techniques.
- Nerve Block:Mandibular and maxillary trunk anaesthesia enables pain-free third-molar extraction and full-arch implantology. United States oral surgery practices command premium reimbursement for deep blockade expertise.
- Infiltration:Terminal nerve branch deposition supports single-tooth restorative work and periodontal maintenance. High procedure frequency sustains volume dominance across general dental practices.
- Topical:Surface mucosal preparation reduces needle insertion pain prior to injection. Paediatric and anxiety-focused practices prioritize patient comfort outcomes.
- Intravenous:Conscious sedation protocols integrate with surgical navigation systems in hospital-affiliated dental departments. Regulatory oversight from FDA and state dental boards constrains deployment scope.
Infiltration holds installed capacity. Nerve block is rotating up the share rankings.
End User:
Customer type concentration reflects capital intensity, regulatory burden, and procedure mix differentiation across care delivery settings.
- Dental Clinics:Independent and group practice settings perform the majority of routine restorative and minor surgical procedures. Group purchasing organizations are consolidating formulary authority across United States dental service organizations.
- Hospitals:Operating room infrastructure supports general anaesthesia and complex maxillofacial reconstruction. Academic medical centres train residents in multimodal pain management protocols.
- Research Laboratories:Formulation stability and pharmacokinetic studies inform next-generation delivery system development. ISO 13485 quality standards govern contract research engagement.
- Academic Institutions:Dental schools standardise student training around specific anaesthetic protocols. Curriculum alignment creates long-term preference lock-in for selected formulations.
Dental clinics hold installed capacity. Hospitals are rotating up the share rankings.
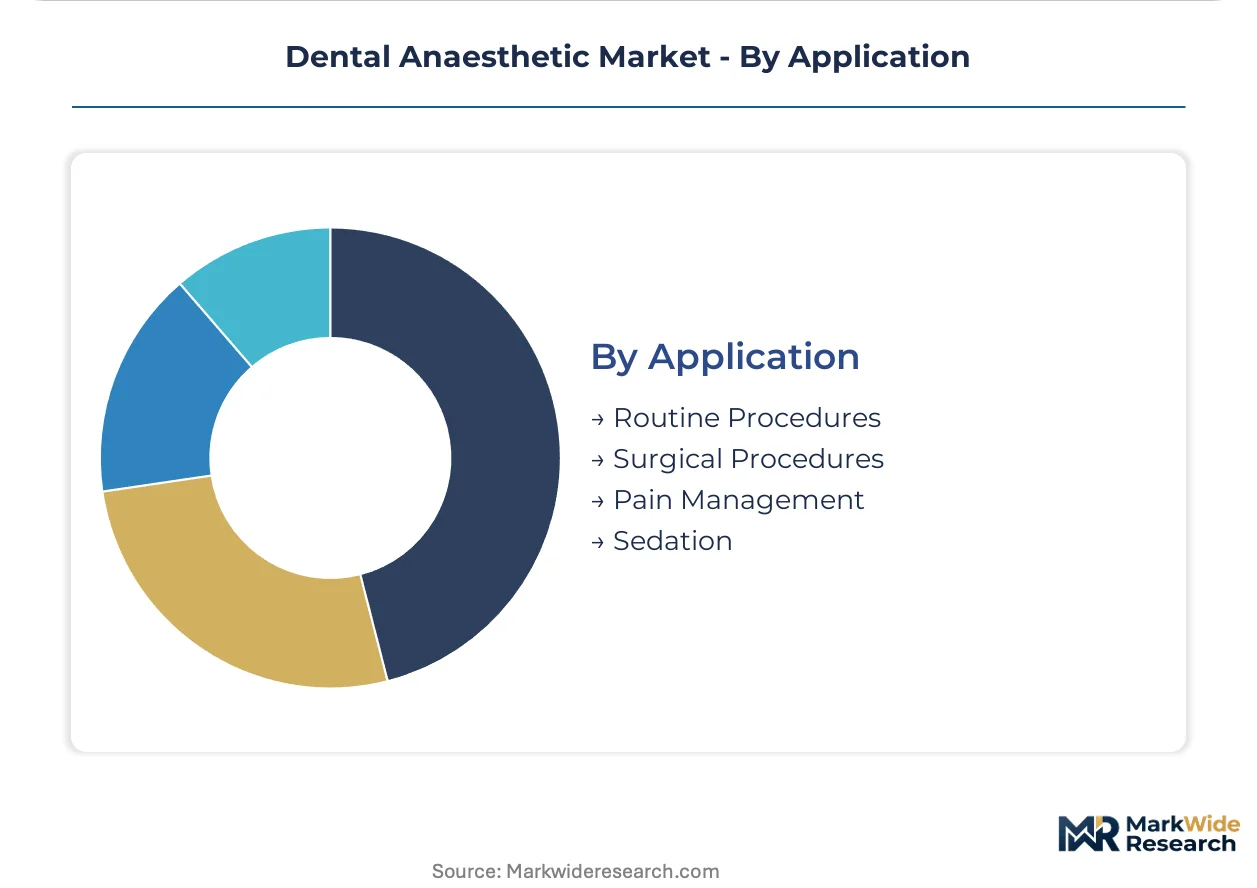
Application:
Margin structure varies sharply across procedure intensity, with sedation and surgical applications capturing premium pricing relative to routine care.
- Surgical Procedures:Implantology and third-molar extraction demand deep anaesthesia with extended duration control. Articaine nerve block formulations dominate this high-value segment.
- Sedation:Conscious sedation protocols for anxious patients and complex multi-quadrant work represent the steepest expansion trajectory. FDA oversight of benzodiazepine-opioid combinations shapes protocol design.
- Routine Procedures:Restorative dentistry and periodontal maintenance sustain baseline anaesthetic consumption. Price compression from generic lidocaine limits margin expansion.
- Pain Management:Post-operative and chronic orofacial pain protocols extend anaesthetic utility beyond operative settings. Bupivacaine extended-release formulations serve this emerging indication.
Routine procedures hold installed capacity. Sedation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ambulatory surgical centers and dental service organizations concentrate procurement authority in mature markets, while emerging economies expand clinic infrastructure to capture unmet oral surgery demand. Regulatory divergence between FDA and EMA pathways shapes formulation approval timelines and post-market surveillance burdens. Manufacturing clusters align with pharmaceutical synthesis capabilities and distribution logistics networks.
United States
Private equity-backed dental service organizations in Sun Belt metropolitan markets aggregate volume and standardize articaine-based protocols for implantology. FDA's updated local anaesthetic manufacturing standards accelerate facility upgrades among domestic producers. Chicago and Minneapolis host major distribution hubs serving ambulatory surgical centers upgrading anaesthetic capabilities.
Germany
Articaine base synthesis concentrates in chemical manufacturing clusters supplying North American formulators. EMA's Committee for Medicinal Products for Human Use tightens authorization requirements through enhanced pharmacovigilance demands. Frankfurt and Ludwigshafen anchor active pharmaceutical ingredient production for European dental anaesthetic supply chains.
France
ANSM oversight of local anaesthetic safety shapes manufacturing audit schedules and batch release protocols. Septodont leverages its European manufacturing base to sustain leadership in articaine formulations. Lyon and Paris host formulation facilities serving Middle Eastern and African export markets.
Italy
Italian chemical manufacturing clusters complement German synthesis capabilities for articaine base production. REACH compliance and ISO 13485 certification govern contract research engagement for formulation stability studies. Milan and Bologna concentrate regulatory affairs capabilities managing EMA authorization timelines.
China
NMPA pathways for local anaesthetic registration extend approval timelines for imported articaine formulations. Domestic clinic chains in Shanghai and Beijing expand oral surgery volumes driving anaesthetic consumption growth. Yangtze River Delta manufacturing zones develop generic lidocaine production for price-sensitive Asian markets.
Dental Anaesthetic Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement pathway access and formulation innovation vectors. The vendor base separates into three tiers: integrated dental equipment platforms, pharmaceutical pure-plays, and distribution-heavy procurement intermediaries. Dominant competitive moves include geographic expansion through regulatory certification arbitrage and portfolio diversification into sedation protocol integration.
Among European pharmaceutical pure-plays, Septodont exemplifies the articaine-specialist archetype anchored in EMA regulatory mastery. Dentsply Sirona occupies the integrated platform position, leveraging North American equipment and consumables convergence. Henry Schein represents the channel-density archetype, controlling procurement pathways for independent practice networks across United States metropolitan markets.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Septodont |
| Henry Schein |
| Pierrel |
| Laboratorios Inibsa |
| Primex Pharmaceuticals |
| Aspen Group |
| Huons Global |
| Cetylite Industries |
| Others |
Value Chain & Pricing Dynamics
German and Italian chemical manufacturing clusters for articaine base synthesis concentrate upstream capacity, anchoring margin capture in European API specialists while North American formulators absorb transport and regulatory transfer costs.
Pricing Analysis
Cost-plus contracts with epinephrine API indexation dominate articaine formulation procurement. Three-tier pricing structure across premium, standard, and economy levels separates Septodont's EMA-certified articaine from commodity lidocaine alternatives. Pricing pressure stems from group purchasing organization consolidation across Sun Belt dental service organizations. Independent practices exhibit highest price sensitivity; ambulatory surgical centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing for articaine base concentrates at German chemical synthesis facilities in Ludwigshafen and Frankfurt, with Italian clusters in Milan and Bologna providing secondary capacity. Formulation draws from epinephrine API, articaine base, and glass ampoule packaging inputs. Single-source vulnerability in German articaine synthesis creates exposure to EMA audit disruptions. Distribution runs through Henry Schein's North American procurement pathways and Dentsply Sirona's integrated equipment-consumables platform.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental anaesthetic procurement fragmentation creates specialist opportunities as sedation protocol integration and needle-free delivery adoption fragment demand across anxiety-focused practices and pediatric segments.
For Market Incumbents: Insulate articaine margin pools through backward integration into European API synthesis capabilities and ISO 13485 certification arbitrage for Middle Eastern tender access. Jet injection technology from dental equipment platforms threatens formulation-only positioning; defend through sedation protocol bundling with benzodiazepine-opioid combinations. For New Entrants and Emerging Players: Sun Belt metropolitan markets with private equity-backed dental service organization expansion present underpenetrated articaine standardization opportunities. Target conscious sedation applications in implantology for premium positioning. Pursue regulatory certification arbitrage through EMA authorization pathway mastery to unlock European procurement access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental service organizations aggregating volume across Arizona, Texas, and Florida markets. Five-to-ten year viability hinges on sedation protocol integration depth rather than commodity formulation scale. Watch FDA adverse event monitoring thresholds for articaine-containing products as inflection signal for liability-adjusted returns.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Authorization Pathway Investment | Unlocks European procurement tenders closed to uncertified competitors under updated CHMP pharmacovigilance demands. |
| Sedation Protocol Integration | Captures premium margin pools in implantology and periodontal surgery beyond conventional nerve block pricing. |
| Needle-Free Delivery System Development | Expands addressable patient populations in pediatric and anxiety-focused practices previously refusing syringe administration. |
| Backward Integration into API Synthesis | Reduces single-source vulnerability from German and Italian articaine base concentration. |
| Group Purchasing Organization Partnership | Secures formulary placement as DSO procurement authority consolidates across United States metropolitan markets. |
Study Parameters
Initial hypotheses were tested against primary input from oral surgeons, dental service organization procurement directors, regulatory affairs specialists at pharmaceutical manufacturers, and group purchasing organization contract managers, then refined against FDA 483 inspection records, EMA CHMP assessment reports, ISO 13485 certification databases, and United States ambulatory surgical center Medicare cost reports. Bottom-up articaine volume estimates from clinic-level procedure data triangulated with top-down pharmaceutical shipment analytics.
Demand-supply balance modeling across the analysis window segmented by product type, delivery method, end user, and application intensity. CAGRs derived from procedure volume elasticity to dental clinic expansion and sedation protocol penetration rates. Forecast inputs incorporated EPA effluent rule compliance timelines and EMA pharmacovigilance study obligations.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by dental equipment platforms would shift outcomes. Quarterly review of FDA adverse event reporting system articaine signals and DSO merger-announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Periodontal Market
Dental Devices
Dental Articulators Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Dental Braces Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Dental Hand Tools Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Impression System Market
Dental Devices
Chile Dental Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Dental Delivery System Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Dental Prosthetics Market