
 Dental Air Polishers Market | 2026-2036
Dental Air Polishers Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Air Polishers Market Outlook
Germany is reconfiguring supply dynamics for precision dental devices through its Baden-Württemberg and Bavaria manufacturing clusters. Dentsply Sirona leverages integrated R&D campuses in Bensheim to sustain technology leadership in air-polishing handpieces. EMS Electro Medical Systems anchors European distribution through its Nyon headquarters while competing aggressively in Asian markets. KaVo Dental dominates premium chairside integration with proprietary coupling systems that control workflow efficiency in German and US clinics.
A dental air polisher is a precision pneumatic instrument that propels a controlled stream of sodium bicarbonate, glycine, or erythritol powder through a narrow nozzle at pressures typically ranging from 40 to 70 psi to remove biofilm and extrinsic stains without mechanical abrasion. The device serves primary industrial purpose in preventive dentistry, periodontal maintenance, and aesthetic stain removal where tissue preservation outweighs cutting efficiency. Handheld and wireless configurations are capturing margin pools as practitioners prioritize ergonomic mobility and reduced cord contamination in operatory environments. Ultrasonic technology segments face saturation in mature markets while air abrasion systems extend into cosmetic dentistry applications where patient comfort drives premium positioning.
FDA 510(k) premarket notification requirements govern US device clearance while EU MDR technical documentation mandates clinical evidence for air-polishing systems sold in European markets. Japan's PMDA enforces QMS ministerial ordinances that shape manufacturing standards for powder delivery mechanisms and nozzle sterilization protocols. The ISO 13485 quality management framework underpins global supplier audits and contract manufacturer eligibility. Stakeholders must monitor evolving powder biocompatibility standards and regional reimbursement codes for preventive prophylaxis to anticipate shifts in clinical adoption and procurement authority.
Market Dynamics
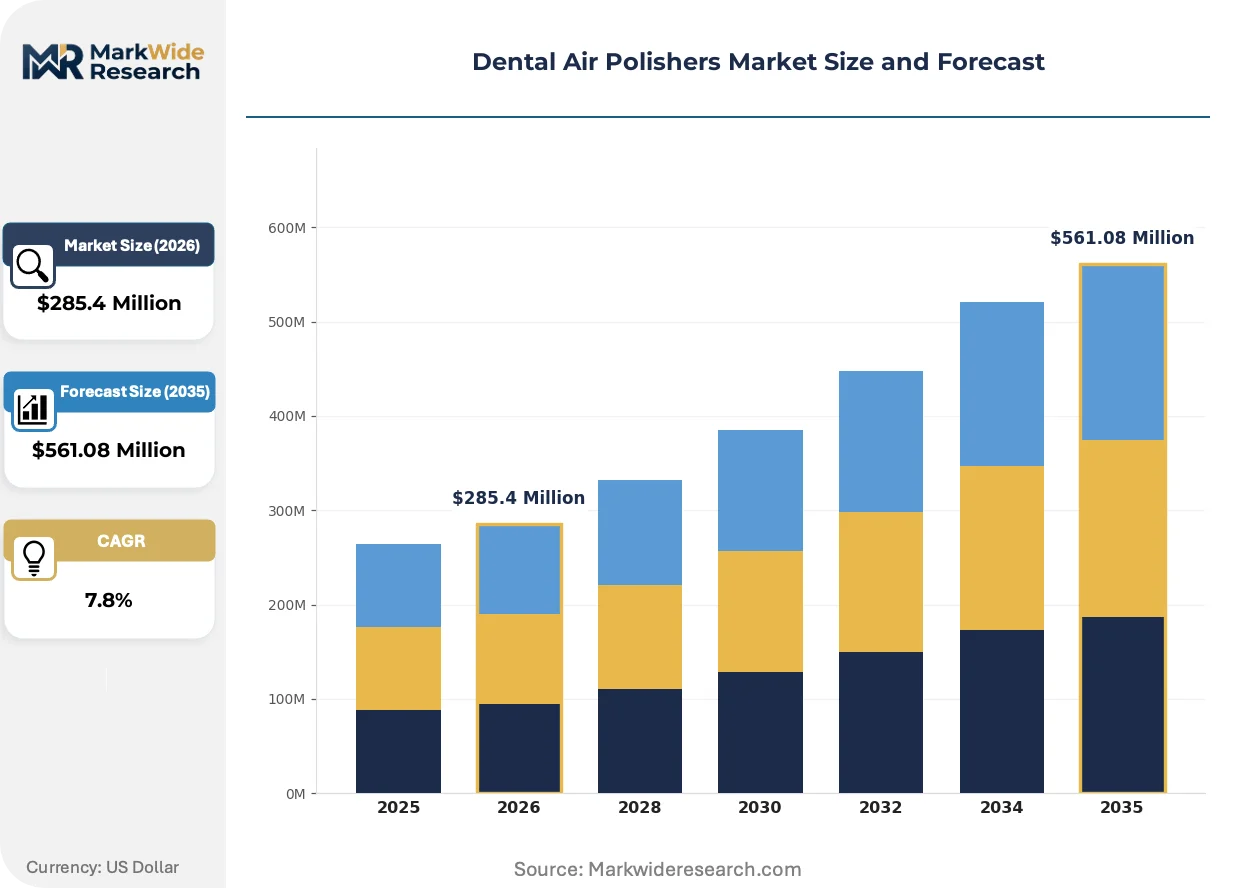
The dental air polishers market is being reshaped by the convergence of EU MDR compliance timelines and wireless ergonomic adoption, forcing manufacturers to redesign powder delivery systems while clinics accelerate replacement cycles for corded legacy units.
Growth Catalysts
- EU MDR Technical Documentation:The European Medical Device Regulation mandates clinical evidence for air-polishing systems, elevating entry barriers that favor established manufacturers with robust quality management systems.
- Japan's Aging-Care Dental Infrastructure:PMDA QMS ministerial ordinances are driving procurement of powder-based biofilm removal systems in geriatric dental facilities where tissue preservation protocols dominate treatment planning.
- Glycine Powder Substitution:Sodium bicarbonate alternatives with reduced abrasivity are expanding air abrasion into cosmetic dentistry applications previously served by ultrasonic scaling systems.
Market Restraints
- Input Cost Volatility:Medical-grade erythritol and glycine powder supply concentrates in Chinese chemical manufacturing clusters, exposing margins to shipping cost fluctuations and customs processing delays.
- Technical Limitation:Powder cloud containment in open-bay dental operatory designs restricts air polisher deployment in high-volume community health settings where HVAC retrofit costs are prohibitive.
- Substitution Threat:Ultrasonic piezoelectric scalers with modified tip geometries are reclaiming periodontal maintenance cases where air polishing previously held advantage in patient comfort metrics.
Strategic Opportunities
- Underpenetrated German Preventive Networks:Statutory health insurance reimbursement expansion for prophylaxis procedures in Baden-Württemberg municipal dental clinics is opening procurement windows for mid-tier wireless systems.
- Technology Convergence:Integration of optical biofilm detection cameras with air-polishing handpieces is creating chairside diagnostic-treatment workflows that command premium positioning in Japanese private practices.
- Distribution Innovation:Direct-to-clinic digital procurement platforms are bypassing traditional dental dealer networks in US metropolitan markets, compressing sales cycles and expanding margin capture for manufacturers.
Industry Challenges
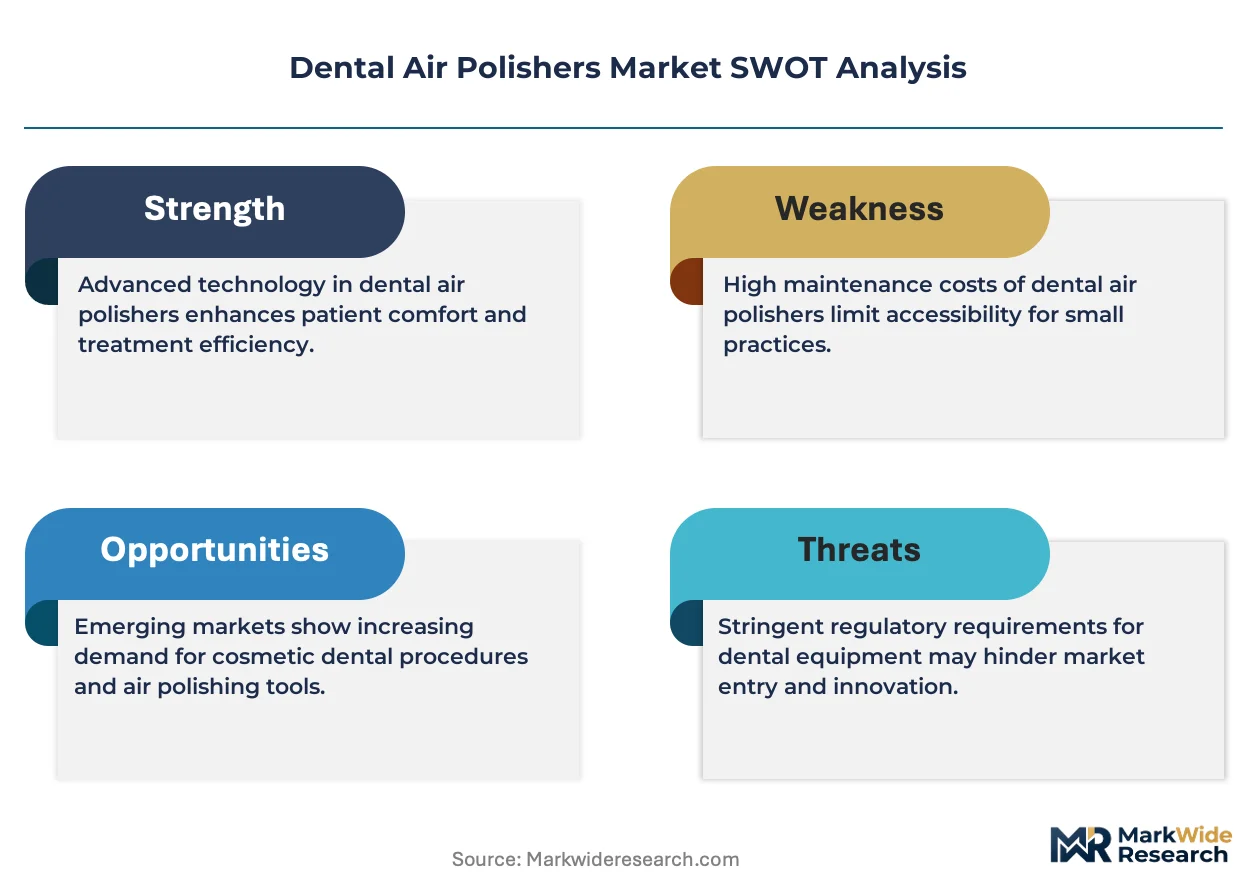
- Certification Timeline Compression:FDA 510(k) premarket notification review periods for novel powder formulations are extending beyond historical baselines as the agency intensifies biocompatibility scrutiny.
- Integration Complexity:Legacy dental unit waterline sterilization protocols conflict with wireless handpiece charging dock placement, requiring operatory redesign investments that delay adoption in capital-constrained practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Air Polishers Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Tabletop, Portable, Wireless Technology: Air Abrasion, Ultrasonic, Electrosurgery, Laser End User: Dental Clinics, Hospitals, Research Labs, Cosmetic Dentistry Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Distributors |
| Companies Covered | Dentsply Sirona, EMS Electro Medical Systems, KaVo Dental, NSK Ltd., ACTEON Group, Hu-Friedy, Bien-Air Dental, Dürr Dental, Mectron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Air Polishers Market Strategic Shifts
Wireless connectivity and powder chemistry advances are converging to redefine clinical workflows, while regulatory evidence requirements and procurement digitization are restructuring how manufacturers reach end-users.
Smart handpiece telemetry is digitizing preventive dentistry by embedding pressure sensors and usage tracking into air-polishing devices. German and Japanese dental clinics are piloting these systems to document prophylaxis outcomes for reimbursement validation. This capability is digitizing compliance documentation and compressing the competitive advantage of manufacturers lacking data infrastructure.
EU MDR clinical evidence requirements are forcing redesign of air-polishing system technical files ahead of 2026 certificate renewal deadlines. Manufacturers must generate prospective clinical data on powder biocompatibility and nozzle sterilization efficacy. Premium wireless segments face the steepest documentation burdens, accelerating consolidation among mid-tier suppliers unable to fund regulatory affairs expansion.
Group purchasing organizations are consolidating procurement authority for dental consumables and devices across US multi-location practice networks. Independent dealers are losing shelf space to direct manufacturer contracts with Dental Service Organizations. This concentration is most visible in Texas and Florida metropolitan corridors where DSOs control 40-plus location fleets and standardize equipment specifications across acquired practices.
Dental Air Polishers Market Segmentation
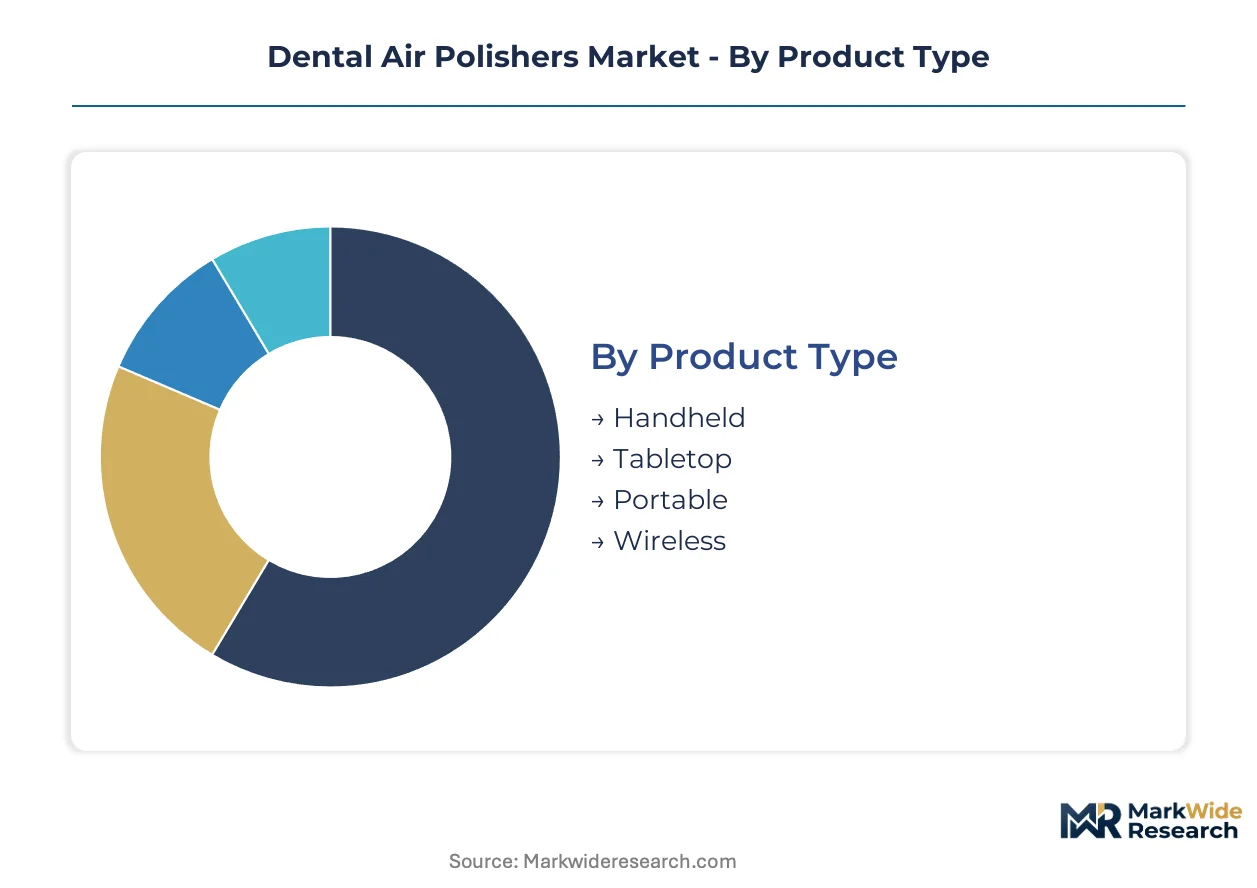
Dental air polisher segmentation reveals how clinical workflow priorities and regulatory constraints fragment procurement decisions across operatories. Manufacturers must align specifications with distinct sterilization protocols, powder compatibility requirements, and integration standards that vary by setting.
Product Type:
Handheld configurations dominate chairside ergonomics while wireless variants capture replacement cycles in renovated operatory environments.
- Handheld:Tethered pneumatic units with direct dental unit coupling deliver consistent 40-70 psi pressure for biofilm removal in high-volume German municipal clinics. Demand concentrates in Baden-Württemberg preventive networks where statutory insurance reimbursement expansion supports equipment refresh programs.
- Wireless:Battery-powered handpieces eliminate cord contamination risks and enable mobility between operatories in Japanese aging-care dental facilities. PMDA QMS ministerial ordinances shape charging dock sterilization protocols, slowing adoption where legacy waterline infrastructure conflicts with dock placement requirements.
- Tabletop:Self-contained units with integrated powder reservoirs serve mobile dental services and field clinics lacking permanent dental unit installation.
- Portable:Compact transportable systems target community health programs and nursing home visitation services where fixed infrastructure is unavailable.
The dominant share belongs to Handheld, while Wireless is closing the gap fastest.
Technology:
Cost tier differentiation separates established pneumatic systems from premium energy-based alternatives competing for periodontal maintenance cases.
- Air Abrasion:Powder-propulsion systems using sodium bicarbonate, glycine, or erythritol achieve selective stain removal without mechanical cutting. EU MDR clinical evidence requirements for powder biocompatibility documentation favor established manufacturers with robust quality management systems.
- Ultrasonic:Piezoelectric scalers with modified tip geometries reclaim market position in US periodontal practices where insurance reimbursement coding favors established procedural categories.
- Electrosurgery:Radiofrequency cutting devices serve soft tissue procedures adjacent to air polishing workflows in hospital-based dental departments.
- Laser:Erbium and diode laser systems command premium positioning in Japanese cosmetic dentistry practices where patient comfort metrics drive technology selection.
Air Abrasion retains volume leadership, though Ultrasonic is expanding most quickly in mature reimbursement markets.
End User:
Application intensity varies from high-frequency preventive protocols in dedicated clinics to intermittent specialized use in hospital settings.
- Dental Clinics:Private and group practices generate concentrated demand for mid-tier wireless systems as US Dental Service Organizations standardize equipment specifications across multi-location fleets.
- Hospitals:Academic medical centers and community hospitals integrate air polishers into comprehensive dentistry departments where sterilization infrastructure supports diverse device portfolios.
- Research Labs:University dental schools and clinical trial facilities procure specialized units for comparative effectiveness studies on powder formulations and nozzle designs.
- Cosmetic Dentistry:Aesthetic-focused practices in Germany's Bavaria region drive glycine powder adoption for low-abrasivity stain removal preceding whitening procedures.
Dental Clinics command the installed base, while Cosmetic Dentistry is gaining share fastest.
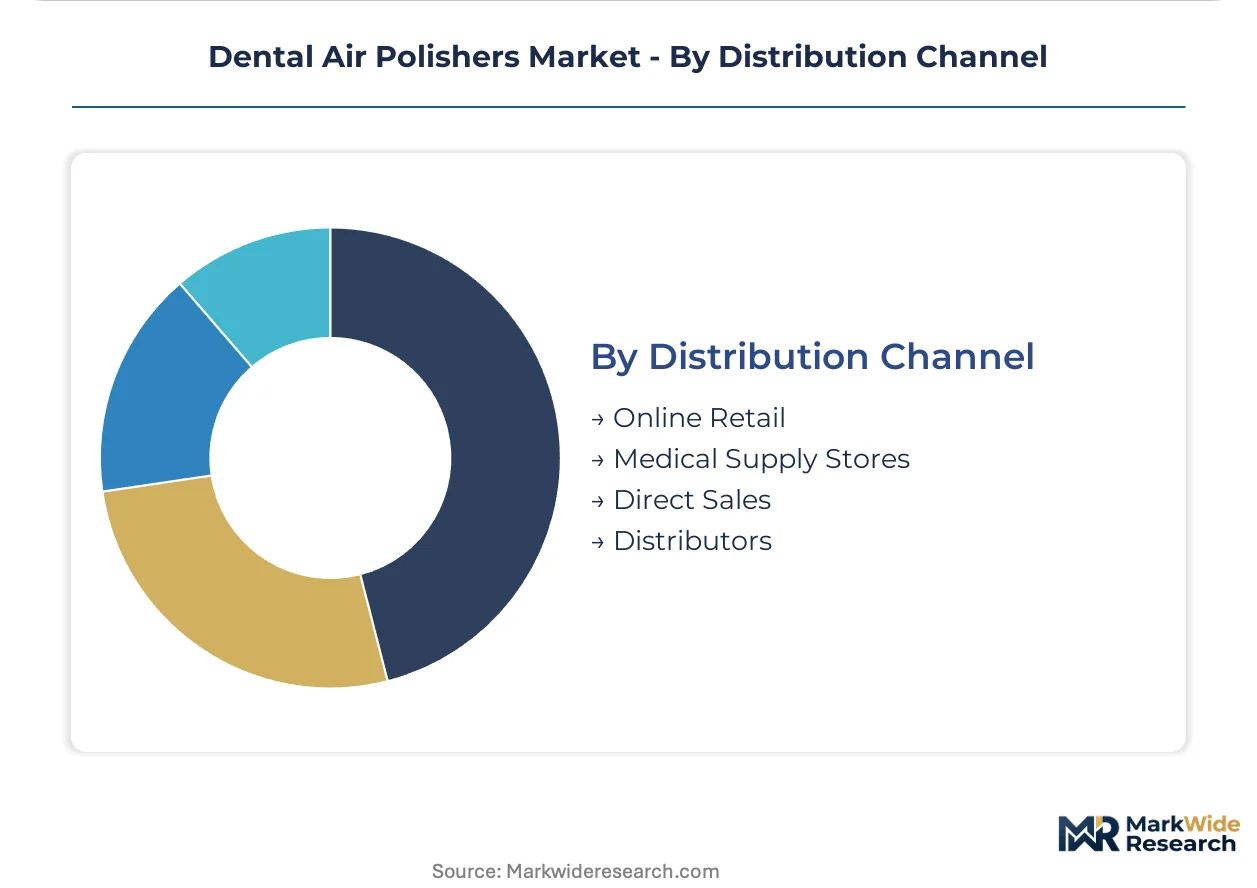
Distribution Channel:
Customer type and purchase scale determine whether procurement flows through traditional dealer networks or direct manufacturer relationships.
- Direct Sales:Manufacturer representatives negotiate enterprise contracts with DSOs and hospital systems in Texas and Florida metropolitan corridors where location fleet standardization compresses sales cycles.
- Distributors:Traditional dental dealers maintain relationships with independent practices requiring installation support and service coverage in dispersed geographic markets.
- Online Retail:Digital procurement platforms bypass dealer markups for consumables and replacement handpieces in capital-constrained solo practices.
- Medical Supply Stores:Regional suppliers serve urgent replacement needs and small-practice equipment purchases with localized inventory availability.
Direct Sales holds the revenue concentration, while Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor US market entry protocols, while EU MDR technical documentation requirements and Japan's PMDA QMS ministerial ordinances reshape manufacturing standards across their respective jurisdictions. Dental clinics in Germany, Japan, and the United States are expanding adoption of air abrasion systems for preventive and cosmetic procedures.
United States
Texas and Florida metropolitan corridors concentrate Dental Service Organization fleet standardization, with DSOs controlling 40-plus location networks that compress procurement cycles. FDA 510(k) premarket notification review periods for novel powder formulations are extending beyond historical baselines as biocompatibility scrutiny intensifies. Direct-to-clinic digital procurement platforms are bypassing traditional dental dealer networks in these urban markets.
Germany
Baden-Württemberg and Bavaria manufacturing clusters reconfigure supply dynamics for precision dental devices, with statutory health insurance reimbursement expansion opening procurement windows for mid-tier wireless systems. EU MDR clinical evidence requirements for powder biocompatibility documentation favor established manufacturers with robust quality management systems. Dentsply Sirona leverages integrated R&D campuses in Bensheim to sustain technology leadership.
Japan
Aging-care dental infrastructure drives procurement of powder-based biofilm removal systems in geriatric facilities where tissue preservation protocols dominate treatment planning. PMDA QMS ministerial ordinances shape charging dock sterilization protocols, slowing wireless adoption where legacy waterline infrastructure conflicts with dock placement requirements. Integration of optical biofilm detection cameras with air-polishing handpieces is creating chairside diagnostic-treatment workflows in private practices.
China
Medical-grade erythritol and glycine powder supply concentrates in chemical manufacturing clusters, exposing margins to shipping cost fluctuations and customs processing delays. The country's national medical device regulator enforces quality management standards that shape manufacturing protocols for powder delivery mechanisms. Domestic production capacity is expanding to serve regional demand for consumables and replacement components.
Switzerland
EMS Electro Medical Systems anchors European distribution through its Nyon headquarters while competing aggressively in Asian markets. Swissmedic oversight of medical device quality systems reinforces technical documentation standards that align with EU MDR requirements. Precision engineering capabilities support development of advanced nozzle designs and powder containment systems.
Dental Air Polishers Market Competitive Environment
Capability concentration sits with integrated multinationals commanding regulatory affairs infrastructure; scale advantage sits with mid-tier specialists leveraging manufacturing efficiency. The market structure reflects tiered consolidation where premium wireless segments face steepest documentation burdens. Three archetypes dominate: integrated device manufacturers with chairside ecosystem control, precision component specialists with powder delivery expertise, and regional fabricators serving price-sensitive procurement. Competitive moves center on M&A for regulatory capability acquisition and strategic partnerships for distribution reach.
Within the integrated multinational tier, Dentsply Sirona and KaVo Dental exemplify archetypes of device ecosystem control and proprietary coupling system dominance. EMS Electro Medical Systems occupies a position bridging European distribution anchoring with Asian market penetration. Among precision specialists, NSK Ltd. and ACTEON Group represent manufacturing depth in pneumatic instrument engineering. These named entities serve as anchors for understanding how regulatory capability, geographic positioning, and technology integration define competitive differentiation in air-polishing system supply.
| Leading Market Players |
|---|
| Dentsply Sirona |
| EMS Electro Medical Systems |
| KaVo Dental |
| NSK Ltd. |
| ACTEON Group |
| Hu-Friedy |
| Bien-Air Dental |
| Dürr Dental |
| Mectron |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ningbo port freight corridors transmit cost volatility from medical-grade erythritol and glycine powder manufacturing clusters directly into German and Japanese distributor markups, while downstream price differentiation stratifies across premium wireless systems, standard handheld units, and economy tabletop configurations serving distinct clinic capital cycles.
Pricing Analysis
Transatlantic price spreads of 15-25% separate EU MDR-certified wireless handpieces in Baden-Württemberg municipal clinics from non-certified portable units in US community health settings. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade, after-sales service bundling, and proprietary coupling system integration. Cost compression in mid-tier segments is intensifying because PMDA QMS documentation requirements inflate regulatory affairs overhead. Dental Service Organizations exhibit lowest price sensitivity due to fleet standardization economies, while solo practitioners in Texas and Florida metropolitan corridors drive hardest bargain through direct-to-clinic digital procurement platforms.
Supply Chain Analysis
Export control regimes governing precision pneumatic instrument technology limit nozzle manufacturing equipment flows from Switzerland and Germany into Chinese chemical processing clusters. Medical-grade powder supply concentrates in Chinese manufacturing hubs, Swiss precision engineering corridors, and German Baden-Württemberg component fabrication. Raw material dependencies rest on pharmaceutical-grade erythritol, glycine, and sodium bicarbonate feedstocks. Single-source vulnerability concentrates in Shanghai-Ningbo logistics chokepoints where customs processing delays propagate through EMS Electro Medical Systems and Dentsply Sirona distribution networks. Distribution runs through Dental Service Organization direct contracts, traditional dental dealer networks, and emerging online retail platforms serving replacement handpiece demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental air polishers market is recovering from regulatory documentation compression cycles, with EU MDR certificate renewal deadlines and FDA 510(k) review period extensions creating replacement demand windows for compliant manufacturers.
For Market Incumbents: Insulate wireless premium positioning by acquiring mid-tier specialists with established EU MDR technical files before 2026 certificate renewal deadlines compress competitive sets. Deepen backward integration into glycine powder formulation capabilities to offset Chinese chemical cluster shipping cost volatility. KaVo Dental and Dentsply Sirona must defend proprietary coupling ecosystem control against ultrasonic scaler substitution threats reclaiming periodontal maintenance cases. For New Entrants and Emerging Players: Establish a beachhead in Japanese aging-care dental facilities where PMDA QMS charging dock sterilization protocols slow incumbent wireless adoption. Target German statutory health insurance reimbursement expansion corridors in Bavaria preventive networks where mid-tier procurement windows remain underpenetrated. Deploy direct-to-clinic digital sales platforms bypassing traditional dental dealer markups in US DSO-dominated metropolitan markets. For Investors and Strategic Acquirers: EU MDR clinical evidence requirements reshape the acquisition landscape toward targets with robust quality management systems and prospective powder biocompatibility datasets. Five-to-ten year viability hinges on regulatory affairs infrastructure scalability rather than manufacturing efficiency alone. Monitor FDA 510(k) premarket notification review period trends as inflection indicator for novel powder formulation market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Expansion | Prospective clinical data on glycine powder biocompatibility secures certificate renewal for wireless handpiece portfolios. |
| Wireless Charging Dock Sterilization Protocol Development | PMDA QMS-compliant dock designs unlock Japanese aging-care facility procurement previously blocked by legacy waterline conflicts. |
| Direct-to-Clinic Digital Platform Launch | Bypassing traditional dental dealer networks in Texas and Florida DSO corridors compresses sales cycles and expands margin capture. |
| Optical Biofilm Detection Integration | Camera-equipped handpieces create diagnostic-treatment workflows commanding premium positioning in Japanese private practices. |
| Backward Integration into Powder Formulation | In-house glycine and erythritol production insulates margins from Shanghai-Ningbo freight corridor volatility. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with dental equipment procurement managers, GPO contracts specialists, biomedical engineers, and clinic operations directors; and secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA QMS ministerial ordinance registers, and hospital procurement system records. Bottom-up triangulation across product type, technology, end user, and distribution channel segmentation dimensions anchored volume estimates, while top-down cross-checks against statutory health insurance reimbursement code expansions validated demand assumptions.
Forecast inputs considered air abrasion system adoption rates, ultrasonic technology substitution patterns, wireless ergonomic replacement cycles, and powder chemistry transition timelines across the analysis window. Segmentation modeling incorporated handheld-wireless-tabletop-portable product configurations, air abrasion-ultrasonic-electrosurgery-laser technology tiers, dental clinic-hospital-research lab-cosmetic dentistry end users, and direct sales-distributor-online retail-medical supply store channel structures. CAGRs derived from equipment refresh cycle analysis, reimbursement code expansion trajectories, and regulatory compliance deadline clustering.
Sensitivities concentrate around EU MDR certificate renewal timeline shifts, FDA biocompatibility scrutiny intensity changes, and Japanese PMDA charging dock sterilization protocol amendments. Forecasts reflect documented assumptions on powder formulation substitution rates and DSO fleet standardization penetration. Material shifts in Sino-German freight corridor cost structures or statutory health insurance reimbursement eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Global Dental Turbine Market
Dental Devices
UAE Dental Devices Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Fittings Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Chair Market
Dental Devices
Dental Carpule Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Global Dental Microscope Market