
 Global IoT Battery Market | 2026-2036
Global IoT Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Battery Market Outlook
Modular battery pack architectures with swappable cell configurations is broadening buyer choice across industrial sensor deployments. LG Energy Solution leverages its cylindrical cell expertise to dominate high-durability outdoor applications. Panasonic anchors premium wearable device contracts through cobalt-optimized energy density formulations. Samsung SDI competes in smart home gateway segments with prismatic designs that minimize thermal footprint.
An IoT battery is a compact electrochemical power source engineered for intermittent discharge profiles, typically operating between 1.5V and 3.7V nominal voltage with self-discharge rates below 2% monthly to sustain decade-long unattended operation in connected endpoints. Its primary purpose is eliminating wired power infrastructure across distributed sensing and telemetry networks. Lithium-polymer chemistry captures margin pools in slim wearable devices where form factor constraints override raw cost. Industrial sensors running on lithium-thionyl chloride primary cells represent the longest replacement-cycle revenue stream. Smart meters across Bluetooth and Zigbee connectivity tiers are consolidating procurement volumes as utilities standardize on unified communication modules.
The EU Green Deal and REACH chemical frameworks restrict cadmium and mercury content in cells sold across member states, while the EPA in the United States governs hazardous material transport and end-of-life disposal pathways for IoT deployments. China's GB standards and MIIT circular economy rules mandate traceable recycling chains for lithium-containing batteries deployed in industrial automation. Stakeholders must monitor how divergent Extended Producer Responsibility schemes across the European Union, United States, and China reshape total cost of ownership calculations for global IoT hardware platforms.
Market Dynamics
Cell chemistry redesign pressure from the EU Green Deal's sustainability mandates is forcing manufacturers to eliminate cadmium and mercury while maintaining decade-long operational lifespans in distributed sensor networks.
Growth Catalysts
- Utility grid digitization:Smart meter deployments across unified Bluetooth and Zigbee communication modules are consolidating procurement volumes as power distributors eliminate manual reading infrastructure.
- REACH chemical framework expansion:Stricter substance restrictions across EU member states are accelerating investment in cobalt-reduced and solid-state formulations for wearable device contracts.
- Lithium-thionyl chloride chemistry:Industrial automation sensors operating on primary cell architectures now achieve fifteen-year replacement cycles, creating predictable aftermarket revenue streams for remote monitoring hardware.
Market Restraints
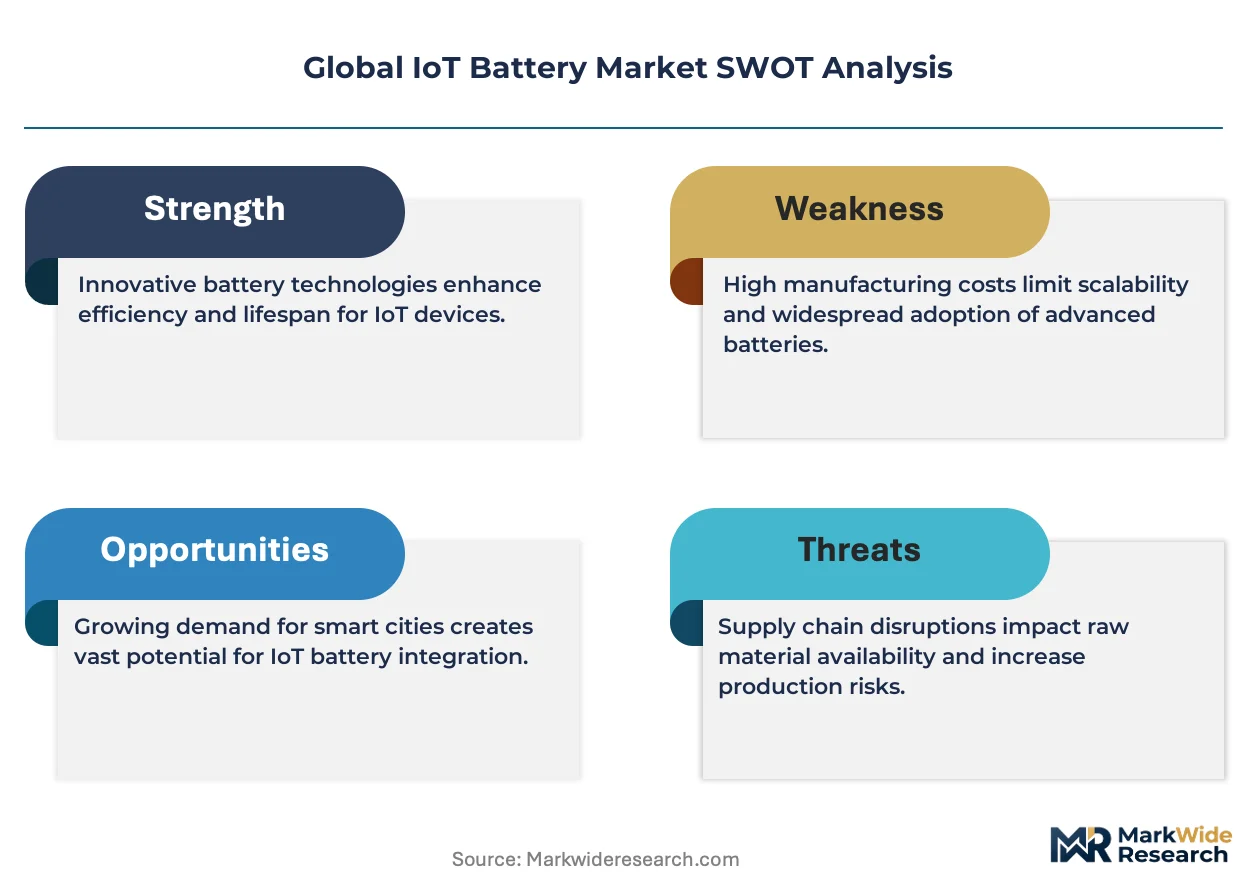
- Cobalt price volatility:Energy density formulations optimized for premium wearables remain exposed to Democratic Republic of Congo supply disruptions and London Metal Exchange price swings.
- East Asian manufacturing concentration:Cell fabrication and raw material refining operations cluster in China, South Korea, and Japan, creating single-point-of-failure risks for European and North American IoT hardware platforms.
- Primary cell disposal friction:EPA hazardous material transport rules and state-level landfill restrictions complicate end-of-life pathways for thionyl chloride batteries deployed in remote agricultural sensors.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing and BIS certification streamlining are opening captive demand from domestic smart factory deployments.
- Energy harvesting convergence:Photovoltaic and thermoelectric capture systems paired with thin-film lithium polymer buffers are eliminating battery replacement entirely in building automation endpoints.
- Modular pack architectures:Swappable cell configurations allow industrial buyers to standardize hardware platforms across voltage tiers without redesigning enclosure form factors.
Industry Challenges
- Electrolyte formulation expertise scarcity:Battery chemistry PhD talent concentrates in East Asian corporate laboratories, constraining European and North American R&D expansion timelines.
- UN 38.3 certification bottlenecks:Lithium metal and lithium-ion variants for air-shipped IoT hardware face testing queue backlogs at third-party laboratories, delaying product launches by six to nine months.
- Legacy 2G network dependency:Agricultural and utility sensors designed for sunset cellular protocols require hardware redesigns to maintain connectivity, compressing effective product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Battery Market |
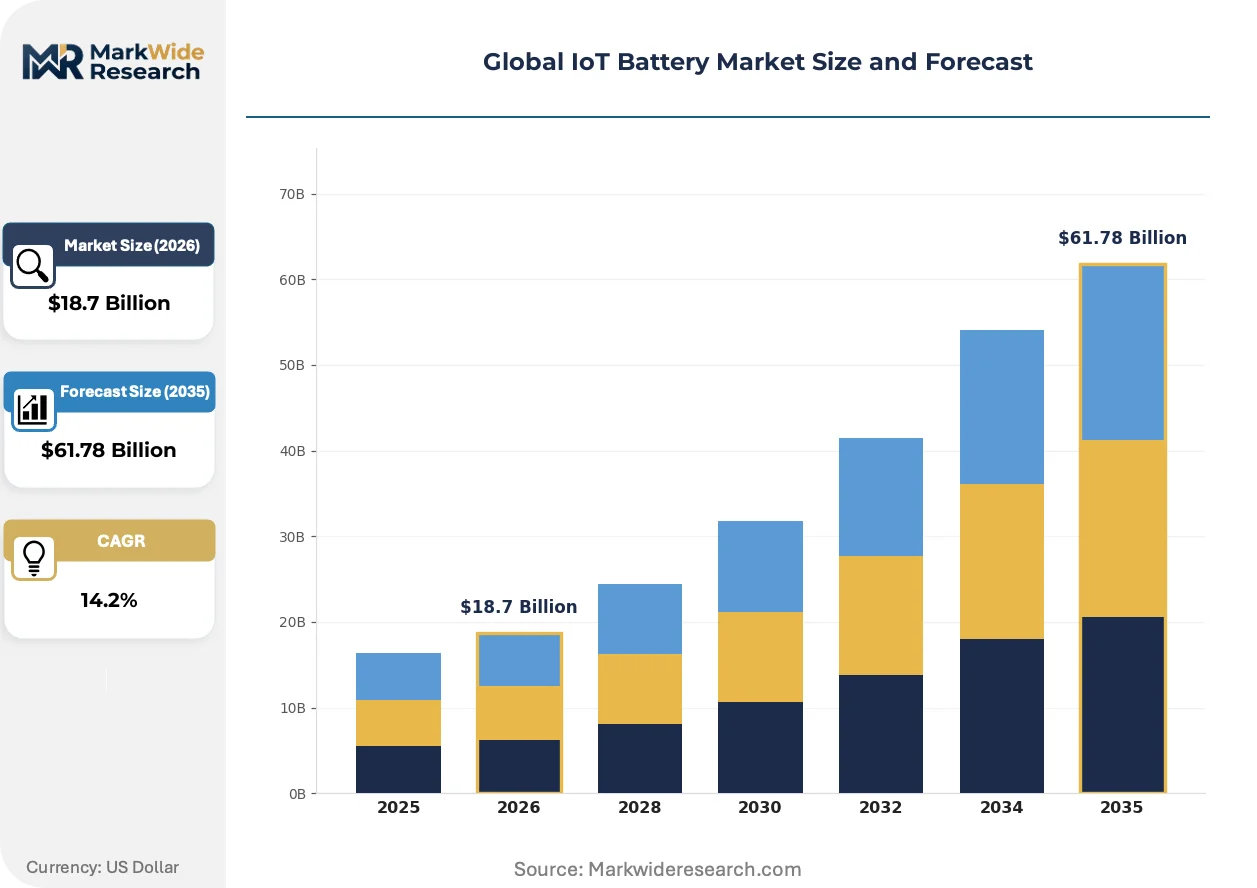
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Meters, Wearable Devices, Industrial Sensors, Smart Home Devices Battery Type: Lithium-ion, NiMH, Lead-acid, Lithium-polymer Connectivity: Bluetooth, Wi-Fi, Cellular, Zigbee End User: Healthcare, Automotive, Industrial Automation, Consumer Electronics |
| Companies Covered | LG Energy Solution, Gotion High-Tech, CATL, SK On, Samsung SDI, EVE Energy, Sunwoda, Panasonic, BYD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Battery Market Strategic Shifts
Solid-state and silicon-anode chemistries are migrating from electric vehicle research pipelines into compact IoT formats, while regulatory pressure on hazardous substances accelerates material substitution timelines.
Solid-state electrolyte architectures are expanding into medical implant and industrial sensor segments where thermal runaway tolerance outweighs cost sensitivity. Device manufacturers in Germany and Switzerland now specify ceramic separator cells for patient-worn monitors and subterranean pipeline sensors. This chemistry is expanding into applications previously reserved for polymer-gel designs, compressing the addressable market for conventional liquid electrolyte formats.
The EU Green Deal's battery sustainability mandates now require carbon footprint declarations and recycled content minimums for cells sold across member states. Industrial sensor OEMs must redesign supply chains to document traceable material provenance from mine to module. Smart home hardware vendors targeting European utilities face the strictest compliance timelines, with some accelerating partnerships with European cell assemblers to shorten certification pathways.
Buyers of industrial sensor hardware increasingly specify total-cost-of-ownership contracts that bundle cell replacement logistics into upfront equipment pricing. Agricultural cooperatives in Brazil and Australia now procure decade-long power service agreements rather than purchasing batteries separately. This purchasing pattern is most visible in remote monitoring deployments where technician dispatch costs exceed cell material value by orders of magnitude.
Global IoT Battery Market Segmentation
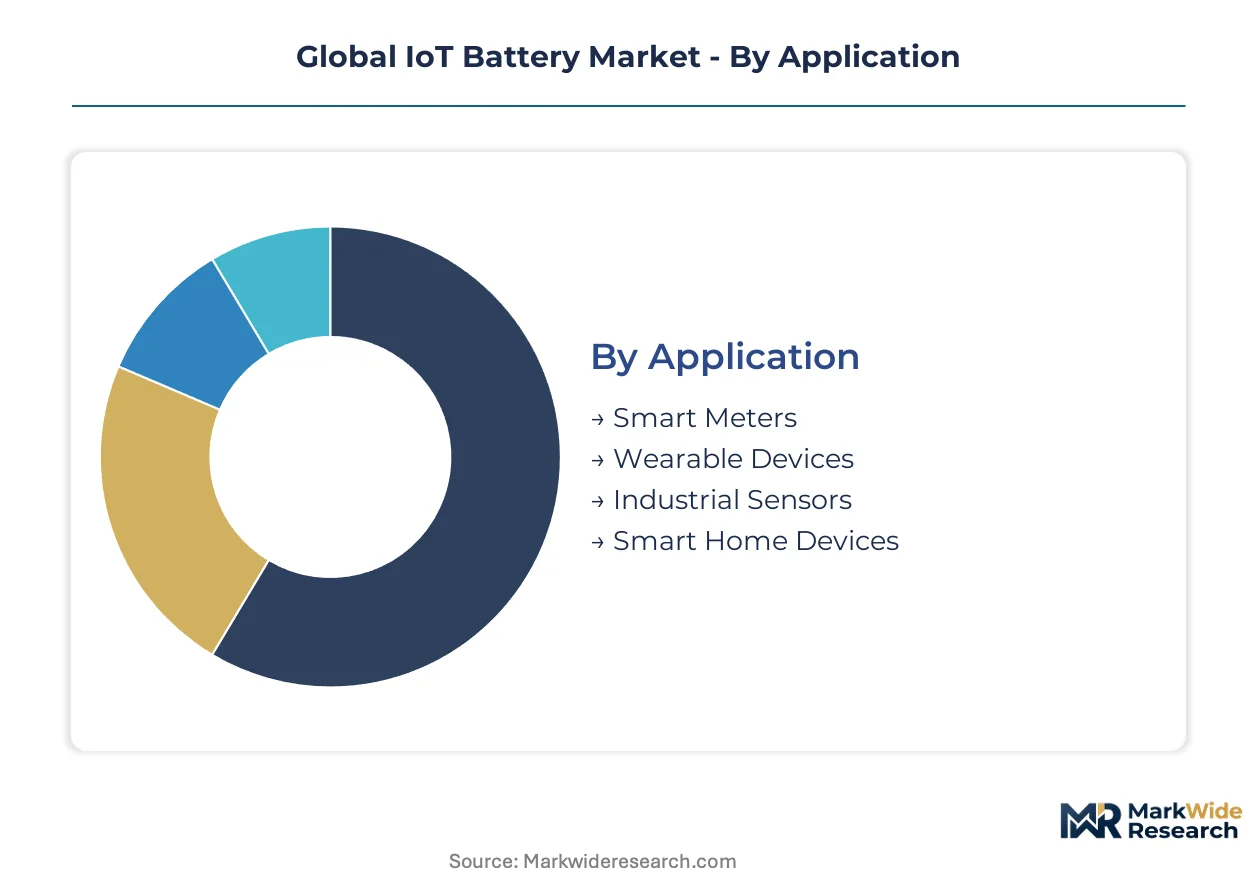
IoT battery procurement patterns diverge sharply across application voltage requirements, chemistry thermal profiles, and connectivity duty cycles. Understanding these segment boundaries clarifies why cell manufacturers maintain specialized production lines rather than universal platforms.
Application:
Supply concentration in cylindrical cell formats favors outdoor infrastructure deployments with standardized form factors over custom wearable geometries.
- Smart Meters:Utilities across Germany and Japan specify lithium-thionyl chloride primary cells for fifteen-year unattended operation in unified Bluetooth and Zigbee communication modules. Consolidated procurement from state-backed grid operators creates predictable volume anchors for cell assemblers.
- Wearable Devices:Slim lithium-polymer pouches dominate patient-worn monitors and fitness trackers where cobalt-optimized energy density overrides raw material cost. Panasonic and LG Energy Solution compete for premium contracts requiring sub-millimeter thickness tolerances.
- Industrial Sensors:Remote agricultural and pipeline monitoring in Brazil and Australia drives demand for primary cell architectures with decade-plus replacement cycles.
- Smart Home Devices:Gateway hardware and security endpoints favor prismatic designs that minimize thermal footprint in enclosed residential spaces.
Smart meters absorb the bulk of installed capacity; wearable devices are expanding most quickly.
Battery Type:
Cost tier stratification separates premium cobalt-containing formulations from commodity manganese-oxide alternatives in price-sensitive consumer hardware.
- Lithium-ion:Cylindrical 18650 and 21700 formats anchor industrial automation and smart home gateway segments with proven thermal management. Chinese cell manufacturers dominate this chemistry through integrated cathode material refining.
- Lithium-polymer:Pouch cells capture margin pools in medical implants and premium wearables where form factor flexibility justifies per-watt-hour premiums. Solid-state electrolyte migration is compressing addressable share for conventional gel-polymer designs.
- NiMH:Nickel-metal hydride persists in legacy utility meter retrofits and temperature-extreme outdoor sensors where lithium transport restrictions complicate air freight.
- Lead-acid:Sealed AGM variants serve backup power buffers in cellular-connected industrial gateways requiring surge current capacity beyond primary cell chemistry limits.
Lithium-ion absorbs the bulk of installed capacity; lithium-polymer is gaining share fastest in high-margin medical and wearable contracts.
Connectivity:
Volume concentration in Bluetooth and Zigbee modules reflects utility standardization efforts, while cellular tiers face protocol sunset pressures.
- Bluetooth:Low-energy stacks in smart meters and building automation endpoints drive the highest cell shipment volumes through unified procurement from European and Japanese utilities.
- Zigbee:Mesh networking protocols in smart home ecosystems require predictable discharge profiles that favor primary lithium-thionyl chloride over rechargeable alternatives.
- Wi-Fi:Higher current draws in video-enabled security hardware push toward lithium-polymer buffers with energy harvesting convergence in building automation.
- Cellular:2G and NB-IoT modules in remote agricultural sensors face hardware redesign cycles as carriers sunset legacy protocols across Brazil and Australia.
Bluetooth absorbs the bulk of installed capacity; Zigbee is climbing the fastest in utility-standardized deployments.
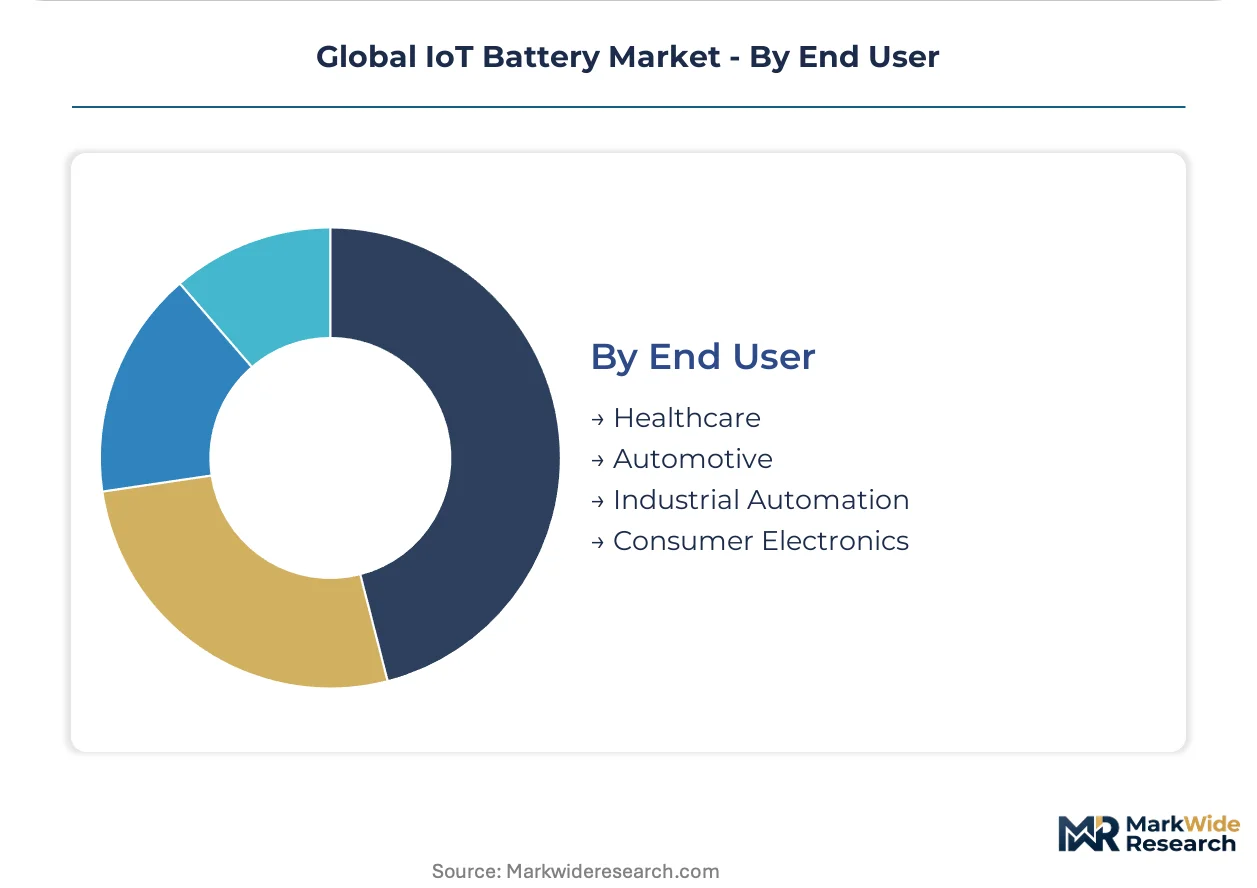
End User:
Customer type determines certification burden, with healthcare and automotive imposing the strictest cell qualification protocols.
- Healthcare:Patient-worn monitors and implantable devices in Germany and Switzerland specify ceramic separator solid-state cells where thermal runaway tolerance outweighs cost sensitivity. FDA and EMA biocompatibility requirements extend qualification timelines.
- Industrial Automation:Smart factory deployments across India's PLI-backed electronics manufacturing zones generate captive demand for modular battery pack architectures with swappable cell configurations.
- Automotive:Tire pressure monitoring and telematics modules require automotive-grade cell qualification against UN 38.3 and OEM-specific vibration standards.
- Consumer Electronics:Price-sensitive wearable and home device segments drive volume but compress margins through commodity lithium-polymer sourcing from Chinese contract manufacturers.
Industrial automation absorbs the bulk of installed capacity; healthcare is expanding most quickly under stringent safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Suzhou concentrate cell manufacturing capacity alongside integrated cathode material refining operations. These zones attract downstream IoT hardware assemblers seeking proximity to battery suppliers.
China
MIIT circular economy rules mandate traceable recycling chains for lithium-containing batteries deployed in industrial automation across the Yangtze River Delta. Shenzhen anchors pouch cell production for wearable device contracts, while Suzhou hosts cylindrical cell lines serving smart meter exporters.
South Korea
Seoul Capital Area manufacturers supply high-durability cylindrical cells for outdoor infrastructure deployments under K-REACH chemical substance registration requirements. Busan-Ulsan refineries process cobalt hydroxide imports for energy density formulations in premium medical wearables.
Germany
EU Green Deal battery sustainability mandates force chemistry redesigns for cells sold across member states, with Bavaria-based industrial sensor OEMs accelerating solid-state partnerships. REACH framework expansions restrict cadmium content in legacy utility meter retrofits.
United States
EPA hazardous material transport rules complicate end-of-life pathways for thionyl chloride batteries in remote agricultural sensors across the Midwest. Texas hosts smart factory deployments procuring modular battery pack architectures with swappable configurations.
India
PLI scheme incentives for electronics manufacturing generate captive demand from domestic industrial automation in Maharashtra and Karnataka. BIS certification streamlining accelerates procurement timelines for smart home gateway hardware targeting utility digitization programs.
Global IoT Battery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across chemistry formats and voltage tiers. The vendor base clusters around three strategic archetypes: integrated material-to-cell conglomerates, specialized cylindrical cell fabricators, and pouch cell specialists serving medical wearables. Capacity expansion and strategic partnerships dominate competitive moves as players secure cathode material offtake agreements.
Within the conglomerate tier, LG Energy Solution and CATL exemplify scale-driven positions spanning multiple IoT battery formats. Samsung SDI occupies a specialized niche in prismatic designs for smart home applications. These three anchors demonstrate how geographic concentration in East Asian manufacturing clusters shapes competitive positioning without requiring identical strategic approaches.
| Leading Market Players |
|---|
| LG Energy Solution |
| Gotion High-Tech |
| CATL |
| SK On |
| Samsung SDI |
| EVE Energy |
| Sunwoda |
| Panasonic |
| BYD |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal battery sustainability mandates are forcing industrial sensor OEMs to absorb certification premiums for carbon footprint declarations and recycled content minimums, compressing margins for cell assemblers unable to document traceable material provenance from mine to module.
Pricing Analysis
Lead-time-driven pricing stratification rewards buyers securing six-month forward contracts with Chinese cylindrical cell manufacturers, while spot purchasers of lithium-polymer pouches pay premiums for sub-90-day delivery. Three-tier pricing separates automotive-grade UN 38.3 certified cells from industrial standard and uncertified economy alternatives. Cost compression in nickel-metal hydride retrofits is intensifying because REACH cadmium restrictions have stranded inventory. Agricultural cooperatives in Brazil exhibit highest price sensitivity, whereas German medical device OEMs prioritize thermal runaway tolerance over per-unit cost.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Suzhou special economic zones are elevating automation investment requirements for pouch and cylindrical cell lines. Supply concentrates in China, South Korea, and Japan, with cathode material refining operations drawing from cobalt hydroxide processed at Busan-Ulsan refineries. Feedstock dependencies span lithium carbonate from Chilean salares, cobalt from the Democratic Republic of Congo, and separator membranes from Japanese polymer specialists. Single-source vulnerability in East Asian manufacturing clusters threatens European and North American IoT hardware platforms. Distribution runs through direct OEM contracts for utility-scale smart meter volumes and electronics manufacturing service aggregators for fragmented wearable device procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where cathode material offtake agreements and captive recycling infrastructure determine cost position and regulatory compliance velocity.
For Market Incumbents: Anchor cylindrical cell capacity expansions in India PLI zones to capture domestic smart factory demand while hedging East Asian concentration risk. Accelerate solid-state electrolyte partnerships with German industrial sensor OEMs facing EU Green Deal certification deadlines. Defensive consolidation through modular battery pack architecture standardization locks in industrial buyer switching costs against emerging pouch cell specialists. For New Entrants and Emerging Players: The mid-tier price gap between Panasonic cobalt-optimized premium wearables and Chinese commodity lithium-polymer sourcing opens white-space for BIS-certified cell assemblers targeting Maharashtra and Karnataka electronics manufacturing zones. India's streamlined certification pathways offer the most penetrable geography. A service-integrated go-to-market bundling decade-long power agreements with hardware procurement addresses Brazilian agricultural cooperative total-cost-of-ownership preferences. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state electrolyte specialists given EU Green Deal mandates accelerating ceramic separator adoption in patient-worn monitors and subterranean pipeline sensors. Long-term viability across the analysis window favors targets with traceable recycling chain documentation and MIIT-compliant circular economy infrastructure. Watch for UN 38.3 certification queue backlogs at third-party laboratories as an inflection indicator for air-shipped IoT hardware launch delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Refining | Captive cobalt hydroxide processing at Busan-Ulsan facilities secures energy density formulation supply for premium medical wearables. |
| Modular Battery Pack Architecture Launch | Swappable cell configurations enable Indian industrial automation buyers to standardize hardware platforms across voltage tiers without enclosure redesign. |
| Solid-State Electrolyte Partnership | Ceramic separator cells address German and Swiss patient-worn monitor specifications where thermal runaway tolerance outweighs cost sensitivity. |
| PLI Zone Manufacturing Scale-Up | Maharashtra and Karnataka capacity additions capture captive demand from India's domestic smart factory deployments under electronics manufacturing incentives. |
| Traceable Recycling Chain Certification | MIIT-compliant circular economy documentation meets China's mandatory requirements for lithium-containing batteries in Yangtze River Delta industrial automation. |
Study Parameters
SEC filings from cell manufacturers, ECHA REACH substance registration databases, and customs trade data from China and South Korea formed the secondary backbone. Primary interviews with plant managers at cylindrical cell fabrication facilities, procurement leads at German industrial sensor OEMs, and regulatory affairs specialists navigating EU Green Deal compliance requirements combined with secondary validation. Bottom-up and top-down triangulation cross-referenced shipment volumes from Shenzhen and Suzhou special economic zones against utility smart meter deployment disclosures from European grid operators.
Bottom-up modeling aggregated segment-level cell chemistry demand across lithium-thionyl chloride primary cells, lithium-polymer pouches, and cylindrical lithium-ion formats, while top-down analysis calibrated aggregate market expansion against utility digitization capex cycles. Segmentation dimensions spanned application voltage requirements, chemistry thermal profiles, connectivity duty cycles, and end-user certification burden tiers. CAGRs derived from regression analysis of historical procurement patterns and projected smart meter rollout schedules. Forecast inputs incorporated REACH framework expansion timelines and EPA hazardous material transport rule enforcement intensity.
Inputs from ECHA substance databases and MIIT circular economy filings were available through the study window; gaps in real-time cobalt spot price volatility and UN 38.3 certification queue lengths introduce uncertainty bands around near-term shipment projections. Forecasts reflect documented assumptions regarding EU member state transposition timelines for battery sustainability mandates and carrier sunset schedules for 2G cellular protocols in Brazil and Australia. Material deviation in EU Green Deal enforcement intensity or East Asian manufacturing cluster disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
Global IoT Managed Services Market
Internet of Things (IoT)
Global IoT in Warehouse Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Maritime Internet of Things Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Aviation IoT Solutions Market